
Collector Bank AB (OM:COLL) April 22, 2016

Description: Collector Bank AB (OM:COLL) April 22, 2016 Investment Thesis Collector Bank B (Collector) is primarily a consumer lending company based in Sweden It has expanded product offering in recent years and received a bank license in 2015
Related Topics
Download Presentation
"Collector Bank AB (OM:COLL) April 22, 2016" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Collector Bank AB (OM:COLL) April 22, 2016<br>
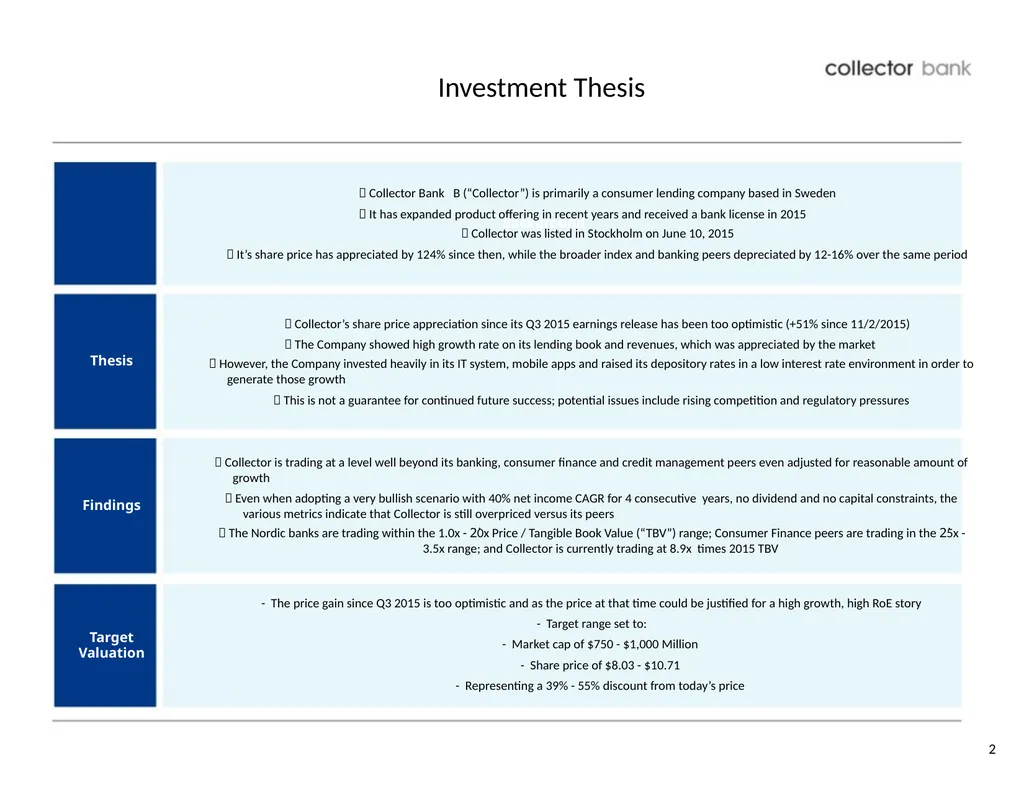
slide2. Investment Thesis Collector Bank B (“Collector”) is primarily a consumer lending company based in Sweden It has expanded product offering in recent years and received a bank license in 2015 Background Collector was listed in Stockholm on June 10, 2015 It’s share price has appreciated by 124% since then, while the broader index and banking peers depreciated by 12-16% over the same period Collector’s share price appreciation since its Q3 2015 earnings release has been too optimistic (+51% since 11/2/2015) The Company showed high growth rate on its lending book and revenues, which was appreciated by the market Thesis Findings Target Valuation However, the Company invested heavily in its IT system, mobile apps and raised its depository rates in a low interest rate environment in order to generate those growth This is not a guarantee for continued future success; potential issues include rising competition and regulatory pressures Collector is trading at a level well beyond its banking, consumer finance and credit management peers even adjusted for reasonable amount of growth Even when adopting a very bullish scenario with 40% net income CAGR for 4 consecutive years, no dividend and no capital constraints, the various metrics indicate that Collector is still overpriced versus its peers The Nordic banks are trading within the 1.0x - 2͘0x Price / Tangible Book Value (“TBV”) range; Consumer Finance peers are trading in the 2͘5x - 3.5x range; and Collector is currently trading at 8.9x times 2015 TBV - The price gain since Q3 2015 is too optimistic and as the price at that time could be justified for a high growth, high RoE story - Target range set to: - Market cap of $750 - $1,000 Million - Share price of $8.03 - $10.71 - Representing a 39% - 55% discount from today’s price 2<br>
slide3. Agenda 1 Business Overview 2 Valuation Analysis 3 Risks, Catalysts and Conclusion 4 Appendix 1 - Loan Book and Capitalization Details 5 Appendix 2 - Supporting Materials 3<br>
slide4. Section 1 Business Overview 4<br>
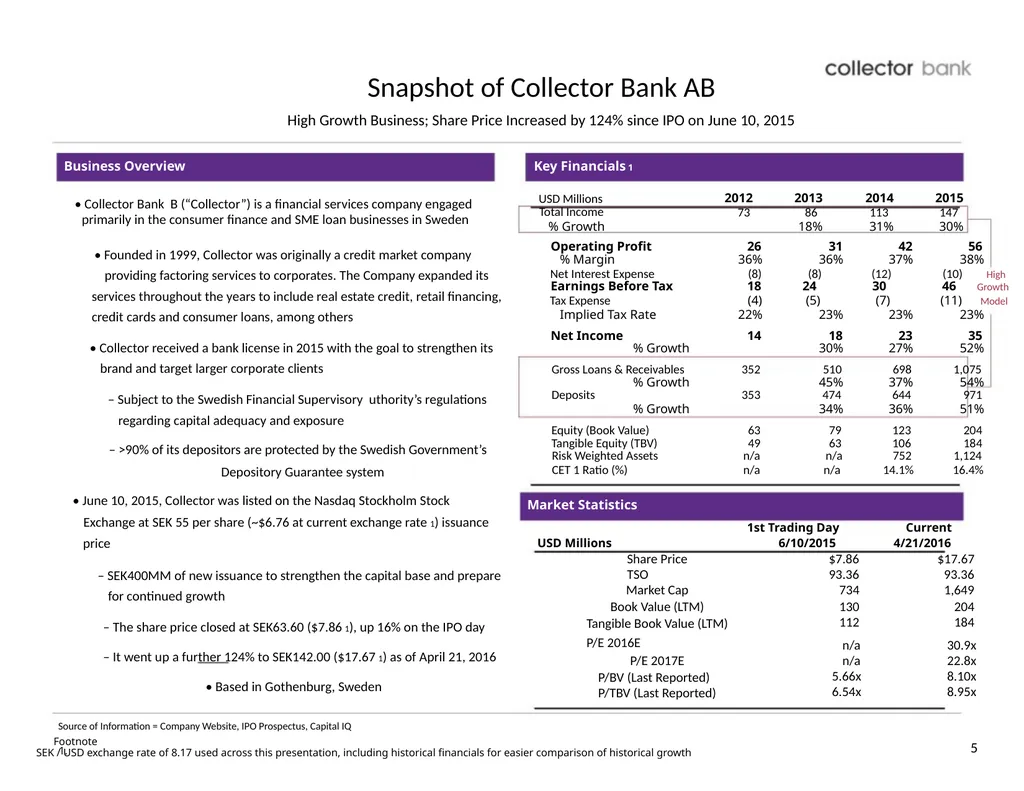
slide5. Snapshot of Collector Bank AB High Growth Business; Share Price Increased by 124% since IPO on June 10, 2015 Business Overview Key Financials 1 • Collector Bank B (“Collector”) is a financial services company engaged USD Millions 2012 2013 2014 2015 Total Income 73 86 113 147 primarily in the consumer finance and SME loan businesses in Sweden % Growth 18% 31% 30% • Founded in 1999, Collector was originally a credit market company providing factoring services to corporates. The Company expanded its services throughout the years to include real estate credit, retail financing, credit cards and consumer loans, among others • Collector received a bank license in 2015 with the goal to strengthen its brand and target larger corporate clients – Subject to the Swedish Financial Supervisory uthority’s regulations regarding capital adequacy and exposure – >90% of its depositors are protected by the Swedish Government’s Depository Guarantee system Operating Profit 26 % Margin 36% Net Interest Expense (8) Earnings Before Tax 18 Tax Expense (4) Implied Tax Rate 22% Net Income 14 % Growth Gross Loans & Receivables 352 % Growth Deposits 353 % Growth Equity (Book Value) 63 Tangible Equity (TBV) 49 Risk Weighted Assets n/a CET 1 Ratio (%) n/a 31 42 56 36% 37% 38% (8) (12) (10) High 24 30 46 Growth (5) (7) (11) Model 23% 23% 23% 18 23 35 30% 27% 52% 510 698 1,075 45% 37% 54% 474 644 971 34% 36% 51% 79 123 204 63 106 184 n/a 752 1,124 n/a 14.1% 16.4% • June 10, 2015, Collector was listed on the Nasdaq Stockholm Stock Market Statistics Exchange at SEK 55 per share (~$6.76 at current exchange rate 1) issuance 1st Trading Day Current price USD Millions 6/10/2015 4/21/2016 – SEK400MM of new issuance to strengthen the capital base and prepare for continued growth – The share price closed at SEK63.60 ($7.86 1), up 16% on the IPO day – It went up a further 124% to SEK142.00 ($17.67 1) as of April 21, 2016 • Based in Gothenburg, Sweden Share Price TSO Market Cap Book Value (LTM) Tangible Book Value (LTM) P/E 2016E P/E 2017E P/BV (Last Reported) P/TBV (Last Reported) $7.86 $17.67 93.36 93.36 734 1,649 130 204 112 184 n/a 30.9x n/a 22.8x 5.66x 8.10x 6.54x 8.95x Source of Information = Company Website, IPO Prospectus, Capital IQ Footnote 1. SEK / USD exchange rate of 8.17 used across this presentation, including historical financials for easier comparison of historical growth 5<br>
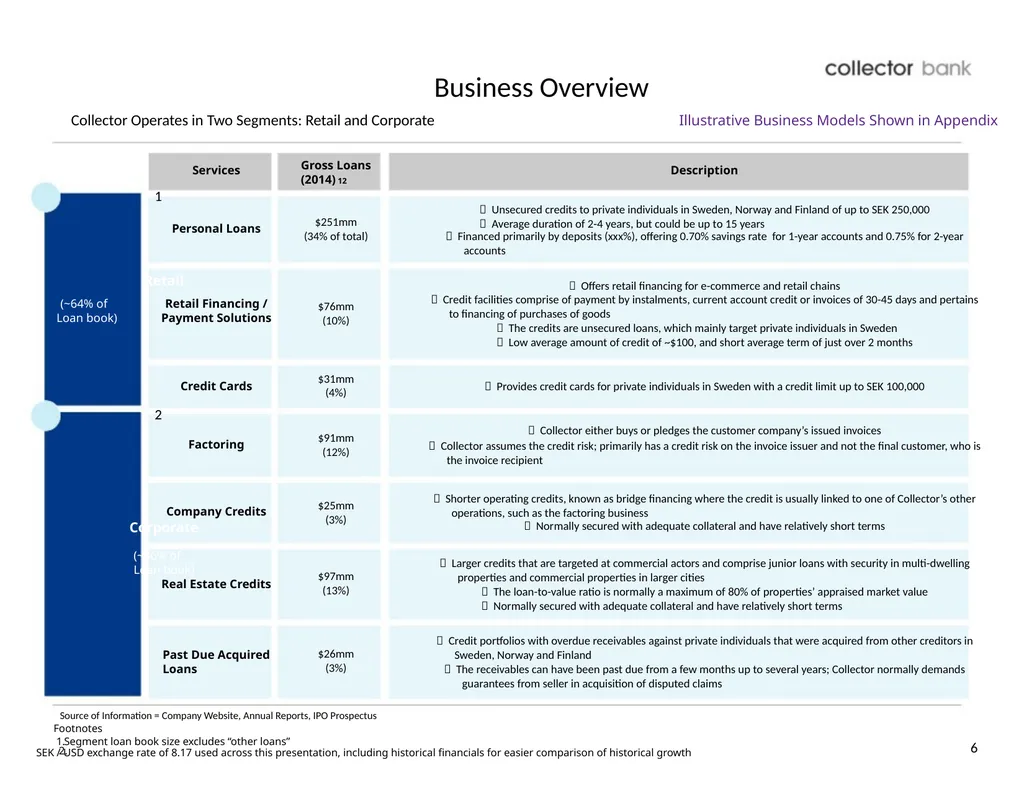
slide6. Business Overview Collector Operates in Two Segments: Retail and Corporate Illustrative Business Models Shown in Appendix Services 1 Personal Loans Retail (~64% of Retail Financing / Loan book) Payment Solutions Credit Cards 2 Factoring Company Credits Corporate (~36% of Loan book) Real Estate Credits Past Due Acquired Loans Gross Loans (2014) 12 $251mm (34% of total) $76mm (10%) $31mm (4%) $91mm (12%) $25mm (3%) $97mm (13%) $26mm (3%) Description Unsecured credits to private individuals in Sweden, Norway and Finland of up to SEK 250,000 Average duration of 2-4 years, but could be up to 15 years Financed primarily by deposits (xxx%), offering 0.70% savings rate for 1-year accounts and 0.75% for 2-year accounts Offers retail financing for e-commerce and retail chains Credit facilities comprise of payment by instalments, current account credit or invoices of 30-45 days and pertains to financing of purchases of goods The credits are unsecured loans, which mainly target private individuals in Sweden Low average amount of credit of ~$100, and short average term of just over 2 months Provides credit cards for private individuals in Sweden with a credit limit up to SEK 100,000 Collector either buys or pledges the customer company’s issued invoices Collector assumes the credit risk; primarily has a credit risk on the invoice issuer and not the final customer, who is the invoice recipient Shorter operating credits, known as bridge financing where the credit is usually linked to one of Collector’s other operations, such as the factoring business Normally secured with adequate collateral and have relatively short terms Larger credits that are targeted at commercial actors and comprise junior loans with security in multi-dwelling properties and commercial properties in larger cities The loan-to-value ratio is normally a maximum of 80% of properties’ appraised market value Normally secured with adequate collateral and have relatively short terms Credit portfolios with overdue receivables against private individuals that were acquired from other creditors in Sweden, Norway and Finland The receivables can have been past due from a few months up to several years; Collector normally demands guarantees from seller in acquisition of disputed claims Source of Information = Company Website, Annual Reports, IPO Prospectus Footnotes 1. Segment loan book size excludes “other loans” 2. SEK / USD exchange rate of 8.17 used across this presentation, including historical financials for easier comparison of historical growth 6<br>
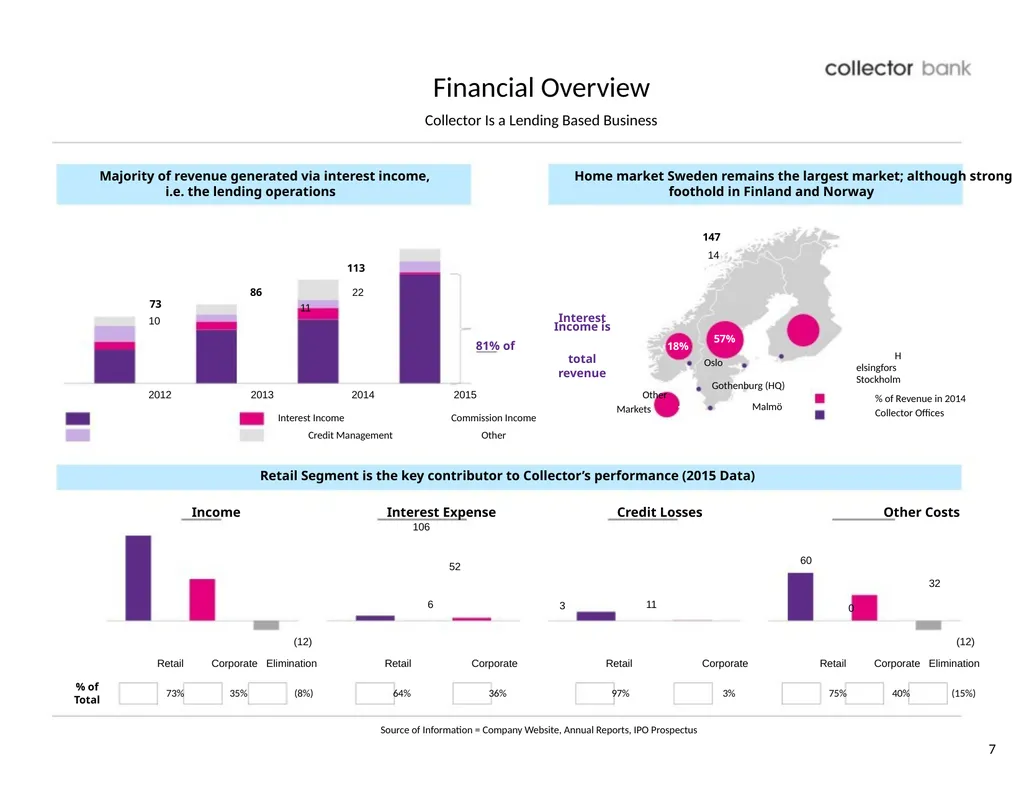
slide7. Financial Overview Collector Is a Lending Based Business Majority of revenue generated via interest income, i.e. the lending operations 113 86 22 73 9 Home market Sweden remains the largest market; although strong foothold in Finland and Norway 147 14 12 2 10 17 8 37 11 8 13 9 59 70 Interest 119 Income is 81% of 18% total revenue 57% Oslo 23% Helsingfors Stockholm Gothenburg (HQ) 2012 2013 2014 2015 Other Markets 1% Interest Income Commission Income Credit Management Other Retail Segment is the key contributor to Collector’s performance (2015 Data) Income Interest Expense Credit Losses 106 52 6 11 Malmö 60 % of Revenue in 2014 Collector Offices Other Costs 32 % of Total (12) Retail Corporate Elimination 73% 35% (8%) 3 Retail Corporate Retail 64% 36% 97% 0 (12) Corporate Retail Corporate Elimination 3% 75% 40% (15%) Source of Information = Company Website, Annual Reports, IPO Prospectus 7<br>
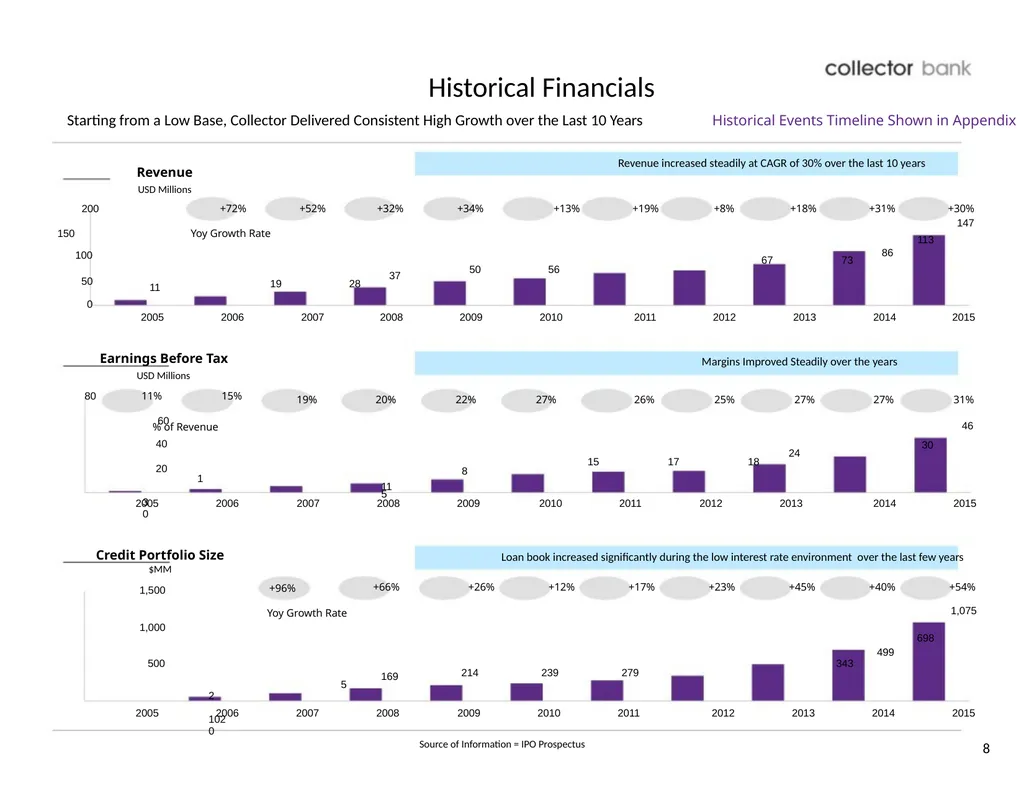
slide8. Historical Financials Starting from a Low Base, Collector Delivered Consistent High Growth over the Last 10 Years Historical Events Timeline Shown in Appendix Revenue USD Millions 200 +72% 150 Yoy Growth Rate +52% +32% +34% Revenue increased steadily at CAGR of 30% over the last 10 years +13% +19% +8% +18% +31% +30% 147 113 86 100 50 0 11 2005 37 19 28 2006 2007 2008 50 56 2009 2010 67 73 2011 2012 2013 2014 2015 Earnings Before Tax USD Millions 80 11% 15% 60 19% 20% 22% 27% Margins Improved Steadily over the years 26% 25% 27% 27% 31% % of Revenue 40 20 1 3 0 2005 2006 8 11 5 2007 2008 2009 24 15 17 18 2010 2011 2012 2013 46 30 2014 2015 Credit Portfolio Size $MM 1,500 1,000 500 +96% Yoy Growth Rate +66% Loan book increased significantly during the low interest rate environment over the last few years +26% +12% +17% +23% +45% +40% +54% 1,075 698 499 343 169 52 102 0 2005 2006 2007 2008 214 239 279 2009 2010 2011 2012 2013 2014 2015 Source of Information = IPO Prospectus 8<br>
slide9. Section 2 Equity Story and Valuation Overview 9<br>
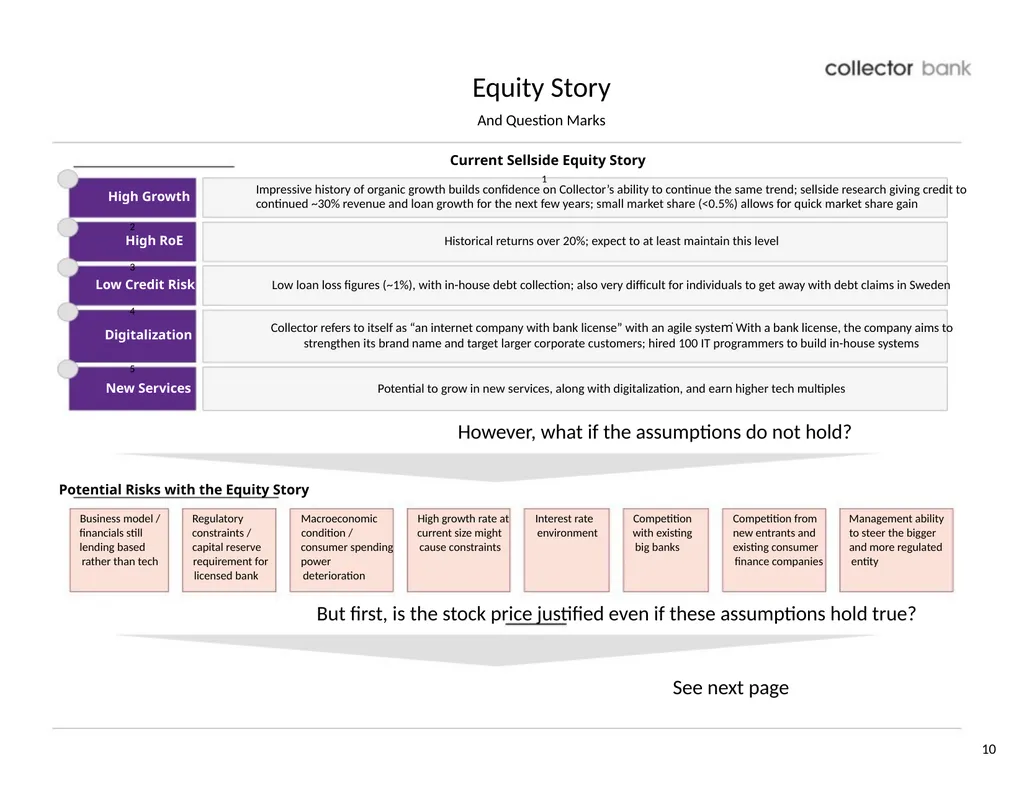
slide10. Equity Story And Question Marks Current Sellside Equity Story 1 High Growth 2 High RoE 3 Low Credit Risk 4 Digitalization 5 New Services Impressive history of organic growth builds confidence on Collector’s ability to continue the same trend; sellside research giving credit to continued ~30% revenue and loan growth for the next few years; small market share (<0.5%) allows for quick market share gain Historical returns over 20%; expect to at least maintain this level Low loan loss figures (~1%), with in-house debt collection; also very difficult for individuals to get away with debt claims in Sweden Collector refers to itself as “an internet company with bank license” with an agile system͘ With a bank license, the company aims to strengthen its brand name and target larger corporate customers; hired 100 IT programmers to build in-house systems Potential to grow in new services, along with digitalization, and earn higher tech multiples However, what if the assumptions do not hold? Potential Risks with the Equity Story Business model / Regulatory Macroeconomic High growth rate at Interest rate Competition Competition from Management ability financials still constraints / condition / current size might environment with existing new entrants and to steer the bigger lending based capital reserve consumer spending cause constraints big banks existing consumer and more regulated rather than tech requirement for power finance companies entity licensed bank deterioration But first, is the stock price justified even if these assumptions hold true? See next page 10<br>
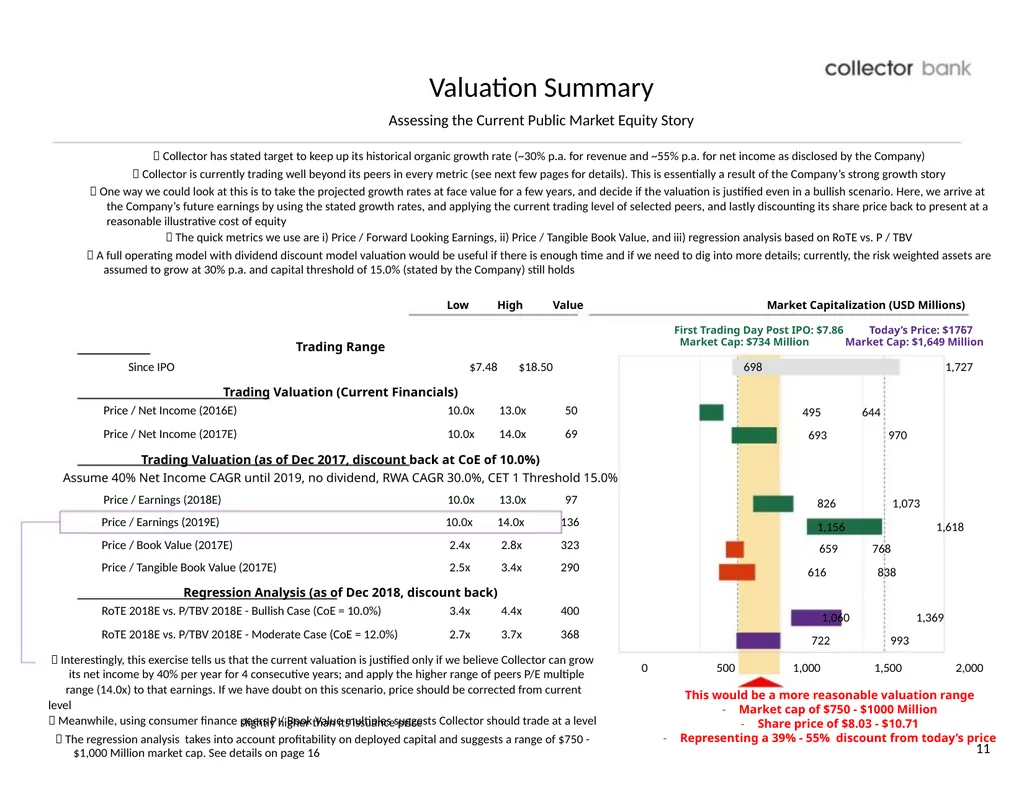
slide11. Valuation Summary Assessing the Current Public Market Equity Story Collector has stated target to keep up its historical organic growth rate (~30% p.a. for revenue and ~55% p.a. for net income as disclosed by the Company) Collector is currently trading well beyond its peers in every metric (see next few pages for details). This is essentially a result of the Company’s strong growth story One way we could look at this is to take the projected growth rates at face value for a few years, and decide if the valuation is justified even in a bullish scenario. Here, we arrive at the Company’s future earnings by using the stated growth rates, and applying the current trading level of selected peers, and lastly discounting its share price back to present at a reasonable illustrative cost of equity The quick metrics we use are i) Price / Forward Looking Earnings, ii) Price / Tangible Book Value, and iii) regression analysis based on RoTE vs. P / TBV A full operating model with dividend discount model valuation would be useful if there is enough time and if we need to dig into more details; currently, the risk weighted assets are assumed to grow at 30% p.a. and capital threshold of 15.0% (stated by the Company) still holds Low High Value Trading Range Since IPO $7.48 $18.50 Trading Valuation (Current Financials) Price / Net Income (2016E) 10.0x 13.0x 50 Price / Net Income (2017E) 10.0x 14.0x 69 Trading Valuation (as of Dec 2017, discount back at CoE of 10.0%) Assume 40% Net Income CAGR until 2019, no dividend, RWA CAGR 30.0%, CET 1 Threshold 15.0% Price / Earnings (2018E) 10.0x 13.0x 97 Price / Earnings (2019E) 10.0x 14.0x 136 Price / Book Value (2017E) 2.4x 2.8x 323 Price / Tangible Book Value (2017E) 2.5x 3.4x 290 Regression Analysis (as of Dec 2018, discount back) RoTE 2018E vs. P/TBV 2018E - Bullish Case (CoE = 10.0%) 3.4x 4.4x 400 RoTE 2018E vs. P/TBV 2018E - Moderate Case (CoE = 12.0%) 2.7x 3.7x 368 Interestingly, this exercise tells us that the current valuation is justified only if we believe Collector can grow its net income by 40% per year for 4 consecutive years; and apply the higher range of peers P/E multiple range (14.0x) to that earnings. If we have doubt on this scenario, price should be corrected from current level Meanwhile, using consumer finance peers P / Book Value multiples suggests Collector should trade at a level slightly higher than its issuance price The regression analysis takes into account profitability on deployed capital and suggests a range of $750 - $1,000 Million market cap. See details on page 16 Market Capitalization (USD Millions) First Trading Day Post IPO: $7.86 Today’s Price: $17͘67 Market Cap: $734 Million Market Cap: $1,649 Million 698 1,727 495 644 693 970 826 1,073 1,156 1,618 659 768 616 838 1,060 1,369 722 993 0 500 1,000 1,500 2,000 This would be a more reasonable valuation range - Market cap of $750 - $1000 Million - Share price of $8.03 - $10.71 - Representing a 39% - 55% discount from today’s price 11<br>
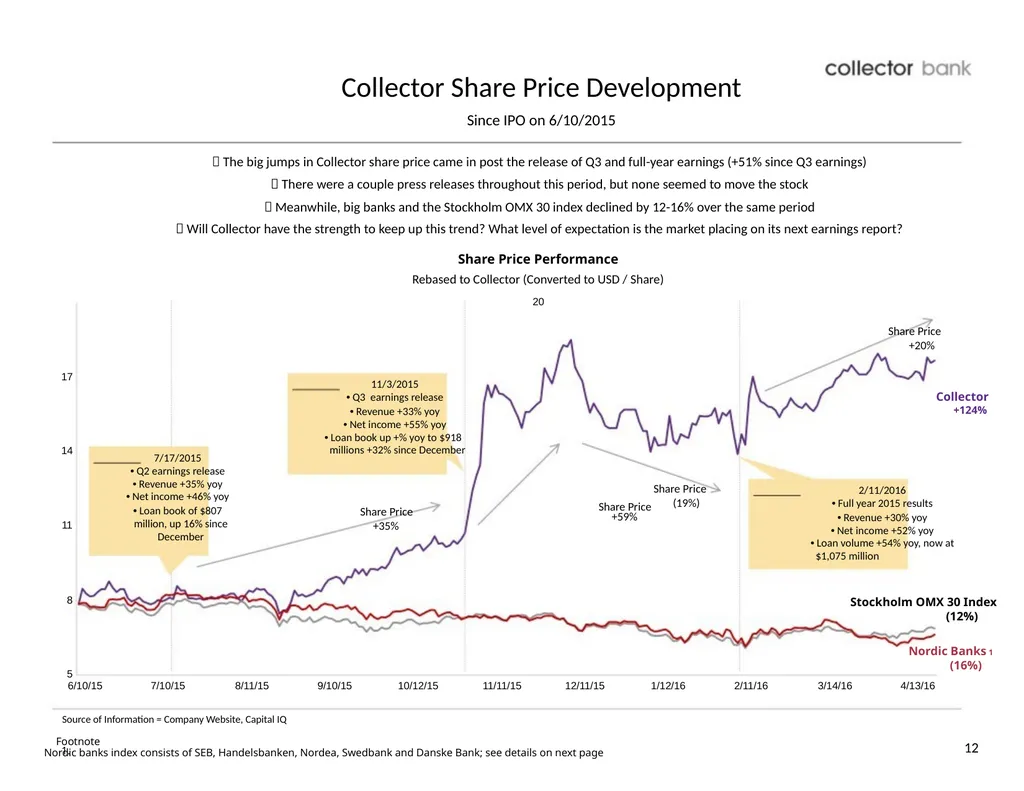
slide12. Collector Share Price Development Since IPO on 6/10/2015 The big jumps in Collector share price came in post the release of Q3 and full-year earnings (+51% since Q3 earnings) There were a couple press releases throughout this period, but none seemed to move the stock Meanwhile, big banks and the Stockholm OMX 30 index declined by 12-16% over the same period Will Collector have the strength to keep up this trend? What level of expectation is the market placing on its next earnings report? Share Price Performance Rebased to Collector (Converted to USD / Share) 20 Share Price +20% 17 14 11 8 5 7/17/2015 • Q2 earnings release • Revenue +35% yoy • Net income +46% yoy • Loan book of $807 million, up 16% since December 11/3/2015 • Q3 earnings release • Revenue +33% yoy • Net income +55% yoy • Loan book up +% yoy to $918 millions +32% since December Share Price +35% Share Price (19%) Share Price +59% Collector +124% 2/11/2016 • Full year 2015 results • Revenue +30% yoy • Net income +52% yoy • Loan volume +54% yoy, now at $1,075 million Stockholm OMX 30 Index (12%) Nordic Banks 1 (16%) 6/10/15 7/10/15 8/11/15 9/10/15 10/12/15 11/11/15 12/11/15 1/12/16 2/11/16 3/14/16 4/13/16 Source of Information = Company Website, Capital IQ Footnote 1. Nordic banks index consists of SEB, Handelsbanken, Nordea, Swedbank and Danske Bank; see details on next page 12<br>
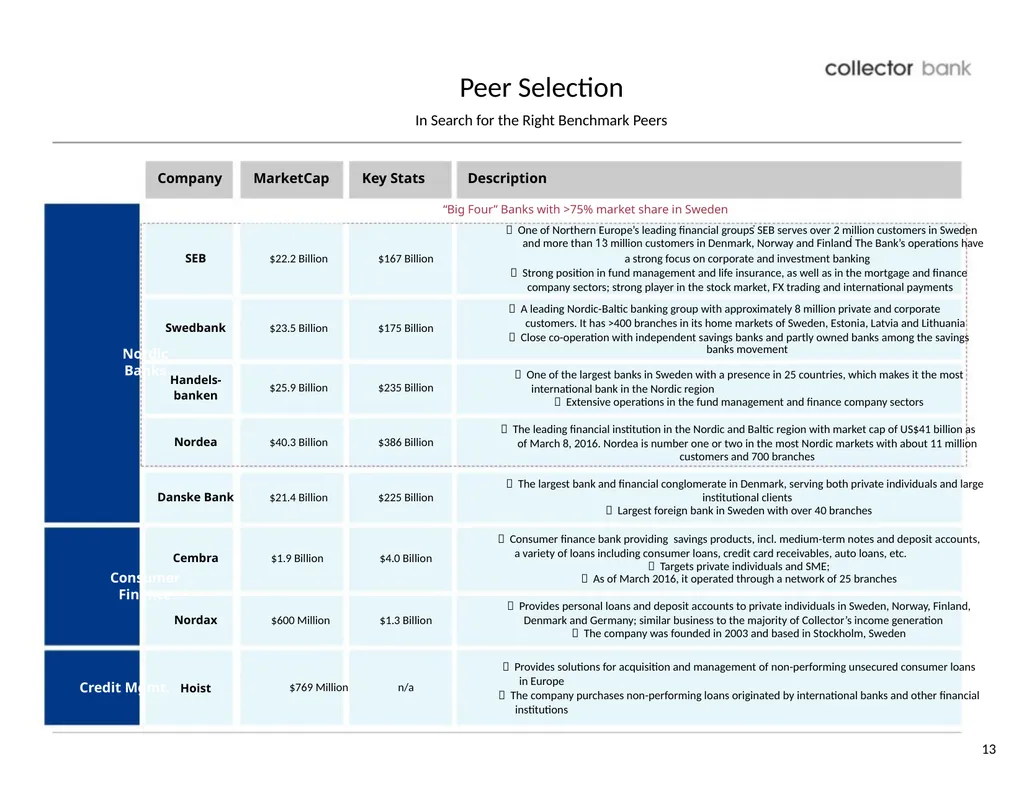
slide13. Peer Selection In Search for the Right Benchmark Peers Company MarketCap Key Stats Description “Big Four” Banks with >75% market share in Sweden One of Northern Europe’s leading financial groups͘ SEB serves over 2 million customers in Sweden and more than 1͘3 million customers in Denmark, Norway and Finland͘ The Bank’s operations have SEB Swedbank Nordic Banks Handels- banken Nordea $22.2 Billion $167 Billion $23.5 Billion $175 Billion $25.9 Billion $235 Billion $40.3 Billion $386 Billion a strong focus on corporate and investment banking Strong position in fund management and life insurance, as well as in the mortgage and finance company sectors; strong player in the stock market, FX trading and international payments A leading Nordic-Baltic banking group with approximately 8 million private and corporate customers. It has >400 branches in its home markets of Sweden, Estonia, Latvia and Lithuania Close co-operation with independent savings banks and partly owned banks among the savings banks movement One of the largest banks in Sweden with a presence in 25 countries, which makes it the most international bank in the Nordic region Extensive operations in the fund management and finance company sectors The leading financial institution in the Nordic and Baltic region with market cap of US$41 billion as of March 8, 2016. Nordea is number one or two in the most Nordic markets with about 11 million customers and 700 branches The largest bank and financial conglomerate in Denmark, serving both private individuals and large Danske Bank Cembra Consumer Finance Nordax Credit Mgmt. Hoist $21.4 Billion $225 Billion $1.9 Billion $4.0 Billion $600 Million $1.3 Billion $769 Million n/a institutional clients Largest foreign bank in Sweden with over 40 branches Consumer finance bank providing savings products, incl. medium-term notes and deposit accounts, a variety of loans including consumer loans, credit card receivables, auto loans, etc. Targets private individuals and SME; As of March 2016, it operated through a network of 25 branches Provides personal loans and deposit accounts to private individuals in Sweden, Norway, Finland, Denmark and Germany; similar business to the majority of Collector’s income generation The company was founded in 2003 and based in Stockholm, Sweden Provides solutions for acquisition and management of non-performing unsecured consumer loans in Europe The company purchases non-performing loans originated by international banks and other financial institutions 13<br>
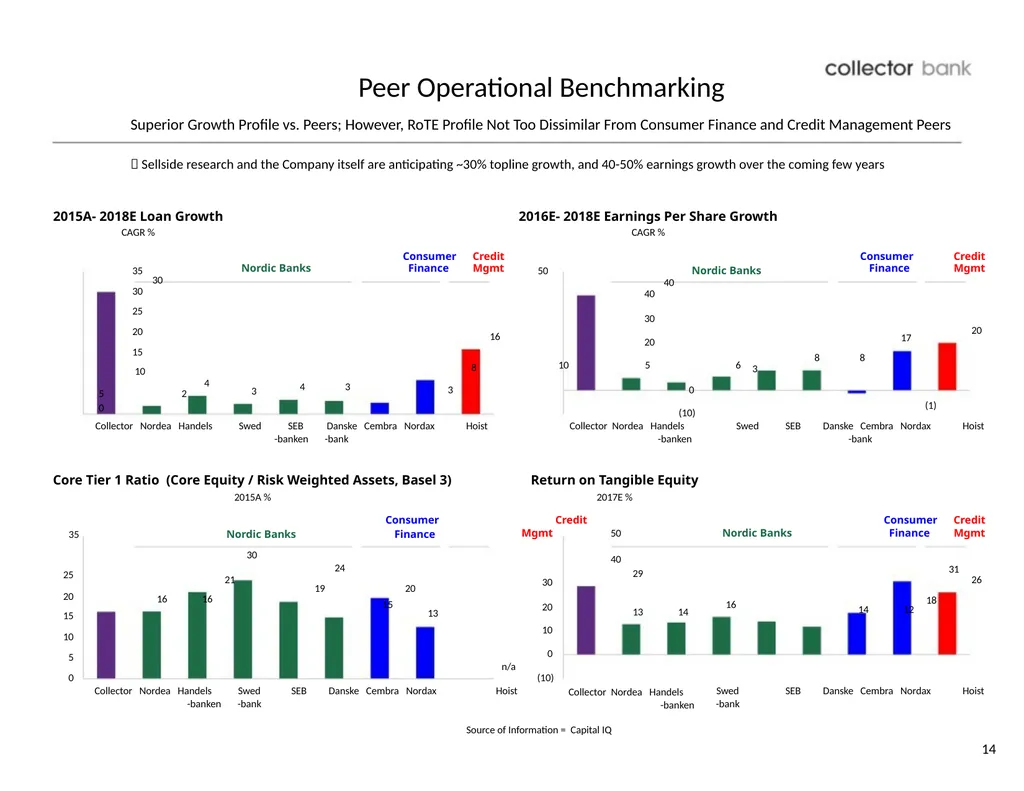
slide14. Peer Operational Benchmarking Superior Growth Profile vs. Peers; However, RoTE Profile Not Too Dissimilar From Consumer Finance and Credit Management Peers Sellside research and the Company itself are anticipating ~30% topline growth, and 40-50% earnings growth over the coming few years 2015A- 2018E Loan Growth CAGR % 35 30 30 25 20 15 Consumer Credit Nordic Banks Finance Mgmt 16 8 2016E- 2018E Earnings Per Share Growth CAGR % 50 Nordic Banks 40 40 30 20 10 5 6 Consumer Finance 17 8 8 Credit Mgmt 20 10 4 5 2 0 3 4 3 3 3 0 (10) (1) Collector Nordea Handels Swed SEB Danske Cembra Nordax -banken -bank Core Tier 1 Ratio (Core Equity / Risk Weighted Assets, Basel 3) 2015A % Consumer 35 Nordic Banks Finance 30 24 Hoist Collector Nordea Handels -banken Return on Tangible Equity 2017E % Credit Mgmt 50 40 Swed SEB Danske Cembra Nordax Hoist -bank Consumer Credit Nordic Banks Finance Mgmt 31 25 20 15 10 5 0 21 16 16 Collector Nordea Handels Swed -banken -bank 19 20 15 13 SEB Danske Cembra Nordax 30 20 10 0 n/a (10) Hoist 29 13 14 Collector Nordea Handels -banken 16 Swed -bank 26 18 14 12 SEB Danske Cembra Nordax Hoist Source of Information = Capital IQ 14<br>
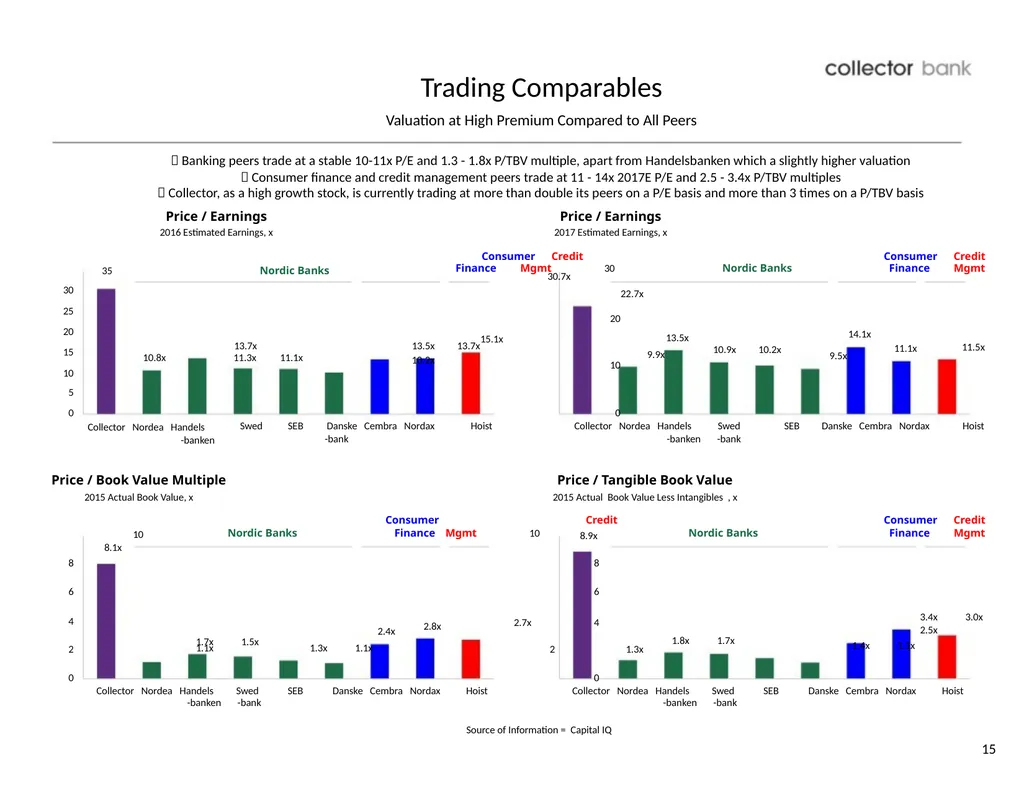
slide15. Trading Comparables Valuation at High Premium Compared to All Peers Banking peers trade at a stable 10-11x P/E and 1.3 - 1.8x P/TBV multiple, apart from Handelsbanken which a slightly higher valuation Consumer finance and credit management peers trade at 11 - 14x 2017E P/E and 2.5 - 3.4x P/TBV multiples Collector, as a high growth stock, is currently trading at more than double its peers on a P/E basis and more than 3 times on a P/TBV basis Price / Earnings 2016 Estimated Earnings, x 35 Nordic Banks Price / Earnings 2017 Estimated Earnings, x Consumer Credit Finance Mgmt 30 Consumer Credit Nordic Banks Finance Mgmt 30.7x 30 25 20 15 10 5 0 13.7x 10.8x 11.3x 11.1x 15.1x 13.5x 13.7x 10.2x 22.7x 20 13.5x 9.9x 10 0 10.9x 10.2x 14.1x 9.5x 11.1x 11.5x Collector Nordea Handels -banken Price / Book Value Multiple 2015 Actual Book Value, x 10 Swed SEB Danske Cembra Nordax -bank Consumer Nordic Banks Finance Hoist Collector Nordea Handels Swed -banken -bank Price / Tangible Book Value 2015 Actual Book Value Less Intangibles , x Credit Mgmt 10 Nordic Banks SEB Danske Cembra Nordax Hoist Consumer Credit Finance Mgmt 8.9x 8.1x 8 6 4 2 0 1.7x 1.5x 1.1x 2.4x 1.3x 1.1x 2.8x 8 6 2.7x 4 2 1.3x 0 1.8x 1.7x 3.4x 3.0x 2.5x 1.4x 1.1x Collector Nordea Handels Swed SEB Danske Cembra Nordax Hoist Collector Nordea Handels Swed SEB Danske Cembra Nordax Hoist -banken -bank -banken -bank Source of Information = Capital IQ 15<br>
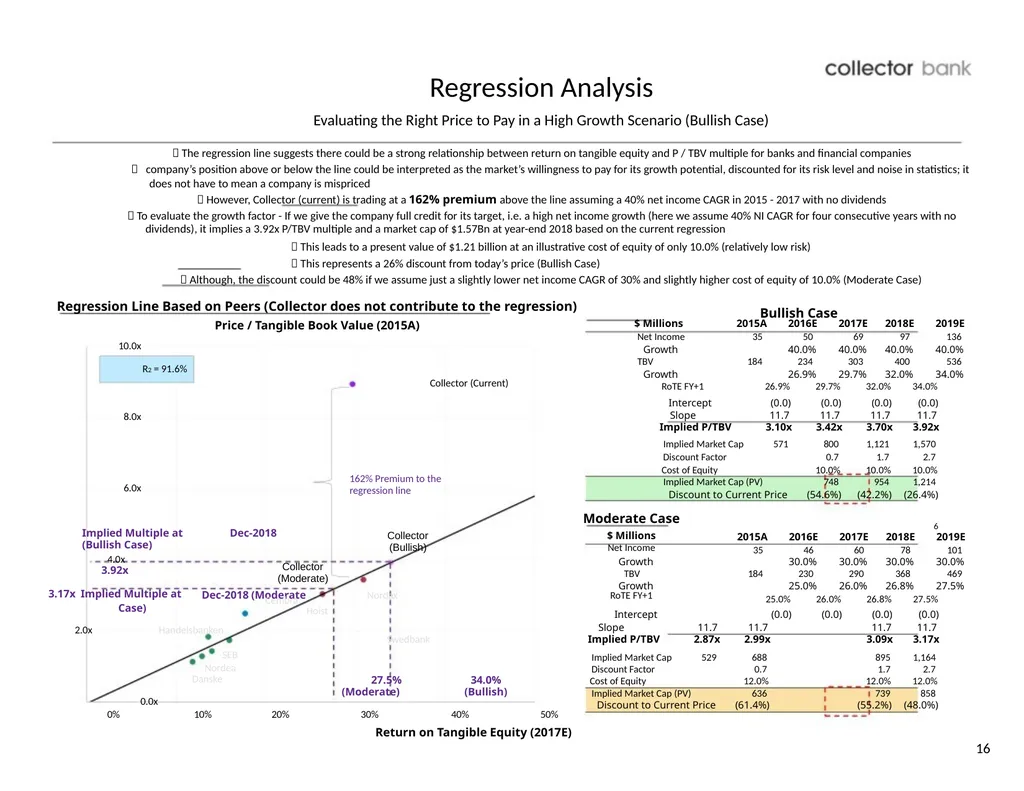
slide16. Regression Analysis Evaluating the Right Price to Pay in a High Growth Scenario (Bullish Case) The regression line suggests there could be a strong relationship between return on tangible equity and P / TBV multiple for banks and financial companies company’s position above or below the line could be interpreted as the market’s willingness to pay for its growth potential, discounted for its risk level and noise in statistics; it does not have to mean a company is mispriced However, Collector (current) is trading at a 162% premium above the line assuming a 40% net income CAGR in 2015 - 2017 with no dividends To evaluate the growth factor - If we give the company full credit for its target, i.e. a high net income growth (here we assume 40% NI CAGR for four consecutive years with no dividends), it implies a 3.92x P/TBV multiple and a market cap of $1.57Bn at year-end 2018 based on the current regression This leads to a present value of $1.21 billion at an illustrative cost of equity of only 10.0% (relatively low risk) This represents a 26% discount from today’s price (Bullish Case) Although, the discount could be 48% if we assume just a slightly lower net income CAGR of 30% and slightly higher cost of equity of 10.0% (Moderate Case) Regression Line Based on Peers (Collector does not contribute to the regression) Price / Tangible Book Value (2015A) Bullish Case $ Millions 2015A 2016E 2017E 2018E 2019E 10.0x R2 = 91.6% 8.0x 6.0x Collector (Current) 162% Premium to the regression line Net Income 35 50 69 97 136 Growth 40.0% 40.0% 40.0% 40.0% TBV 184 234 303 400 536 Growth 26.9% 29.7% 32.0% 34.0% RoTE FY+1 26.9% 29.7% 32.0% 34.0% Intercept (0.0) (0.0) (0.0) (0.0) Slope 11.7 11.7 11.7 11.7 Implied P/TBV 3.10x 3.42x 3.70x 3.92x Implied Market Cap 571 800 1,121 1,570 Discount Factor 0.7 1.7 2.7 Cost of Equity 10.0% 10.0% 10.0% Implied Market Cap (PV) 748 954 1,214 Discount to Current Price (54.6%) (42.2%) (26.4%) Implied Multiple at (Bullish Case) 4.0x 3.92x 3.17x Implied Multiple at Case) Dec-2018 Collector (Moderate) Dec-2018 (Moderate Cembra Hoist Moderate Case Collector $ Millions (Bullish) Net Income Growth TBV Growth Nordax RoTE FY+1 Intercept 6 2015A 2016E 2017E 2018E 2019E 35 46 60 78 101 30.0% 30.0% 30.0% 30.0% 184 230 290 368 469 25.0% 26.0% 26.8% 27.5% 25.0% 26.0% 26.8% 27.5% (0.0) (0.0) (0.0) (0.0) 2.0x Handelsbanken SEB Nordea Danske 0.0x 0% 10% Swedbank 27.5% 34.0% (Moderate) (Bullish) 20% 30% 40% 50% Return on Tangible Equity (2017E) Slope 11.7 11.7 Implied P/TBV 2.87x 2.99x Implied Market Cap 529 688 Discount Factor 0.7 Cost of Equity 12.0% Implied Market Cap (PV) 636 Discount to Current Price (61.4%) 11.7 11.7 3.09x 3.17x 895 1,164 1.7 2.7 12.0% 12.0% 739 858 (55.2%) (48.0%) 16<br>
slide17. Section 4 Risks, Catalysts and Conclusion 17<br>
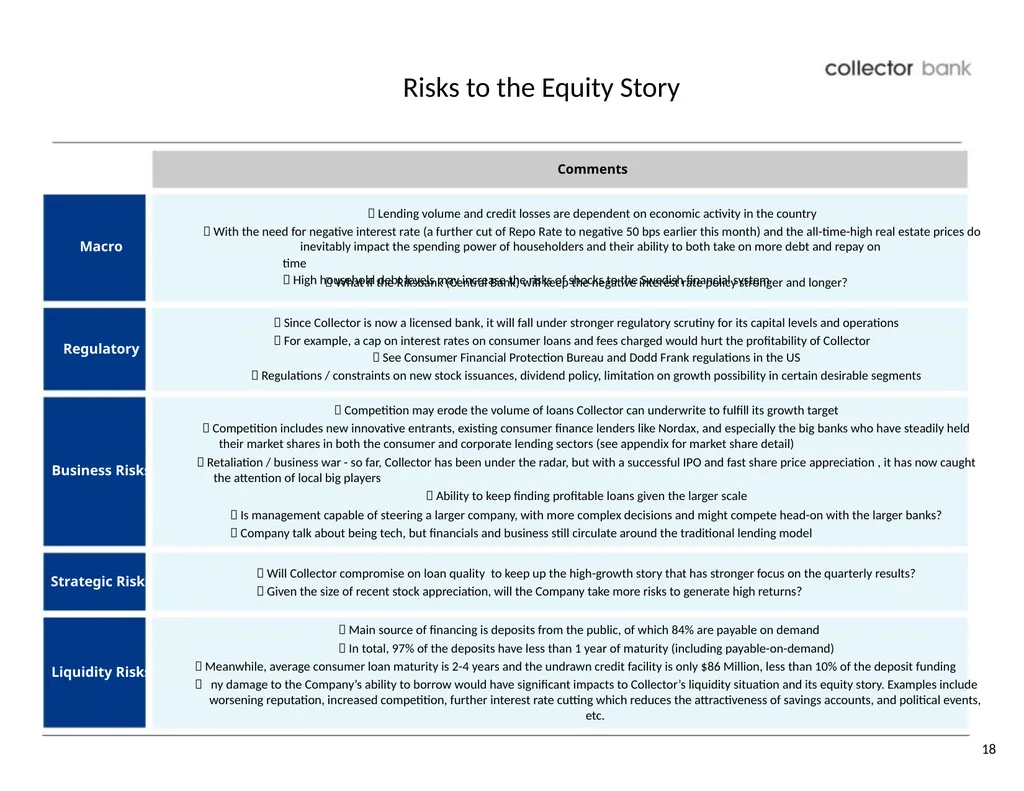
slide18. Risks to the Equity Story Comments Lending volume and credit losses are dependent on economic activity in the country With the need for negative interest rate (a further cut of Repo Rate to negative 50 bps earlier this month) and the all-time-high real estate prices do Macro Regulatory Business Risks Strategic Risks Liquidity Risks inevitably impact the spending power of householders and their ability to both take on more debt and repay on time High household debt levels may increase the risks of shocks to the Swedish financial system What if the Riksbank (Central Bank) will keep the negative interest rate policy stronger and longer? Since Collector is now a licensed bank, it will fall under stronger regulatory scrutiny for its capital levels and operations For example, a cap on interest rates on consumer loans and fees charged would hurt the profitability of Collector See Consumer Financial Protection Bureau and Dodd Frank regulations in the US Regulations / constraints on new stock issuances, dividend policy, limitation on growth possibility in certain desirable segments Competition may erode the volume of loans Collector can underwrite to fulfill its growth target Competition includes new innovative entrants, existing consumer finance lenders like Nordax, and especially the big banks who have steadily held their market shares in both the consumer and corporate lending sectors (see appendix for market share detail) Retaliation / business war - so far, Collector has been under the radar, but with a successful IPO and fast share price appreciation , it has now caught the attention of local big players Ability to keep finding profitable loans given the larger scale Is management capable of steering a larger company, with more complex decisions and might compete head-on with the larger banks? Company talk about being tech, but financials and business still circulate around the traditional lending model Will Collector compromise on loan quality to keep up the high-growth story that has stronger focus on the quarterly results? Given the size of recent stock appreciation, will the Company take more risks to generate high returns? Main source of financing is deposits from the public, of which 84% are payable on demand In total, 97% of the deposits have less than 1 year of maturity (including payable-on-demand) Meanwhile, average consumer loan maturity is 2-4 years and the undrawn credit facility is only $86 Million, less than 10% of the deposit funding ny damage to the Company’s ability to borrow would have significant impacts to Collector’s liquidity situation and its equity story. Examples include worsening reputation, increased competition, further interest rate cutting which reduces the attractiveness of savings accounts, and political events, etc. 18<br>
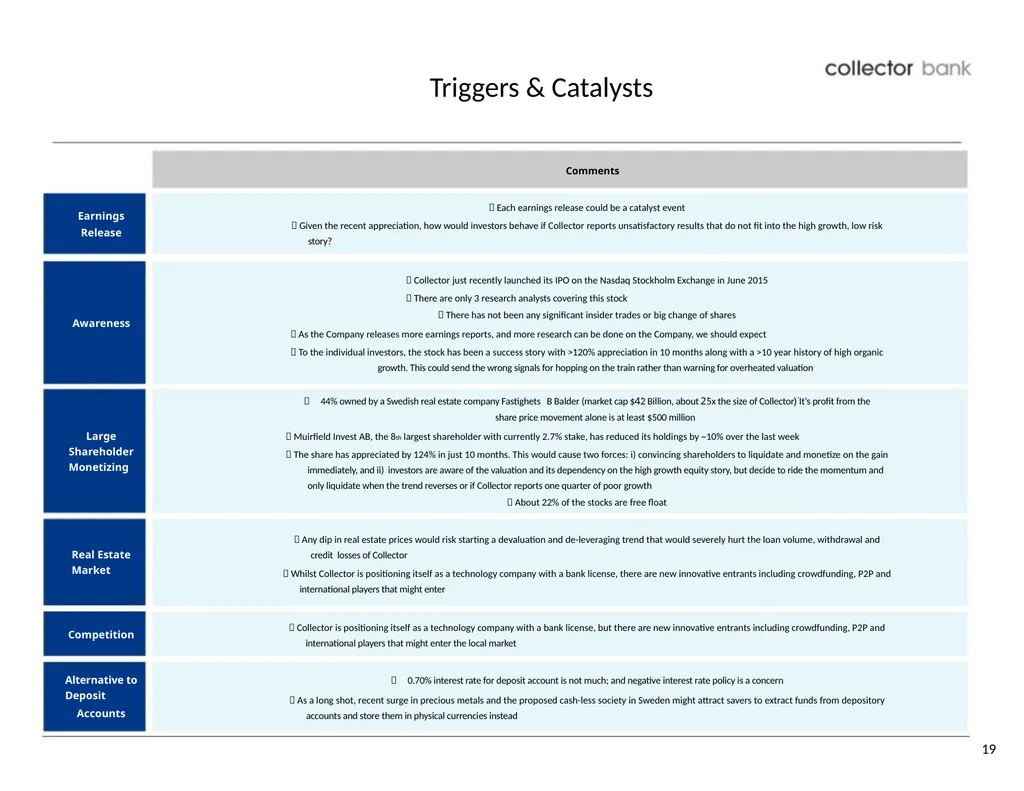
slide19. Triggers & Catalysts Comments Earnings Release Awareness Large Shareholder Monetizing Real Estate Market Competition Alternative to Deposit Accounts Each earnings release could be a catalyst event Given the recent appreciation, how would investors behave if Collector reports unsatisfactory results that do not fit into the high growth, low risk story? Collector just recently launched its IPO on the Nasdaq Stockholm Exchange in June 2015 There are only 3 research analysts covering this stock There has not been any significant insider trades or big change of shares As the Company releases more earnings reports, and more research can be done on the Company, we should expect To the individual investors, the stock has been a success story with >120% appreciation in 10 months along with a >10 year history of high organic growth. This could send the wrong signals for hopping on the train rather than warning for overheated valuation 44% owned by a Swedish real estate company Fastighets B Balder (market cap $4͘2 Billion, about 2͘5x the size of Collector)͘ It’s profit from the share price movement alone is at least $500 million Muirfield Invest AB, the 8th largest shareholder with currently 2.7% stake, has reduced its holdings by ~10% over the last week The share has appreciated by 124% in just 10 months. This would cause two forces: i) convincing shareholders to liquidate and monetize on the gain immediately, and ii) investors are aware of the valuation and its dependency on the high growth equity story, but decide to ride the momentum and only liquidate when the trend reverses or if Collector reports one quarter of poor growth About 22% of the stocks are free float Any dip in real estate prices would risk starting a devaluation and de-leveraging trend that would severely hurt the loan volume, withdrawal and credit losses of Collector Whilst Collector is positioning itself as a technology company with a bank license, there are new innovative entrants including crowdfunding, P2P and international players that might enter Collector is positioning itself as a technology company with a bank license, but there are new innovative entrants including crowdfunding, P2P and international players that might enter the local market 0.70% interest rate for deposit account is not much; and negative interest rate policy is a concern As a long shot, recent surge in precious metals and the proposed cash-less society in Sweden might attract savers to extract funds from depository accounts and store them in physical currencies instead 19<br>
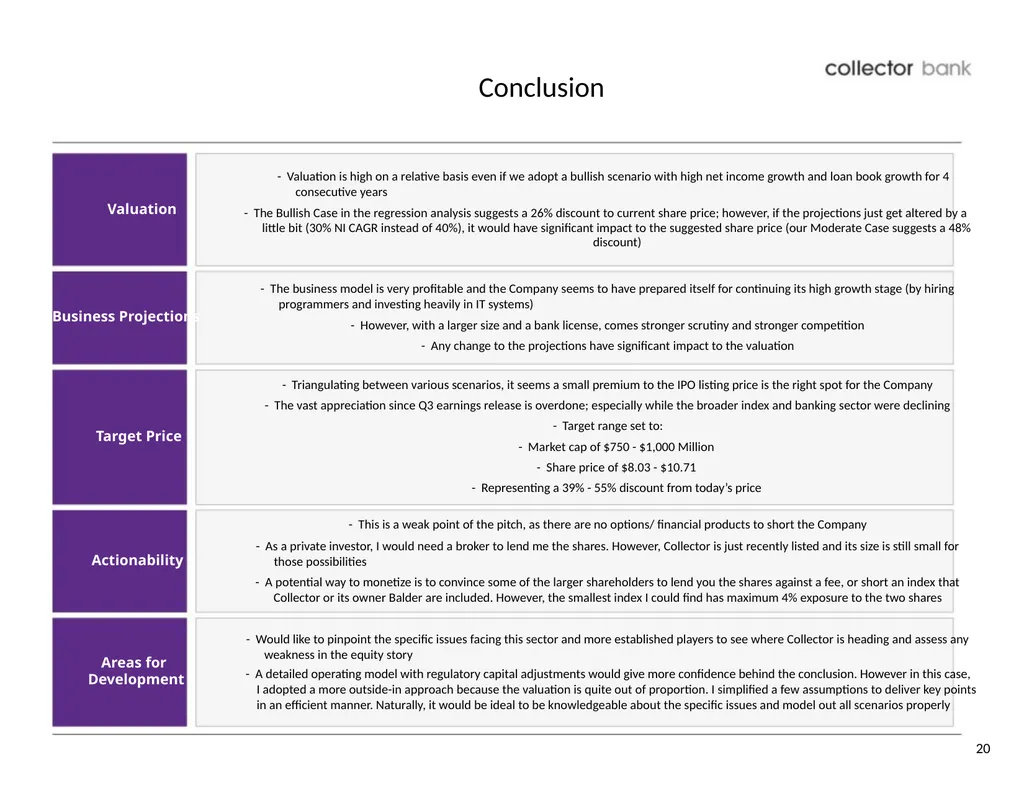
slide20. Conclusion - Valuation is high on a relative basis even if we adopt a bullish scenario with high net income growth and loan book growth for 4 consecutive years Valuation Business Projections Target Price Actionability Areas for Development - The Bullish Case in the regression analysis suggests a 26% discount to current share price; however, if the projections just get altered by a little bit (30% NI CAGR instead of 40%), it would have significant impact to the suggested share price (our Moderate Case suggests a 48% discount) - The business model is very profitable and the Company seems to have prepared itself for continuing its high growth stage (by hiring programmers and investing heavily in IT systems) - However, with a larger size and a bank license, comes stronger scrutiny and stronger competition - Any change to the projections have significant impact to the valuation - Triangulating between various scenarios, it seems a small premium to the IPO listing price is the right spot for the Company - The vast appreciation since Q3 earnings release is overdone; especially while the broader index and banking sector were declining - Target range set to: - Market cap of $750 - $1,000 Million - Share price of $8.03 - $10.71 - Representing a 39% - 55% discount from today’s price - This is a weak point of the pitch, as there are no options/ financial products to short the Company - As a private investor, I would need a broker to lend me the shares. However, Collector is just recently listed and its size is still small for those possibilities - A potential way to monetize is to convince some of the larger shareholders to lend you the shares against a fee, or short an index that Collector or its owner Balder are included. However, the smallest index I could find has maximum 4% exposure to the two shares - Would like to pinpoint the specific issues facing this sector and more established players to see where Collector is heading and assess any weakness in the equity story - A detailed operating model with regulatory capital adjustments would give more confidence behind the conclusion. However in this case, I adopted a more outside-in approach because the valuation is quite out of proportion. I simplified a few assumptions to deliver key points in an efficient manner. Naturally, it would be ideal to be knowledgeable about the specific issues and model out all scenarios properly 20<br>
slide21. Appendix 1 Loan Book and Capitalization Details 21<br>
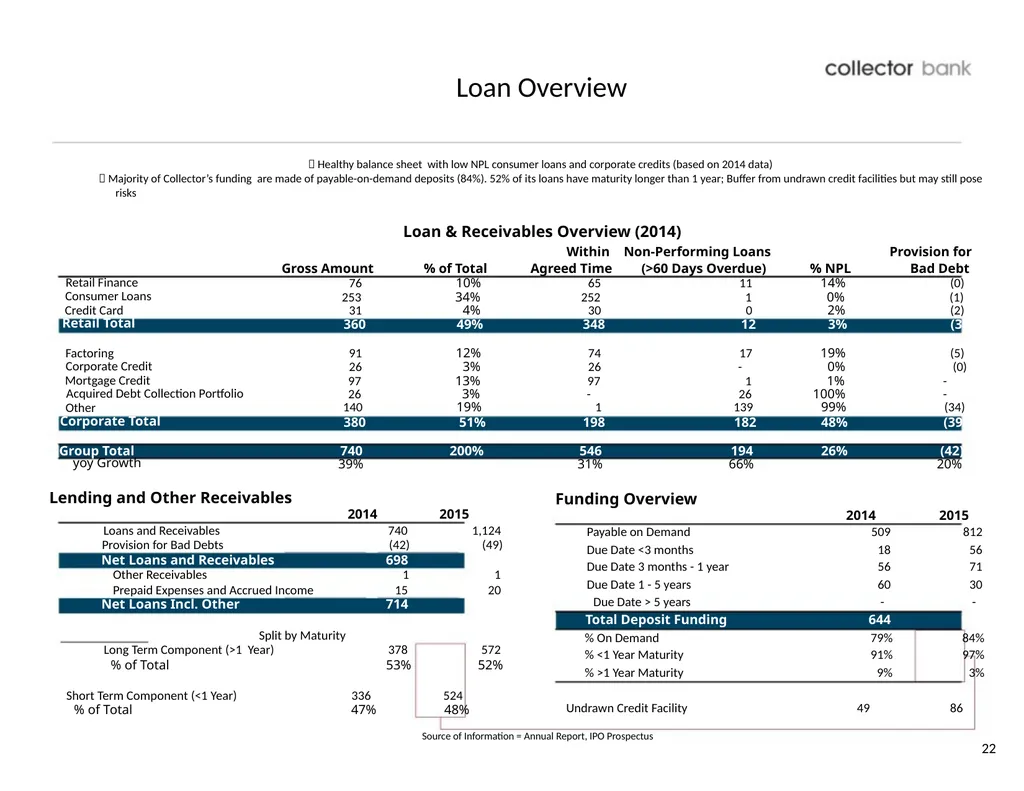
slide22. Loan Overview Healthy balance sheet with low NPL consumer loans and corporate credits (based on 2014 data) Majority of Collector’s funding are made of payable-on-demand deposits (84%). 52% of its loans have maturity longer than 1 year; Buffer from undrawn credit facilities but may still pose risks Loan & Receivables Overview (2014) Within Non-Performing Loans Provision for Gross Amount % of Total Agreed Time (>60 Days Overdue) % NPL Bad Debt Retail Finance 76 10% 65 11 14% (0) Consumer Loans 253 34% 252 1 0% (1) Credit Card 31 4% 30 0 2% (2) Retail Total 360 49% 348 12 3% (3) Factoring 91 12% 74 17 19% (5) Corporate Credit 26 3% 26 - 0% (0) Mortgage Credit 97 13% 97 1 1% - Acquired Debt Collection Portfolio 26 3% - 26 100% - Other 140 19% 1 139 99% (34) Corporate Total 380 51% 198 182 48% (39) Group Total 740 200% 546 194 26% (42) yoy Growth 39% 31% 66% 20% Lending and Other Receivables Funding Overview 2014 2015 2014 2015 Loans and Receivables 740 1,124 Provision for Bad Debts (42) (49) Net Loans and Receivables 698 1,075 Other Receivables 1 1 Prepaid Expenses and Accrued Income 15 20 Net Loans Incl. Other 714 1,096 Split by Maturity Long Term Component (>1 Year) 378 572 % of Total 53% 52% Payable on Demand 509 812 Due Date <3 months 18 56 Due Date 3 months - 1 year 56 71 Due Date 1 - 5 years 60 30 Due Date > 5 years - - Total Deposit Funding 644 971 % On Demand 79% 84% % <1 Year Maturity 91% 97% % >1 Year Maturity 9% 3% Short Term Component (<1 Year) 336 524 % of Total 47% 48% Undrawn Credit Facility 49 86 Source of Information = Annual Report, IPO Prospectus 22<br>
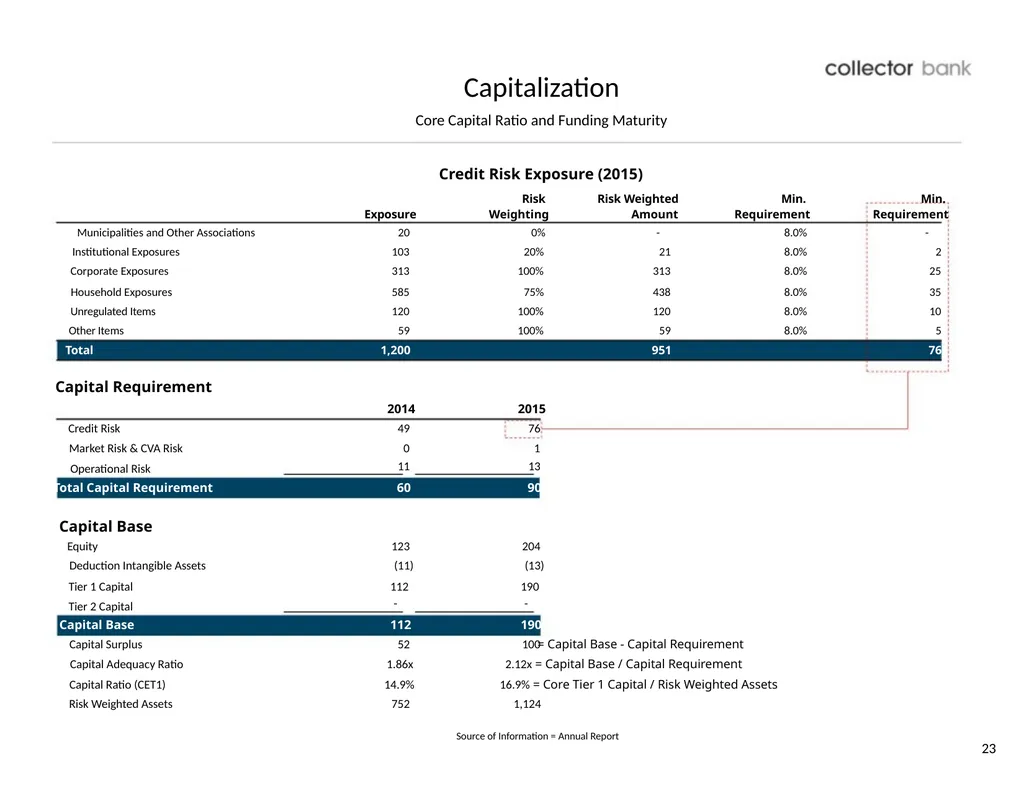
slide23. Capitalization Core Capital Ratio and Funding Maturity Credit Risk Exposure (2015) Risk Risk Weighted Min. Min. Exposure Weighting Amount Requirement Requirement Municipalities and Other Associations 20 0% - 8.0% - Institutional Exposures 103 20% 21 8.0% 2 Corporate Exposures 313 100% 313 8.0% 25 Household Exposures 585 75% 438 8.0% 35 Unregulated Items 120 100% 120 8.0% 10 Other Items 59 100% 59 8.0% 5 Total 1,200 951 76 Capital Requirement 2014 2015 Credit Risk 49 76 Market Risk & CVA Risk 0 1 Operational Risk 11 13 Total Capital Requirement 60 90 Capital Base Equity 123 204 Deduction Intangible Assets (11) (13) Tier 1 Capital 112 190 Tier 2 Capital - - Capital Base 112 190 Capital Surplus 52 100 = Capital Base - Capital Requirement Capital Adequacy Ratio 1.86x 2.12x = Capital Base / Capital Requirement Capital Ratio (CET1) 14.9% 16.9% = Core Tier 1 Capital / Risk Weighted Assets Risk Weighted Assets 752 1,124 Source of Information = Annual Report 23<br>
slide24. Appendix 2 Supporting Materials 24<br>
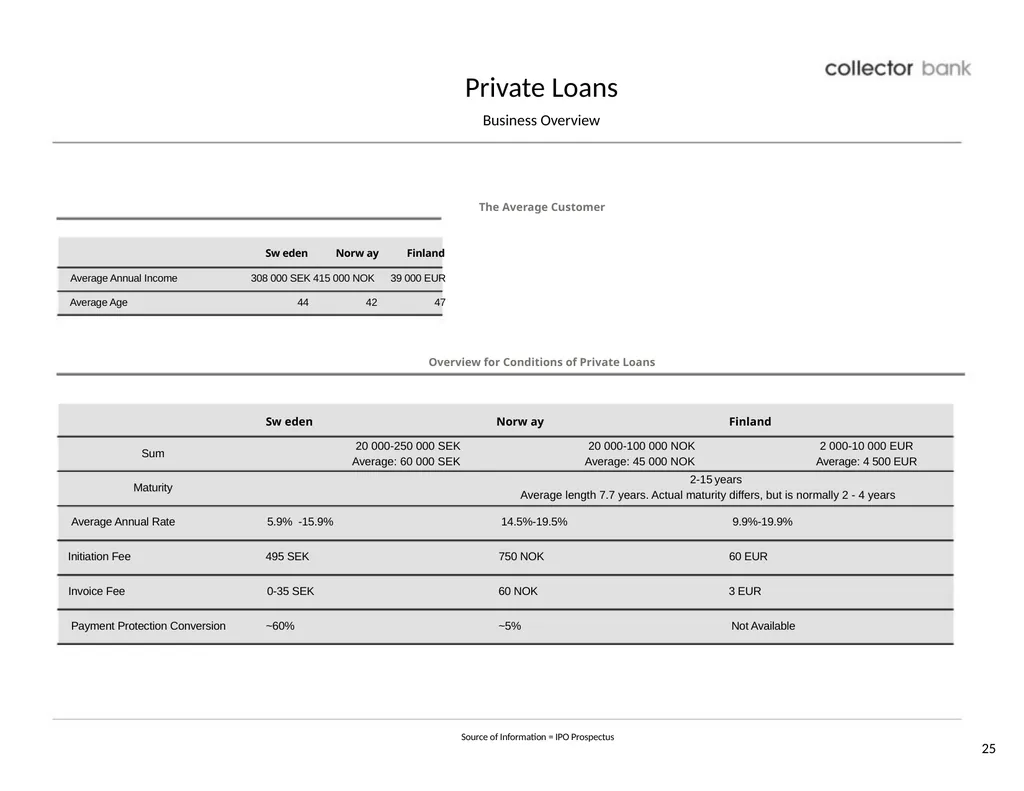
slide25. Private Loans Business Overview The Average Customer Sw eden Norw ay Finland Average Annual Income 308 000 SEK 415 000 NOK 39 000 EUR Average Age 44 42 47 Overview for Conditions of Private Loans Sw eden Norw ay Finland Sum Maturity 20 000-250 000 SEK 20 000-100 000 NOK 2 000-10 000 EUR Average: 60 000 SEK Average: 45 000 NOK Average: 4 500 EUR 2-15 years Average length 7.7 years. Actual maturity differs, but is normally 2 - 4 years Average Annual Rate 5.9% -15.9% 14.5%-19.5% 9.9%-19.9% Initiation Fee 495 SEK 750 NOK 60 EUR Invoice Fee 0-35 SEK 60 NOK 3 EUR Payment Protection Conversion ~60% ~5% Not Available Source of Information = IPO Prospectus 25<br>
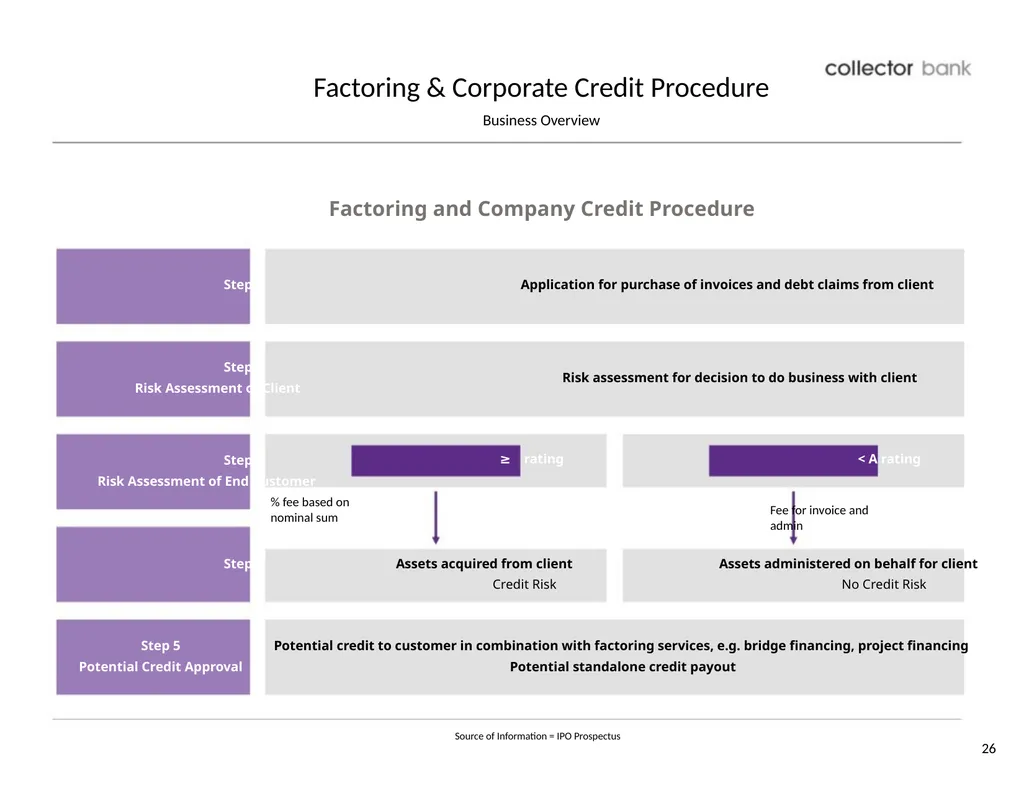
slide26. Factoring & Corporate Credit Procedure Business Overview Factoring and Company Credit Procedure Step 1 Step 2 Risk Assessment of Client Step 3 Risk Assessment of End Customer % fee based on nominal sum Step 4 Application for purchase of invoices and debt claims from client Risk assessment for decision to do business with client ≥ rating < A rating Fee for invoice and admin Assets acquired from client Assets administered on behalf for client Credit Risk No Credit Risk Step 5 Potential credit to customer in combination with factoring services, e.g. bridge financing, project financing Potential Credit Approval Potential standalone credit payout Source of Information = IPO Prospectus 26<br>
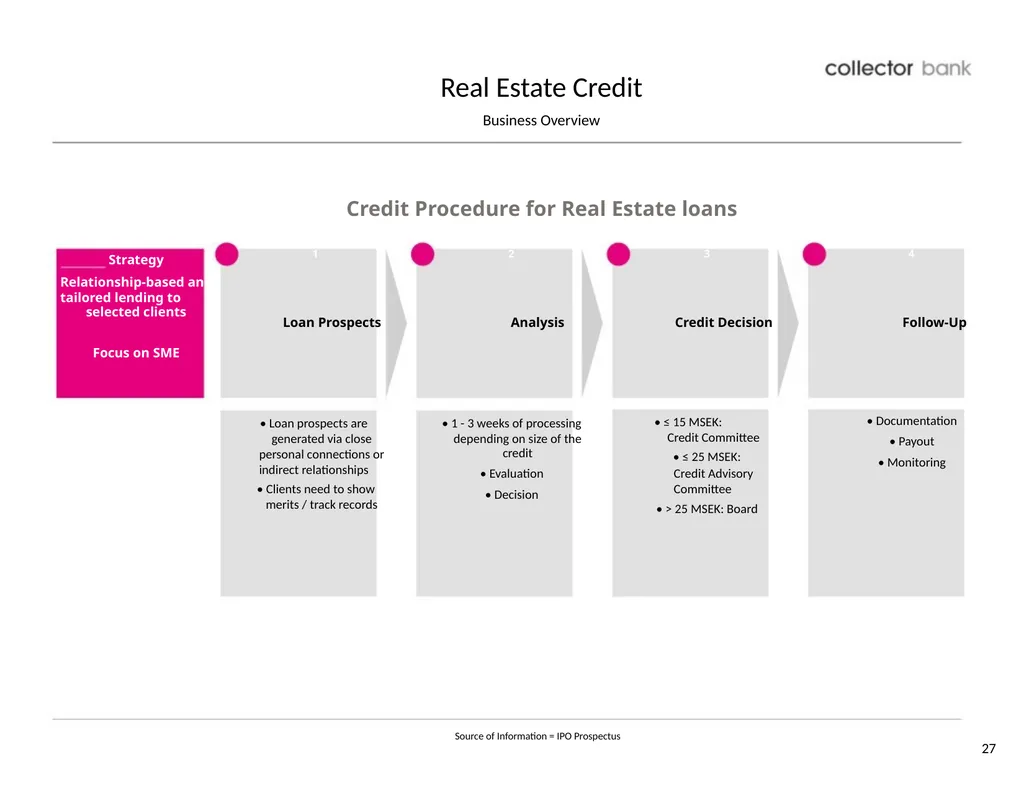
slide27. Real Estate Credit Business Overview Credit Procedure for Real Estate loans Strategy Relationship-based and tailored lending to selected clients Focus on SME 1 Loan Prospects • Loan prospects are generated via close personal connections or indirect relationships • Clients need to show merits / track records 2 Analysis • 1 - 3 weeks of processing depending on size of the credit • Evaluation • Decision 3 Credit Decision • ≤ 15 MSEK: Credit Committee • ≤ 25 MSEK: Credit Advisory Committee • > 25 MSEK: Board 4 Follow-Up • Documentation • Payout • Monitoring Source of Information = IPO Prospectus 27<br>
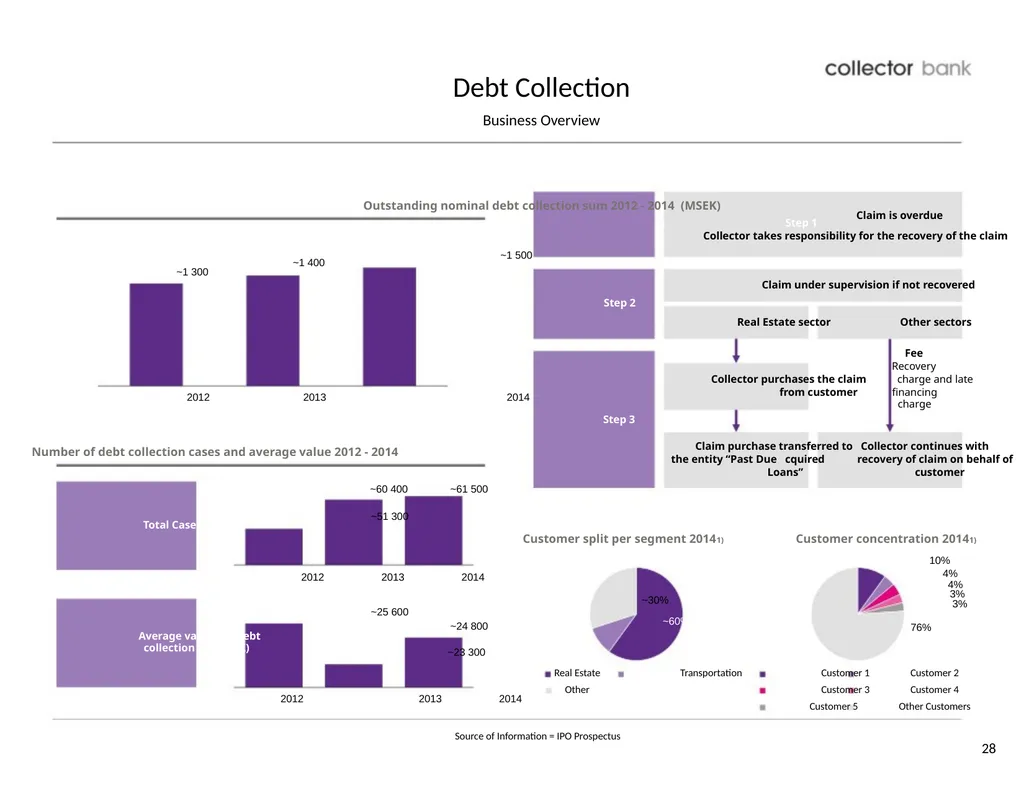
slide28. Debt Collection Business Overview Outstanding nominal debt collection sum 2012 - 2014 (MSEK) Claim is overdue Step 1 Collector takes responsibility for the recovery of the claim ~1 300 ~1 400 ~1 500 Step 2 Claim under supervision if not recovered Real Estate sector Other sectors Fee Recovery Collector purchases the claim charge and late 2012 2013 Number of debt collection cases and average value 2012 - 2014 2014 Step 3 from customer financing charge Claim purchase transferred to Collector continues with the entity “Past Due cquired recovery of claim on behalf of Total Cases ~60 400 ~61 500 ~51 300 2012 2013 2014 ~25 600 ~24 800 Customer split per segment 20141) ~30% ~60% Loans” customer Customer concentration 20141) 10% 4% 4% 3% 3% Average value per debt collection case (SEK) 2012 ~23 300 Real Estate Other 2013 2014 ~10% 76% Transportation Customer 1 Customer 2 Customer 3 Customer 4 Customer 5 Other Customers Source of Information = IPO Prospectus 28<br>
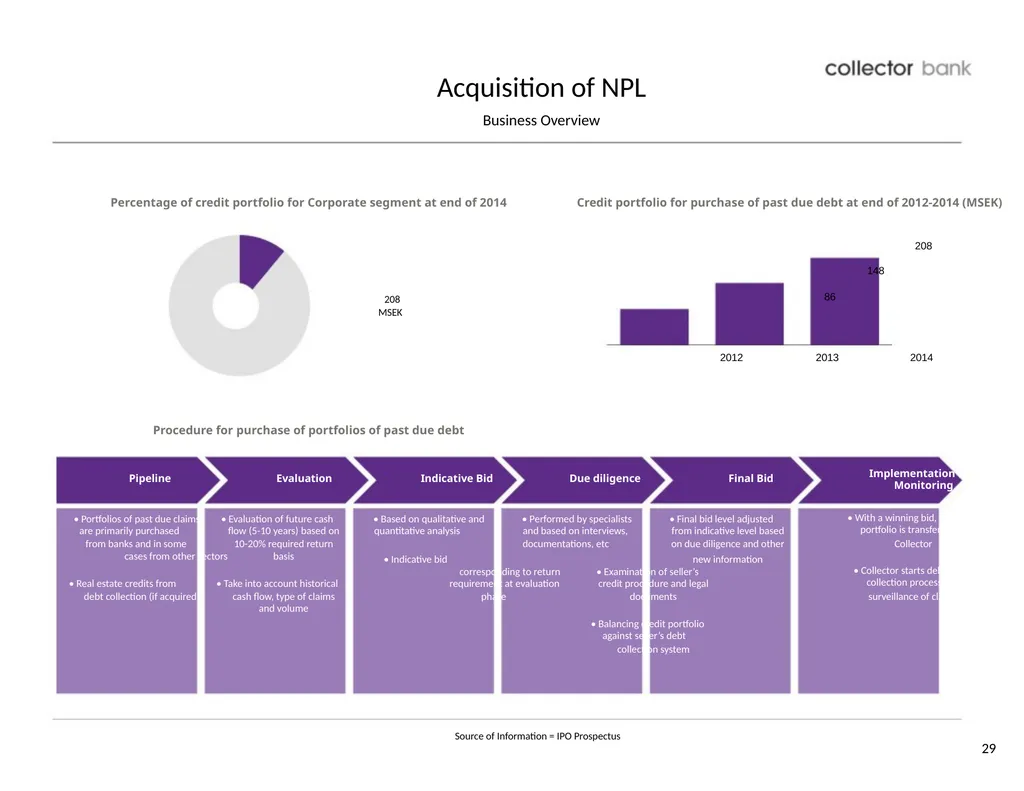
slide29. Acquisition of NPL Business Overview Percentage of credit portfolio for Corporate segment at end of 2014 11% 208 MSEK Procedure for purchase of portfolios of past due debt Credit portfolio for purchase of past due debt at end of 2012-2014 (MSEK) 208 148 86 2012 2013 2014 Implementation and Pipeline Evaluation • Portfolios of past due claims • Evaluation of future cash are primarily purchased flow (5-10 years) based on from banks and in some 10-20% required return cases from other sectors basis • Real estate credits from • Take into account historical debt collection (if acquired) cash flow, type of claims and volume Indicative Bid Due diligence Final Bid • Based on qualitative and • Performed by specialists • Final bid level adjusted quantitative analysis and based on interviews, from indicative level based documentations, etc on due diligence and other • Indicative bid new information corresponding to return • Examination of seller’s requirement at evaluation credit procedure and legal phase documents • Balancing credit portfolio against seller’s debt collection system Monitoring • With a winning bid, portfolio is transferred to Collector • Collector starts debt collection process and surveillance of claims Source of Information = IPO Prospectus 29<br>
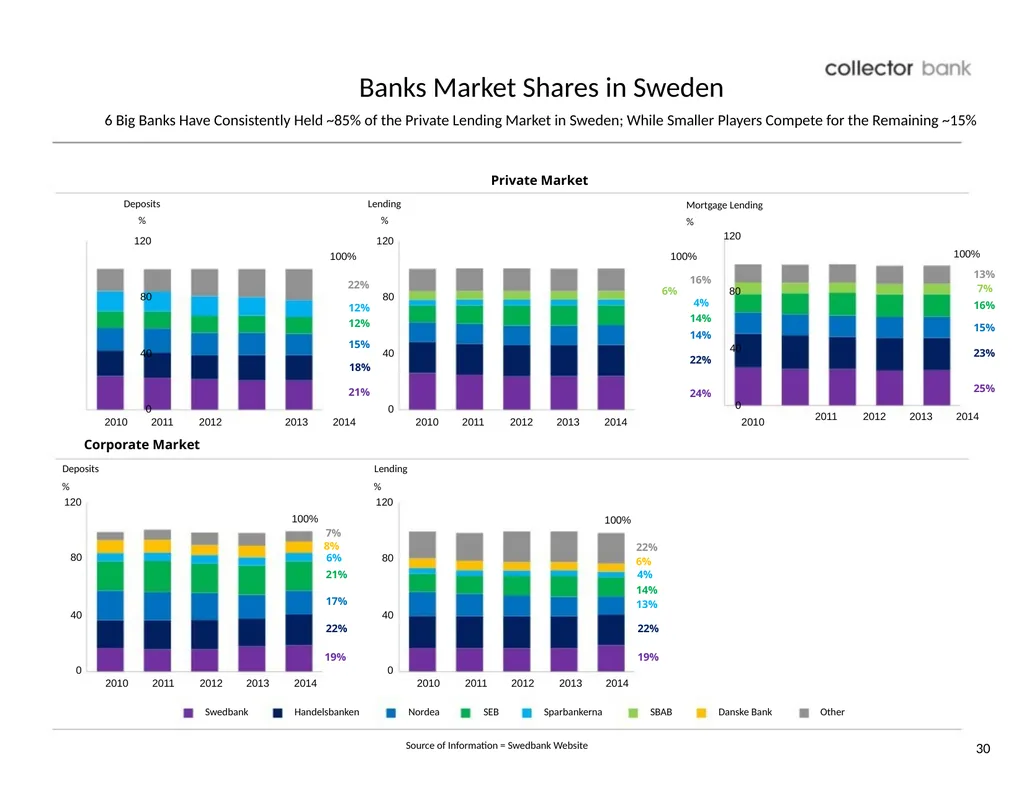
slide30. Banks Market Shares in Sweden 6 Big Banks Have Consistently Held ~85% of the Private Lending Market in Sweden; While Smaller Players Compete for the Remaining ~15% Private Market Deposits % 120 80 40 0 2010 2011 2012 Corporate Market Lending % 120 100% 22% 80 12% 12% 15% 40 18% 21% 0 2013 2014 2010 2011 2012 2013 Mortgage Lending % 120 100% 16% 6% 80 4% 14% 14% 40 22% 24% 0 2014 2010 100% 13% 7% 16% 15% 23% 25% 2011 2012 2013 2014 Deposits Lending % % 120 120 100% 100% 7% 8% 22% 80 6% 80 6% 21% 4% 14% 17% 13% 40 40 22% 22% 19% 19% 0 0 2010 2011 2012 2013 2014 2010 2011 2012 2013 2014 Swedbank Handelsbanken Nordea SEB Sparbankerna SBAB Danske Bank Other Source of Information = Swedbank Website 30<br>
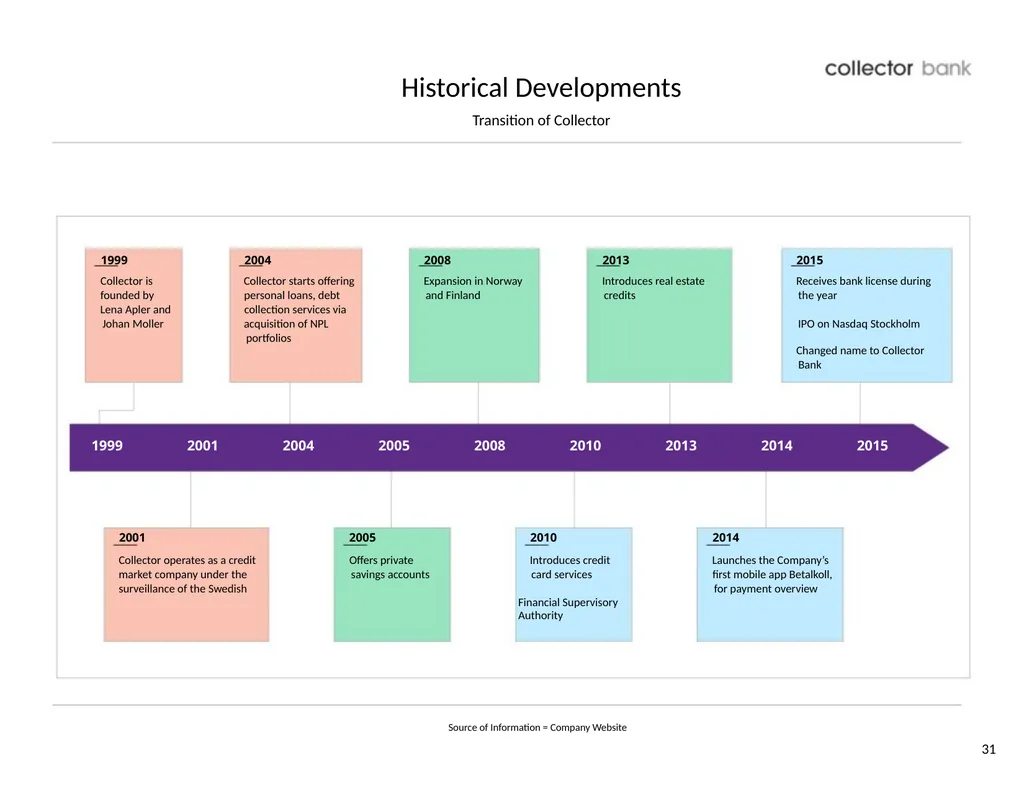
slide31. Historical Developments Transition of Collector 1999 2004 2008 2013 2015 Collector is Collector starts offering Expansion in Norway Introduces real estate Receives bank license during founded by personal loans, debt and Finland credits the year Lena Apler and collection services via Johan Moller acquisition of NPL IPO on Nasdaq Stockholm portfolios Changed name to Collector Bank 1999 2001 2004 2005 2008 2010 2013 2014 2015 2001 2005 2010 2014 Collector operates as a credit Offers private Introduces credit Launches the Company’s market company under the savings accounts card services first mobile app Betalkoll, surveillance of the Swedish for payment overview Financial Supervisory Authority Source of Information = Company Website 31<br>
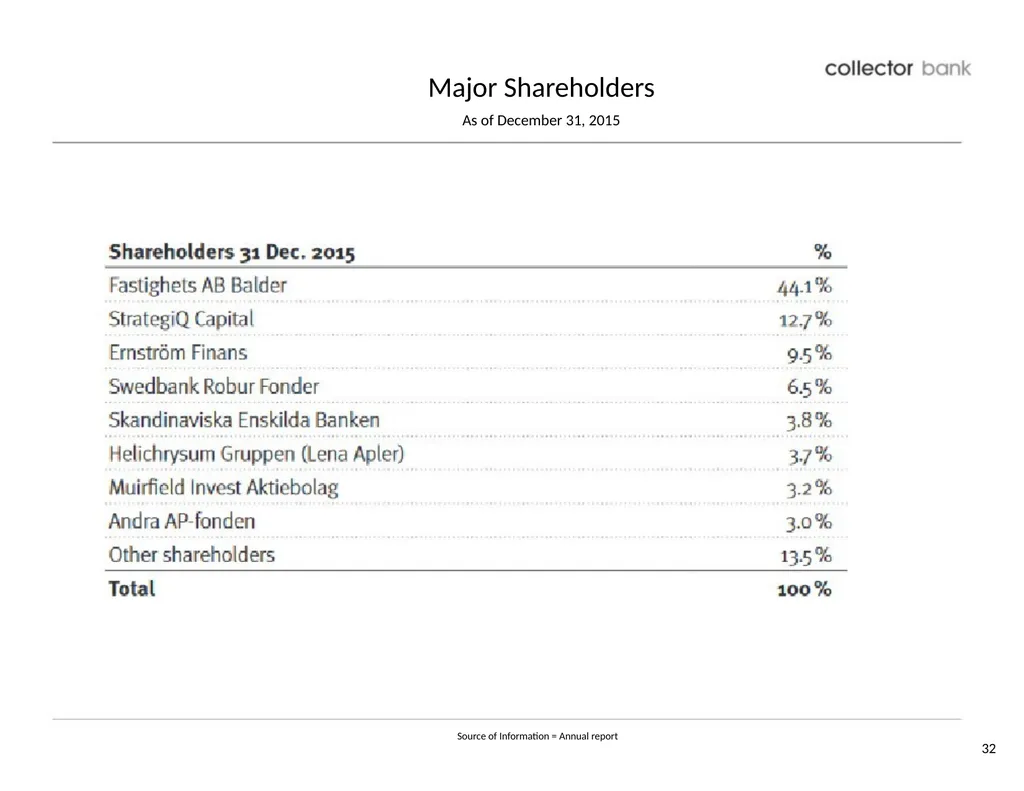
slide32. Major Shareholders As of December 31, 2015 Source of Information = Annual report 32<br>
slide2. Investment Thesis Collector Bank B (“Collector”) is primarily a consumer lending company based in Sweden It has expanded product offering in recent years and received a bank license in 2015 Background Collector was listed in Stockholm on June 10, 2015 It’s share price has appreciated by 124% since then, while the broader index and banking peers depreciated by 12-16% over the same period Collector’s share price appreciation since its Q3 2015 earnings release has been too optimistic (+51% since 11/2/2015) The Company showed high growth rate on its lending book and revenues, which was appreciated by the market Thesis Findings Target Valuation However, the Company invested heavily in its IT system, mobile apps and raised its depository rates in a low interest rate environment in order to generate those growth This is not a guarantee for continued future success; potential issues include rising competition and regulatory pressures Collector is trading at a level well beyond its banking, consumer finance and credit management peers even adjusted for reasonable amount of growth Even when adopting a very bullish scenario with 40% net income CAGR for 4 consecutive years, no dividend and no capital constraints, the various metrics indicate that Collector is still overpriced versus its peers The Nordic banks are trading within the 1.0x - 2͘0x Price / Tangible Book Value (“TBV”) range; Consumer Finance peers are trading in the 2͘5x - 3.5x range; and Collector is currently trading at 8.9x times 2015 TBV - The price gain since Q3 2015 is too optimistic and as the price at that time could be justified for a high growth, high RoE story - Target range set to: - Market cap of $750 - $1,000 Million - Share price of $8.03 - $10.71 - Representing a 39% - 55% discount from today’s price 2<br>
slide3. Agenda 1 Business Overview 2 Valuation Analysis 3 Risks, Catalysts and Conclusion 4 Appendix 1 - Loan Book and Capitalization Details 5 Appendix 2 - Supporting Materials 3<br>
slide4. Section 1 Business Overview 4<br>
slide5. Snapshot of Collector Bank AB High Growth Business; Share Price Increased by 124% since IPO on June 10, 2015 Business Overview Key Financials 1 • Collector Bank B (“Collector”) is a financial services company engaged USD Millions 2012 2013 2014 2015 Total Income 73 86 113 147 primarily in the consumer finance and SME loan businesses in Sweden % Growth 18% 31% 30% • Founded in 1999, Collector was originally a credit market company providing factoring services to corporates. The Company expanded its services throughout the years to include real estate credit, retail financing, credit cards and consumer loans, among others • Collector received a bank license in 2015 with the goal to strengthen its brand and target larger corporate clients – Subject to the Swedish Financial Supervisory uthority’s regulations regarding capital adequacy and exposure – >90% of its depositors are protected by the Swedish Government’s Depository Guarantee system Operating Profit 26 % Margin 36% Net Interest Expense (8) Earnings Before Tax 18 Tax Expense (4) Implied Tax Rate 22% Net Income 14 % Growth Gross Loans & Receivables 352 % Growth Deposits 353 % Growth Equity (Book Value) 63 Tangible Equity (TBV) 49 Risk Weighted Assets n/a CET 1 Ratio (%) n/a 31 42 56 36% 37% 38% (8) (12) (10) High 24 30 46 Growth (5) (7) (11) Model 23% 23% 23% 18 23 35 30% 27% 52% 510 698 1,075 45% 37% 54% 474 644 971 34% 36% 51% 79 123 204 63 106 184 n/a 752 1,124 n/a 14.1% 16.4% • June 10, 2015, Collector was listed on the Nasdaq Stockholm Stock Market Statistics Exchange at SEK 55 per share (~$6.76 at current exchange rate 1) issuance 1st Trading Day Current price USD Millions 6/10/2015 4/21/2016 – SEK400MM of new issuance to strengthen the capital base and prepare for continued growth – The share price closed at SEK63.60 ($7.86 1), up 16% on the IPO day – It went up a further 124% to SEK142.00 ($17.67 1) as of April 21, 2016 • Based in Gothenburg, Sweden Share Price TSO Market Cap Book Value (LTM) Tangible Book Value (LTM) P/E 2016E P/E 2017E P/BV (Last Reported) P/TBV (Last Reported) $7.86 $17.67 93.36 93.36 734 1,649 130 204 112 184 n/a 30.9x n/a 22.8x 5.66x 8.10x 6.54x 8.95x Source of Information = Company Website, IPO Prospectus, Capital IQ Footnote 1. SEK / USD exchange rate of 8.17 used across this presentation, including historical financials for easier comparison of historical growth 5<br>
slide6. Business Overview Collector Operates in Two Segments: Retail and Corporate Illustrative Business Models Shown in Appendix Services 1 Personal Loans Retail (~64% of Retail Financing / Loan book) Payment Solutions Credit Cards 2 Factoring Company Credits Corporate (~36% of Loan book) Real Estate Credits Past Due Acquired Loans Gross Loans (2014) 12 $251mm (34% of total) $76mm (10%) $31mm (4%) $91mm (12%) $25mm (3%) $97mm (13%) $26mm (3%) Description Unsecured credits to private individuals in Sweden, Norway and Finland of up to SEK 250,000 Average duration of 2-4 years, but could be up to 15 years Financed primarily by deposits (xxx%), offering 0.70% savings rate for 1-year accounts and 0.75% for 2-year accounts Offers retail financing for e-commerce and retail chains Credit facilities comprise of payment by instalments, current account credit or invoices of 30-45 days and pertains to financing of purchases of goods The credits are unsecured loans, which mainly target private individuals in Sweden Low average amount of credit of ~$100, and short average term of just over 2 months Provides credit cards for private individuals in Sweden with a credit limit up to SEK 100,000 Collector either buys or pledges the customer company’s issued invoices Collector assumes the credit risk; primarily has a credit risk on the invoice issuer and not the final customer, who is the invoice recipient Shorter operating credits, known as bridge financing where the credit is usually linked to one of Collector’s other operations, such as the factoring business Normally secured with adequate collateral and have relatively short terms Larger credits that are targeted at commercial actors and comprise junior loans with security in multi-dwelling properties and commercial properties in larger cities The loan-to-value ratio is normally a maximum of 80% of properties’ appraised market value Normally secured with adequate collateral and have relatively short terms Credit portfolios with overdue receivables against private individuals that were acquired from other creditors in Sweden, Norway and Finland The receivables can have been past due from a few months up to several years; Collector normally demands guarantees from seller in acquisition of disputed claims Source of Information = Company Website, Annual Reports, IPO Prospectus Footnotes 1. Segment loan book size excludes “other loans” 2. SEK / USD exchange rate of 8.17 used across this presentation, including historical financials for easier comparison of historical growth 6<br>
slide7. Financial Overview Collector Is a Lending Based Business Majority of revenue generated via interest income, i.e. the lending operations 113 86 22 73 9 Home market Sweden remains the largest market; although strong foothold in Finland and Norway 147 14 12 2 10 17 8 37 11 8 13 9 59 70 Interest 119 Income is 81% of 18% total revenue 57% Oslo 23% Helsingfors Stockholm Gothenburg (HQ) 2012 2013 2014 2015 Other Markets 1% Interest Income Commission Income Credit Management Other Retail Segment is the key contributor to Collector’s performance (2015 Data) Income Interest Expense Credit Losses 106 52 6 11 Malmö 60 % of Revenue in 2014 Collector Offices Other Costs 32 % of Total (12) Retail Corporate Elimination 73% 35% (8%) 3 Retail Corporate Retail 64% 36% 97% 0 (12) Corporate Retail Corporate Elimination 3% 75% 40% (15%) Source of Information = Company Website, Annual Reports, IPO Prospectus 7<br>
slide8. Historical Financials Starting from a Low Base, Collector Delivered Consistent High Growth over the Last 10 Years Historical Events Timeline Shown in Appendix Revenue USD Millions 200 +72% 150 Yoy Growth Rate +52% +32% +34% Revenue increased steadily at CAGR of 30% over the last 10 years +13% +19% +8% +18% +31% +30% 147 113 86 100 50 0 11 2005 37 19 28 2006 2007 2008 50 56 2009 2010 67 73 2011 2012 2013 2014 2015 Earnings Before Tax USD Millions 80 11% 15% 60 19% 20% 22% 27% Margins Improved Steadily over the years 26% 25% 27% 27% 31% % of Revenue 40 20 1 3 0 2005 2006 8 11 5 2007 2008 2009 24 15 17 18 2010 2011 2012 2013 46 30 2014 2015 Credit Portfolio Size $MM 1,500 1,000 500 +96% Yoy Growth Rate +66% Loan book increased significantly during the low interest rate environment over the last few years +26% +12% +17% +23% +45% +40% +54% 1,075 698 499 343 169 52 102 0 2005 2006 2007 2008 214 239 279 2009 2010 2011 2012 2013 2014 2015 Source of Information = IPO Prospectus 8<br>
slide9. Section 2 Equity Story and Valuation Overview 9<br>
slide10. Equity Story And Question Marks Current Sellside Equity Story 1 High Growth 2 High RoE 3 Low Credit Risk 4 Digitalization 5 New Services Impressive history of organic growth builds confidence on Collector’s ability to continue the same trend; sellside research giving credit to continued ~30% revenue and loan growth for the next few years; small market share (<0.5%) allows for quick market share gain Historical returns over 20%; expect to at least maintain this level Low loan loss figures (~1%), with in-house debt collection; also very difficult for individuals to get away with debt claims in Sweden Collector refers to itself as “an internet company with bank license” with an agile system͘ With a bank license, the company aims to strengthen its brand name and target larger corporate customers; hired 100 IT programmers to build in-house systems Potential to grow in new services, along with digitalization, and earn higher tech multiples However, what if the assumptions do not hold? Potential Risks with the Equity Story Business model / Regulatory Macroeconomic High growth rate at Interest rate Competition Competition from Management ability financials still constraints / condition / current size might environment with existing new entrants and to steer the bigger lending based capital reserve consumer spending cause constraints big banks existing consumer and more regulated rather than tech requirement for power finance companies entity licensed bank deterioration But first, is the stock price justified even if these assumptions hold true? See next page 10<br>
slide11. Valuation Summary Assessing the Current Public Market Equity Story Collector has stated target to keep up its historical organic growth rate (~30% p.a. for revenue and ~55% p.a. for net income as disclosed by the Company) Collector is currently trading well beyond its peers in every metric (see next few pages for details). This is essentially a result of the Company’s strong growth story One way we could look at this is to take the projected growth rates at face value for a few years, and decide if the valuation is justified even in a bullish scenario. Here, we arrive at the Company’s future earnings by using the stated growth rates, and applying the current trading level of selected peers, and lastly discounting its share price back to present at a reasonable illustrative cost of equity The quick metrics we use are i) Price / Forward Looking Earnings, ii) Price / Tangible Book Value, and iii) regression analysis based on RoTE vs. P / TBV A full operating model with dividend discount model valuation would be useful if there is enough time and if we need to dig into more details; currently, the risk weighted assets are assumed to grow at 30% p.a. and capital threshold of 15.0% (stated by the Company) still holds Low High Value Trading Range Since IPO $7.48 $18.50 Trading Valuation (Current Financials) Price / Net Income (2016E) 10.0x 13.0x 50 Price / Net Income (2017E) 10.0x 14.0x 69 Trading Valuation (as of Dec 2017, discount back at CoE of 10.0%) Assume 40% Net Income CAGR until 2019, no dividend, RWA CAGR 30.0%, CET 1 Threshold 15.0% Price / Earnings (2018E) 10.0x 13.0x 97 Price / Earnings (2019E) 10.0x 14.0x 136 Price / Book Value (2017E) 2.4x 2.8x 323 Price / Tangible Book Value (2017E) 2.5x 3.4x 290 Regression Analysis (as of Dec 2018, discount back) RoTE 2018E vs. P/TBV 2018E - Bullish Case (CoE = 10.0%) 3.4x 4.4x 400 RoTE 2018E vs. P/TBV 2018E - Moderate Case (CoE = 12.0%) 2.7x 3.7x 368 Interestingly, this exercise tells us that the current valuation is justified only if we believe Collector can grow its net income by 40% per year for 4 consecutive years; and apply the higher range of peers P/E multiple range (14.0x) to that earnings. If we have doubt on this scenario, price should be corrected from current level Meanwhile, using consumer finance peers P / Book Value multiples suggests Collector should trade at a level slightly higher than its issuance price The regression analysis takes into account profitability on deployed capital and suggests a range of $750 - $1,000 Million market cap. See details on page 16 Market Capitalization (USD Millions) First Trading Day Post IPO: $7.86 Today’s Price: $17͘67 Market Cap: $734 Million Market Cap: $1,649 Million 698 1,727 495 644 693 970 826 1,073 1,156 1,618 659 768 616 838 1,060 1,369 722 993 0 500 1,000 1,500 2,000 This would be a more reasonable valuation range - Market cap of $750 - $1000 Million - Share price of $8.03 - $10.71 - Representing a 39% - 55% discount from today’s price 11<br>
slide12. Collector Share Price Development Since IPO on 6/10/2015 The big jumps in Collector share price came in post the release of Q3 and full-year earnings (+51% since Q3 earnings) There were a couple press releases throughout this period, but none seemed to move the stock Meanwhile, big banks and the Stockholm OMX 30 index declined by 12-16% over the same period Will Collector have the strength to keep up this trend? What level of expectation is the market placing on its next earnings report? Share Price Performance Rebased to Collector (Converted to USD / Share) 20 Share Price +20% 17 14 11 8 5 7/17/2015 • Q2 earnings release • Revenue +35% yoy • Net income +46% yoy • Loan book of $807 million, up 16% since December 11/3/2015 • Q3 earnings release • Revenue +33% yoy • Net income +55% yoy • Loan book up +% yoy to $918 millions +32% since December Share Price +35% Share Price (19%) Share Price +59% Collector +124% 2/11/2016 • Full year 2015 results • Revenue +30% yoy • Net income +52% yoy • Loan volume +54% yoy, now at $1,075 million Stockholm OMX 30 Index (12%) Nordic Banks 1 (16%) 6/10/15 7/10/15 8/11/15 9/10/15 10/12/15 11/11/15 12/11/15 1/12/16 2/11/16 3/14/16 4/13/16 Source of Information = Company Website, Capital IQ Footnote 1. Nordic banks index consists of SEB, Handelsbanken, Nordea, Swedbank and Danske Bank; see details on next page 12<br>
slide13. Peer Selection In Search for the Right Benchmark Peers Company MarketCap Key Stats Description “Big Four” Banks with >75% market share in Sweden One of Northern Europe’s leading financial groups͘ SEB serves over 2 million customers in Sweden and more than 1͘3 million customers in Denmark, Norway and Finland͘ The Bank’s operations have SEB Swedbank Nordic Banks Handels- banken Nordea $22.2 Billion $167 Billion $23.5 Billion $175 Billion $25.9 Billion $235 Billion $40.3 Billion $386 Billion a strong focus on corporate and investment banking Strong position in fund management and life insurance, as well as in the mortgage and finance company sectors; strong player in the stock market, FX trading and international payments A leading Nordic-Baltic banking group with approximately 8 million private and corporate customers. It has >400 branches in its home markets of Sweden, Estonia, Latvia and Lithuania Close co-operation with independent savings banks and partly owned banks among the savings banks movement One of the largest banks in Sweden with a presence in 25 countries, which makes it the most international bank in the Nordic region Extensive operations in the fund management and finance company sectors The leading financial institution in the Nordic and Baltic region with market cap of US$41 billion as of March 8, 2016. Nordea is number one or two in the most Nordic markets with about 11 million customers and 700 branches The largest bank and financial conglomerate in Denmark, serving both private individuals and large Danske Bank Cembra Consumer Finance Nordax Credit Mgmt. Hoist $21.4 Billion $225 Billion $1.9 Billion $4.0 Billion $600 Million $1.3 Billion $769 Million n/a institutional clients Largest foreign bank in Sweden with over 40 branches Consumer finance bank providing savings products, incl. medium-term notes and deposit accounts, a variety of loans including consumer loans, credit card receivables, auto loans, etc. Targets private individuals and SME; As of March 2016, it operated through a network of 25 branches Provides personal loans and deposit accounts to private individuals in Sweden, Norway, Finland, Denmark and Germany; similar business to the majority of Collector’s income generation The company was founded in 2003 and based in Stockholm, Sweden Provides solutions for acquisition and management of non-performing unsecured consumer loans in Europe The company purchases non-performing loans originated by international banks and other financial institutions 13<br>
slide14. Peer Operational Benchmarking Superior Growth Profile vs. Peers; However, RoTE Profile Not Too Dissimilar From Consumer Finance and Credit Management Peers Sellside research and the Company itself are anticipating ~30% topline growth, and 40-50% earnings growth over the coming few years 2015A- 2018E Loan Growth CAGR % 35 30 30 25 20 15 Consumer Credit Nordic Banks Finance Mgmt 16 8 2016E- 2018E Earnings Per Share Growth CAGR % 50 Nordic Banks 40 40 30 20 10 5 6 Consumer Finance 17 8 8 Credit Mgmt 20 10 4 5 2 0 3 4 3 3 3 0 (10) (1) Collector Nordea Handels Swed SEB Danske Cembra Nordax -banken -bank Core Tier 1 Ratio (Core Equity / Risk Weighted Assets, Basel 3) 2015A % Consumer 35 Nordic Banks Finance 30 24 Hoist Collector Nordea Handels -banken Return on Tangible Equity 2017E % Credit Mgmt 50 40 Swed SEB Danske Cembra Nordax Hoist -bank Consumer Credit Nordic Banks Finance Mgmt 31 25 20 15 10 5 0 21 16 16 Collector Nordea Handels Swed -banken -bank 19 20 15 13 SEB Danske Cembra Nordax 30 20 10 0 n/a (10) Hoist 29 13 14 Collector Nordea Handels -banken 16 Swed -bank 26 18 14 12 SEB Danske Cembra Nordax Hoist Source of Information = Capital IQ 14<br>
slide15. Trading Comparables Valuation at High Premium Compared to All Peers Banking peers trade at a stable 10-11x P/E and 1.3 - 1.8x P/TBV multiple, apart from Handelsbanken which a slightly higher valuation Consumer finance and credit management peers trade at 11 - 14x 2017E P/E and 2.5 - 3.4x P/TBV multiples Collector, as a high growth stock, is currently trading at more than double its peers on a P/E basis and more than 3 times on a P/TBV basis Price / Earnings 2016 Estimated Earnings, x 35 Nordic Banks Price / Earnings 2017 Estimated Earnings, x Consumer Credit Finance Mgmt 30 Consumer Credit Nordic Banks Finance Mgmt 30.7x 30 25 20 15 10 5 0 13.7x 10.8x 11.3x 11.1x 15.1x 13.5x 13.7x 10.2x 22.7x 20 13.5x 9.9x 10 0 10.9x 10.2x 14.1x 9.5x 11.1x 11.5x Collector Nordea Handels -banken Price / Book Value Multiple 2015 Actual Book Value, x 10 Swed SEB Danske Cembra Nordax -bank Consumer Nordic Banks Finance Hoist Collector Nordea Handels Swed -banken -bank Price / Tangible Book Value 2015 Actual Book Value Less Intangibles , x Credit Mgmt 10 Nordic Banks SEB Danske Cembra Nordax Hoist Consumer Credit Finance Mgmt 8.9x 8.1x 8 6 4 2 0 1.7x 1.5x 1.1x 2.4x 1.3x 1.1x 2.8x 8 6 2.7x 4 2 1.3x 0 1.8x 1.7x 3.4x 3.0x 2.5x 1.4x 1.1x Collector Nordea Handels Swed SEB Danske Cembra Nordax Hoist Collector Nordea Handels Swed SEB Danske Cembra Nordax Hoist -banken -bank -banken -bank Source of Information = Capital IQ 15<br>
slide16. Regression Analysis Evaluating the Right Price to Pay in a High Growth Scenario (Bullish Case) The regression line suggests there could be a strong relationship between return on tangible equity and P / TBV multiple for banks and financial companies company’s position above or below the line could be interpreted as the market’s willingness to pay for its growth potential, discounted for its risk level and noise in statistics; it does not have to mean a company is mispriced However, Collector (current) is trading at a 162% premium above the line assuming a 40% net income CAGR in 2015 - 2017 with no dividends To evaluate the growth factor - If we give the company full credit for its target, i.e. a high net income growth (here we assume 40% NI CAGR for four consecutive years with no dividends), it implies a 3.92x P/TBV multiple and a market cap of $1.57Bn at year-end 2018 based on the current regression This leads to a present value of $1.21 billion at an illustrative cost of equity of only 10.0% (relatively low risk) This represents a 26% discount from today’s price (Bullish Case) Although, the discount could be 48% if we assume just a slightly lower net income CAGR of 30% and slightly higher cost of equity of 10.0% (Moderate Case) Regression Line Based on Peers (Collector does not contribute to the regression) Price / Tangible Book Value (2015A) Bullish Case $ Millions 2015A 2016E 2017E 2018E 2019E 10.0x R2 = 91.6% 8.0x 6.0x Collector (Current) 162% Premium to the regression line Net Income 35 50 69 97 136 Growth 40.0% 40.0% 40.0% 40.0% TBV 184 234 303 400 536 Growth 26.9% 29.7% 32.0% 34.0% RoTE FY+1 26.9% 29.7% 32.0% 34.0% Intercept (0.0) (0.0) (0.0) (0.0) Slope 11.7 11.7 11.7 11.7 Implied P/TBV 3.10x 3.42x 3.70x 3.92x Implied Market Cap 571 800 1,121 1,570 Discount Factor 0.7 1.7 2.7 Cost of Equity 10.0% 10.0% 10.0% Implied Market Cap (PV) 748 954 1,214 Discount to Current Price (54.6%) (42.2%) (26.4%) Implied Multiple at (Bullish Case) 4.0x 3.92x 3.17x Implied Multiple at Case) Dec-2018 Collector (Moderate) Dec-2018 (Moderate Cembra Hoist Moderate Case Collector $ Millions (Bullish) Net Income Growth TBV Growth Nordax RoTE FY+1 Intercept 6 2015A 2016E 2017E 2018E 2019E 35 46 60 78 101 30.0% 30.0% 30.0% 30.0% 184 230 290 368 469 25.0% 26.0% 26.8% 27.5% 25.0% 26.0% 26.8% 27.5% (0.0) (0.0) (0.0) (0.0) 2.0x Handelsbanken SEB Nordea Danske 0.0x 0% 10% Swedbank 27.5% 34.0% (Moderate) (Bullish) 20% 30% 40% 50% Return on Tangible Equity (2017E) Slope 11.7 11.7 Implied P/TBV 2.87x 2.99x Implied Market Cap 529 688 Discount Factor 0.7 Cost of Equity 12.0% Implied Market Cap (PV) 636 Discount to Current Price (61.4%) 11.7 11.7 3.09x 3.17x 895 1,164 1.7 2.7 12.0% 12.0% 739 858 (55.2%) (48.0%) 16<br>
slide17. Section 4 Risks, Catalysts and Conclusion 17<br>
slide18. Risks to the Equity Story Comments Lending volume and credit losses are dependent on economic activity in the country With the need for negative interest rate (a further cut of Repo Rate to negative 50 bps earlier this month) and the all-time-high real estate prices do Macro Regulatory Business Risks Strategic Risks Liquidity Risks inevitably impact the spending power of householders and their ability to both take on more debt and repay on time High household debt levels may increase the risks of shocks to the Swedish financial system What if the Riksbank (Central Bank) will keep the negative interest rate policy stronger and longer? Since Collector is now a licensed bank, it will fall under stronger regulatory scrutiny for its capital levels and operations For example, a cap on interest rates on consumer loans and fees charged would hurt the profitability of Collector See Consumer Financial Protection Bureau and Dodd Frank regulations in the US Regulations / constraints on new stock issuances, dividend policy, limitation on growth possibility in certain desirable segments Competition may erode the volume of loans Collector can underwrite to fulfill its growth target Competition includes new innovative entrants, existing consumer finance lenders like Nordax, and especially the big banks who have steadily held their market shares in both the consumer and corporate lending sectors (see appendix for market share detail) Retaliation / business war - so far, Collector has been under the radar, but with a successful IPO and fast share price appreciation , it has now caught the attention of local big players Ability to keep finding profitable loans given the larger scale Is management capable of steering a larger company, with more complex decisions and might compete head-on with the larger banks? Company talk about being tech, but financials and business still circulate around the traditional lending model Will Collector compromise on loan quality to keep up the high-growth story that has stronger focus on the quarterly results? Given the size of recent stock appreciation, will the Company take more risks to generate high returns? Main source of financing is deposits from the public, of which 84% are payable on demand In total, 97% of the deposits have less than 1 year of maturity (including payable-on-demand) Meanwhile, average consumer loan maturity is 2-4 years and the undrawn credit facility is only $86 Million, less than 10% of the deposit funding ny damage to the Company’s ability to borrow would have significant impacts to Collector’s liquidity situation and its equity story. Examples include worsening reputation, increased competition, further interest rate cutting which reduces the attractiveness of savings accounts, and political events, etc. 18<br>
slide19. Triggers & Catalysts Comments Earnings Release Awareness Large Shareholder Monetizing Real Estate Market Competition Alternative to Deposit Accounts Each earnings release could be a catalyst event Given the recent appreciation, how would investors behave if Collector reports unsatisfactory results that do not fit into the high growth, low risk story? Collector just recently launched its IPO on the Nasdaq Stockholm Exchange in June 2015 There are only 3 research analysts covering this stock There has not been any significant insider trades or big change of shares As the Company releases more earnings reports, and more research can be done on the Company, we should expect To the individual investors, the stock has been a success story with >120% appreciation in 10 months along with a >10 year history of high organic growth. This could send the wrong signals for hopping on the train rather than warning for overheated valuation 44% owned by a Swedish real estate company Fastighets B Balder (market cap $4͘2 Billion, about 2͘5x the size of Collector)͘ It’s profit from the share price movement alone is at least $500 million Muirfield Invest AB, the 8th largest shareholder with currently 2.7% stake, has reduced its holdings by ~10% over the last week The share has appreciated by 124% in just 10 months. This would cause two forces: i) convincing shareholders to liquidate and monetize on the gain immediately, and ii) investors are aware of the valuation and its dependency on the high growth equity story, but decide to ride the momentum and only liquidate when the trend reverses or if Collector reports one quarter of poor growth About 22% of the stocks are free float Any dip in real estate prices would risk starting a devaluation and de-leveraging trend that would severely hurt the loan volume, withdrawal and credit losses of Collector Whilst Collector is positioning itself as a technology company with a bank license, there are new innovative entrants including crowdfunding, P2P and international players that might enter Collector is positioning itself as a technology company with a bank license, but there are new innovative entrants including crowdfunding, P2P and international players that might enter the local market 0.70% interest rate for deposit account is not much; and negative interest rate policy is a concern As a long shot, recent surge in precious metals and the proposed cash-less society in Sweden might attract savers to extract funds from depository accounts and store them in physical currencies instead 19<br>
slide20. Conclusion - Valuation is high on a relative basis even if we adopt a bullish scenario with high net income growth and loan book growth for 4 consecutive years Valuation Business Projections Target Price Actionability Areas for Development - The Bullish Case in the regression analysis suggests a 26% discount to current share price; however, if the projections just get altered by a little bit (30% NI CAGR instead of 40%), it would have significant impact to the suggested share price (our Moderate Case suggests a 48% discount) - The business model is very profitable and the Company seems to have prepared itself for continuing its high growth stage (by hiring programmers and investing heavily in IT systems) - However, with a larger size and a bank license, comes stronger scrutiny and stronger competition - Any change to the projections have significant impact to the valuation - Triangulating between various scenarios, it seems a small premium to the IPO listing price is the right spot for the Company - The vast appreciation since Q3 earnings release is overdone; especially while the broader index and banking sector were declining - Target range set to: - Market cap of $750 - $1,000 Million - Share price of $8.03 - $10.71 - Representing a 39% - 55% discount from today’s price - This is a weak point of the pitch, as there are no options/ financial products to short the Company - As a private investor, I would need a broker to lend me the shares. However, Collector is just recently listed and its size is still small for those possibilities - A potential way to monetize is to convince some of the larger shareholders to lend you the shares against a fee, or short an index that Collector or its owner Balder are included. However, the smallest index I could find has maximum 4% exposure to the two shares - Would like to pinpoint the specific issues facing this sector and more established players to see where Collector is heading and assess any weakness in the equity story - A detailed operating model with regulatory capital adjustments would give more confidence behind the conclusion. However in this case, I adopted a more outside-in approach because the valuation is quite out of proportion. I simplified a few assumptions to deliver key points in an efficient manner. Naturally, it would be ideal to be knowledgeable about the specific issues and model out all scenarios properly 20<br>
slide21. Appendix 1 Loan Book and Capitalization Details 21<br>
slide22. Loan Overview Healthy balance sheet with low NPL consumer loans and corporate credits (based on 2014 data) Majority of Collector’s funding are made of payable-on-demand deposits (84%). 52% of its loans have maturity longer than 1 year; Buffer from undrawn credit facilities but may still pose risks Loan & Receivables Overview (2014) Within Non-Performing Loans Provision for Gross Amount % of Total Agreed Time (>60 Days Overdue) % NPL Bad Debt Retail Finance 76 10% 65 11 14% (0) Consumer Loans 253 34% 252 1 0% (1) Credit Card 31 4% 30 0 2% (2) Retail Total 360 49% 348 12 3% (3) Factoring 91 12% 74 17 19% (5) Corporate Credit 26 3% 26 - 0% (0) Mortgage Credit 97 13% 97 1 1% - Acquired Debt Collection Portfolio 26 3% - 26 100% - Other 140 19% 1 139 99% (34) Corporate Total 380 51% 198 182 48% (39) Group Total 740 200% 546 194 26% (42) yoy Growth 39% 31% 66% 20% Lending and Other Receivables Funding Overview 2014 2015 2014 2015 Loans and Receivables 740 1,124 Provision for Bad Debts (42) (49) Net Loans and Receivables 698 1,075 Other Receivables 1 1 Prepaid Expenses and Accrued Income 15 20 Net Loans Incl. Other 714 1,096 Split by Maturity Long Term Component (>1 Year) 378 572 % of Total 53% 52% Payable on Demand 509 812 Due Date <3 months 18 56 Due Date 3 months - 1 year 56 71 Due Date 1 - 5 years 60 30 Due Date > 5 years - - Total Deposit Funding 644 971 % On Demand 79% 84% % <1 Year Maturity 91% 97% % >1 Year Maturity 9% 3% Short Term Component (<1 Year) 336 524 % of Total 47% 48% Undrawn Credit Facility 49 86 Source of Information = Annual Report, IPO Prospectus 22<br>
slide23. Capitalization Core Capital Ratio and Funding Maturity Credit Risk Exposure (2015) Risk Risk Weighted Min. Min. Exposure Weighting Amount Requirement Requirement Municipalities and Other Associations 20 0% - 8.0% - Institutional Exposures 103 20% 21 8.0% 2 Corporate Exposures 313 100% 313 8.0% 25 Household Exposures 585 75% 438 8.0% 35 Unregulated Items 120 100% 120 8.0% 10 Other Items 59 100% 59 8.0% 5 Total 1,200 951 76 Capital Requirement 2014 2015 Credit Risk 49 76 Market Risk & CVA Risk 0 1 Operational Risk 11 13 Total Capital Requirement 60 90 Capital Base Equity 123 204 Deduction Intangible Assets (11) (13) Tier 1 Capital 112 190 Tier 2 Capital - - Capital Base 112 190 Capital Surplus 52 100 = Capital Base - Capital Requirement Capital Adequacy Ratio 1.86x 2.12x = Capital Base / Capital Requirement Capital Ratio (CET1) 14.9% 16.9% = Core Tier 1 Capital / Risk Weighted Assets Risk Weighted Assets 752 1,124 Source of Information = Annual Report 23<br>
slide24. Appendix 2 Supporting Materials 24<br>
slide25. Private Loans Business Overview The Average Customer Sw eden Norw ay Finland Average Annual Income 308 000 SEK 415 000 NOK 39 000 EUR Average Age 44 42 47 Overview for Conditions of Private Loans Sw eden Norw ay Finland Sum Maturity 20 000-250 000 SEK 20 000-100 000 NOK 2 000-10 000 EUR Average: 60 000 SEK Average: 45 000 NOK Average: 4 500 EUR 2-15 years Average length 7.7 years. Actual maturity differs, but is normally 2 - 4 years Average Annual Rate 5.9% -15.9% 14.5%-19.5% 9.9%-19.9% Initiation Fee 495 SEK 750 NOK 60 EUR Invoice Fee 0-35 SEK 60 NOK 3 EUR Payment Protection Conversion ~60% ~5% Not Available Source of Information = IPO Prospectus 25<br>
slide26. Factoring & Corporate Credit Procedure Business Overview Factoring and Company Credit Procedure Step 1 Step 2 Risk Assessment of Client Step 3 Risk Assessment of End Customer % fee based on nominal sum Step 4 Application for purchase of invoices and debt claims from client Risk assessment for decision to do business with client ≥ rating < A rating Fee for invoice and admin Assets acquired from client Assets administered on behalf for client Credit Risk No Credit Risk Step 5 Potential credit to customer in combination with factoring services, e.g. bridge financing, project financing Potential Credit Approval Potential standalone credit payout Source of Information = IPO Prospectus 26<br>
slide27. Real Estate Credit Business Overview Credit Procedure for Real Estate loans Strategy Relationship-based and tailored lending to selected clients Focus on SME 1 Loan Prospects • Loan prospects are generated via close personal connections or indirect relationships • Clients need to show merits / track records 2 Analysis • 1 - 3 weeks of processing depending on size of the credit • Evaluation • Decision 3 Credit Decision • ≤ 15 MSEK: Credit Committee • ≤ 25 MSEK: Credit Advisory Committee • > 25 MSEK: Board 4 Follow-Up • Documentation • Payout • Monitoring Source of Information = IPO Prospectus 27<br>
slide28. Debt Collection Business Overview Outstanding nominal debt collection sum 2012 - 2014 (MSEK) Claim is overdue Step 1 Collector takes responsibility for the recovery of the claim ~1 300 ~1 400 ~1 500 Step 2 Claim under supervision if not recovered Real Estate sector Other sectors Fee Recovery Collector purchases the claim charge and late 2012 2013 Number of debt collection cases and average value 2012 - 2014 2014 Step 3 from customer financing charge Claim purchase transferred to Collector continues with the entity “Past Due cquired recovery of claim on behalf of Total Cases ~60 400 ~61 500 ~51 300 2012 2013 2014 ~25 600 ~24 800 Customer split per segment 20141) ~30% ~60% Loans” customer Customer concentration 20141) 10% 4% 4% 3% 3% Average value per debt collection case (SEK) 2012 ~23 300 Real Estate Other 2013 2014 ~10% 76% Transportation Customer 1 Customer 2 Customer 3 Customer 4 Customer 5 Other Customers Source of Information = IPO Prospectus 28<br>
slide29. Acquisition of NPL Business Overview Percentage of credit portfolio for Corporate segment at end of 2014 11% 208 MSEK Procedure for purchase of portfolios of past due debt Credit portfolio for purchase of past due debt at end of 2012-2014 (MSEK) 208 148 86 2012 2013 2014 Implementation and Pipeline Evaluation • Portfolios of past due claims • Evaluation of future cash are primarily purchased flow (5-10 years) based on from banks and in some 10-20% required return cases from other sectors basis • Real estate credits from • Take into account historical debt collection (if acquired) cash flow, type of claims and volume Indicative Bid Due diligence Final Bid • Based on qualitative and • Performed by specialists • Final bid level adjusted quantitative analysis and based on interviews, from indicative level based documentations, etc on due diligence and other • Indicative bid new information corresponding to return • Examination of seller’s requirement at evaluation credit procedure and legal phase documents • Balancing credit portfolio against seller’s debt collection system Monitoring • With a winning bid, portfolio is transferred to Collector • Collector starts debt collection process and surveillance of claims Source of Information = IPO Prospectus 29<br>
slide30. Banks Market Shares in Sweden 6 Big Banks Have Consistently Held ~85% of the Private Lending Market in Sweden; While Smaller Players Compete for the Remaining ~15% Private Market Deposits % 120 80 40 0 2010 2011 2012 Corporate Market Lending % 120 100% 22% 80 12% 12% 15% 40 18% 21% 0 2013 2014 2010 2011 2012 2013 Mortgage Lending % 120 100% 16% 6% 80 4% 14% 14% 40 22% 24% 0 2014 2010 100% 13% 7% 16% 15% 23% 25% 2011 2012 2013 2014 Deposits Lending % % 120 120 100% 100% 7% 8% 22% 80 6% 80 6% 21% 4% 14% 17% 13% 40 40 22% 22% 19% 19% 0 0 2010 2011 2012 2013 2014 2010 2011 2012 2013 2014 Swedbank Handelsbanken Nordea SEB Sparbankerna SBAB Danske Bank Other Source of Information = Swedbank Website 30<br>
slide31. Historical Developments Transition of Collector 1999 2004 2008 2013 2015 Collector is Collector starts offering Expansion in Norway Introduces real estate Receives bank license during founded by personal loans, debt and Finland credits the year Lena Apler and collection services via Johan Moller acquisition of NPL IPO on Nasdaq Stockholm portfolios Changed name to Collector Bank 1999 2001 2004 2005 2008 2010 2013 2014 2015 2001 2005 2010 2014 Collector operates as a credit Offers private Introduces credit Launches the Company’s market company under the savings accounts card services first mobile app Betalkoll, surveillance of the Swedish for payment overview Financial Supervisory Authority Source of Information = Company Website 31<br>
slide32. Major Shareholders As of December 31, 2015 Source of Information = Annual report 32<br>