
December 10-11, 2019| Markets committee Hanhan

Description: December 10-11, 2019 Markets committee Hanhan Hammer, Chris Geissler 413.535.4049 hhammeriso-ne.com; 413.535.4367 CGEIssleriso-ne.com Day-Ahead Reserves - Alternative Settlement Design and its Fuel Security Implications ENERGY
Related Topics
Download Presentation
"December 10-11, 2019| Markets committee Hanhan" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. December 10-11, 2019| Markets committee Hanhan Hammer, Chris Geissler 413.535.4049 | hhammer@iso-ne.com; 413.535.4367 | CGEIssler@iso-ne.com Day-Ahead Reserves - Alternative Settlement Design and its Fuel Security Implications ENERGY SECURITY IMPROVEMENTS:
MARKET-BASED APPROACHES<br>
slide2. 2 Winter Energy Security Improvements WMPP ID:
125 Proposed Effective Date: June 1, 2024 In accordance with FERC’s July 2, 2018 order in EL18-182-000, the ISO must develop and file improvements to its market design to better address regional fuel security, and file by April 15, 2020
Key Projects – Energy-Security Improvements
Discussion Paper 2019-04-09 and 2019-04-10 MC A00 ISO Discussion Paper on Energy Security Improvements – Version 1<br>
slide3. 3 Prior Energy-Security Improvement Presentations November ESI presentation
September ESI presentation
August ESI presentation
July 30 ESI presentation
July 8-10 ESI presentation
June ESI presentation
May ESI presentation
April ESI presentation<br>
slide4. 4 Presentation Outline Section 1: Introduction
Section 2: Design Comparison
Section 3: Design Incentives - Examples
Section 4: Comparative Cost Implications<br>
slide5. Section 1: Introduction 5<br>
slide6. 6 Today’s Focus Address a stakeholder question:
Why does the ISO propose to settle DA reserve awards as options on RT energy, rather than as a forward sale of RT reserves?
We’ll compare the two designs, and explain the reasons for the ISO’s proposed approach. We will use the terms:
‘DA energy options’ to describe the ISO’s proposed design
‘DA forward reserves’ to describe the alternative design, where deviations from DA reserve awards settle at the RT reserve price<br>
slide7. 7 Today’s Takeaways Unlike DA energy, the reserve market designs of the nine ISOs/RTOs are not standardized (presently)
For the two designs compared today, neither is more complex for the ISO to implement
The ISO’s proposed design (DA energy options) provides stronger incentives to arrange fuel, and better addresses the region’s fuel security concerns
The alternative design (DA forward reserves) provides weaker incentives to arrange fuel, and does not fully address the region’s fuel security concerns
Note: ‘Arranging fuel’ refers to the ability to produce energy when needed, not about ‘fuel’ as a stockpile<br>
slide8. Section 2: DA Energy Options versus DA forward reserves Design Comparison Basics 8<br>
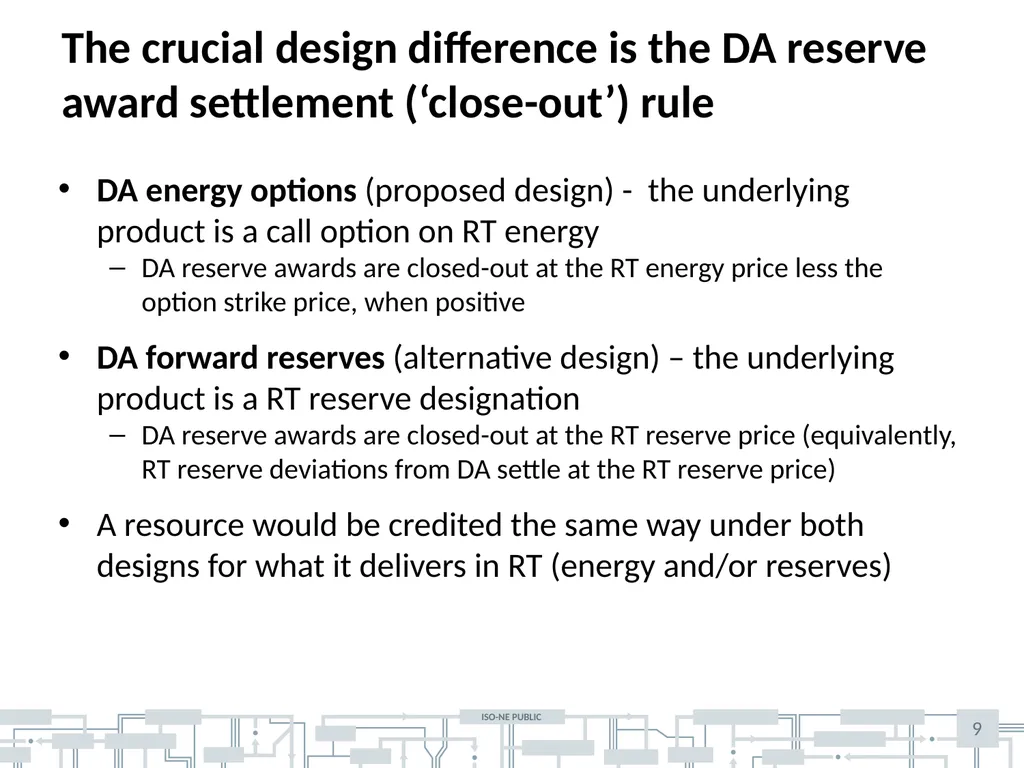
slide9. 9 The crucial design difference is the DA reserve award settlement (‘close-out’) rule DA energy options (proposed design) - the underlying product is a call option on RT energy
DA reserve awards are closed-out at the RT energy price less the option strike price, when positive
DA forward reserves (alternative design) – the underlying product is a RT reserve designation
DA reserve awards are closed-out at the RT reserve price (equivalently, RT reserve deviations from DA settle at the RT reserve price)
A resource would be credited the same way under both designs for what it delivers in RT (energy and/or reserves)<br>
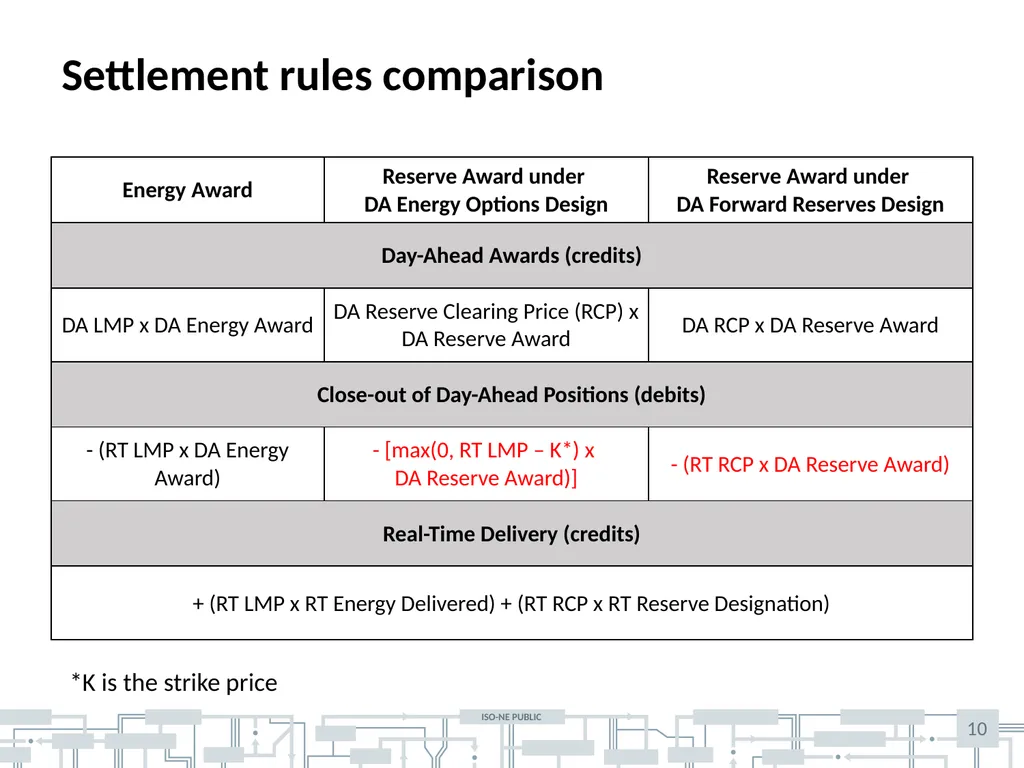
slide10. 10 Settlement rules comparison *K is the strike price<br>
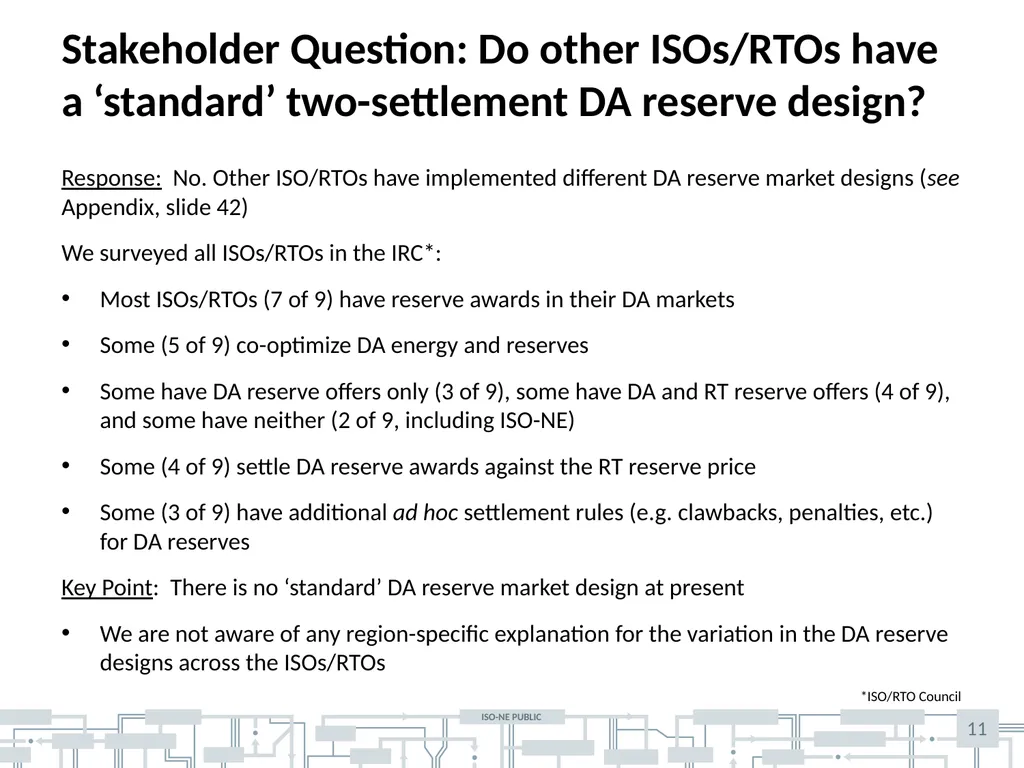
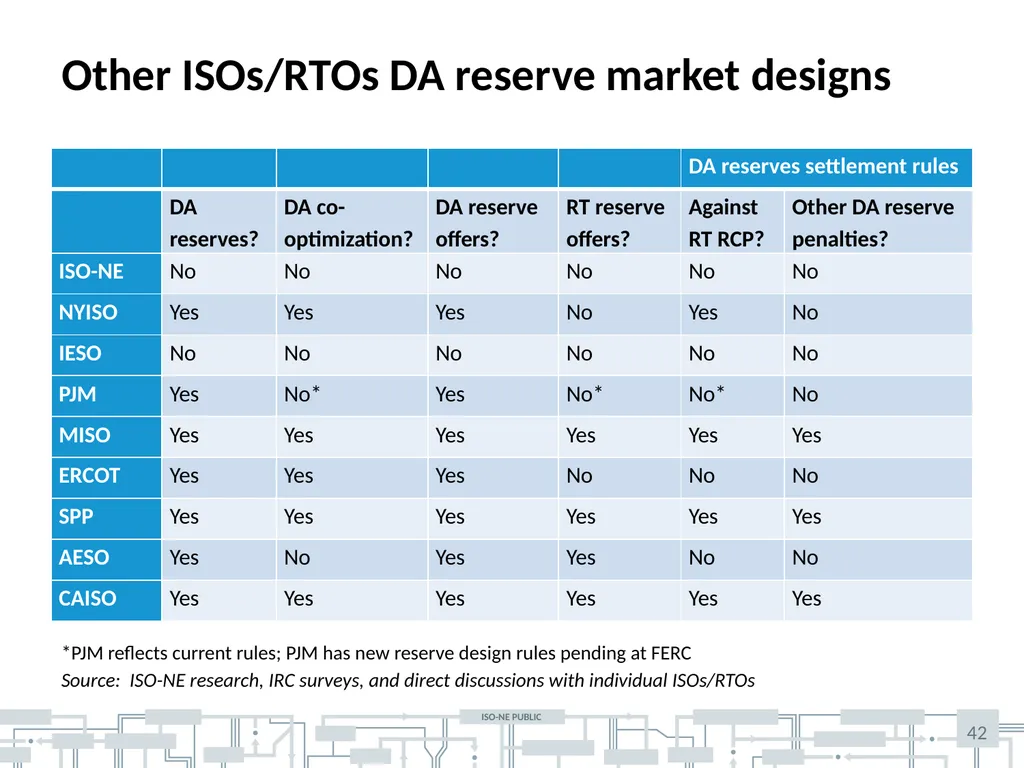
slide11. 11 Stakeholder Question: Do other ISOs/RTOs have a ‘standard’ two-settlement DA reserve design? Response: No. Other ISO/RTOs have implemented different DA reserve market designs (see Appendix, slide 42)
We surveyed all ISOs/RTOs in the IRC*:
Most ISOs/RTOs (7 of 9) have reserve awards in their DA markets
Some (5 of 9) co-optimize DA energy and reserves
Some have DA reserve offers only (3 of 9), some have DA and RT reserve offers (4 of 9), and some have neither (2 of 9, including ISO-NE)
Some (4 of 9) settle DA reserve awards against the RT reserve price
Some (3 of 9) have additional ad hoc settlement rules (e.g. clawbacks, penalties, etc.) for DA reserves
Key Point: There is no ‘standard’ DA reserve market design at present
We are not aware of any region-specific explanation for the variation in the DA reserve designs across the ISOs/RTOs *ISO/RTO Council<br>
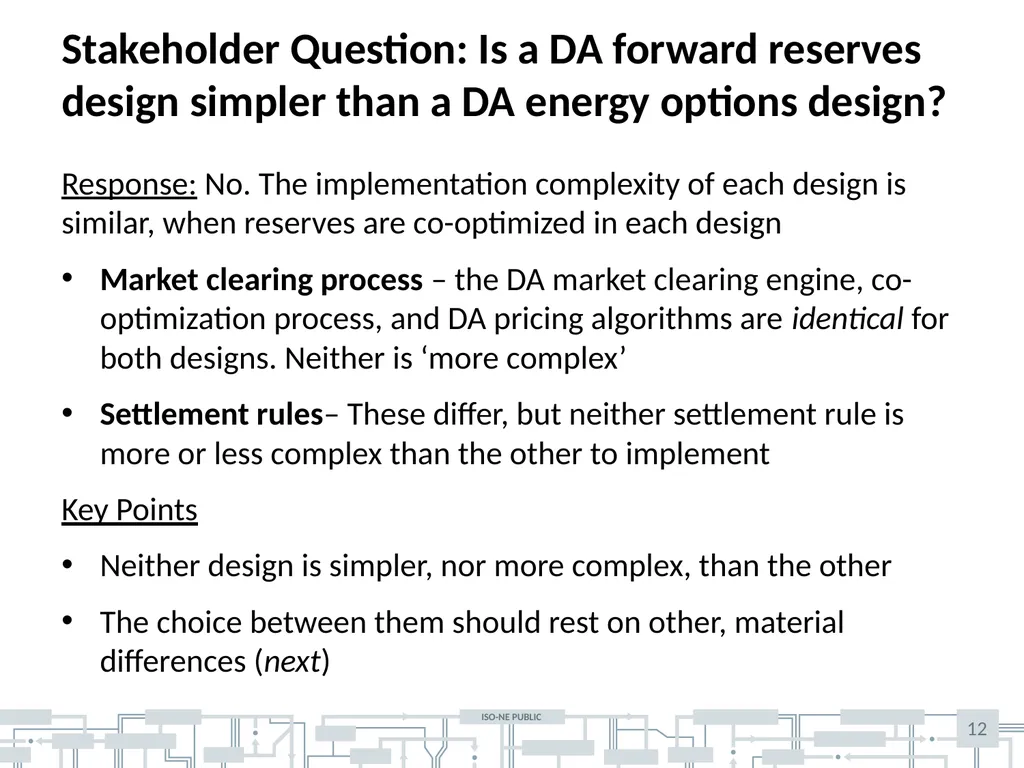
slide12. 12 Stakeholder Question: Is a DA forward reserves design simpler than a DA energy options design? Response: No. The implementation complexity of each design is similar, when reserves are co-optimized in each design
Market clearing process – the DA market clearing engine, co-optimization process, and DA pricing algorithms are identical for both designs. Neither is ‘more complex’
Settlement rules– These differ, but neither settlement rule is more or less complex than the other to implement
Key Points
Neither design is simpler, nor more complex, than the other
The choice between them should rest on other, material differences (next)<br>
slide13. Section 3: Design incentives - Examples An extension of example 2 in the Discussion Paper 13<br>
slide14. 14 Stakeholder Question: Why is the ISO proposing the DA energy options design? Response: The proposed design provides stronger incentives for resources to arrange fuel, as compared to the DA forward reserves design
In this section, we will explain why using a series of numerical examples
Key Point
The DA energy options design better achieves the FERC’s directive to develop market-based solutions to “better address the region’s fuel security concerns”<br>
slide15. 15 A road map of examples ahead Example 2 in the April ESI Discussion Paper is a 4-generator model where:
Status quo (current energy-only DA market) does not provide an incentive for a generator (‘Gen 3’) to arrange fuel, though that would be efficient
DA energy options do provide efficient incentives for Gen 3 to arrange fuel
Today we will extend that example to examine whether the alternative design (DA forward reserves) provides incentives for Gen 3 to arrange fuel
We will calculate and compare Gen 3’s expected net revenue with and without fuel under the alternative design
We will see:
Gen 3’s expected net revenue is lower with fuel than without fuel
As a result, Gen 3 has no incentive to arrange fuel under the alternative design. Yet, it does under the DA energy options design<br>
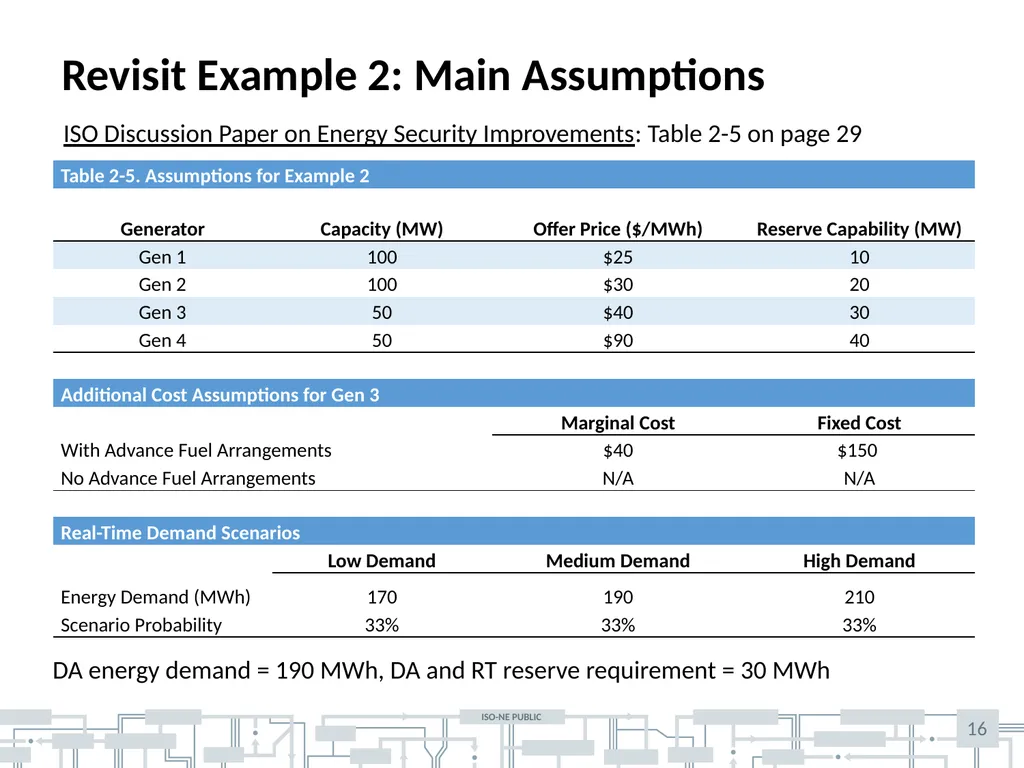
slide16. 16 Revisit Example 2: Main Assumptions DA energy demand = 190 MWh, DA and RT reserve requirement = 30 MWh ISO Discussion Paper on Energy Security Improvements: Table 2-5 on page 29<br>
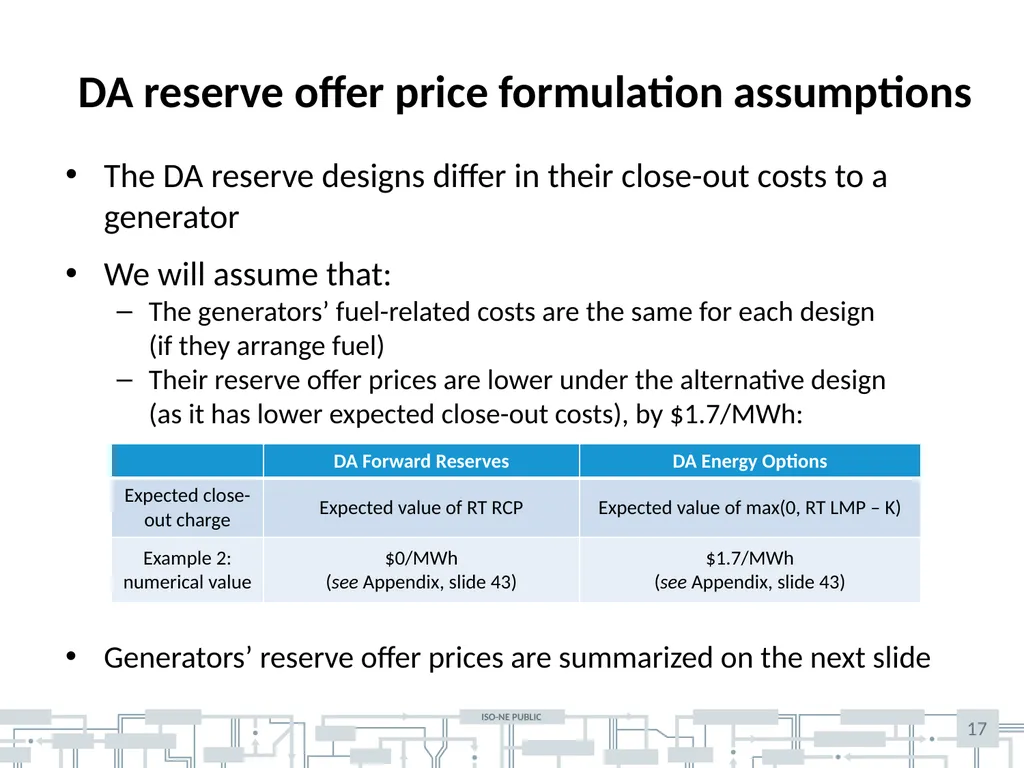
slide17. 17 The DA reserve designs differ in their close-out costs to a generator
We will assume that:
The generators’ fuel-related costs are the same for each design (if they arrange fuel)
Their reserve offer prices are lower under the alternative design (as it has lower expected close-out costs), by $1.7/MWh: DA reserve offer price formulation assumptions Generators’ reserve offer prices are summarized on the next slide<br>
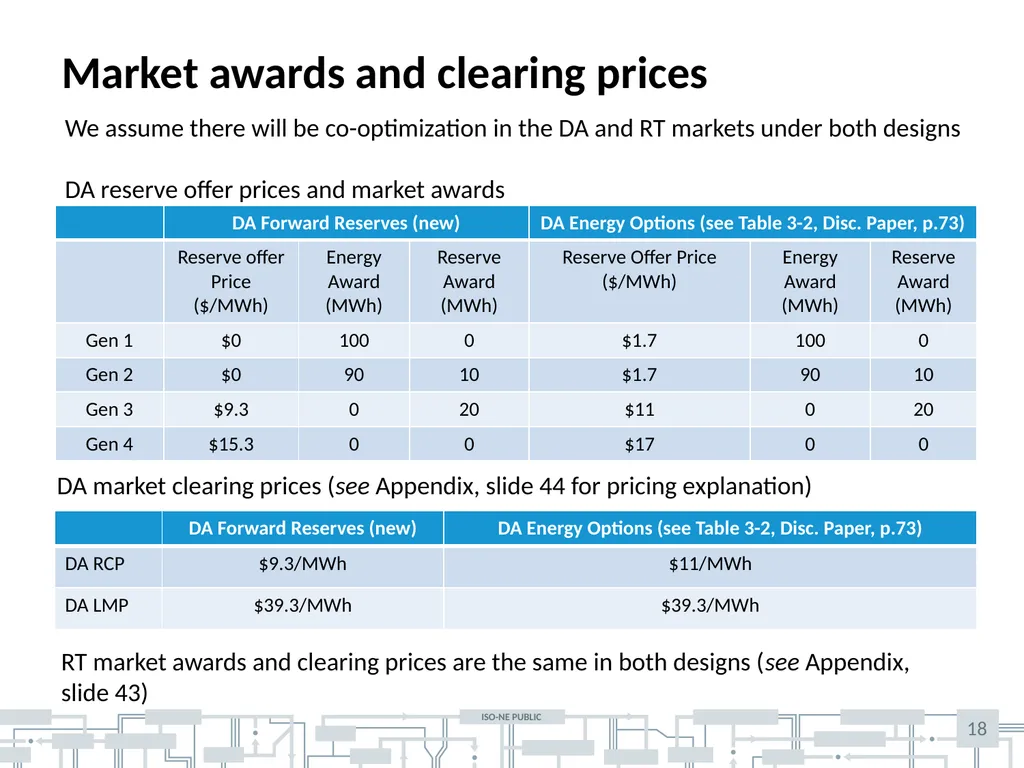
slide18. 18 Market awards and clearing prices We assume there will be co-optimization in the DA and RT markets under both designs
DA reserve offer prices and market awards DA market clearing prices (see Appendix, slide 44 for pricing explanation) RT market awards and clearing prices are the same in both designs (see Appendix, slide 43)<br>
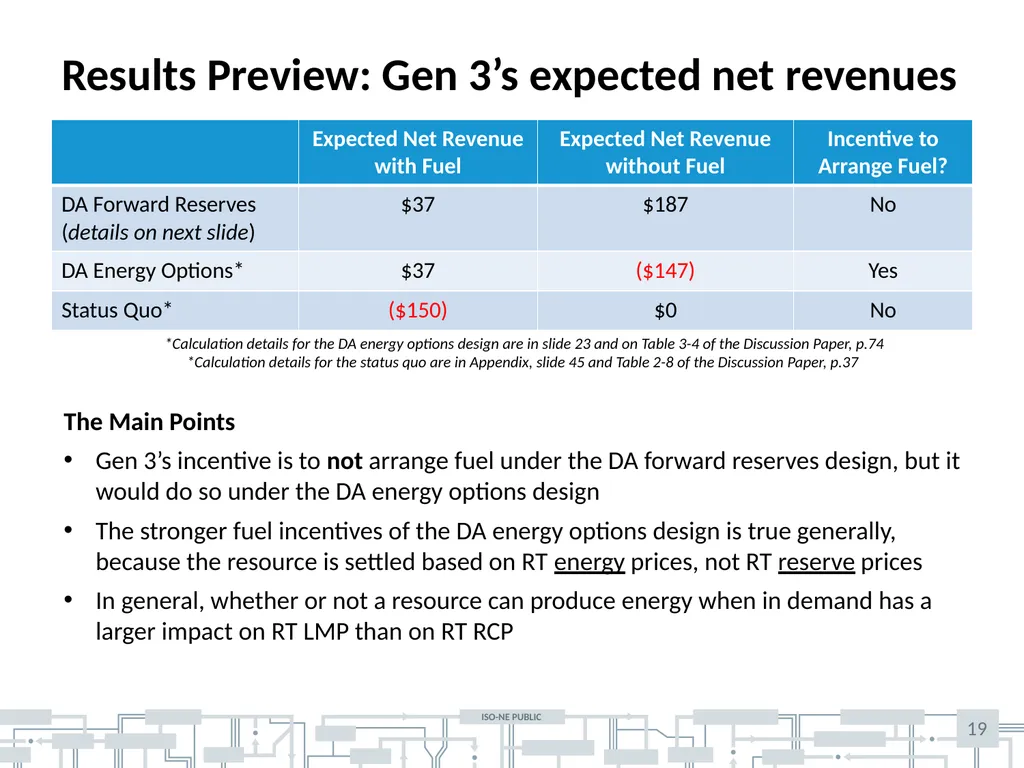
slide19. 19 Results Preview: Gen 3’s expected net revenues The Main Points
Gen 3’s incentive is to not arrange fuel under the DA forward reserves design, but it would do so under the DA energy options design
The stronger fuel incentives of the DA energy options design is true generally, because the resource is settled based on RT energy prices, not RT reserve prices
In general, whether or not a resource can produce energy when in demand has a larger impact on RT LMP than on RT RCP *Calculation details for the DA energy options design are in slide 23 and on Table 3-4 of the Discussion Paper, p.74
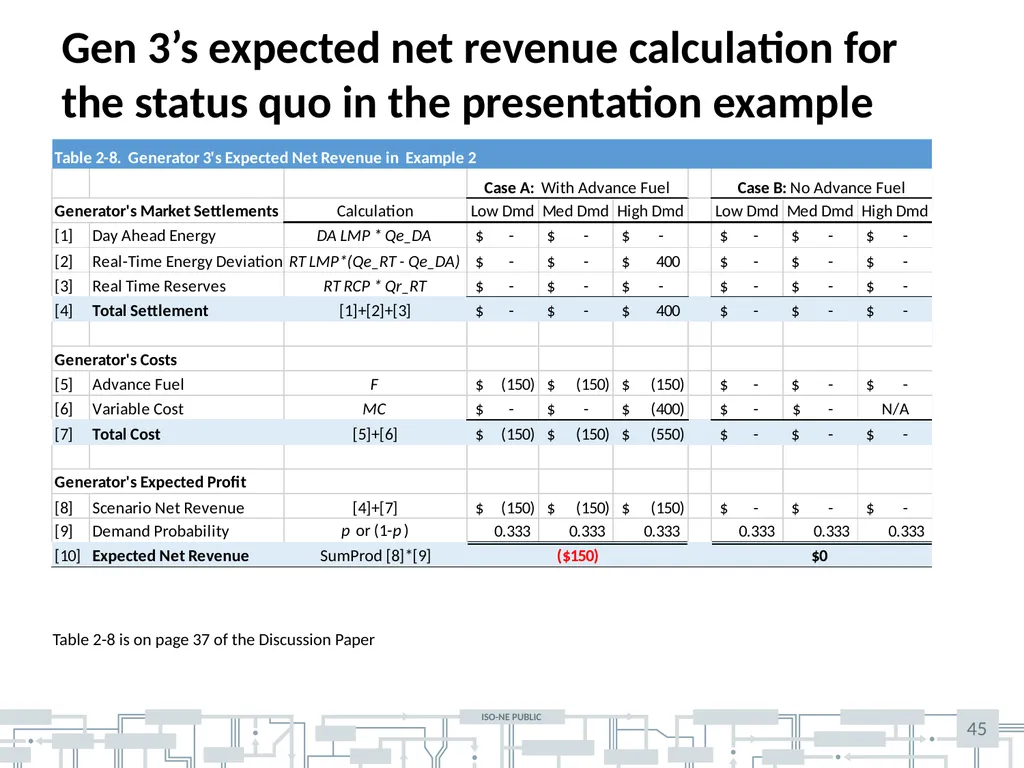
*Calculation details for the status quo are in Appendix, slide 45 and Table 2-8 of the Discussion Paper, p.37<br>
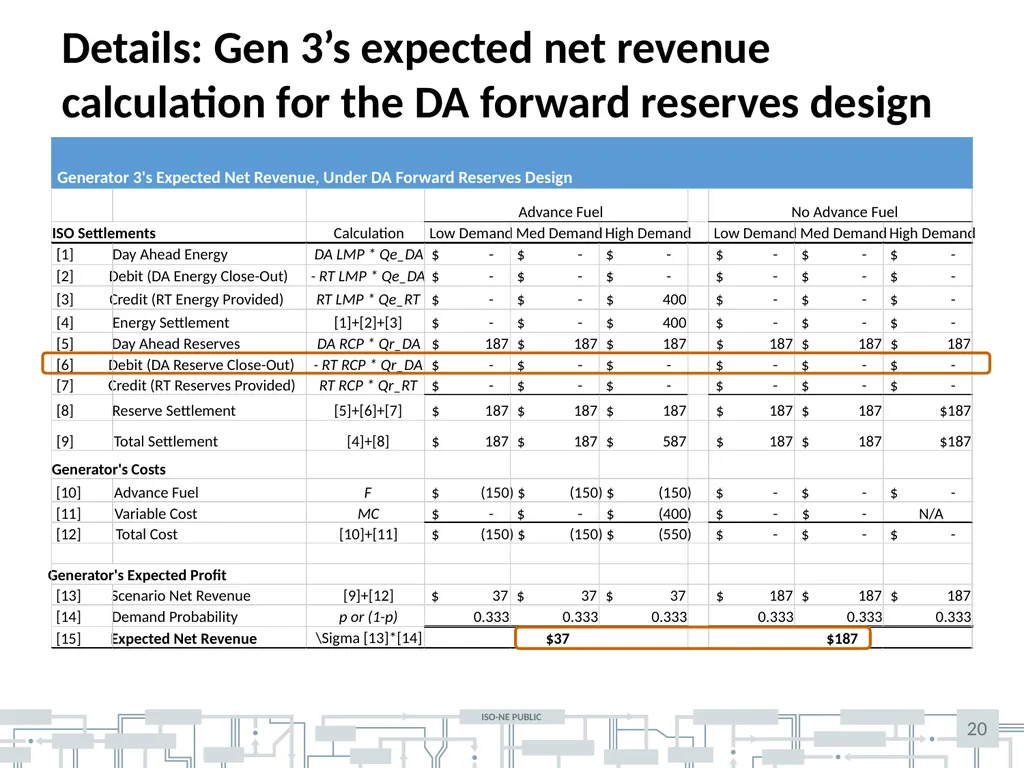
slide20. 20 Details: Gen 3’s expected net revenue calculation for the DA forward reserves design<br>
slide21. 21 Key Points - DA forward reserves design Observation
Row [6] shows the DA reserve close-out charge is $0 in all scenarios. This is because RT RCP is $0/MWh in all scenarios, even when Gen 3 has no fuel
Whether or not Gen 3 has fuel doesn't impact the RT RCP, but it does impact the RT LMP (increases from $40/MWh when Gen 3 has fuel to $90/MWh when Gen 3 has no fuel)
Key Points
Gen 3 faces no financial consequence if it cannot produce energy when in demand because the close-out charge is not based on energy prices
As a result, the DA forward reserves design doesn’t change Gen 3’s financial calculus with respect to its fuel arrangements
Other ISOs/RTOs have adopted various non-market reserve penalty mechanisms in an attempt to address reserve non-performance issues (see Appendix, slide 42)
Such non-market penalties are ad hoc “crutches”, rather than a true fix for the underlying (misaligned incentives) design issue<br>
slide22. 22 The DA forward reserves design does not fix the misaligned incentives problem [In the current market], “resources facing production uncertainty may have inefficiently low incentives to invest in additional energy supply arrangements, even though such arrangements would be cost effective from society’s standpoint as a means to reduce reliability risk”
April Discussion Paper, p. 10
In this example, it is socially efficient for Gen 3 to arrange fuel
Gen 3 having fuel reduces RT total production cost by $167, more than enough to cover its $150 up-front fuel arrangement cost (see page 36 of the Discussion Paper)
With the DA forward reserves design, Gen 3’s financial best interest is to not arrange fuel
Its financial consequences, if it cannot produce energy, are too low (zero)
The DA forward reserve design fails to align society’s preferred decision with Gen 3’s private fuel arrangement decision
This is true in general: the DA forward reserve design does not resolve the misaligned incentives problem<br>
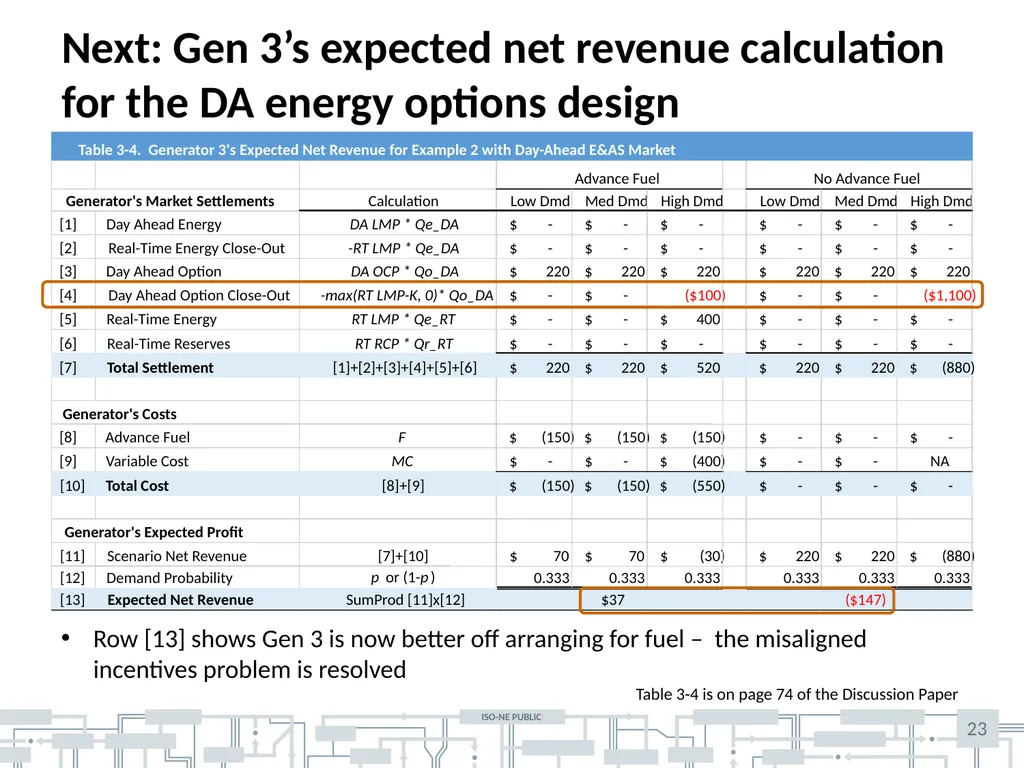
slide23. 23 Next: Gen 3’s expected net revenue calculation for the DA energy options design Row [13] shows Gen 3 is now better off arranging for fuel – the misaligned incentives problem is resolved
Table 3-4 is on page 74 of the Discussion Paper<br>
slide24. 24 Key Points - DA energy options design Observation
Row [4] shows Gen 3 incurs a steep $1,100 close-out charge when it has no advance fuel and load turns out to be high
Close-out charge = (RT LMP of $90/MWh – K of $35/MWh) x Option Award of 20 MWh
Key Points
Gen 3 faces high financial consequence if it cannot produce energy when needed because the close-out charge is based on the cost of energy (RT LMP of $90/MWh)
As a result, the DA energy options design changes a resource’s financial calculus with respect to whether or not to arrange fuel:
The fuel incentive is stronger than the DA forward reserves design; and
The fuel incentive is stronger than the status quo<br>
slide25. 25 Design comparison takeaways To provide efficient incentives to arrange fuel, there should be a financial consequence tied to whether or not a resource can produce energy in real-time
That financial consequence should resolve the misaligned incentives problem, i.e., align society’s interest with the generator’s private financial interest to arrange fuel
The DA forward reserves design doesn’t tie financial consequence to the price of energy in real-time
Close-out charge is $0 (based on $0/MWh RT RCP), in this example
This design does not resolve the misaligned incentives problem
The DA energy options design does tie financial consequence to the price of energy in real-time
If a resource cannot produce energy when needed, the close-out charge is high at $1,100 in total (based on $90/MWh RT LMP), in this example
This design resolves the misaligned incentives problem<br>
slide26. 26 Summary Unlike DA energy, the reserve market designs of the nine ISOs/RTOs are not standardized (presently)
For the two designs compared today, neither is more complex for the ISO to implement
The ISO’s proposed design (DA energy options) provides stronger incentives to arrange fuel, and better addresses the region’s fuel security concerns
The alternative design (DA forward reserves) provides weaker incentives to arrange fuel, and does not fully address the region’s fuel security concerns<br>
slide27. Comparative Cost Implications 27 Section 4: DA Energy Options versus DA forward reserves<br>
slide28. 28 Stakeholder Question: How would total consumer costs (and producer revenues) change if the ISO uses a DA forward reserves design? Procurement of DA reserves under a DA forward reserves design would be in place of ISO’s proposal to buy DA reserves under a DA energy options design
DA forward reserves would settle against the RT reserve price using the standard two-settlement structure
Address this question using experience in two other RTOs that have DA forward reserves – NYISO and MISO
Use data on DA and RT reserve prices from these regions to assess potential market impacts if we observed similar pricing relationship in New England<br>
slide29. 29 Today’s discussion does not assess the costs of other changes to ancillary service markets Evaluation does not consider if/how a DA forward reserves design could accommodate EIR or RER, for which there is currently no RT counterpart
Discussion excludes consideration of the FRM, which does not follow the standard two-settlement structure and includes a number of administrative rules
Will evaluate impacts of buying a different set of DA energy options than proposed (e.g., no RER products) at future MC meetings as part of the Impact Analysis<br>
slide30. 30 Evaluate cost implications of a DA forward reserves design using data from other RTOs Both NYISO and MISO procure DA reserves and provide compensation for this service
They do not procure products that are comparable to EIR or RER
Their design details differ, with varying cost implications
Use annual price data from both RTOs to assess the impact of procuring DA reserves using a DA forward reserves design on consumer costs in New England
Caveat: There are many differences between the market rules and structure in these RTOs and in New England beyond their procurement of DA reserves
Estimated cost impacts from these RTOs cannot be applied to New England in an apples-to-apples manner
Next: Discuss potential impacts on reserve costs in each RTO before considering possible effects on energy costs<br>
slide31. 31 NYISO has experienced higher reserve prices in DA than in RT NYISO’s design allows participants to submit priced offers for reserves in the DA market, but does not allow priced RT offers
In 2017 and 2018, average DA reserve prices were higher than in RT, where the difference varied by year, location, product:
For example, average prices for 30 minute reserves in West New York in 2018 were $4.16/MWh in DA, and $0.41 in RT
Difference between DA and RT prices may occur because of:
Risk premium in DA offers
Exclusion of virtuals from DA reserve market
Other potential design features
Source: 2018 State of the Market Report (Appendix), Figures A16-A19<br>
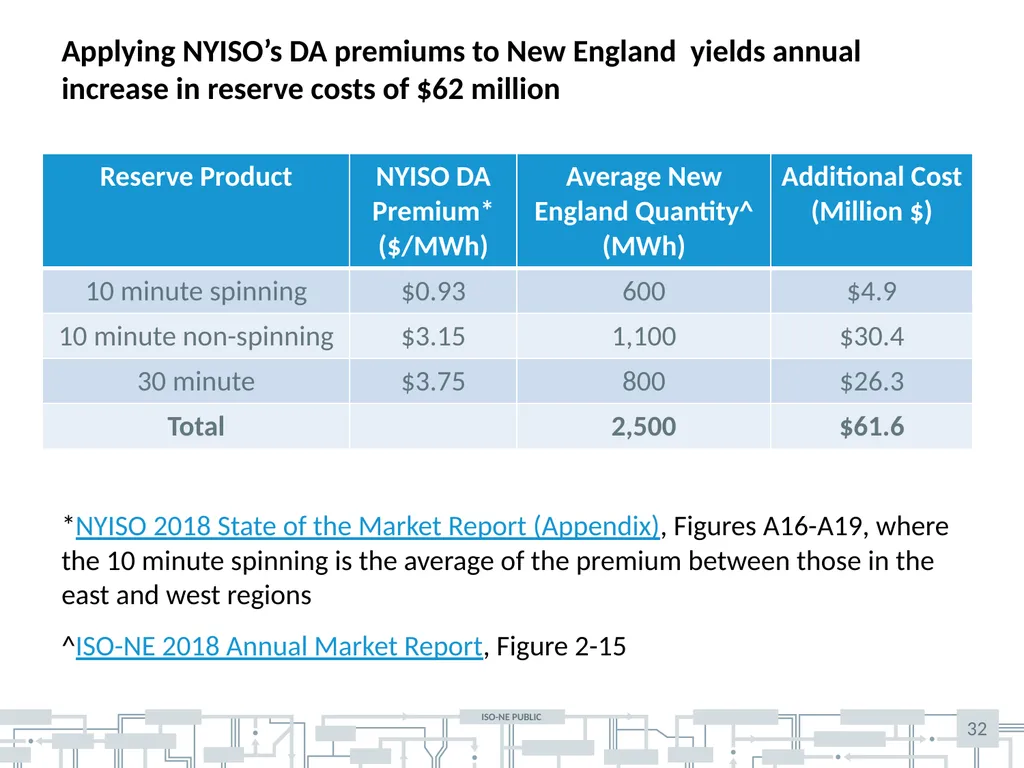
slide32. 32 Applying NYISO’s DA premiums to New England yields annual increase in reserve costs of $62 million *NYISO 2018 State of the Market Report (Appendix), Figures A16-A19, where the 10 minute spinning is the average of the premium between those in the east and west regions
^ISO-NE 2018 Annual Market Report, Figure 2-15<br>
slide33. 33 MISO’s experience does not yield clear estimates if reserve costs would change MISO’s design allows participants to submit priced offers for reserves in both the DA and RT markets
Total reserve costs could go up under such a design, if allowance of RT reserve offer prices increases the average RT reserve clearing price
Assessing this impact would require detailed data on reserve price components
In 2017 and 2018, average reserve prices were roughly $3 for spinning reserves, $1 for supplemental reserves
Average DA and RT reserve prices were close (within $0.50)
Suggests that there would not be a reserve cost increase associated with a DA premium
Source: 2018 State of the Markets Report (Analytical Appendix), Figure A27<br>
slide34. 34 NYISO approach appears unlikely to materially impact energy costs NYISO approach does not allow reserve offer prices in RT
New England’s current market rules also do not allow such offer prices
Applying the NYISO approach to New England would therefore not change the RT optimization and pricing from current market rules
Would therefore expect similar RT energy (and reserve) prices
DA energy prices are unlikely to be higher than RT prices because INCs and DECs will generally converge the DA energy price to its expected RT value
With no expected changes to DA or RT energy prices, would not expect material change in energy market costs<br>
slide35. 35 MISO design may lead to higher energy prices By allowing resources to offer priced reserves in RT, New England’s adoption of the MISO design could increase RT energy prices relative to current market rules
RT co-optimization and energy pricing must account for opportunity costs associated with not selling RT reserves
This higher RT price would flow through into a higher corresponding DA price
Virtuals would again be expected to converge the DA energy price to its expected RT value
Do not currently have data necessary to assess potential magnitude of any such price impact<br>
slide36. 36 Assessment of NYISO and MISO suggests consumer costs may increase with a DA forward reserves design Observed DA reserve premia suggest that the NYISO design could increase costs in the range of $60 million per year
NYISO design allows resources to price reserves in DA market, but does not allow priced reserves in RT
Cost increase is likely to be associated with reserves, and not energy
MISO design could increase costs associated with reserves and/or energy, though it is difficult to assess the likelihood and possible magnitude of these impacts
MISO design allows resources to price reserves in both DA and RT<br>
slide37. 37 Today’s discussion on the consumer costs under a DA forward reserves design is intended to be high level It uses aggregated summary data from other RTOs and qualitative pricing relationships to discuss possible cost implications associated with a DA forward reserve construct
Estimating these costs in a more rigorous manner would require more detailed analysis that includes:
More precise determination of reserve price offer rules (e.g. NYISO vs. MISO approach) and other design elements
The development of an economic model that simulated offer prices, cleared the market, solved for market clearing prices
ISO therefore urges caution when drawing any conclusions from the estimates presented today<br>
slide38. next steps 38<br>
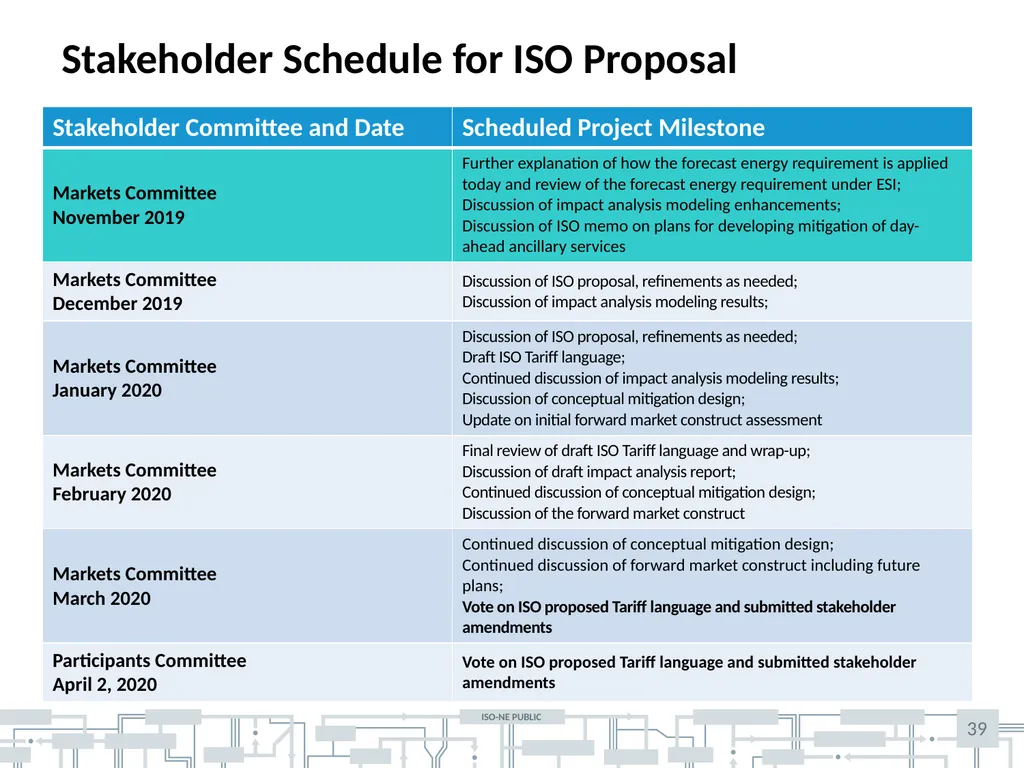
slide39. Stakeholder Schedule for ISO Proposal 39<br>
slide40. Appendix 40<br>
slide41. 41 Acronyms For brevity and clarity of messaging the following acronyms are used in this presentation
DA – Day-Ahead
ESI – Energy Security Improvements
IRC – ISO/RTO Council
LMP – Locational Marginal Price
RCP – Reserve Clearing Price
RT – Real-Time<br>
slide42. Other ISOs/RTOs DA reserve market designs 42 *PJM reflects current rules; PJM has new reserve design rules pending at FERC Source: ISO-NE research, IRC surveys, and direct discussions with individual ISOs/RTOs<br>
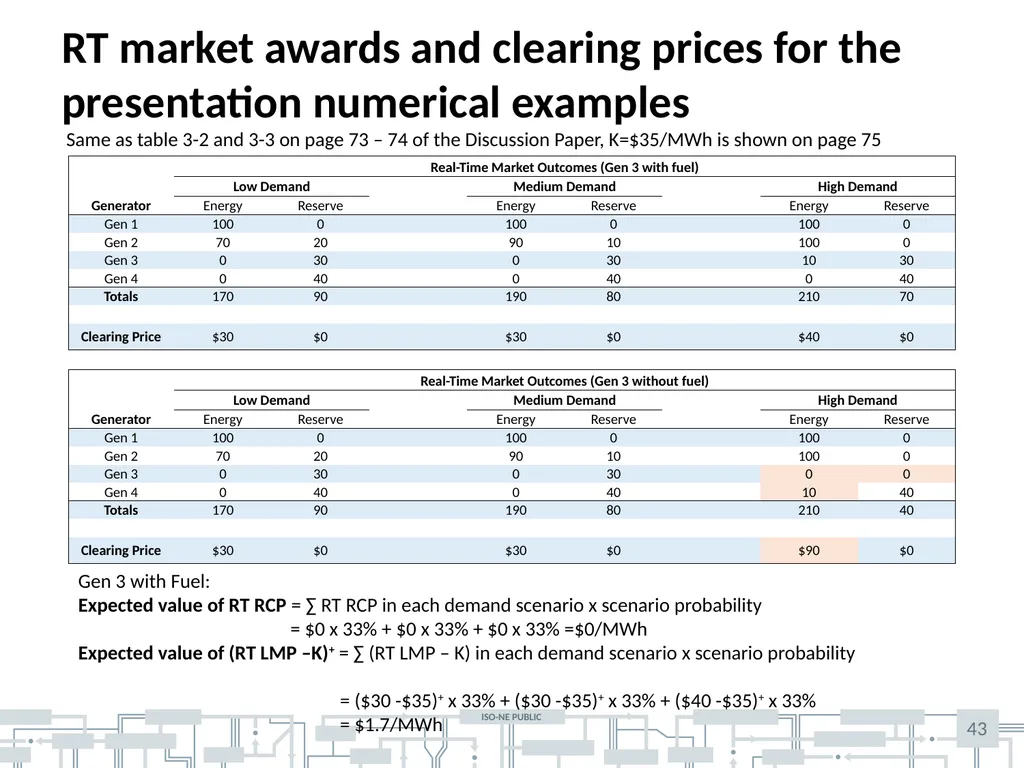
slide43. 43 RT market awards and clearing prices for the presentation numerical examples Gen 3 with Fuel:
Expected value of RT RCP = ∑ RT RCP in each demand scenario x scenario probability
= $0 x 33% + $0 x 33% + $0 x 33% =$0/MWh
Expected value of (RT LMP –K)+ = ∑ (RT LMP – K) in each demand scenario x scenario probability
= ($30 -$35)+ x 33% + ($30 -$35)+ x 33% + ($40 -$35)+ x 33%
= $1.7/MWh Same as table 3-2 and 3-3 on page 73 – 74 of the Discussion Paper, K=$35/MWh is shown on page 75<br>
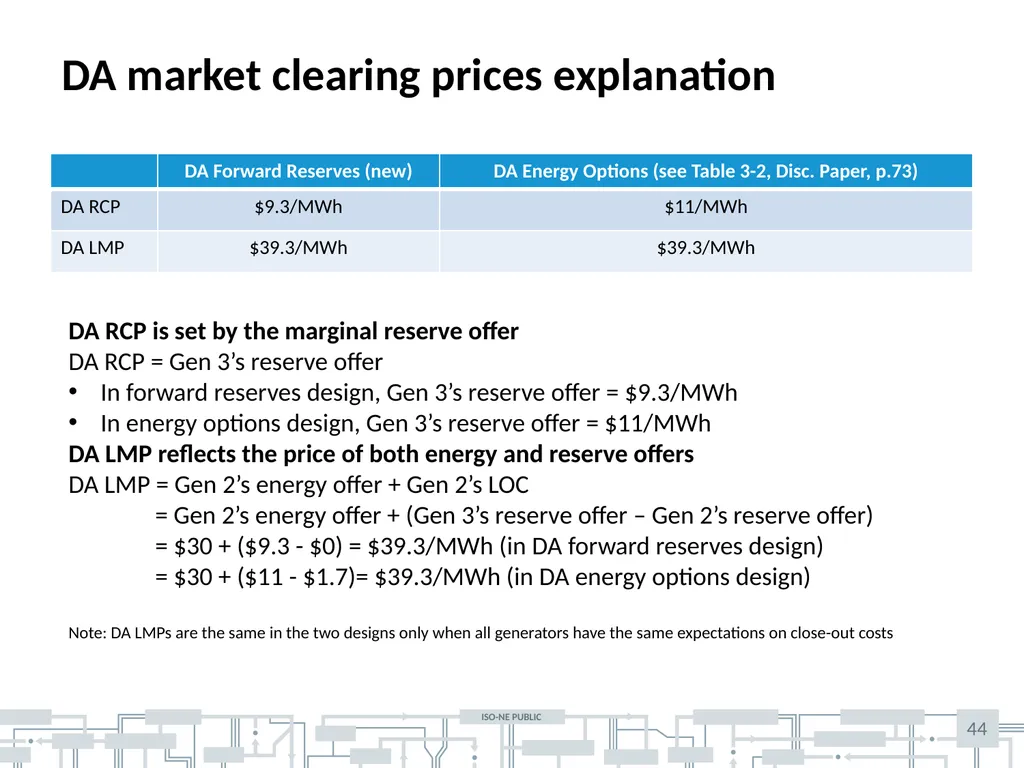
slide44. 44 DA market clearing prices explanation DA RCP is set by the marginal reserve offer
DA RCP = Gen 3’s reserve offer
In forward reserves design, Gen 3’s reserve offer = $9.3/MWh
In energy options design, Gen 3’s reserve offer = $11/MWh
DA LMP reflects the price of both energy and reserve offers
DA LMP = Gen 2’s energy offer + Gen 2’s LOC
= Gen 2’s energy offer + (Gen 3’s reserve offer – Gen 2’s reserve offer)
= $30 + ($9.3 - $0) = $39.3/MWh (in DA forward reserves design)
= $30 + ($11 - $1.7)= $39.3/MWh (in DA energy options design)
Note: DA LMPs are the same in the two designs only when all generators have the same expectations on close-out costs<br>
slide45. 45 Gen 3’s expected net revenue calculation for the status quo in the presentation example Table 2-8 is on page 37 of the Discussion Paper<br>
MARKET-BASED APPROACHES<br>
slide2. 2 Winter Energy Security Improvements WMPP ID:
125 Proposed Effective Date: June 1, 2024 In accordance with FERC’s July 2, 2018 order in EL18-182-000, the ISO must develop and file improvements to its market design to better address regional fuel security, and file by April 15, 2020
Key Projects – Energy-Security Improvements
Discussion Paper 2019-04-09 and 2019-04-10 MC A00 ISO Discussion Paper on Energy Security Improvements – Version 1<br>
slide3. 3 Prior Energy-Security Improvement Presentations November ESI presentation
September ESI presentation
August ESI presentation
July 30 ESI presentation
July 8-10 ESI presentation
June ESI presentation
May ESI presentation
April ESI presentation<br>
slide4. 4 Presentation Outline Section 1: Introduction
Section 2: Design Comparison
Section 3: Design Incentives - Examples
Section 4: Comparative Cost Implications<br>
slide5. Section 1: Introduction 5<br>
slide6. 6 Today’s Focus Address a stakeholder question:
Why does the ISO propose to settle DA reserve awards as options on RT energy, rather than as a forward sale of RT reserves?
We’ll compare the two designs, and explain the reasons for the ISO’s proposed approach. We will use the terms:
‘DA energy options’ to describe the ISO’s proposed design
‘DA forward reserves’ to describe the alternative design, where deviations from DA reserve awards settle at the RT reserve price<br>
slide7. 7 Today’s Takeaways Unlike DA energy, the reserve market designs of the nine ISOs/RTOs are not standardized (presently)
For the two designs compared today, neither is more complex for the ISO to implement
The ISO’s proposed design (DA energy options) provides stronger incentives to arrange fuel, and better addresses the region’s fuel security concerns
The alternative design (DA forward reserves) provides weaker incentives to arrange fuel, and does not fully address the region’s fuel security concerns
Note: ‘Arranging fuel’ refers to the ability to produce energy when needed, not about ‘fuel’ as a stockpile<br>
slide8. Section 2: DA Energy Options versus DA forward reserves Design Comparison Basics 8<br>
slide9. 9 The crucial design difference is the DA reserve award settlement (‘close-out’) rule DA energy options (proposed design) - the underlying product is a call option on RT energy
DA reserve awards are closed-out at the RT energy price less the option strike price, when positive
DA forward reserves (alternative design) – the underlying product is a RT reserve designation
DA reserve awards are closed-out at the RT reserve price (equivalently, RT reserve deviations from DA settle at the RT reserve price)
A resource would be credited the same way under both designs for what it delivers in RT (energy and/or reserves)<br>
slide10. 10 Settlement rules comparison *K is the strike price<br>
slide11. 11 Stakeholder Question: Do other ISOs/RTOs have a ‘standard’ two-settlement DA reserve design? Response: No. Other ISO/RTOs have implemented different DA reserve market designs (see Appendix, slide 42)
We surveyed all ISOs/RTOs in the IRC*:
Most ISOs/RTOs (7 of 9) have reserve awards in their DA markets
Some (5 of 9) co-optimize DA energy and reserves
Some have DA reserve offers only (3 of 9), some have DA and RT reserve offers (4 of 9), and some have neither (2 of 9, including ISO-NE)
Some (4 of 9) settle DA reserve awards against the RT reserve price
Some (3 of 9) have additional ad hoc settlement rules (e.g. clawbacks, penalties, etc.) for DA reserves
Key Point: There is no ‘standard’ DA reserve market design at present
We are not aware of any region-specific explanation for the variation in the DA reserve designs across the ISOs/RTOs *ISO/RTO Council<br>
slide12. 12 Stakeholder Question: Is a DA forward reserves design simpler than a DA energy options design? Response: No. The implementation complexity of each design is similar, when reserves are co-optimized in each design
Market clearing process – the DA market clearing engine, co-optimization process, and DA pricing algorithms are identical for both designs. Neither is ‘more complex’
Settlement rules– These differ, but neither settlement rule is more or less complex than the other to implement
Key Points
Neither design is simpler, nor more complex, than the other
The choice between them should rest on other, material differences (next)<br>
slide13. Section 3: Design incentives - Examples An extension of example 2 in the Discussion Paper 13<br>
slide14. 14 Stakeholder Question: Why is the ISO proposing the DA energy options design? Response: The proposed design provides stronger incentives for resources to arrange fuel, as compared to the DA forward reserves design
In this section, we will explain why using a series of numerical examples
Key Point
The DA energy options design better achieves the FERC’s directive to develop market-based solutions to “better address the region’s fuel security concerns”<br>
slide15. 15 A road map of examples ahead Example 2 in the April ESI Discussion Paper is a 4-generator model where:
Status quo (current energy-only DA market) does not provide an incentive for a generator (‘Gen 3’) to arrange fuel, though that would be efficient
DA energy options do provide efficient incentives for Gen 3 to arrange fuel
Today we will extend that example to examine whether the alternative design (DA forward reserves) provides incentives for Gen 3 to arrange fuel
We will calculate and compare Gen 3’s expected net revenue with and without fuel under the alternative design
We will see:
Gen 3’s expected net revenue is lower with fuel than without fuel
As a result, Gen 3 has no incentive to arrange fuel under the alternative design. Yet, it does under the DA energy options design<br>
slide16. 16 Revisit Example 2: Main Assumptions DA energy demand = 190 MWh, DA and RT reserve requirement = 30 MWh ISO Discussion Paper on Energy Security Improvements: Table 2-5 on page 29<br>
slide17. 17 The DA reserve designs differ in their close-out costs to a generator
We will assume that:
The generators’ fuel-related costs are the same for each design (if they arrange fuel)
Their reserve offer prices are lower under the alternative design (as it has lower expected close-out costs), by $1.7/MWh: DA reserve offer price formulation assumptions Generators’ reserve offer prices are summarized on the next slide<br>
slide18. 18 Market awards and clearing prices We assume there will be co-optimization in the DA and RT markets under both designs
DA reserve offer prices and market awards DA market clearing prices (see Appendix, slide 44 for pricing explanation) RT market awards and clearing prices are the same in both designs (see Appendix, slide 43)<br>
slide19. 19 Results Preview: Gen 3’s expected net revenues The Main Points
Gen 3’s incentive is to not arrange fuel under the DA forward reserves design, but it would do so under the DA energy options design
The stronger fuel incentives of the DA energy options design is true generally, because the resource is settled based on RT energy prices, not RT reserve prices
In general, whether or not a resource can produce energy when in demand has a larger impact on RT LMP than on RT RCP *Calculation details for the DA energy options design are in slide 23 and on Table 3-4 of the Discussion Paper, p.74
*Calculation details for the status quo are in Appendix, slide 45 and Table 2-8 of the Discussion Paper, p.37<br>
slide20. 20 Details: Gen 3’s expected net revenue calculation for the DA forward reserves design<br>
slide21. 21 Key Points - DA forward reserves design Observation
Row [6] shows the DA reserve close-out charge is $0 in all scenarios. This is because RT RCP is $0/MWh in all scenarios, even when Gen 3 has no fuel
Whether or not Gen 3 has fuel doesn't impact the RT RCP, but it does impact the RT LMP (increases from $40/MWh when Gen 3 has fuel to $90/MWh when Gen 3 has no fuel)
Key Points
Gen 3 faces no financial consequence if it cannot produce energy when in demand because the close-out charge is not based on energy prices
As a result, the DA forward reserves design doesn’t change Gen 3’s financial calculus with respect to its fuel arrangements
Other ISOs/RTOs have adopted various non-market reserve penalty mechanisms in an attempt to address reserve non-performance issues (see Appendix, slide 42)
Such non-market penalties are ad hoc “crutches”, rather than a true fix for the underlying (misaligned incentives) design issue<br>
slide22. 22 The DA forward reserves design does not fix the misaligned incentives problem [In the current market], “resources facing production uncertainty may have inefficiently low incentives to invest in additional energy supply arrangements, even though such arrangements would be cost effective from society’s standpoint as a means to reduce reliability risk”
April Discussion Paper, p. 10
In this example, it is socially efficient for Gen 3 to arrange fuel
Gen 3 having fuel reduces RT total production cost by $167, more than enough to cover its $150 up-front fuel arrangement cost (see page 36 of the Discussion Paper)
With the DA forward reserves design, Gen 3’s financial best interest is to not arrange fuel
Its financial consequences, if it cannot produce energy, are too low (zero)
The DA forward reserve design fails to align society’s preferred decision with Gen 3’s private fuel arrangement decision
This is true in general: the DA forward reserve design does not resolve the misaligned incentives problem<br>
slide23. 23 Next: Gen 3’s expected net revenue calculation for the DA energy options design Row [13] shows Gen 3 is now better off arranging for fuel – the misaligned incentives problem is resolved
Table 3-4 is on page 74 of the Discussion Paper<br>
slide24. 24 Key Points - DA energy options design Observation
Row [4] shows Gen 3 incurs a steep $1,100 close-out charge when it has no advance fuel and load turns out to be high
Close-out charge = (RT LMP of $90/MWh – K of $35/MWh) x Option Award of 20 MWh
Key Points
Gen 3 faces high financial consequence if it cannot produce energy when needed because the close-out charge is based on the cost of energy (RT LMP of $90/MWh)
As a result, the DA energy options design changes a resource’s financial calculus with respect to whether or not to arrange fuel:
The fuel incentive is stronger than the DA forward reserves design; and
The fuel incentive is stronger than the status quo<br>
slide25. 25 Design comparison takeaways To provide efficient incentives to arrange fuel, there should be a financial consequence tied to whether or not a resource can produce energy in real-time
That financial consequence should resolve the misaligned incentives problem, i.e., align society’s interest with the generator’s private financial interest to arrange fuel
The DA forward reserves design doesn’t tie financial consequence to the price of energy in real-time
Close-out charge is $0 (based on $0/MWh RT RCP), in this example
This design does not resolve the misaligned incentives problem
The DA energy options design does tie financial consequence to the price of energy in real-time
If a resource cannot produce energy when needed, the close-out charge is high at $1,100 in total (based on $90/MWh RT LMP), in this example
This design resolves the misaligned incentives problem<br>
slide26. 26 Summary Unlike DA energy, the reserve market designs of the nine ISOs/RTOs are not standardized (presently)
For the two designs compared today, neither is more complex for the ISO to implement
The ISO’s proposed design (DA energy options) provides stronger incentives to arrange fuel, and better addresses the region’s fuel security concerns
The alternative design (DA forward reserves) provides weaker incentives to arrange fuel, and does not fully address the region’s fuel security concerns<br>
slide27. Comparative Cost Implications 27 Section 4: DA Energy Options versus DA forward reserves<br>
slide28. 28 Stakeholder Question: How would total consumer costs (and producer revenues) change if the ISO uses a DA forward reserves design? Procurement of DA reserves under a DA forward reserves design would be in place of ISO’s proposal to buy DA reserves under a DA energy options design
DA forward reserves would settle against the RT reserve price using the standard two-settlement structure
Address this question using experience in two other RTOs that have DA forward reserves – NYISO and MISO
Use data on DA and RT reserve prices from these regions to assess potential market impacts if we observed similar pricing relationship in New England<br>
slide29. 29 Today’s discussion does not assess the costs of other changes to ancillary service markets Evaluation does not consider if/how a DA forward reserves design could accommodate EIR or RER, for which there is currently no RT counterpart
Discussion excludes consideration of the FRM, which does not follow the standard two-settlement structure and includes a number of administrative rules
Will evaluate impacts of buying a different set of DA energy options than proposed (e.g., no RER products) at future MC meetings as part of the Impact Analysis<br>
slide30. 30 Evaluate cost implications of a DA forward reserves design using data from other RTOs Both NYISO and MISO procure DA reserves and provide compensation for this service
They do not procure products that are comparable to EIR or RER
Their design details differ, with varying cost implications
Use annual price data from both RTOs to assess the impact of procuring DA reserves using a DA forward reserves design on consumer costs in New England
Caveat: There are many differences between the market rules and structure in these RTOs and in New England beyond their procurement of DA reserves
Estimated cost impacts from these RTOs cannot be applied to New England in an apples-to-apples manner
Next: Discuss potential impacts on reserve costs in each RTO before considering possible effects on energy costs<br>
slide31. 31 NYISO has experienced higher reserve prices in DA than in RT NYISO’s design allows participants to submit priced offers for reserves in the DA market, but does not allow priced RT offers
In 2017 and 2018, average DA reserve prices were higher than in RT, where the difference varied by year, location, product:
For example, average prices for 30 minute reserves in West New York in 2018 were $4.16/MWh in DA, and $0.41 in RT
Difference between DA and RT prices may occur because of:
Risk premium in DA offers
Exclusion of virtuals from DA reserve market
Other potential design features
Source: 2018 State of the Market Report (Appendix), Figures A16-A19<br>
slide32. 32 Applying NYISO’s DA premiums to New England yields annual increase in reserve costs of $62 million *NYISO 2018 State of the Market Report (Appendix), Figures A16-A19, where the 10 minute spinning is the average of the premium between those in the east and west regions
^ISO-NE 2018 Annual Market Report, Figure 2-15<br>
slide33. 33 MISO’s experience does not yield clear estimates if reserve costs would change MISO’s design allows participants to submit priced offers for reserves in both the DA and RT markets
Total reserve costs could go up under such a design, if allowance of RT reserve offer prices increases the average RT reserve clearing price
Assessing this impact would require detailed data on reserve price components
In 2017 and 2018, average reserve prices were roughly $3 for spinning reserves, $1 for supplemental reserves
Average DA and RT reserve prices were close (within $0.50)
Suggests that there would not be a reserve cost increase associated with a DA premium
Source: 2018 State of the Markets Report (Analytical Appendix), Figure A27<br>
slide34. 34 NYISO approach appears unlikely to materially impact energy costs NYISO approach does not allow reserve offer prices in RT
New England’s current market rules also do not allow such offer prices
Applying the NYISO approach to New England would therefore not change the RT optimization and pricing from current market rules
Would therefore expect similar RT energy (and reserve) prices
DA energy prices are unlikely to be higher than RT prices because INCs and DECs will generally converge the DA energy price to its expected RT value
With no expected changes to DA or RT energy prices, would not expect material change in energy market costs<br>
slide35. 35 MISO design may lead to higher energy prices By allowing resources to offer priced reserves in RT, New England’s adoption of the MISO design could increase RT energy prices relative to current market rules
RT co-optimization and energy pricing must account for opportunity costs associated with not selling RT reserves
This higher RT price would flow through into a higher corresponding DA price
Virtuals would again be expected to converge the DA energy price to its expected RT value
Do not currently have data necessary to assess potential magnitude of any such price impact<br>
slide36. 36 Assessment of NYISO and MISO suggests consumer costs may increase with a DA forward reserves design Observed DA reserve premia suggest that the NYISO design could increase costs in the range of $60 million per year
NYISO design allows resources to price reserves in DA market, but does not allow priced reserves in RT
Cost increase is likely to be associated with reserves, and not energy
MISO design could increase costs associated with reserves and/or energy, though it is difficult to assess the likelihood and possible magnitude of these impacts
MISO design allows resources to price reserves in both DA and RT<br>
slide37. 37 Today’s discussion on the consumer costs under a DA forward reserves design is intended to be high level It uses aggregated summary data from other RTOs and qualitative pricing relationships to discuss possible cost implications associated with a DA forward reserve construct
Estimating these costs in a more rigorous manner would require more detailed analysis that includes:
More precise determination of reserve price offer rules (e.g. NYISO vs. MISO approach) and other design elements
The development of an economic model that simulated offer prices, cleared the market, solved for market clearing prices
ISO therefore urges caution when drawing any conclusions from the estimates presented today<br>
slide38. next steps 38<br>
slide39. Stakeholder Schedule for ISO Proposal 39<br>
slide40. Appendix 40<br>
slide41. 41 Acronyms For brevity and clarity of messaging the following acronyms are used in this presentation
DA – Day-Ahead
ESI – Energy Security Improvements
IRC – ISO/RTO Council
LMP – Locational Marginal Price
RCP – Reserve Clearing Price
RT – Real-Time<br>
slide42. Other ISOs/RTOs DA reserve market designs 42 *PJM reflects current rules; PJM has new reserve design rules pending at FERC Source: ISO-NE research, IRC surveys, and direct discussions with individual ISOs/RTOs<br>
slide43. 43 RT market awards and clearing prices for the presentation numerical examples Gen 3 with Fuel:
Expected value of RT RCP = ∑ RT RCP in each demand scenario x scenario probability
= $0 x 33% + $0 x 33% + $0 x 33% =$0/MWh
Expected value of (RT LMP –K)+ = ∑ (RT LMP – K) in each demand scenario x scenario probability
= ($30 -$35)+ x 33% + ($30 -$35)+ x 33% + ($40 -$35)+ x 33%
= $1.7/MWh Same as table 3-2 and 3-3 on page 73 – 74 of the Discussion Paper, K=$35/MWh is shown on page 75<br>
slide44. 44 DA market clearing prices explanation DA RCP is set by the marginal reserve offer
DA RCP = Gen 3’s reserve offer
In forward reserves design, Gen 3’s reserve offer = $9.3/MWh
In energy options design, Gen 3’s reserve offer = $11/MWh
DA LMP reflects the price of both energy and reserve offers
DA LMP = Gen 2’s energy offer + Gen 2’s LOC
= Gen 2’s energy offer + (Gen 3’s reserve offer – Gen 2’s reserve offer)
= $30 + ($9.3 - $0) = $39.3/MWh (in DA forward reserves design)
= $30 + ($11 - $1.7)= $39.3/MWh (in DA energy options design)
Note: DA LMPs are the same in the two designs only when all generators have the same expectations on close-out costs<br>
slide45. 45 Gen 3’s expected net revenue calculation for the status quo in the presentation example Table 2-8 is on page 37 of the Discussion Paper<br>