
Finance for Normal People Chapter 11: Behavioral
Description: Finance for Normal People Chapter 11: Behavioral Market Efficiency Behavioral Market Efficiency Efficient markets in standard finance Eugene Fama described an efficient market as one in which prices always fully reflect available
Related Topics
Download Presentation
"Finance for Normal People Chapter 11: Behavioral" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Finance for Normal People
Chapter 11: Behavioral Market Efficiency<br>
slide2. Behavioral Market Efficiency Efficient markets in standard finance
Eugene Fama described an efficient market as one “in which prices always fully reflect available information”
“Available information,” however, is an ambiguous term, and so are the terms “public information” and “private information”<br>
slide3. Behavioral Market Efficiency The two versions of efficient markets and the two corresponding efficient market hypotheses
Price-equals-value markets - Markets where investments
prices always equal their intrinsic values
Hard-to-beat markets - Markets where some investors
are able to beat the market, but most are unable to do so<br>
slide4. Behavioral Market Efficiency The price-equals-value market hypothesis is false
The hard-to-beat market hypothesis is true
Why do so many investors believe that markets are easy to beat?<br>
slide5. Behavioral Market Efficiency “Why do active investors continue to play a negative sum game?”
1. Ignorance
2. Cognitive and emotional errors
3. Wants for expressive and emotional benefits<br>
slide6. Behavioral Market Efficiency Intrinsic value
A cow for her milk,
A hen for her eggs,
And a stock, by heck, for her dividends
John Burr Williams, The Theory of Investment Value<br>
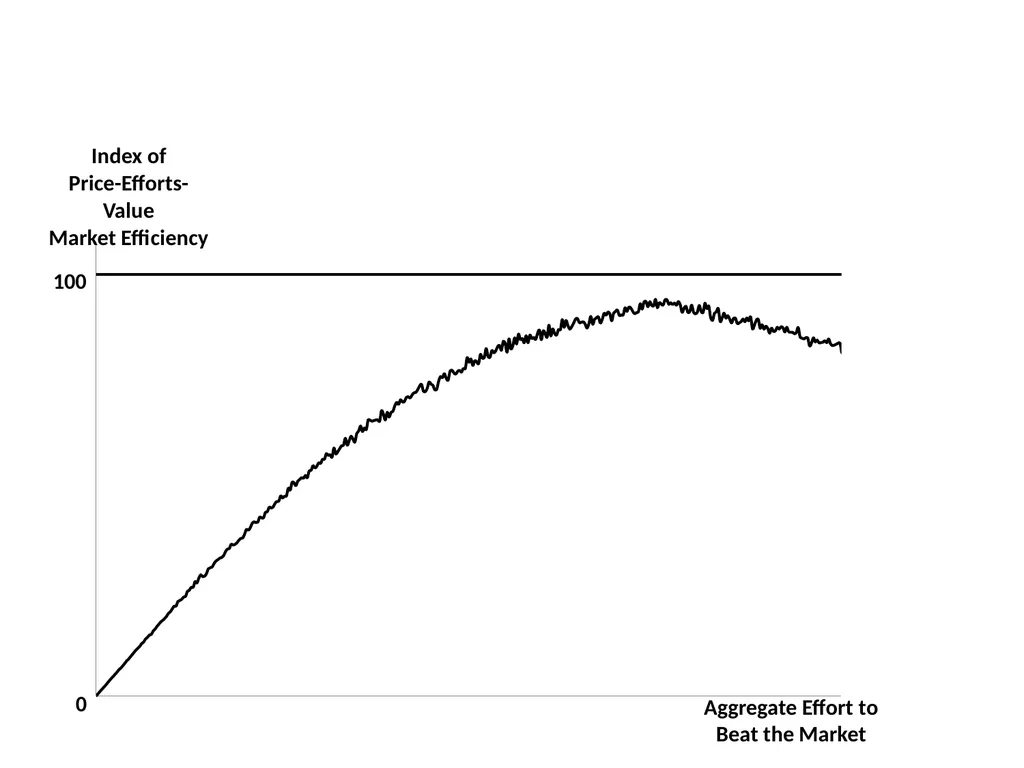
slide7. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
Warren Buffett received three bids from sellers of Citizens Insurance bonds, one at a price that would yield 11.33%, one at 9.87% and one at 6.00%
"It's the same bond, the same time, the same dealer. And a big issue”<br>
slide8. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
“This is not some little anomaly, as they like to say in academic circles every time they find something that disagrees with their [efficient market] theory“
Buffett referred to “efficient market,” but the term price-equals-value market would have been more precise<br>
slide9. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
Buffett cautioned investors not to jump too fast from evidence that markets are not price-equals-value markets to the conclusion that markets are not hard-to-beat markets<br>
slide10. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
When asked “What advice would you give to someone who is not a professional investor,” Buffett said:
“Well, if they’re not going to be an active investor – and very few should try that – then they should just stay with index funds. Any low-cost index fund… They’re not going to be able to pick the right price and the right time”<br>
slide11. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
Investors might not care much about whether markets are price-equals-value markets
But everyone should care about whether markets are price-equals-value markets
Proper allocation of the economy’s resources benefits everyone<br>
slide12. Behavioral Market Efficiency The price-equals-value market hypothesis
Testing the price-equals-value market hypothesis directly is difficult
because estimating the intrinsic values of investments is difficult<br>
slide13. Behavioral Market Efficiency The change-price-equals-change-value market hypothesis
This hypothesis is easier to test
The story of the Titanic illustrates<br>
slide14. Behavioral Market Efficiency The change-price-equals-change-value market hypothesis
Other evidence is inconsistent with this hypothesis
Large changes in the level of the S&P 500 Index occurred with no events likely associated with changes in intrinsic values<br>
slide15. Behavioral Market Efficiency Fama described an efficient market as one “in which prices always “fully reflect” available information”
“Available information,” however, is an ambiguous term, and so are the terms “public information” and “private information”
Publication in Nature make information publicly available, and so does publication in the New York Times
Yet publication in the New York Times makes information widely available whereas publication in Nature, makes it only narrowly available<br>
slide16. Behavioral Market Efficiency Eugene Fama divided the efficient market hypothesis into three forms:
1. The strong form
2. The semi-strong form
3. The weak form<br>
slide17. Behavioral Market Efficiency The three forms of the hard-to-beat market hypothesis
1. The exclusively-available-information form
2. The narrowly-available-information form
3. The widely-available-information form<br>
slide18. Behavioral Market Efficiency Who beats a hard-to-beat market?
Hard-to-beat markets are not impossible to beat
Investors with exclusively-available information find it easy to beat the market
Investors with narrowly-available information find it hard but not impossible to beat the market
Yet, on average, investors with nothing more than widely-available information find it impossible to beat the market<br>
slide19. Behavioral Market Efficiency Why do investors with only widely-available information try to beat the market?
Think of a stock market game as a tennis game
You profit by $100 if you do not play
You profit by $150 if you play and win
You profit by $50 if you play and lose
Would you play?<br>
slide20. Behavioral Market Efficiency Why do investors with only widely-available information try to beat the market?
Match-the-market investors choose not to play
Divide beat-the-market players into two kinds, amateurs and professionals
Professionals win half the games when facing professionals, collecting $100 on average in each game
Professionals always win when facing amateurs, collecting $150
Professionals collect $125 on average in each game<br>
slide21. Behavioral Market Efficiency Why do investors with only widely-available information try to beat the market?
Amateurs win half the games when facing amateurs, collecting $100 on average in each game
They lose all games when facing professionals, collecting $50 in each game
Amateurs collect $75 on average in each game<br>
slide22. Behavioral Market Efficiency Fischer Black described the trading puzzle in “Noise.”
“A person with information or insights about individual firms will want to trade, but will realize that only another person with information or insights will take the other side of the trade
Taking the other side's information into account, is it still worth trading?
From the point of view of someone who knows what both the traders know, one side or the other must be making a mistake
If the one who is making a mistake declines to trade, there will be no trading on information”<br>
slide23. Behavioral Market Efficiency Noise trading, wrote Black, is the key to solving the trading puzzle
Some noise traders are motivated to trade by ignorance about their cognitive and emotional errors - “Perhaps they think the noise they are trading on is information”
Other noise traders are motivated to trade by wants - “Or perhaps they just like to trade”<br>
slide24. Behavioral Market Efficiency Why do investors with only widely-available information try to beat the market?
Framing errors – Framing trading as tennis played against a training wall
Overplacement errors – Can you really beat Djokovic?
Availability errors – Winners are more available to memory
Representativeness errors - focusing on their own recent returns and neglecting to consider the average returns of all investors over long time periods<br>
slide25. Behavioral Market Efficiency Wants affect behavior even in the absence of cognitive and emotional errors
A Fidelity survey found that 78% of traders trade for reasons beyond profits;
54% enjoy “the thrill of the hunt,”
53% enjoy learning new investment skills,
More than half enjoy engaging in social activities<br>
slide26. Behavioral Market Efficiency Money managers cater to investors’ wants and exploit their cognitive and emotional errors
Managers of beat-the-market funds satisfy their investors’ wants for the utilitarian benefits of high returns
and the expressive and emotional benefits of playing the beat-the-market game and winning<br>
slide27. Behavioral Market Efficiency Mutual fund managers exploit availability errors by “window dressing,”
changing the composition of their portfolios to increase their appeal when disclosed to investors<br>
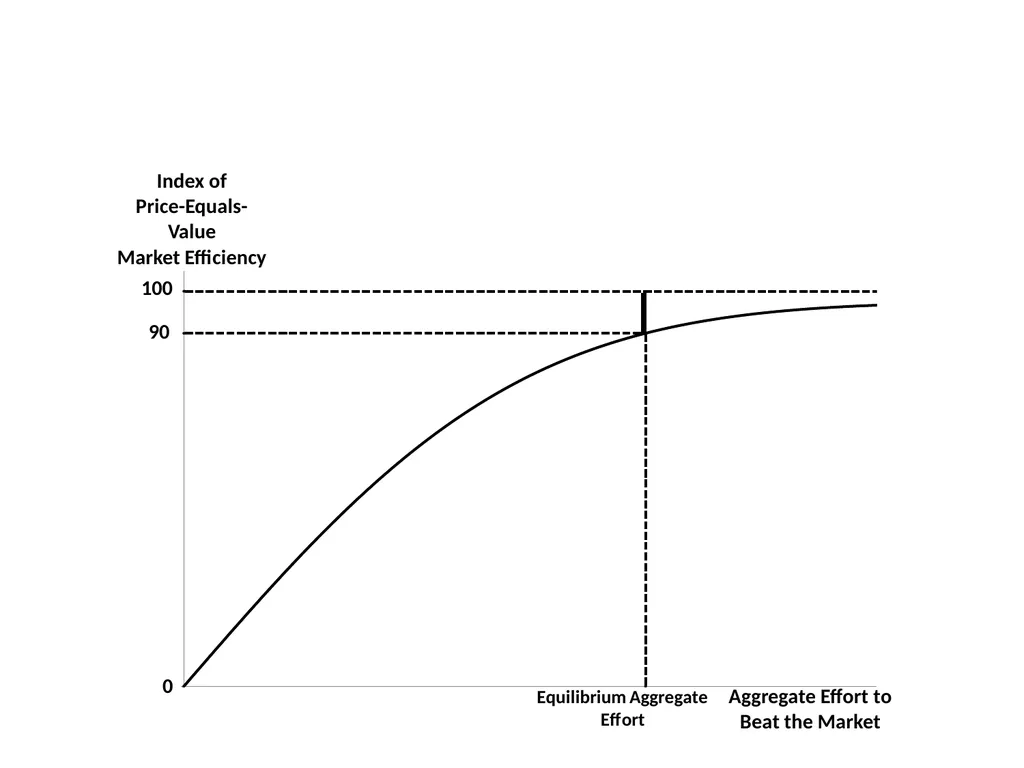
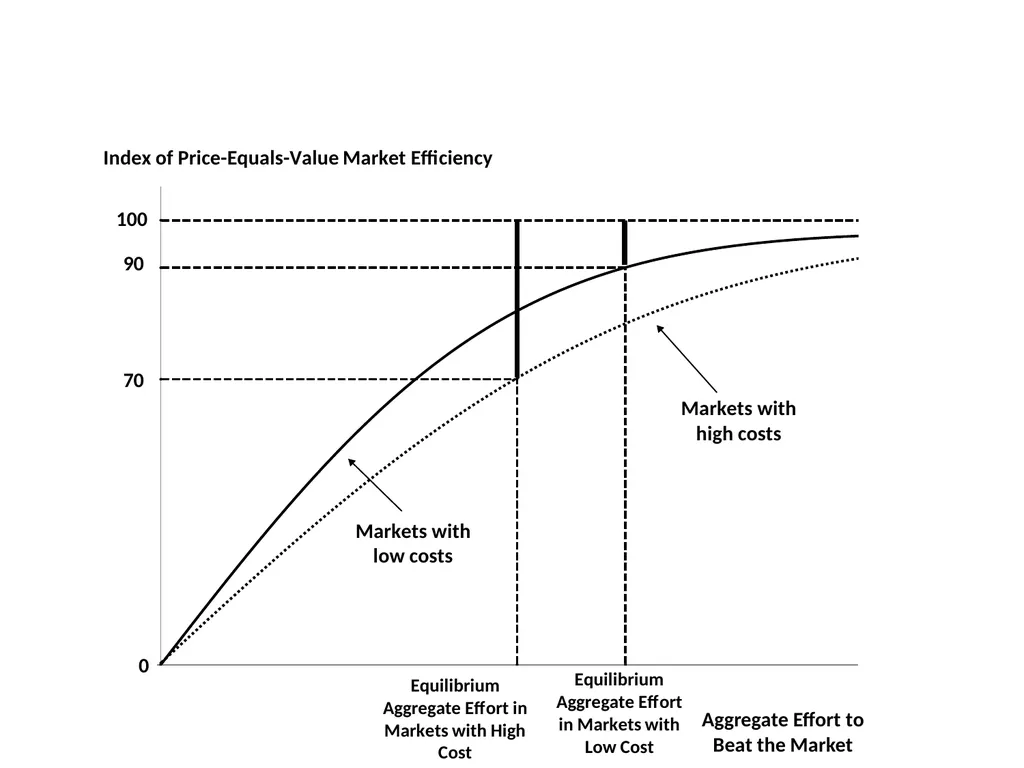
slide28. Behavioral Market Efficiency Making the market hard to beat by beating it
We face what seems like a paradox: Investors who believe that the hard-to-beat market hypothesis is false can make the hard-to-beat market hypothesis come true
Indeed, they can even make the price-equals-value market hypothesis come true.<br>
slide33. Behavioral Market Efficiency Bubbles in rational and hard-to-beat markets
Bubbles cannot exist in price-equals-value markets
Bubbles, however, can persist in hard-to-beat markets<br>
slide38. Behavioral Market Efficiency The joint hypothesis: Market efficiency, asset pricing, and “smart beta”
The efficient market hypothesis cannot be tested on its own
Returns of small-capitalization and value stocks when measured by the CAPM might indicate that the market is not efficient
Or they might indicate that the CAPM is a faulty model of expected returns<br>
slide39. Behavioral Market Efficiency Smart beta strategies center on portfolios whose allocations do not correspond to market capitalizations
The proportion of a particular value stock might be 0.5% by market capitalization
But the proportion allocated to this value stock might be 2% in a smart beta portfolio
Are excess returns of smart beta strategies evidence that markets are not efficient?
Or are they reflections of faulty asset pricing models?<br>
slide40. Behavioral Market Efficiency Jennifer Bender of State Street Global Investors said:
“For smart beta, the end investor makes a decision to have exposure to certain factors…
This is very different from, say, a traditional quantitative manager who would use factors… to generate [market-beating] alpha…
[Q]uite a bit of active returns can be explained by very simple rules-based factor portfolios
And that does present a challenge to active investing overall!”<br>
slide41. Behavioral efficient markets What is the joint hypothesis?
You have the file “Factors-Students” from Chapter 10, and you calculated regressions of each of 4 mutual fund by the CAPM, 3-factor, and 5-factor asset pricing models. The “alpha” of each fund by each asset pricing model is its excess returns. (The estimated alpha of each fund by each asset pricing model is the intercept of the regression)
Look at the alphas of each fund by each of the asset pricing models. Are the alphas of each fund the same by the 3 models or are they different? What do the alphas tell us about market efficiency? How do they illustrate the joint hypothesis?<br>
slide42. Behavioral asset pricing Question
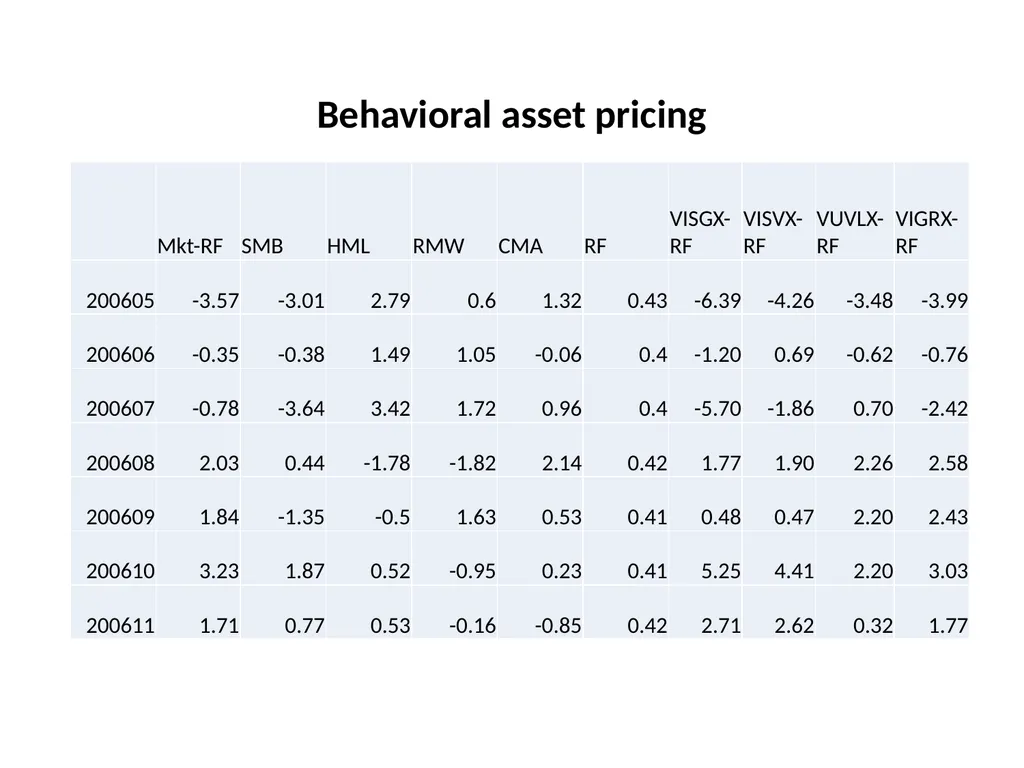
Excel file “factors-Students” includes monthly factor returns of 5 factors, market, small-large, value-growth, profitability, and investment. Factor returns are returns minus Treasury-bill returns that proxy for the risk free returns. It also includes monthly returns minus Treasury-bill returns of four mutual funds:
VISGX - Vanguard Small Capitalization Growth Index Fund
VISVX - Vanguard Small Capitalization Value Index Fund
VUVLX - Vanguard US Value
VIGRX - Vanguard Growth Index Fund<br>
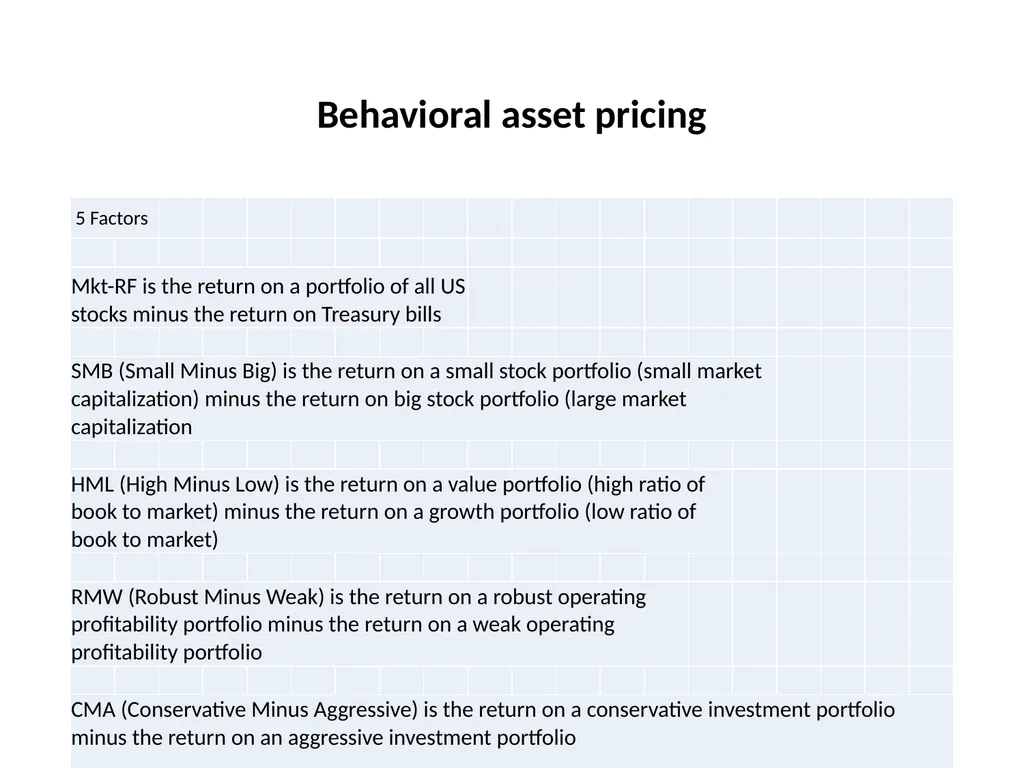
slide43. Behavioral asset pricing<br>
slide44. Behavioral asset pricing Examine the returns minus Treasury-bill returns of each mutual fund by the CAPM, 3-factor model, and 5-factor model
What are the betas of each factor according to each model?
How do you interpret the betas?
Are the betas consistent with the names of the funds?
How are the betas similar or different across the 3 models?<br>
slide45. Behavioral asset pricing<br>
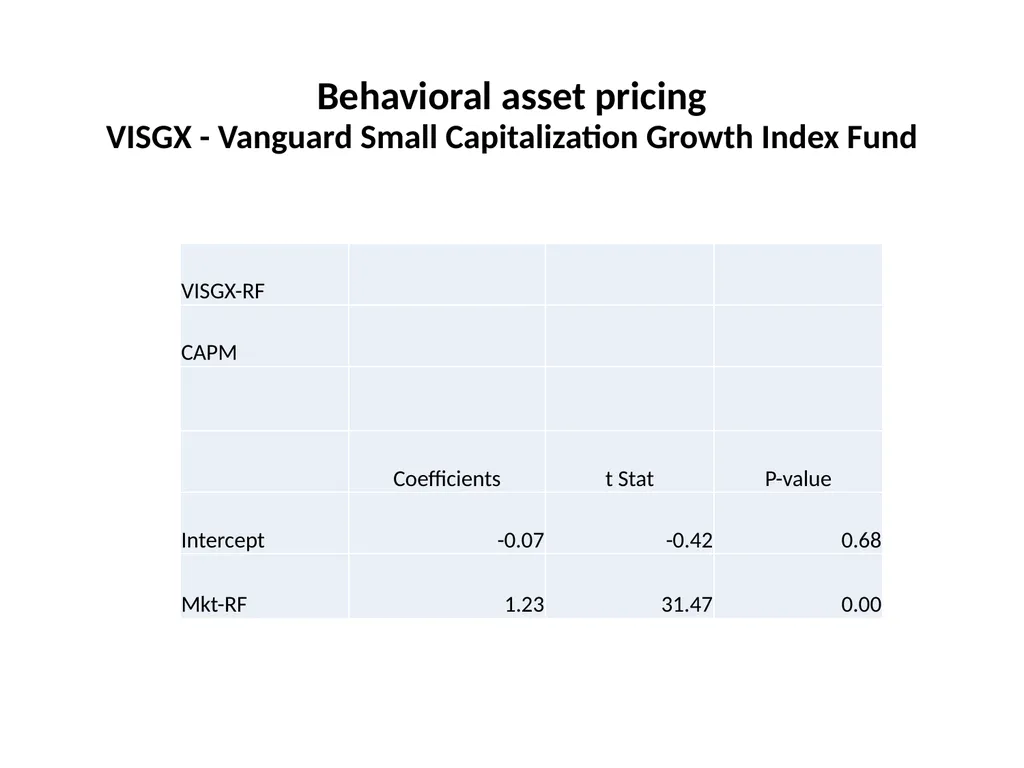
slide46. Behavioral asset pricing VISGX - Vanguard Small Capitalization Growth Index Fund<br>
slide47. Behavioral asset pricing VISGX is a small growth fund
Based on the CAPM (1-factor model) it has a market-factor beta of 1.23
So when the return of the stock market increases by 1 percentage point, the return of VISGX can be expected to increase by 1.23 percentage points<br>
slide48. Behavioral asset pricing VISGX - Vanguard Small Capitalization Growth Index Fund<br>
slide49. Behavioral asset pricing VISGX is a small growth fund
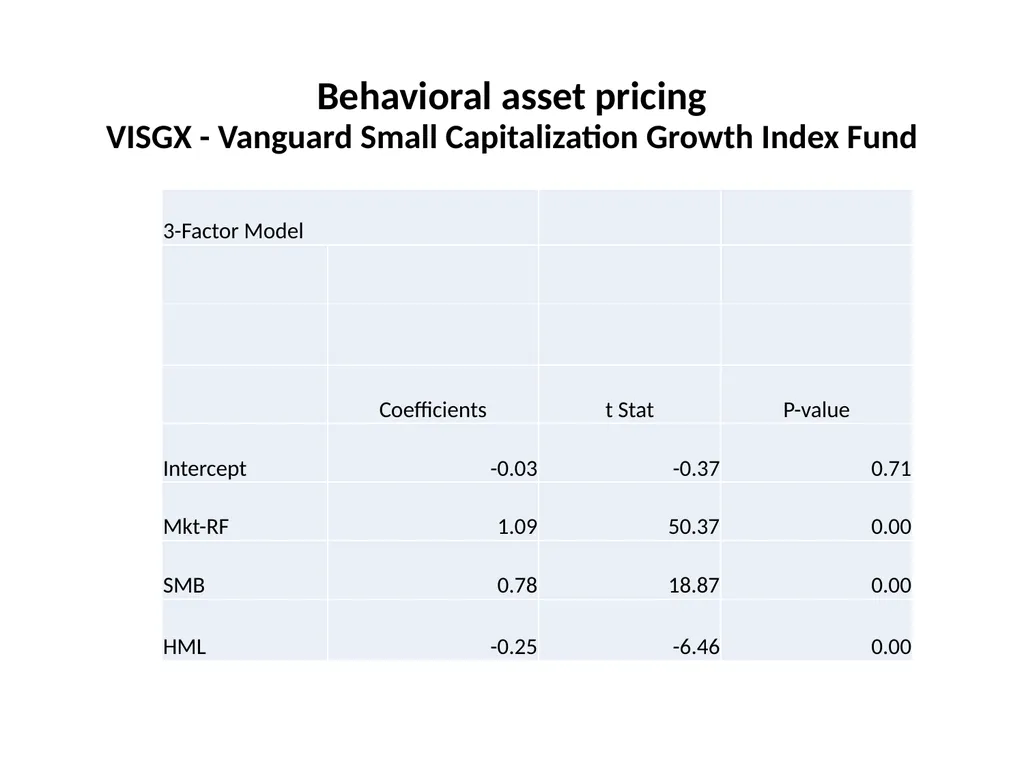
Based on the 3-factor model, it tilts toward small capitalization stocks and away from large capitalization stocks (Its Small-Large (SMB) beta is positive 0.78)
It tilts away from value stocks and toward growth stocks (Its Value-Growth (HML) beta is negative -0.25)<br>
slide50. Behavioral asset pricing VISGX - Vanguard Small Capitalization Growth Index Fund<br>
slide51. Behavioral asset pricing VISGX is a small growth fund
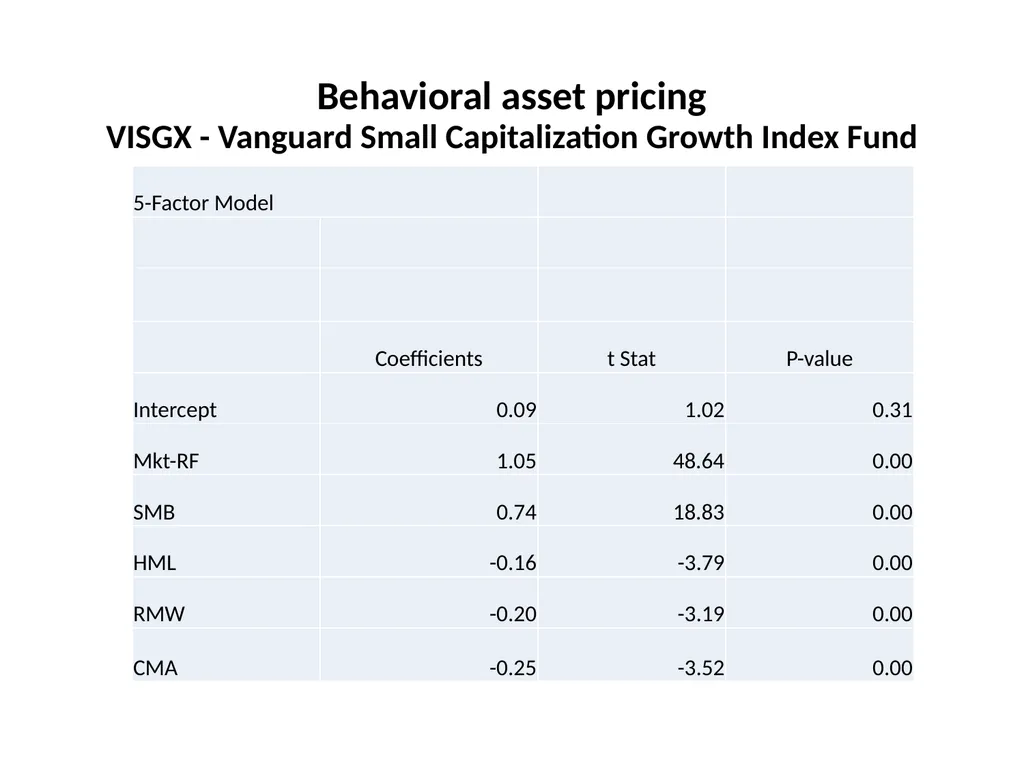
Based on the 5-factor model, it tilts away from stocks with robust profitability and stocks with conservative investment
Its RMW coefficient is negative -0.20, and its CMA coefficient is negative -0.25<br>
Chapter 11: Behavioral Market Efficiency<br>
slide2. Behavioral Market Efficiency Efficient markets in standard finance
Eugene Fama described an efficient market as one “in which prices always fully reflect available information”
“Available information,” however, is an ambiguous term, and so are the terms “public information” and “private information”<br>
slide3. Behavioral Market Efficiency The two versions of efficient markets and the two corresponding efficient market hypotheses
Price-equals-value markets - Markets where investments
prices always equal their intrinsic values
Hard-to-beat markets - Markets where some investors
are able to beat the market, but most are unable to do so<br>
slide4. Behavioral Market Efficiency The price-equals-value market hypothesis is false
The hard-to-beat market hypothesis is true
Why do so many investors believe that markets are easy to beat?<br>
slide5. Behavioral Market Efficiency “Why do active investors continue to play a negative sum game?”
1. Ignorance
2. Cognitive and emotional errors
3. Wants for expressive and emotional benefits<br>
slide6. Behavioral Market Efficiency Intrinsic value
A cow for her milk,
A hen for her eggs,
And a stock, by heck, for her dividends
John Burr Williams, The Theory of Investment Value<br>
slide7. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
Warren Buffett received three bids from sellers of Citizens Insurance bonds, one at a price that would yield 11.33%, one at 9.87% and one at 6.00%
"It's the same bond, the same time, the same dealer. And a big issue”<br>
slide8. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
“This is not some little anomaly, as they like to say in academic circles every time they find something that disagrees with their [efficient market] theory“
Buffett referred to “efficient market,” but the term price-equals-value market would have been more precise<br>
slide9. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
Buffett cautioned investors not to jump too fast from evidence that markets are not price-equals-value markets to the conclusion that markets are not hard-to-beat markets<br>
slide10. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
When asked “What advice would you give to someone who is not a professional investor,” Buffett said:
“Well, if they’re not going to be an active investor – and very few should try that – then they should just stay with index funds. Any low-cost index fund… They’re not going to be able to pick the right price and the right time”<br>
slide11. Behavioral Market Efficiency Price-equals-value and hard-to-beat markets
Investors might not care much about whether markets are price-equals-value markets
But everyone should care about whether markets are price-equals-value markets
Proper allocation of the economy’s resources benefits everyone<br>
slide12. Behavioral Market Efficiency The price-equals-value market hypothesis
Testing the price-equals-value market hypothesis directly is difficult
because estimating the intrinsic values of investments is difficult<br>
slide13. Behavioral Market Efficiency The change-price-equals-change-value market hypothesis
This hypothesis is easier to test
The story of the Titanic illustrates<br>
slide14. Behavioral Market Efficiency The change-price-equals-change-value market hypothesis
Other evidence is inconsistent with this hypothesis
Large changes in the level of the S&P 500 Index occurred with no events likely associated with changes in intrinsic values<br>
slide15. Behavioral Market Efficiency Fama described an efficient market as one “in which prices always “fully reflect” available information”
“Available information,” however, is an ambiguous term, and so are the terms “public information” and “private information”
Publication in Nature make information publicly available, and so does publication in the New York Times
Yet publication in the New York Times makes information widely available whereas publication in Nature, makes it only narrowly available<br>
slide16. Behavioral Market Efficiency Eugene Fama divided the efficient market hypothesis into three forms:
1. The strong form
2. The semi-strong form
3. The weak form<br>
slide17. Behavioral Market Efficiency The three forms of the hard-to-beat market hypothesis
1. The exclusively-available-information form
2. The narrowly-available-information form
3. The widely-available-information form<br>
slide18. Behavioral Market Efficiency Who beats a hard-to-beat market?
Hard-to-beat markets are not impossible to beat
Investors with exclusively-available information find it easy to beat the market
Investors with narrowly-available information find it hard but not impossible to beat the market
Yet, on average, investors with nothing more than widely-available information find it impossible to beat the market<br>
slide19. Behavioral Market Efficiency Why do investors with only widely-available information try to beat the market?
Think of a stock market game as a tennis game
You profit by $100 if you do not play
You profit by $150 if you play and win
You profit by $50 if you play and lose
Would you play?<br>
slide20. Behavioral Market Efficiency Why do investors with only widely-available information try to beat the market?
Match-the-market investors choose not to play
Divide beat-the-market players into two kinds, amateurs and professionals
Professionals win half the games when facing professionals, collecting $100 on average in each game
Professionals always win when facing amateurs, collecting $150
Professionals collect $125 on average in each game<br>
slide21. Behavioral Market Efficiency Why do investors with only widely-available information try to beat the market?
Amateurs win half the games when facing amateurs, collecting $100 on average in each game
They lose all games when facing professionals, collecting $50 in each game
Amateurs collect $75 on average in each game<br>
slide22. Behavioral Market Efficiency Fischer Black described the trading puzzle in “Noise.”
“A person with information or insights about individual firms will want to trade, but will realize that only another person with information or insights will take the other side of the trade
Taking the other side's information into account, is it still worth trading?
From the point of view of someone who knows what both the traders know, one side or the other must be making a mistake
If the one who is making a mistake declines to trade, there will be no trading on information”<br>
slide23. Behavioral Market Efficiency Noise trading, wrote Black, is the key to solving the trading puzzle
Some noise traders are motivated to trade by ignorance about their cognitive and emotional errors - “Perhaps they think the noise they are trading on is information”
Other noise traders are motivated to trade by wants - “Or perhaps they just like to trade”<br>
slide24. Behavioral Market Efficiency Why do investors with only widely-available information try to beat the market?
Framing errors – Framing trading as tennis played against a training wall
Overplacement errors – Can you really beat Djokovic?
Availability errors – Winners are more available to memory
Representativeness errors - focusing on their own recent returns and neglecting to consider the average returns of all investors over long time periods<br>
slide25. Behavioral Market Efficiency Wants affect behavior even in the absence of cognitive and emotional errors
A Fidelity survey found that 78% of traders trade for reasons beyond profits;
54% enjoy “the thrill of the hunt,”
53% enjoy learning new investment skills,
More than half enjoy engaging in social activities<br>
slide26. Behavioral Market Efficiency Money managers cater to investors’ wants and exploit their cognitive and emotional errors
Managers of beat-the-market funds satisfy their investors’ wants for the utilitarian benefits of high returns
and the expressive and emotional benefits of playing the beat-the-market game and winning<br>
slide27. Behavioral Market Efficiency Mutual fund managers exploit availability errors by “window dressing,”
changing the composition of their portfolios to increase their appeal when disclosed to investors<br>
slide28. Behavioral Market Efficiency Making the market hard to beat by beating it
We face what seems like a paradox: Investors who believe that the hard-to-beat market hypothesis is false can make the hard-to-beat market hypothesis come true
Indeed, they can even make the price-equals-value market hypothesis come true.<br>
slide33. Behavioral Market Efficiency Bubbles in rational and hard-to-beat markets
Bubbles cannot exist in price-equals-value markets
Bubbles, however, can persist in hard-to-beat markets<br>
slide38. Behavioral Market Efficiency The joint hypothesis: Market efficiency, asset pricing, and “smart beta”
The efficient market hypothesis cannot be tested on its own
Returns of small-capitalization and value stocks when measured by the CAPM might indicate that the market is not efficient
Or they might indicate that the CAPM is a faulty model of expected returns<br>
slide39. Behavioral Market Efficiency Smart beta strategies center on portfolios whose allocations do not correspond to market capitalizations
The proportion of a particular value stock might be 0.5% by market capitalization
But the proportion allocated to this value stock might be 2% in a smart beta portfolio
Are excess returns of smart beta strategies evidence that markets are not efficient?
Or are they reflections of faulty asset pricing models?<br>
slide40. Behavioral Market Efficiency Jennifer Bender of State Street Global Investors said:
“For smart beta, the end investor makes a decision to have exposure to certain factors…
This is very different from, say, a traditional quantitative manager who would use factors… to generate [market-beating] alpha…
[Q]uite a bit of active returns can be explained by very simple rules-based factor portfolios
And that does present a challenge to active investing overall!”<br>
slide41. Behavioral efficient markets What is the joint hypothesis?
You have the file “Factors-Students” from Chapter 10, and you calculated regressions of each of 4 mutual fund by the CAPM, 3-factor, and 5-factor asset pricing models. The “alpha” of each fund by each asset pricing model is its excess returns. (The estimated alpha of each fund by each asset pricing model is the intercept of the regression)
Look at the alphas of each fund by each of the asset pricing models. Are the alphas of each fund the same by the 3 models or are they different? What do the alphas tell us about market efficiency? How do they illustrate the joint hypothesis?<br>
slide42. Behavioral asset pricing Question
Excel file “factors-Students” includes monthly factor returns of 5 factors, market, small-large, value-growth, profitability, and investment. Factor returns are returns minus Treasury-bill returns that proxy for the risk free returns. It also includes monthly returns minus Treasury-bill returns of four mutual funds:
VISGX - Vanguard Small Capitalization Growth Index Fund
VISVX - Vanguard Small Capitalization Value Index Fund
VUVLX - Vanguard US Value
VIGRX - Vanguard Growth Index Fund<br>
slide43. Behavioral asset pricing<br>
slide44. Behavioral asset pricing Examine the returns minus Treasury-bill returns of each mutual fund by the CAPM, 3-factor model, and 5-factor model
What are the betas of each factor according to each model?
How do you interpret the betas?
Are the betas consistent with the names of the funds?
How are the betas similar or different across the 3 models?<br>
slide45. Behavioral asset pricing<br>
slide46. Behavioral asset pricing VISGX - Vanguard Small Capitalization Growth Index Fund<br>
slide47. Behavioral asset pricing VISGX is a small growth fund
Based on the CAPM (1-factor model) it has a market-factor beta of 1.23
So when the return of the stock market increases by 1 percentage point, the return of VISGX can be expected to increase by 1.23 percentage points<br>
slide48. Behavioral asset pricing VISGX - Vanguard Small Capitalization Growth Index Fund<br>
slide49. Behavioral asset pricing VISGX is a small growth fund
Based on the 3-factor model, it tilts toward small capitalization stocks and away from large capitalization stocks (Its Small-Large (SMB) beta is positive 0.78)
It tilts away from value stocks and toward growth stocks (Its Value-Growth (HML) beta is negative -0.25)<br>
slide50. Behavioral asset pricing VISGX - Vanguard Small Capitalization Growth Index Fund<br>
slide51. Behavioral asset pricing VISGX is a small growth fund
Based on the 5-factor model, it tilts away from stocks with robust profitability and stocks with conservative investment
Its RMW coefficient is negative -0.20, and its CMA coefficient is negative -0.25<br>