
For Information Finance Report October 2023 (Month
GB
Published · 21 slides · 0 views

1 / 1
Description
For Information Finance Report October 2023 (Month 7), FY24 Report to Board of Directors Executive Summary Income Statement Forecast Movement from Previous Month Forecast Risks Opportunities Capital Investment Programme Directorate
Related Topics
Share
Embed code
Download this presentation From Below
"For Information Finance Report October 2023 (Month" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
For Information
Finance Report
October 2023 (Month 7), FY24
Report to Board of Directors Executive Summary
Income Statement
Forecast Movement from Previous Month
Forecast Risks & Opportunities
Capital Investment Programme
Directorate Financial Performance Summary
Pay Trends
Agency Analysis
Non-Pay Expenditure analysis
Out of Area Placements
Cost Improvement Plan
Productivity Improvement Plan
Statement of Position
Cash-flow
Working Capital Indicators Contents A risk assessment has been undertaken around the legal issues that this paper presents and there are no issues that need to be referred to the Trust Solicitors. 1<br>
02
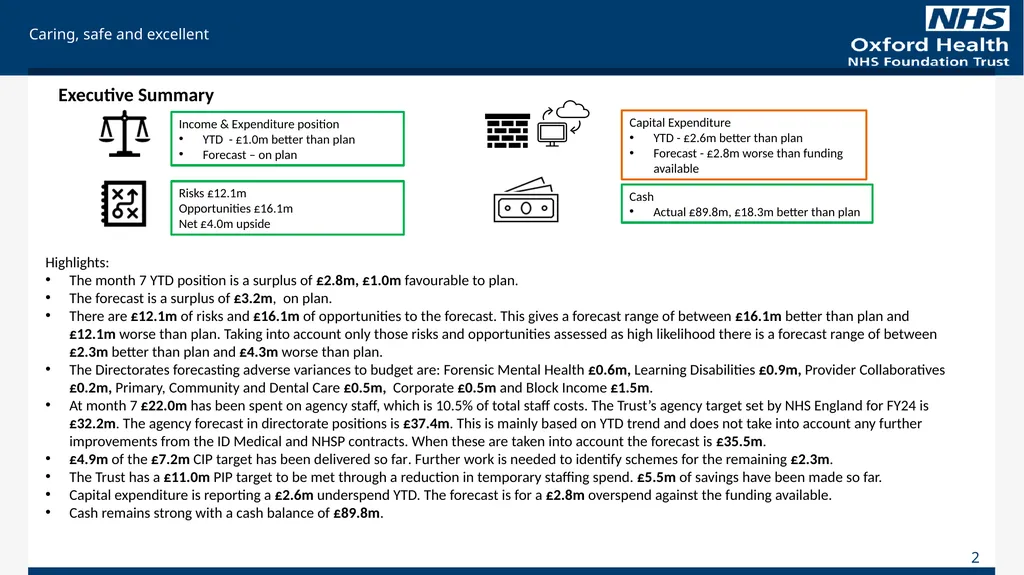
2 Executive Summary Highlights:
The month 7 YTD position is a surplus of £2.8m, £1.0m favourable to plan.
The forecast is a surplus of £3.2m, on plan.
There are £12.1m of risks and £16.1m of opportunities to the forecast. This gives a forecast range of between £16.1m better than plan and £12.1m worse than plan. Taking into account only those risks and opportunities assessed as high likelihood there is a forecast range of between £2.3m better than plan and £4.3m worse than plan.
The Directorates forecasting adverse variances to budget are: Forensic Mental Health £0.6m, Learning Disabilities £0.9m, Provider Collaboratives £0.2m, Primary, Community and Dental Care £0.5m, Corporate £0.5m and Block Income £1.5m.
At month 7 £22.0m has been spent on agency staff, which is 10.5% of total staff costs. The Trust’s agency target set by NHS England for FY24 is £32.2m. The agency forecast in directorate positions is £37.4m. This is mainly based on YTD trend and does not take into account any further improvements from the ID Medical and NHSP contracts. When these are taken into account the forecast is £35.5m.
£4.9m of the £7.2m CIP target has been delivered so far. Further work is needed to identify schemes for the remaining £2.3m.
The Trust has a £11.0m PIP target to be met through a reduction in temporary staffing spend. £5.5m of savings have been made so far.
Capital expenditure is reporting a £2.6m underspend YTD. The forecast is for a £2.8m overspend against the funding available.
Cash remains strong with a cash balance of £89.8m. Income & Expenditure position
YTD - £1.0m better than plan
Forecast – on plan Capital Expenditure
YTD - £2.6m better than plan
Forecast - £2.8m worse than funding available Cash
Actual £89.8m, £18.3m better than plan Risks £12.1m
Opportunities £16.1m
Net £4.0m upside<br>
03
Year-to-Date Performance
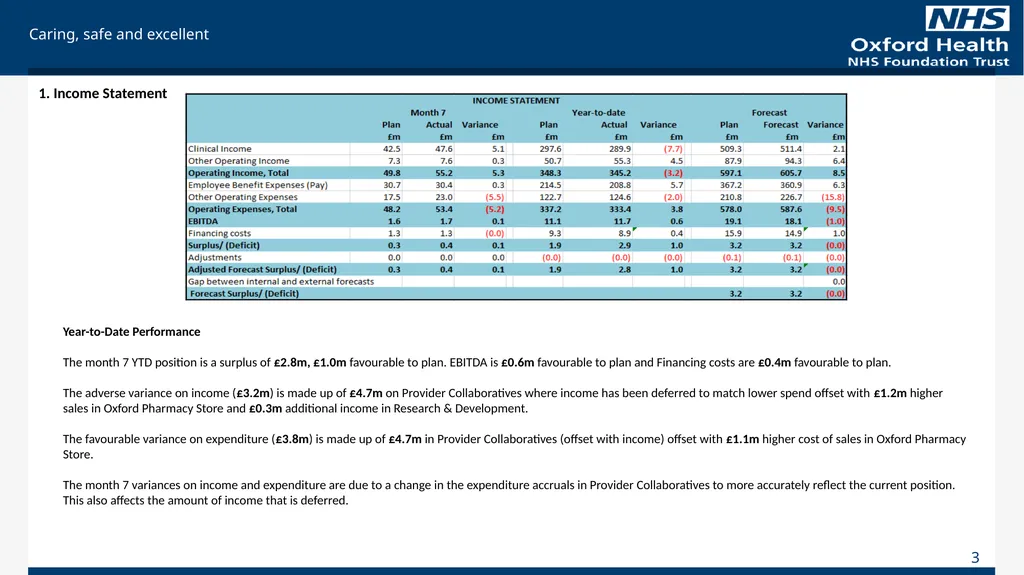
The month 7 YTD position is a surplus of £2.8m, £1.0m favourable to plan. EBITDA is £0.6m favourable to plan and Financing costs are £0.4m favourable to plan.
The adverse variance on income (£3.2m) is made up of £4.7m on Provider Collaboratives where income has been deferred to match lower spend offset with £1.2m higher sales in Oxford Pharmacy Store and £0.3m additional income in Research & Development.
The favourable variance on expenditure (£3.8m) is made up of £4.7m in Provider Collaboratives (offset with income) offset with £1.1m higher cost of sales in Oxford Pharmacy Store.
The month 7 variances on income and expenditure are due to a change in the expenditure accruals in Provider Collaboratives to more accurately reflect the current position. This also affects the amount of income that is deferred. 1. Income Statement 3<br>
04
4 2. Forecast movement from previous month<br>
05
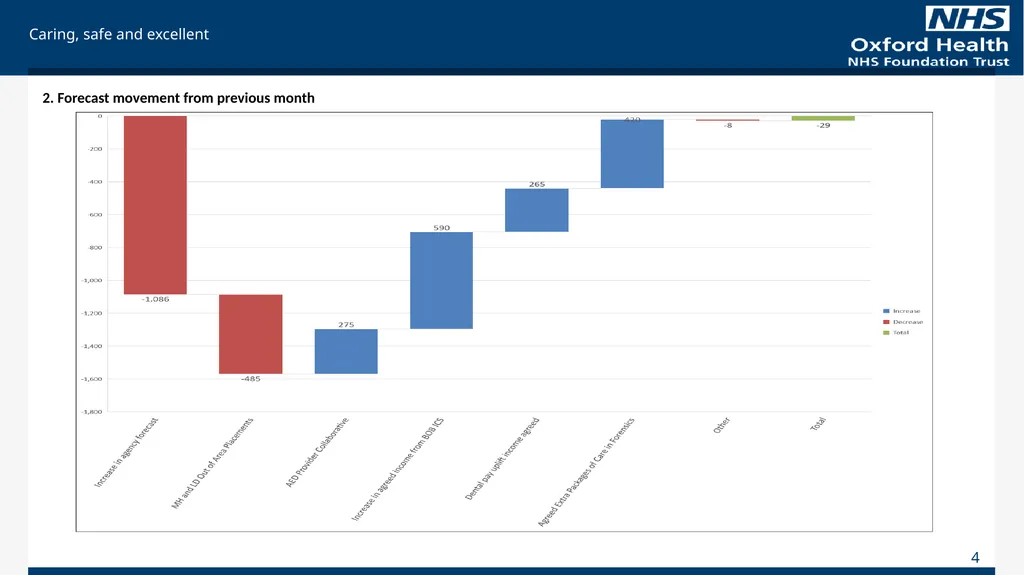
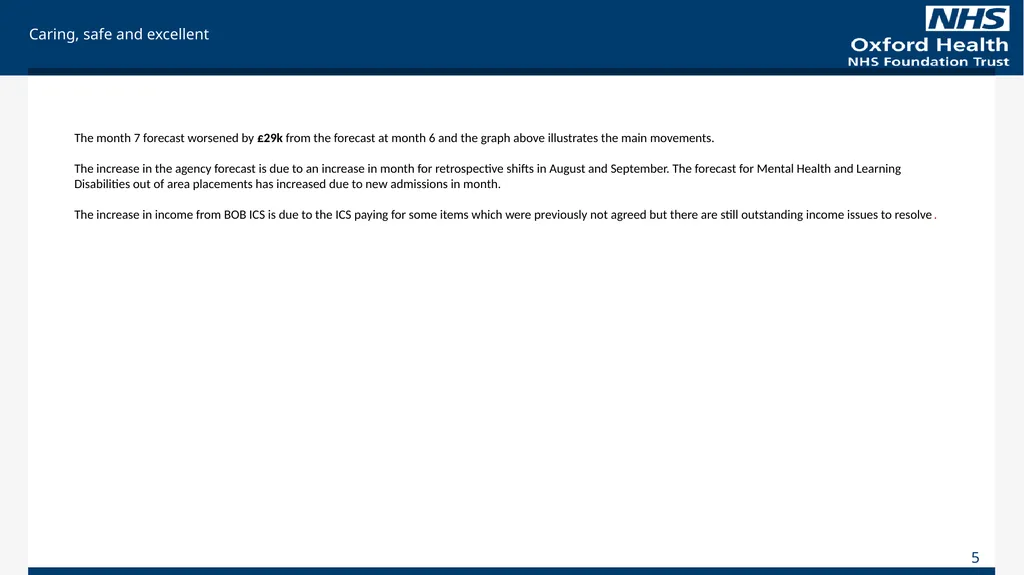
5 The month 7 forecast worsened by £29k from the forecast at month 6 and the graph above illustrates the main movements.
The increase in the agency forecast is due to an increase in month for retrospective shifts in August and September. The forecast for Mental Health and Learning Disabilities out of area placements has increased due to new admissions in month.
The increase in income from BOB ICS is due to the ICS paying for some items which were previously not agreed but there are still outstanding income issues to resolve.<br>
06
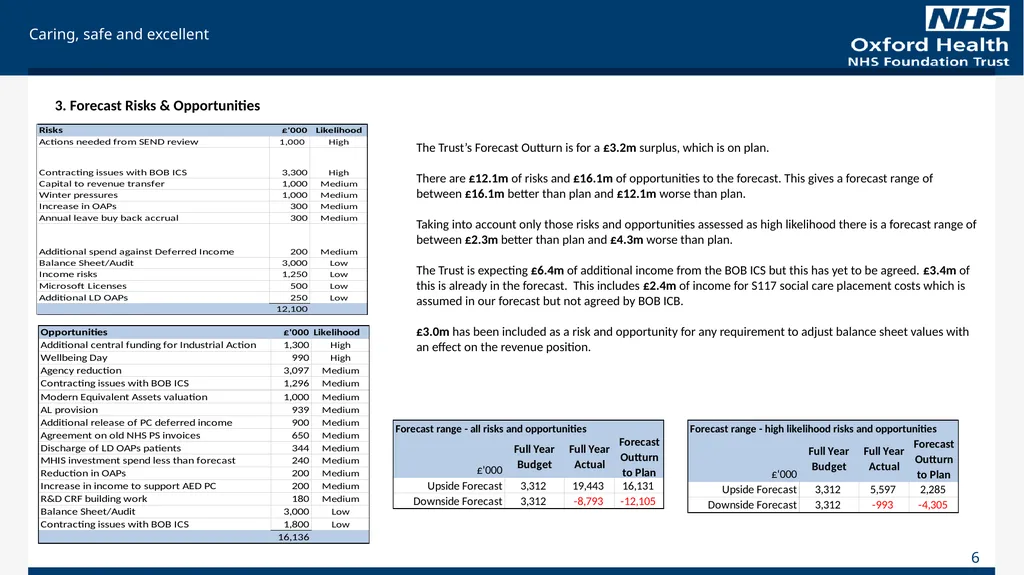
3. Forecast Risks & Opportunities The Trust’s Forecast Outturn is for a £3.2m surplus, which is on plan.
There are £12.1m of risks and £16.1m of opportunities to the forecast. This gives a forecast range of between £16.1m better than plan and £12.1m worse than plan.
Taking into account only those risks and opportunities assessed as high likelihood there is a forecast range of between £2.3m better than plan and £4.3m worse than plan.
The Trust is expecting £6.4m of additional income from the BOB ICS but this has yet to be agreed. £3.4m of this is already in the forecast. This includes £2.4m of income for S117 social care placement costs which is assumed in our forecast but not agreed by BOB ICB.
£3.0m has been included as a risk and opportunity for any requirement to adjust balance sheet values with an effect on the revenue position. 6<br>
07
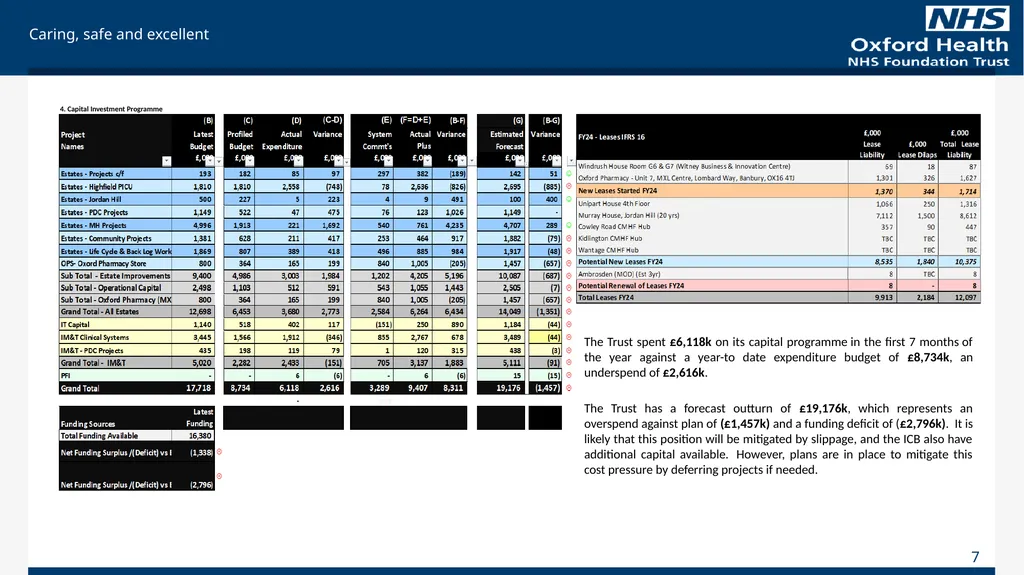
4. Capital Investment Programme The Trust spent £6,118k on its capital programme in the first 7 months of the year against a year-to date expenditure budget of £8,734k, an underspend of £2,616k.
The Trust has a forecast outturn of £19,176k, which represents an overspend against plan of (£1,457k) and a funding deficit of (£2,796k). It is likely that this position will be mitigated by slippage, and the ICB also have additional capital available. However, plans are in place to mitigate this cost pressure by deferring projects if needed. 7<br>
The Trust has a forecast outturn of £19,176k, which represents an overspend against plan of (£1,457k) and a funding deficit of (£2,796k). It is likely that this position will be mitigated by slippage, and the ICB also have additional capital available. However, plans are in place to mitigate this cost pressure by deferring projects if needed. 7<br>
08
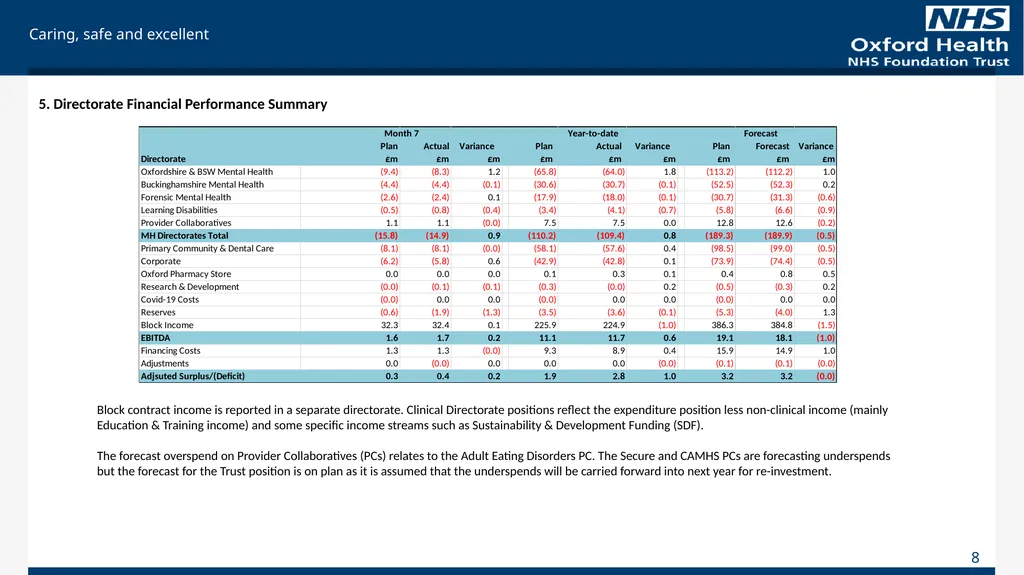
8 5. Directorate Financial Performance Summary Block contract income is reported in a separate directorate. Clinical Directorate positions reflect the expenditure position less non-clinical income (mainly Education & Training income) and some specific income streams such as Sustainability & Development Funding (SDF).
The forecast overspend on Provider Collaboratives (PCs) relates to the Adult Eating Disorders PC. The Secure and CAMHS PCs are forecasting underspends but the forecast for the Trust position is on plan as it is assumed that the underspends will be carried forward into next year for re-investment.<br>
The forecast overspend on Provider Collaboratives (PCs) relates to the Adult Eating Disorders PC. The Secure and CAMHS PCs are forecasting underspends but the forecast for the Trust position is on plan as it is assumed that the underspends will be carried forward into next year for re-investment.<br>
09
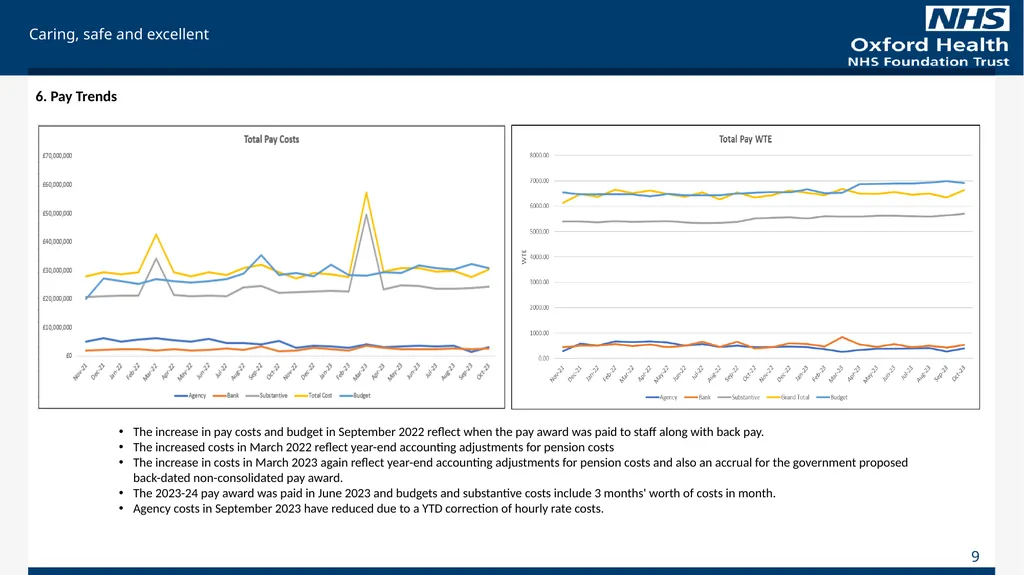
6. Pay Trends The increase in pay costs and budget in September 2022 reflect when the pay award was paid to staff along with back pay.
The increased costs in March 2022 reflect year-end accounting adjustments for pension costs
The increase in costs in March 2023 again reflect year-end accounting adjustments for pension costs and also an accrual for the government proposed back-dated non-consolidated pay award.
The 2023-24 pay award was paid in June 2023 and budgets and substantive costs include 3 months' worth of costs in month.
Agency costs in September 2023 have reduced due to a YTD correction of hourly rate costs. 9<br>
10
10<br>
11
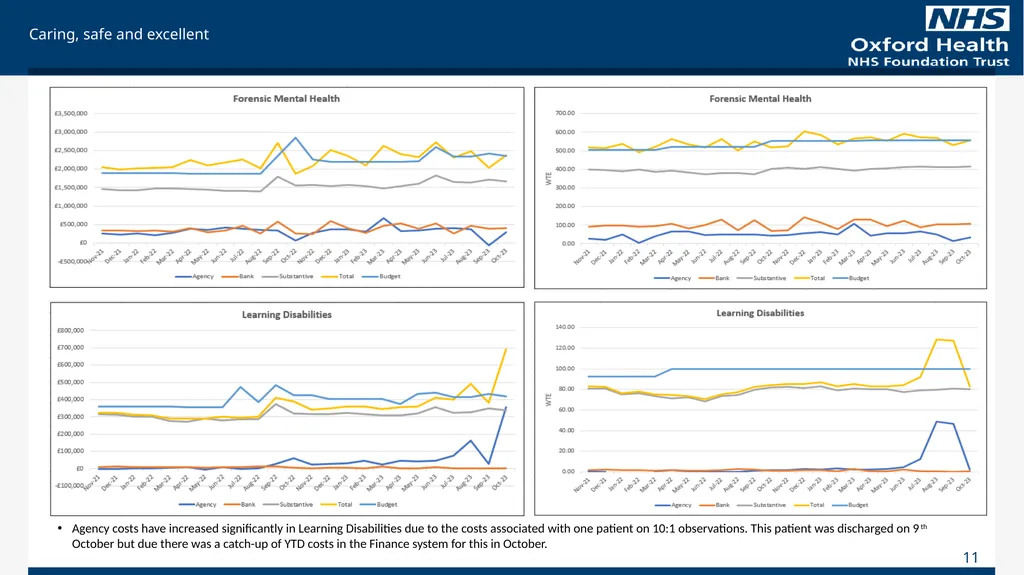
11 Agency costs have increased significantly in Learning Disabilities due to the costs associated with one patient on 10:1 observations. This patient was discharged on 9th October but due there was a catch-up of YTD costs in the Finance system for this in October.<br>
12
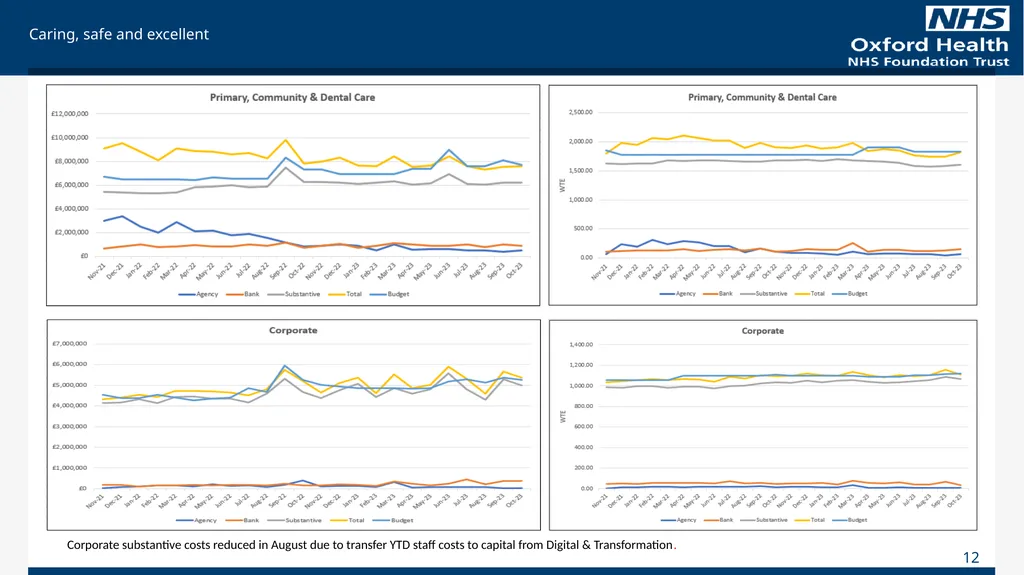
12 Corporate substantive costs reduced in August due to transfer YTD staff costs to capital from Digital & Transformation.<br>
13
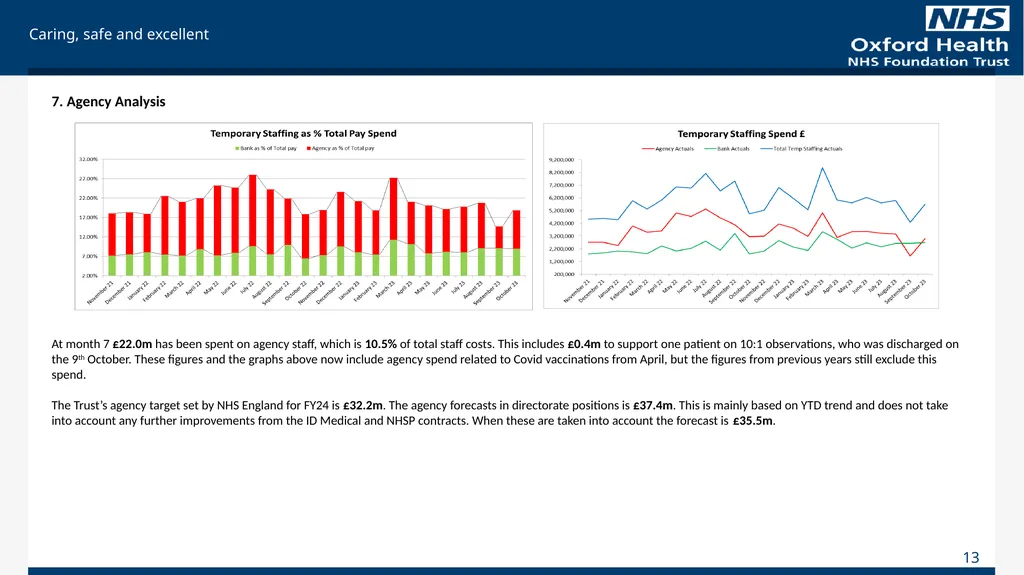
7. Agency Analysis At month 7 £22.0m has been spent on agency staff, which is 10.5% of total staff costs. This includes £0.4m to support one patient on 10:1 observations, who was discharged on the 9th October. These figures and the graphs above now include agency spend related to Covid vaccinations from April, but the figures from previous years still exclude this spend.
The Trust’s agency target set by NHS England for FY24 is £32.2m. The agency forecasts in directorate positions is £37.4m. This is mainly based on YTD trend and does not take into account any further improvements from the ID Medical and NHSP contracts. When these are taken into account the forecast is £35.5m. 13<br>
The Trust’s agency target set by NHS England for FY24 is £32.2m. The agency forecasts in directorate positions is £37.4m. This is mainly based on YTD trend and does not take into account any further improvements from the ID Medical and NHSP contracts. When these are taken into account the forecast is £35.5m. 13<br>
14
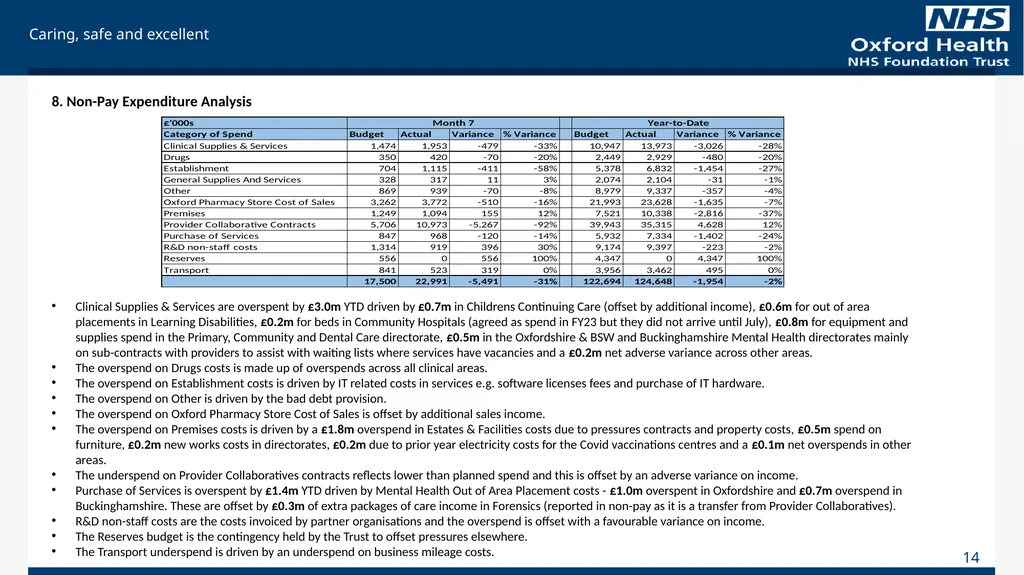
14 8. Non-Pay Expenditure Analysis Clinical Supplies & Services are overspent by £3.0m YTD driven by £0.7m in Childrens Continuing Care (offset by additional income), £0.6m for out of area placements in Learning Disabilities, £0.2m for beds in Community Hospitals (agreed as spend in FY23 but they did not arrive until July), £0.8m for equipment and supplies spend in the Primary, Community and Dental Care directorate, £0.5m in the Oxfordshire & BSW and Buckinghamshire Mental Health directorates mainly on sub-contracts with providers to assist with waiting lists where services have vacancies and a £0.2m net adverse variance across other areas.
The overspend on Drugs costs is made up of overspends across all clinical areas.
The overspend on Establishment costs is driven by IT related costs in services e.g. software licenses fees and purchase of IT hardware.
The overspend on Other is driven by the bad debt provision.
The overspend on Oxford Pharmacy Store Cost of Sales is offset by additional sales income.
The overspend on Premises costs is driven by a £1.8m overspend in Estates & Facilities costs due to pressures contracts and property costs, £0.5m spend on furniture, £0.2m new works costs in directorates, £0.2m due to prior year electricity costs for the Covid vaccinations centres and a £0.1m net overspends in other areas.
The underspend on Provider Collaboratives contracts reflects lower than planned spend and this is offset by an adverse variance on income.
Purchase of Services is overspent by £1.4m YTD driven by Mental Health Out of Area Placement costs - £1.0m overspent in Oxfordshire and £0.7m overspend in Buckinghamshire. These are offset by £0.3m of extra packages of care income in Forensics (reported in non-pay as it is a transfer from Provider Collaboratives).
R&D non-staff costs are the costs invoiced by partner organisations and the overspend is offset with a favourable variance on income.
The Reserves budget is the contingency held by the Trust to offset pressures elsewhere.
The Transport underspend is driven by an underspend on business mileage costs.<br>
15
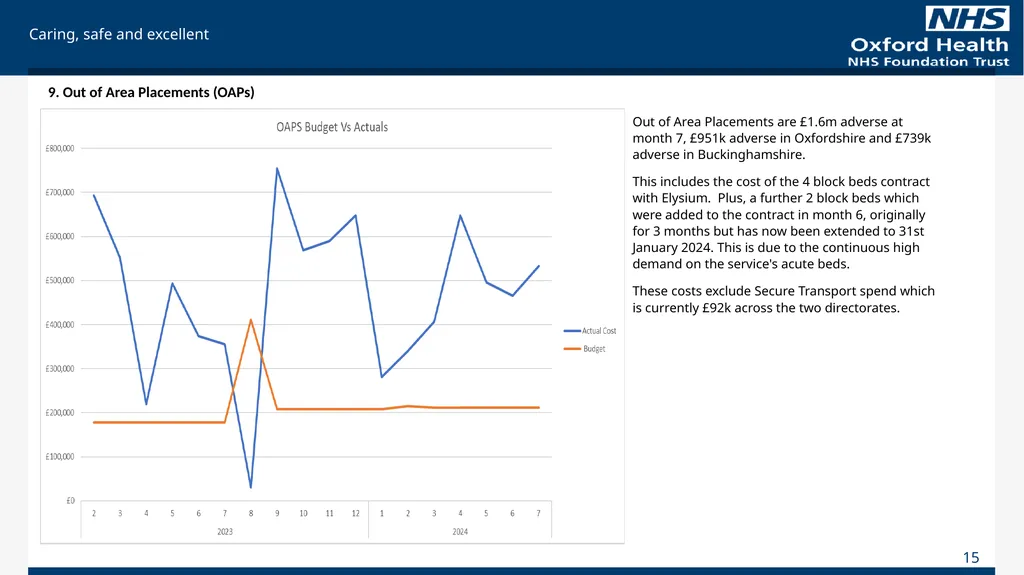
9. Out of Area Placements (OAPs) Out of Area Placements are £1.6m adverse at month 7, £951k adverse in Oxfordshire and £739k adverse in Buckinghamshire.
This includes the cost of the 4 block beds contract with Elysium. Plus, a further 2 block beds which were added to the contract in month 6, originally for 3 months but has now been extended to 31st January 2024. This is due to the continuous high demand on the service's acute beds.
These costs exclude Secure Transport spend which is currently £92k across the two directorates. 15<br>
16
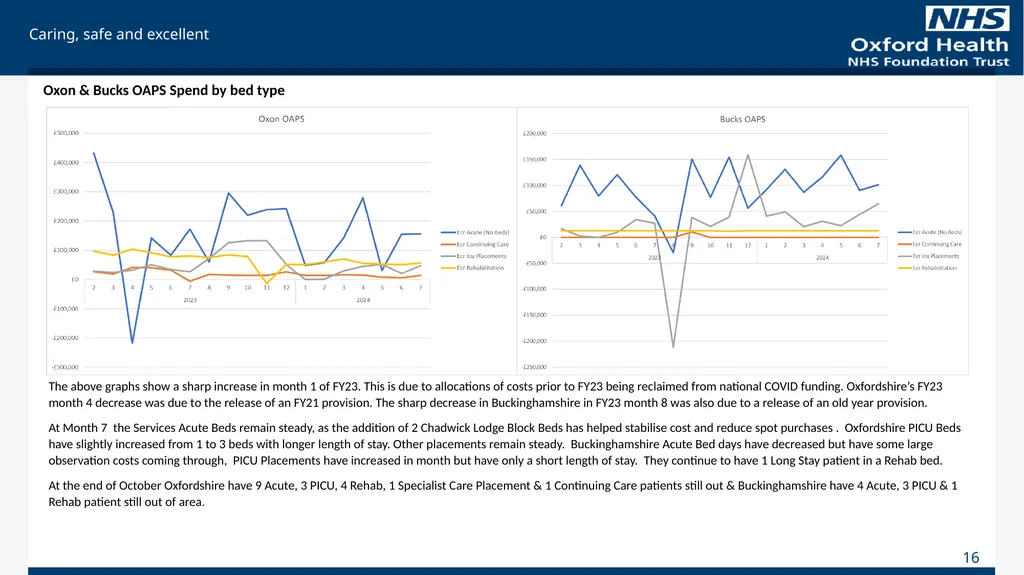
Oxon & Bucks OAPS Spend by bed type The above graphs show a sharp increase in month 1 of FY23. This is due to allocations of costs prior to FY23 being reclaimed from national COVID funding. Oxfordshire’s FY23 month 4 decrease was due to the release of an FY21 provision. The sharp decrease in Buckinghamshire in FY23 month 8 was also due to a release of an old year provision.
At Month 7 the Services Acute Beds remain steady, as the addition of 2 Chadwick Lodge Block Beds has helped stabilise cost and reduce spot purchases . Oxfordshire PICU Beds have slightly increased from 1 to 3 beds with longer length of stay. Other placements remain steady. Buckinghamshire Acute Bed days have decreased but have some large observation costs coming through, PICU Placements have increased in month but have only a short length of stay. They continue to have 1 Long Stay patient in a Rehab bed.
At the end of October Oxfordshire have 9 Acute, 3 PICU, 4 Rehab, 1 Specialist Care Placement & 1 Continuing Care patients still out & Buckinghamshire have 4 Acute, 3 PICU & 1 Rehab patient still out of area. 16<br>
17
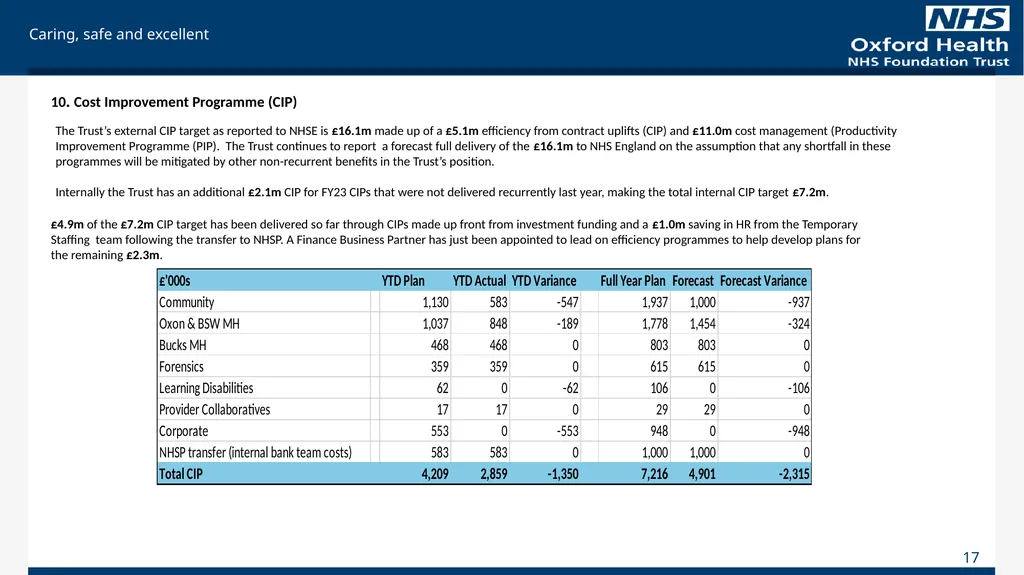
10. Cost Improvement Programme (CIP) 17 The Trust’s external CIP target as reported to NHSE is £16.1m made up of a £5.1m efficiency from contract uplifts (CIP) and £11.0m cost management (Productivity Improvement Programme (PIP). The Trust continues to report a forecast full delivery of the £16.1m to NHS England on the assumption that any shortfall in these programmes will be mitigated by other non-recurrent benefits in the Trust’s position.
Internally the Trust has an additional £2.1m CIP for FY23 CIPs that were not delivered recurrently last year, making the total internal CIP target £7.2m. £4.9m of the £7.2m CIP target has been delivered so far through CIPs made up front from investment funding and a £1.0m saving in HR from the Temporary Staffing team following the transfer to NHSP. A Finance Business Partner has just been appointed to lead on efficiency programmes to help develop plans for the remaining £2.3m.<br>
Internally the Trust has an additional £2.1m CIP for FY23 CIPs that were not delivered recurrently last year, making the total internal CIP target £7.2m. £4.9m of the £7.2m CIP target has been delivered so far through CIPs made up front from investment funding and a £1.0m saving in HR from the Temporary Staffing team following the transfer to NHSP. A Finance Business Partner has just been appointed to lead on efficiency programmes to help develop plans for the remaining £2.3m.<br>
18
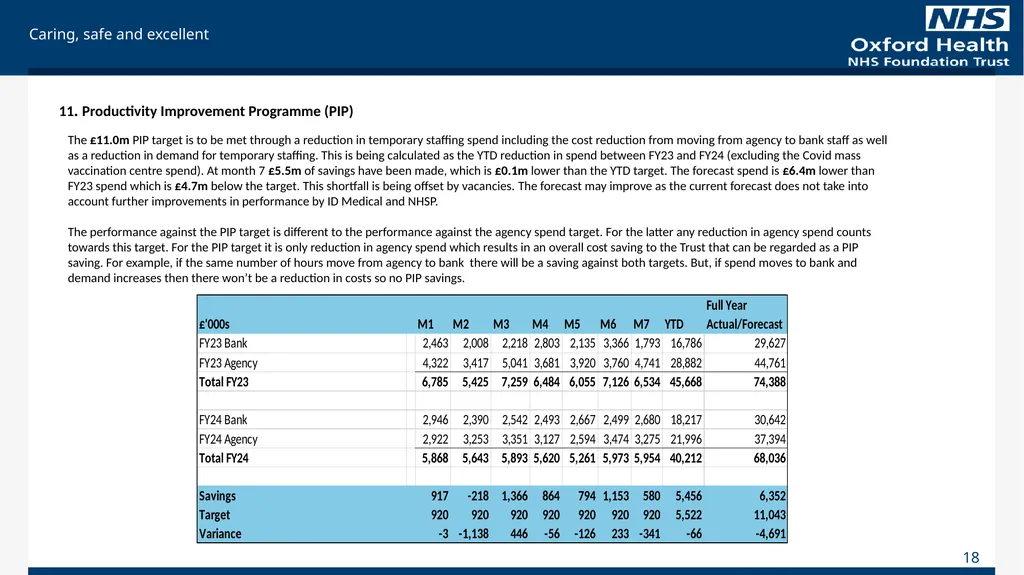
18 11. Productivity Improvement Programme (PIP) The £11.0m PIP target is to be met through a reduction in temporary staffing spend including the cost reduction from moving from agency to bank staff as well as a reduction in demand for temporary staffing. This is being calculated as the YTD reduction in spend between FY23 and FY24 (excluding the Covid mass vaccination centre spend). At month 7 £5.5m of savings have been made, which is £0.1m lower than the YTD target. The forecast spend is £6.4m lower than FY23 spend which is £4.7m below the target. This shortfall is being offset by vacancies. The forecast may improve as the current forecast does not take into account further improvements in performance by ID Medical and NHSP.
The performance against the PIP target is different to the performance against the agency spend target. For the latter any reduction in agency spend counts towards this target. For the PIP target it is only reduction in agency spend which results in an overall cost saving to the Trust that can be regarded as a PIP saving. For example, if the same number of hours move from agency to bank there will be a saving against both targets. But, if spend moves to bank and demand increases then there won’t be a reduction in costs so no PIP savings.<br>
The performance against the PIP target is different to the performance against the agency spend target. For the latter any reduction in agency spend counts towards this target. For the PIP target it is only reduction in agency spend which results in an overall cost saving to the Trust that can be regarded as a PIP saving. For example, if the same number of hours move from agency to bank there will be a saving against both targets. But, if spend moves to bank and demand increases then there won’t be a reduction in costs so no PIP savings.<br>
19
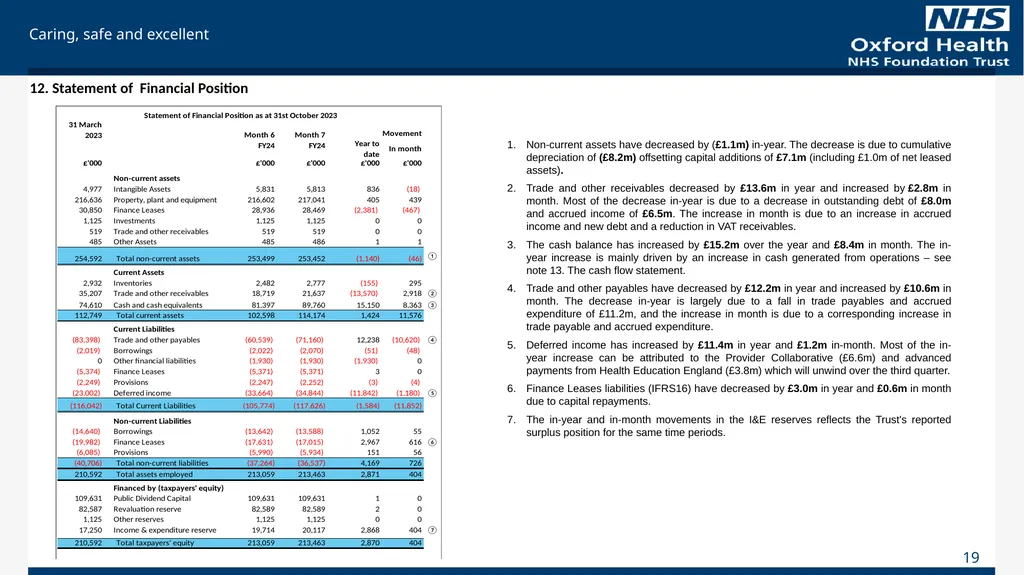
12. Statement of Financial Position Non-current assets have decreased by (£1.1m) in-year. The decrease is due to cumulative depreciation of (£8.2m) offsetting capital additions of £7.1m (including £1.0m of net leased assets).
Trade and other receivables decreased by £13.6m in year and increased by £2.8m in month. Most of the decrease in-year is due to a decrease in outstanding debt of £8.0m and accrued income of £6.5m. The increase in month is due to an increase in accrued income and new debt and a reduction in VAT receivables.
The cash balance has increased by £15.2m over the year and £8.4m in month. The in-year increase is mainly driven by an increase in cash generated from operations – see note 13. The cash flow statement.
Trade and other payables have decreased by £12.2m in year and increased by £10.6m in month. The decrease in-year is largely due to a fall in trade payables and accrued expenditure of £11.2m, and the increase in month is due to a corresponding increase in trade payable and accrued expenditure.
Deferred income has increased by £11.4m in year and £1.2m in-month. Most of the in-year increase can be attributed to the Provider Collaborative (£6.6m) and advanced payments from Health Education England (£3.8m) which will unwind over the third quarter.
Finance Leases liabilities (IFRS16) have decreased by £3.0m in year and £0.6m in month due to capital repayments.
The in-year and in-month movements in the I&E reserves reflects the Trust's reported surplus position for the same time periods. 19<br>
20
13. Cash Flow Summary Notes
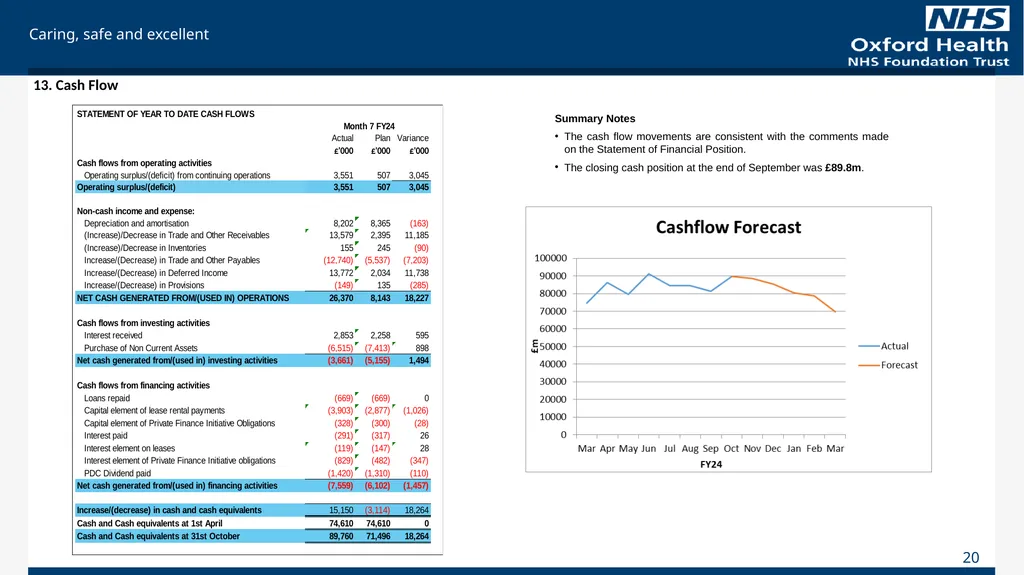
The cash flow movements are consistent with the comments made on the Statement of Financial Position.
The closing cash position at the end of September was £89.8m. 20<br>
The cash flow movements are consistent with the comments made on the Statement of Financial Position.
The closing cash position at the end of September was £89.8m. 20<br>
21
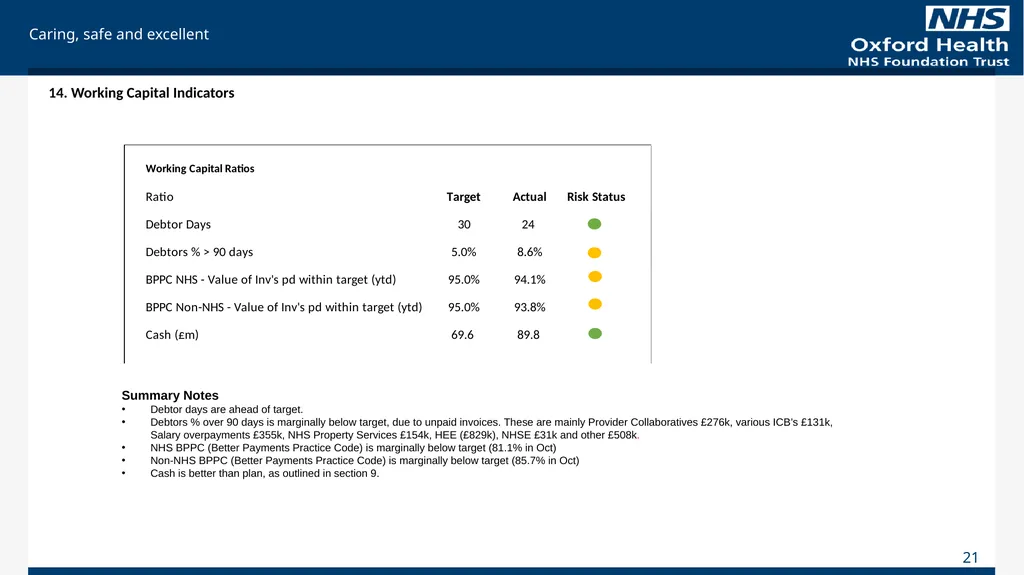
14. Working Capital Indicators Summary Notes
Debtor days are ahead of target.
Debtors % over 90 days is marginally below target, due to unpaid invoices. These are mainly Provider Collaboratives £276k, various ICB’s £131k, Salary overpayments £355k, NHS Property Services £154k, HEE (£829k), NHSE £31k and other £508k.
NHS BPPC (Better Payments Practice Code) is marginally below target (81.1% in Oct)
Non-NHS BPPC (Better Payments Practice Code) is marginally below target (85.7% in Oct)
Cash is better than plan, as outlined in section 9. 21<br>