
“Fragility, Taxation and Development: Reflections
Description: Fragility, Taxation and Development: Reflections from Liberia Dec 7-8, 2022 Sierra Leone Tax for Development Conference. The Radisson Blu, Freetown Jimmy suah Shilue Strengthening Fragile States Through Taxation (FRAGTAX) In Partnership
Related Topics
Download Presentation
"“Fragility, Taxation and Development: Reflections" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. “Fragility, Taxation and Development: Reflections from Liberia”
Dec 7-8, 2022
Sierra Leone Tax for Development Conference.
The Radisson Blu, Freetown
Jimmy suah Shilue Strengthening Fragile States Through Taxation (FRAGTAX)
In Partnership with: NUPI & CMI<br>
slide2. PRESENTATION CONTENTS OVERVIEW OF THE ASSIGNMENT
Brief Background
OVERVIEW OF DOMESTICE RESOURCE MOBILIZATION IN LIBERIA
APPROACH (METHODOLOGY)
FINDINGS
CONCLUSION/OBSERVATION
RECOMMENDATIONS<br>
slide3. OVERVIEW OF THE Study Gauge the perception of citizens in selected districts of Margibi County and parts of Montserrado on tax compliance issues, particularly real estate tax.
To help enhance understanding of citizens’ perceptions of tax collection in Liberia
Generate formative data that the Norwegian Institute for International Affairs (NUPI) can use to shape its ideas in anticipation of a forthcoming national study on taxation, particularly citizens’ compliance in fragile states.<br>
slide4. At the interception of domestic resource mobilization in Liberia, lies citizens’ demand for the provision of basic social services, adequate social safety net and wealth redistribution. Why a paradigm shift?<br>
slide5. OVERVIEW OF DOMESTIC RESOURCE MOBILIZATION IN LIBERIA For decades, Liberia relied heavily on Natural Resource (NR) exploitation as major source of revenue generation. The resultant effects of this have led to major spending deficits, which the government has filled by borrowing from the Central Bank, tapping into its reserves, and relying on foreign loans and aid.
The Government of Liberia (GoL) has taken measures to diversify and expand its tax base, minimize revenue loss and ensure adequate and predictable multiyear financing of national development plan, the Pro-Poor Agenda for Prosperity and Development (PAPD).
Beginning in 2012, key reform measures were taken by the Government. BY 2013, GoL removed the responsibility of revenue collection from the Ministry of Finance and established the Liberia Revenue Authority (LRA) in 2013.
While these efforts remain laudable, challenges remain, in large part inextricably linked to structural weaknesses, particularly in the governance structure, limited institutional capacity, transparency and accountability, etc.
Without a realistic decentralization plan and stable domestic revenue base, these services and aspirations become difficult to effectively achieve<br>
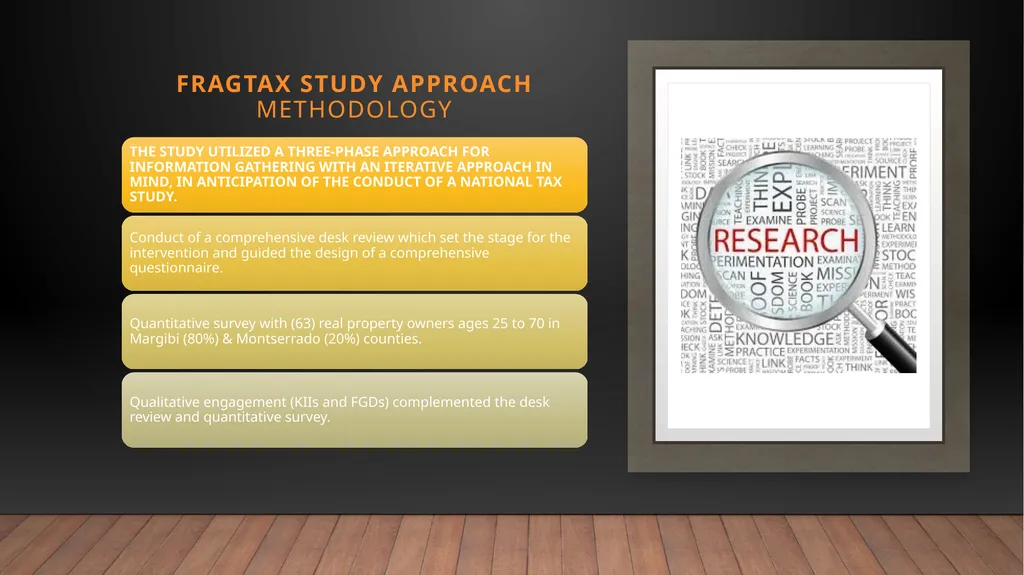
slide6. FRAGTAX STUDY APPROACH Methodology<br>
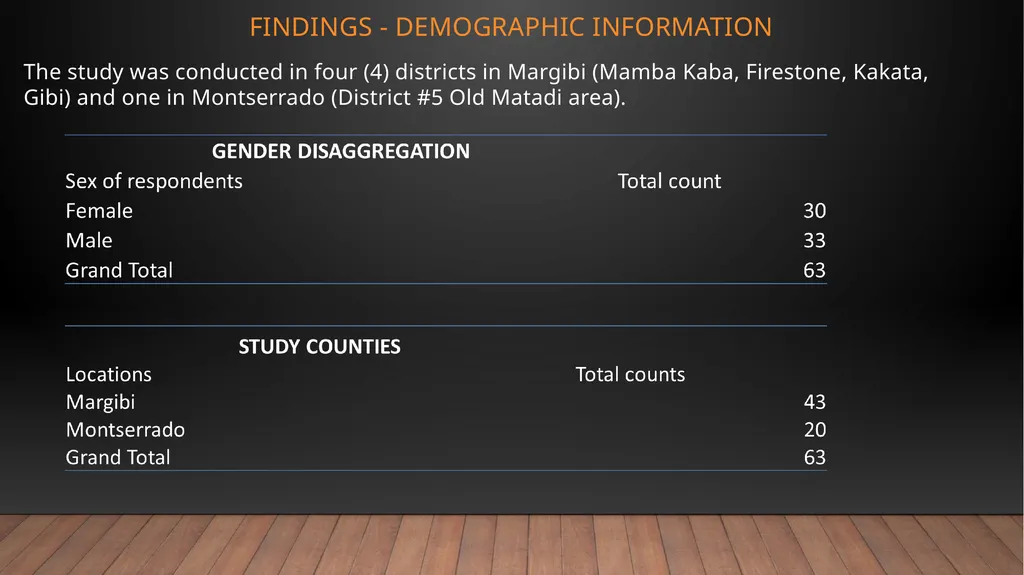
slide7. FINDINGS - Demographic information The study was conducted in four (4) districts in Margibi (Mamba Kaba, Firestone, Kakata, Gibi) and one in Montserrado (District #5 Old Matadi area).<br>
slide8. FINDINGS- Property Ownership All one hundred-sixteen (116) respondents who participated in the study said they own various undeveloped lands and residential properties, with a few saying they own commercial properties.
On average, property values ranged between $2,500- $5,000 USD. However, 9 out of every 10 respondents admittedly declared that the stated values of their properties were based on individual self-declarations.
Observation showed that there is ineffective assessment of properties, which is resulting in under/over-estimation of registered properties.
Gender dimension to property ownership was key. There is certain ambiguity within Liberia’s Land Right’s law that could potentially undermine women’s ability to become ‘real property owner’ and tax compliance. For example, land inheritance by widows is often contingent on women willingness to marry a surviving male relative of their deceased husband. “Individual self-declaration of real property values is admissible by LRA because the agency is challenged by limited institutional capacity to effectively conduct comprehensive property valuations across the country.”
–LRA Official<br>
slide9. FINDINGS- Property Ownership (con’t) Men more forthcoming in responding to questions on property acquisition and ownership than female respondents. For instance, when the question “Do you own properties and which types” was asked, varied responses were received from both the male and female respondents. In most focus group discussions, it was observed that most property owners are men.
Centralized system concentrates power and authority in Monrovia and reduces incentives for citizens outside of Monrovia to benefit from social services and comply with tax payment; “I don’t think the superintendents got power and will ever get power to make any decisions on how property taxes should be used.”<br>
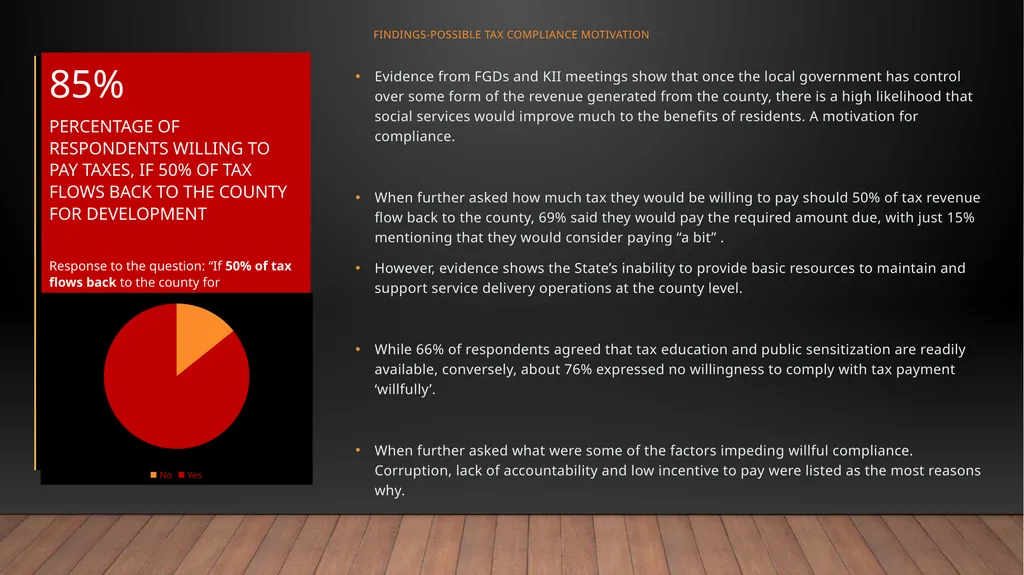
slide10. FINDINGS-Possible tax compliance motivation Evidence from FGDs and KII meetings show that once the local government has control over some form of the revenue generated from the county, there is a high likelihood that social services would improve much to the benefits of residents. A motivation for compliance.
When further asked how much tax they would be willing to pay should 50% of tax revenue flow back to the county, 69% said they would pay the required amount due, with just 15% mentioning that they would consider paying “a bit” .
However, evidence shows the State’s inability to provide basic resources to maintain and support service delivery operations at the county level.
While 66% of respondents agreed that tax education and public sensitization are readily available, conversely, about 76% expressed no willingness to comply with tax payment ‘willfully’.
When further asked what were some of the factors impeding willful compliance. Corruption, lack of accountability and low incentive to pay were listed as the most reasons why.<br>
slide11. FINDINGS-Centralization/Elite Capture Respondents provided that the centralized system concentrates power and authority in Monrovia and reduced incentives for citizens outside of Monrovia to benefit from social services and comply with tax payment.
Governance system is more centralized and needs to be decentralized for easy access to basic services for example, birth certificate , marriage certificate, drivers; license, etc.
Emphasizing centralization, a female respondent was emphatic when she said…
-“what do you call governance system! Nothing is being done here in respect to county development funds, except for what individual lawmakers carry out as development.”
Administrators of hospitals and schools look up to decisions from Monrovia (central level) to run public institutions leading to inefficiencies in public service delivery.<br>
slide12. FINDINGS-50/50 revenue sharing pilot The 50-50 revenue sharing pilot is two-fold:
1st, it focuses on establishing a revenue sharing partnership agreement between the central government and the local government of Margibi county,
2nd it focuses on training county officials to eventually carry out real property tax registration and collection
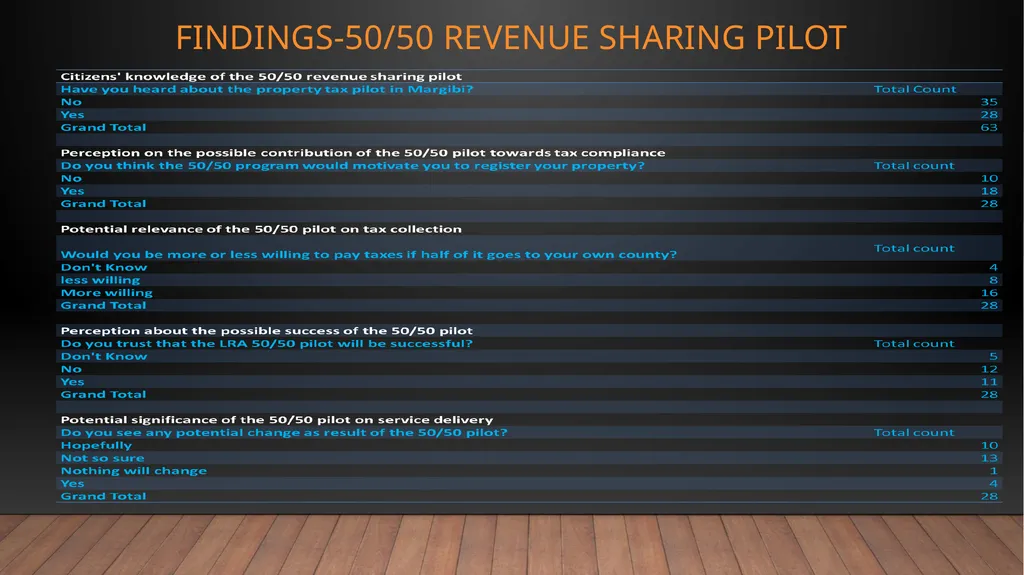
44% of respondents reported to have heard of the pilot and could articulate what it is designed to achieve. However, when further asked if a success of the pilot would encourage tax compliance, 65% (N=28) said yes, while 35% (N=28) said no.<br>
slide13. The findings revealed, that current income generation streams may likely not facilitate a progressive tax regime and is likely to create challenges that might perpetuate non-compliance.
The study also observed that collecting real property tax in Liberia has been a difficult task for the Government because of lack of comprehensive database on property locations, ownership and values<br>
slide14. FINDINGS-50/50 revenue sharing pilot<br>
slide15. Observations & CONCLUSIONs Local, state-led incentives (i.e. the provision of basic social services, inclusion adequate public schools, health facilities, electricity, etc.) to drive compliance does not exist and there is persistent accusation of corrupt practices by tax collectors.
Payment on property tax outside of Monrovia are mostly non-existent, with few citizens obliging/ complying to pay only if it has a direct personal benefit to them.
Demonstrable evidence shows the state inability to provide basic resources to maintain and support service delivery functions at the county level influence Citizens trust , thoughts and perceptions of GoL..
Generally, the respondents concurred that tax awareness has been created mainly because of thee 50/50 pilot in Margibi.<br>
slide16. CON’t Outside of income tax, respondents concurred that property or real estate tax payment is uncommon in their communities.
Perceived acts of corruption by civil servants, as well as inadequate social service are driving up citizens’ unwilling to pay taxes.
There was consensus amongst respondents that the centralize system concentrate power and authority in Monrovia and reduced incentives for citizens outside of Monrovia to benefit from social services and comply with tax payment.
Hope and optimism remain high insofar as the 50/50 revenue sharing pilot is concern. However, skepticism remain high that the deal/pilot is highly likely not going to work because of fear of elite capture and corruption.<br>
slide17. recommendations GoL to consider one-stop digitize tax payment locations at the county level for the public to avoid physical human interaction for tax collection. Also, mobile money could be an alternative model for local communities.
As of 2020, Liberia had a population of 5.05 million, 49.7 percent being female, and 50.3 percent being male. Despite women constituting 49% of the population, development indices are negative for women compared to men. A need to review and consider the ambiguity in the inheritance law that tends to undermine women, especially those in customary relationship rights to fully gain property ownership.
Efficiency in tax collection should go beyond radio awareness and one-off outreach engagements. Establishing mutual trust by utilizing revenue generated to provide adequate social services is critical and is likely to contribute to increasing citizens’ willingness to pay taxes.
The devolution of power and authority is essential and is likely to contribute to tax collection. This would require political will and commitment and should include fiscal decentralization to ensure local authorities are able to provide, manage and maintain services essential to local citizens.<br>
slide18. Thank you Q&As<br>
Dec 7-8, 2022
Sierra Leone Tax for Development Conference.
The Radisson Blu, Freetown
Jimmy suah Shilue Strengthening Fragile States Through Taxation (FRAGTAX)
In Partnership with: NUPI & CMI<br>
slide2. PRESENTATION CONTENTS OVERVIEW OF THE ASSIGNMENT
Brief Background
OVERVIEW OF DOMESTICE RESOURCE MOBILIZATION IN LIBERIA
APPROACH (METHODOLOGY)
FINDINGS
CONCLUSION/OBSERVATION
RECOMMENDATIONS<br>
slide3. OVERVIEW OF THE Study Gauge the perception of citizens in selected districts of Margibi County and parts of Montserrado on tax compliance issues, particularly real estate tax.
To help enhance understanding of citizens’ perceptions of tax collection in Liberia
Generate formative data that the Norwegian Institute for International Affairs (NUPI) can use to shape its ideas in anticipation of a forthcoming national study on taxation, particularly citizens’ compliance in fragile states.<br>
slide4. At the interception of domestic resource mobilization in Liberia, lies citizens’ demand for the provision of basic social services, adequate social safety net and wealth redistribution. Why a paradigm shift?<br>
slide5. OVERVIEW OF DOMESTIC RESOURCE MOBILIZATION IN LIBERIA For decades, Liberia relied heavily on Natural Resource (NR) exploitation as major source of revenue generation. The resultant effects of this have led to major spending deficits, which the government has filled by borrowing from the Central Bank, tapping into its reserves, and relying on foreign loans and aid.
The Government of Liberia (GoL) has taken measures to diversify and expand its tax base, minimize revenue loss and ensure adequate and predictable multiyear financing of national development plan, the Pro-Poor Agenda for Prosperity and Development (PAPD).
Beginning in 2012, key reform measures were taken by the Government. BY 2013, GoL removed the responsibility of revenue collection from the Ministry of Finance and established the Liberia Revenue Authority (LRA) in 2013.
While these efforts remain laudable, challenges remain, in large part inextricably linked to structural weaknesses, particularly in the governance structure, limited institutional capacity, transparency and accountability, etc.
Without a realistic decentralization plan and stable domestic revenue base, these services and aspirations become difficult to effectively achieve<br>
slide6. FRAGTAX STUDY APPROACH Methodology<br>
slide7. FINDINGS - Demographic information The study was conducted in four (4) districts in Margibi (Mamba Kaba, Firestone, Kakata, Gibi) and one in Montserrado (District #5 Old Matadi area).<br>
slide8. FINDINGS- Property Ownership All one hundred-sixteen (116) respondents who participated in the study said they own various undeveloped lands and residential properties, with a few saying they own commercial properties.
On average, property values ranged between $2,500- $5,000 USD. However, 9 out of every 10 respondents admittedly declared that the stated values of their properties were based on individual self-declarations.
Observation showed that there is ineffective assessment of properties, which is resulting in under/over-estimation of registered properties.
Gender dimension to property ownership was key. There is certain ambiguity within Liberia’s Land Right’s law that could potentially undermine women’s ability to become ‘real property owner’ and tax compliance. For example, land inheritance by widows is often contingent on women willingness to marry a surviving male relative of their deceased husband. “Individual self-declaration of real property values is admissible by LRA because the agency is challenged by limited institutional capacity to effectively conduct comprehensive property valuations across the country.”
–LRA Official<br>
slide9. FINDINGS- Property Ownership (con’t) Men more forthcoming in responding to questions on property acquisition and ownership than female respondents. For instance, when the question “Do you own properties and which types” was asked, varied responses were received from both the male and female respondents. In most focus group discussions, it was observed that most property owners are men.
Centralized system concentrates power and authority in Monrovia and reduces incentives for citizens outside of Monrovia to benefit from social services and comply with tax payment; “I don’t think the superintendents got power and will ever get power to make any decisions on how property taxes should be used.”<br>
slide10. FINDINGS-Possible tax compliance motivation Evidence from FGDs and KII meetings show that once the local government has control over some form of the revenue generated from the county, there is a high likelihood that social services would improve much to the benefits of residents. A motivation for compliance.
When further asked how much tax they would be willing to pay should 50% of tax revenue flow back to the county, 69% said they would pay the required amount due, with just 15% mentioning that they would consider paying “a bit” .
However, evidence shows the State’s inability to provide basic resources to maintain and support service delivery operations at the county level.
While 66% of respondents agreed that tax education and public sensitization are readily available, conversely, about 76% expressed no willingness to comply with tax payment ‘willfully’.
When further asked what were some of the factors impeding willful compliance. Corruption, lack of accountability and low incentive to pay were listed as the most reasons why.<br>
slide11. FINDINGS-Centralization/Elite Capture Respondents provided that the centralized system concentrates power and authority in Monrovia and reduced incentives for citizens outside of Monrovia to benefit from social services and comply with tax payment.
Governance system is more centralized and needs to be decentralized for easy access to basic services for example, birth certificate , marriage certificate, drivers; license, etc.
Emphasizing centralization, a female respondent was emphatic when she said…
-“what do you call governance system! Nothing is being done here in respect to county development funds, except for what individual lawmakers carry out as development.”
Administrators of hospitals and schools look up to decisions from Monrovia (central level) to run public institutions leading to inefficiencies in public service delivery.<br>
slide12. FINDINGS-50/50 revenue sharing pilot The 50-50 revenue sharing pilot is two-fold:
1st, it focuses on establishing a revenue sharing partnership agreement between the central government and the local government of Margibi county,
2nd it focuses on training county officials to eventually carry out real property tax registration and collection
44% of respondents reported to have heard of the pilot and could articulate what it is designed to achieve. However, when further asked if a success of the pilot would encourage tax compliance, 65% (N=28) said yes, while 35% (N=28) said no.<br>
slide13. The findings revealed, that current income generation streams may likely not facilitate a progressive tax regime and is likely to create challenges that might perpetuate non-compliance.
The study also observed that collecting real property tax in Liberia has been a difficult task for the Government because of lack of comprehensive database on property locations, ownership and values<br>
slide14. FINDINGS-50/50 revenue sharing pilot<br>
slide15. Observations & CONCLUSIONs Local, state-led incentives (i.e. the provision of basic social services, inclusion adequate public schools, health facilities, electricity, etc.) to drive compliance does not exist and there is persistent accusation of corrupt practices by tax collectors.
Payment on property tax outside of Monrovia are mostly non-existent, with few citizens obliging/ complying to pay only if it has a direct personal benefit to them.
Demonstrable evidence shows the state inability to provide basic resources to maintain and support service delivery functions at the county level influence Citizens trust , thoughts and perceptions of GoL..
Generally, the respondents concurred that tax awareness has been created mainly because of thee 50/50 pilot in Margibi.<br>
slide16. CON’t Outside of income tax, respondents concurred that property or real estate tax payment is uncommon in their communities.
Perceived acts of corruption by civil servants, as well as inadequate social service are driving up citizens’ unwilling to pay taxes.
There was consensus amongst respondents that the centralize system concentrate power and authority in Monrovia and reduced incentives for citizens outside of Monrovia to benefit from social services and comply with tax payment.
Hope and optimism remain high insofar as the 50/50 revenue sharing pilot is concern. However, skepticism remain high that the deal/pilot is highly likely not going to work because of fear of elite capture and corruption.<br>
slide17. recommendations GoL to consider one-stop digitize tax payment locations at the county level for the public to avoid physical human interaction for tax collection. Also, mobile money could be an alternative model for local communities.
As of 2020, Liberia had a population of 5.05 million, 49.7 percent being female, and 50.3 percent being male. Despite women constituting 49% of the population, development indices are negative for women compared to men. A need to review and consider the ambiguity in the inheritance law that tends to undermine women, especially those in customary relationship rights to fully gain property ownership.
Efficiency in tax collection should go beyond radio awareness and one-off outreach engagements. Establishing mutual trust by utilizing revenue generated to provide adequate social services is critical and is likely to contribute to increasing citizens’ willingness to pay taxes.
The devolution of power and authority is essential and is likely to contribute to tax collection. This would require political will and commitment and should include fiscal decentralization to ensure local authorities are able to provide, manage and maintain services essential to local citizens.<br>
slide18. Thank you Q&As<br>