
International Corporate Reporting Chapter 15
YM
Published · 47 slides · 0 views
1 / 1



Description
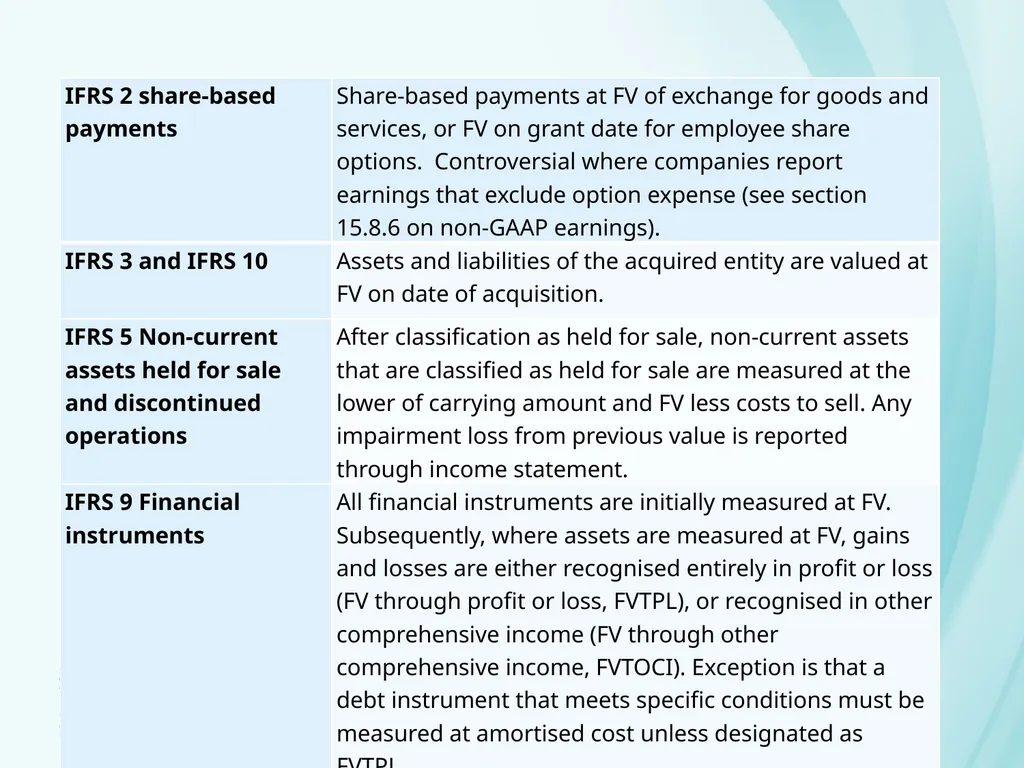
International Corporate Reporting Chapter 15 Current issues in accounting Fair value accounting Fair value defined Price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market
Related Topics
Share
Embed code
Download this presentation From Below
"International Corporate Reporting Chapter 15" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
International Corporate Reporting
Chapter 15
Current issues in accounting<br>
02
Fair value accounting<br>
03
Fair value defined Price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date.
An ‘exit price’.
Transaction price (an entry price) may be used at the point of initial recognition but that does not necessarily mean it represents the fair value of an asset or liability on its initial recognition –practical compromise.<br>
An ‘exit price’.
Transaction price (an entry price) may be used at the point of initial recognition but that does not necessarily mean it represents the fair value of an asset or liability on its initial recognition –practical compromise.<br>
04
Measuring fair value The principal (or most advantageous) market at the measurement date under current market conditions.
Would achieve highest and best use, or by selling it to another market participant that would use the asset in its highest and best use.
Significant judgement required, using the core concepts of the standard’s principles-based framework.<br>
Would achieve highest and best use, or by selling it to another market participant that would use the asset in its highest and best use.
Significant judgement required, using the core concepts of the standard’s principles-based framework.<br>
05
Fair value hierarchy (steps) IFRS 13 and US GAAP set out a ‘hierarchy’ for determining fair value depending on the nature of the market.
Level 1 inputs are quoted prices in active markets for identical assets or liabilities that the entity can access at the measurement date.
Level 2 inputs are not quoted but observable for the asset or liability, either directly or indirectly.
Level 3 inputs are unobservable inputs for the asset or liability (estimated by management).<br>
06
Applying fair value Differences between IFRS Standards and US GAAP lie in the uses of fair value in measurement.
US GAAP generally requires historical cost and prohibits revaluations except for certain categories of financial instruments, which are carried at fair value.
Ability to revalue assets to fair value over a wider range of categories under IFRS Standards might create significant differences in the carrying value of assets as compared with US GAAP.<br>
07
Investment properties<br>
08
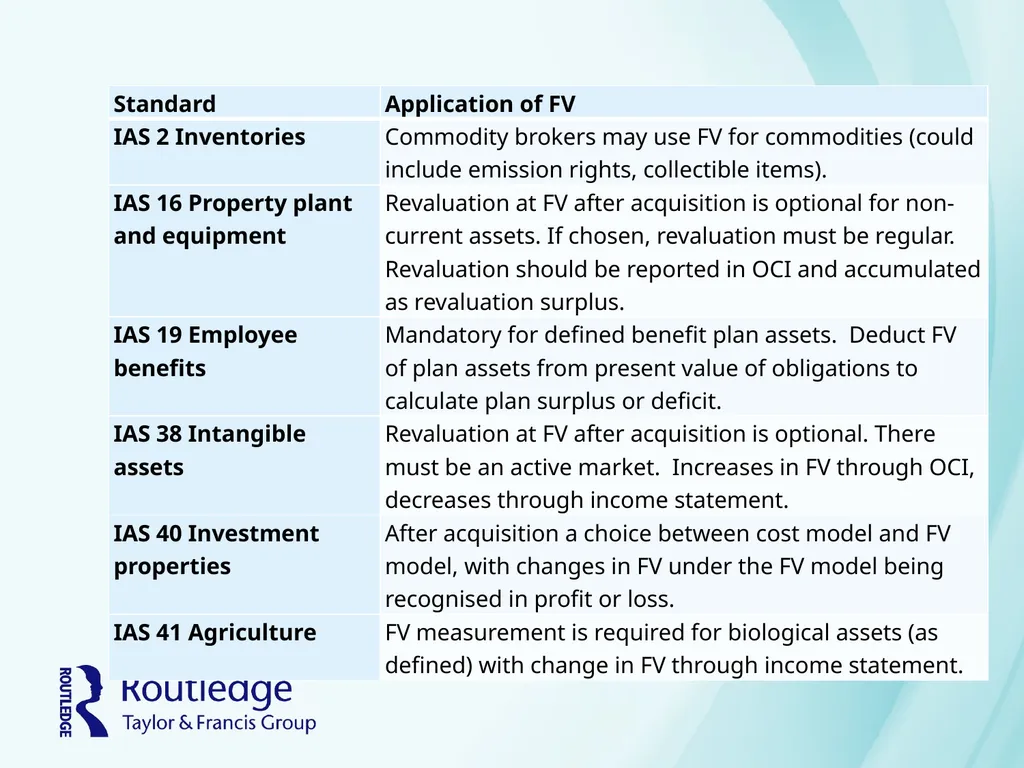
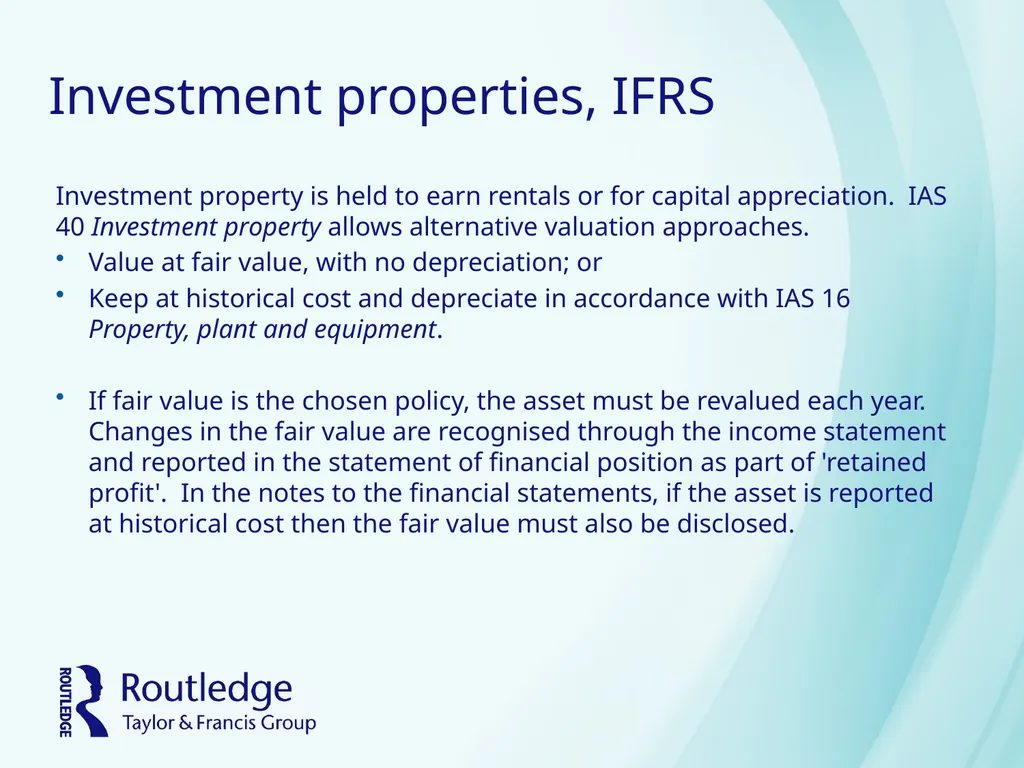
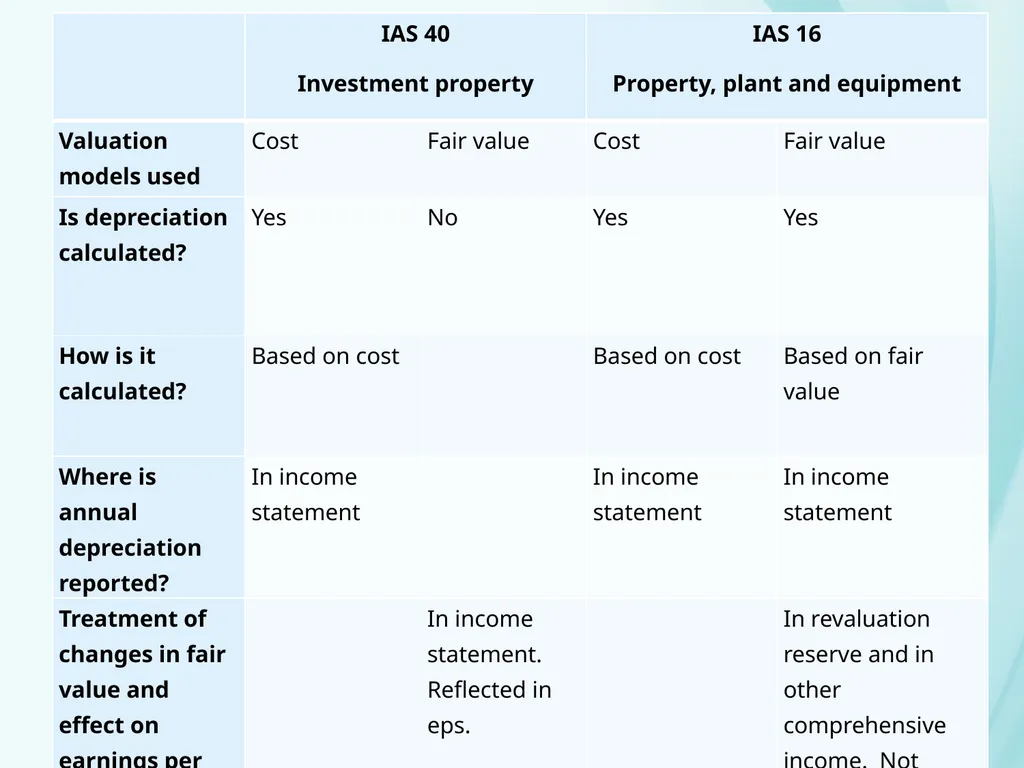
Investment properties, IFRS Investment property is held to earn rentals or for capital appreciation. IAS 40 Investment property allows alternative valuation approaches.
Value at fair value, with no depreciation; or
Keep at historical cost and depreciate in accordance with IAS 16 Property, plant and equipment.
If fair value is the chosen policy, the asset must be revalued each year. Changes in the fair value are recognised through the income statement and reported in the statement of financial position as part of 'retained profit'. In the notes to the financial statements, if the asset is reported at historical cost then the fair value must also be disclosed.<br>
09
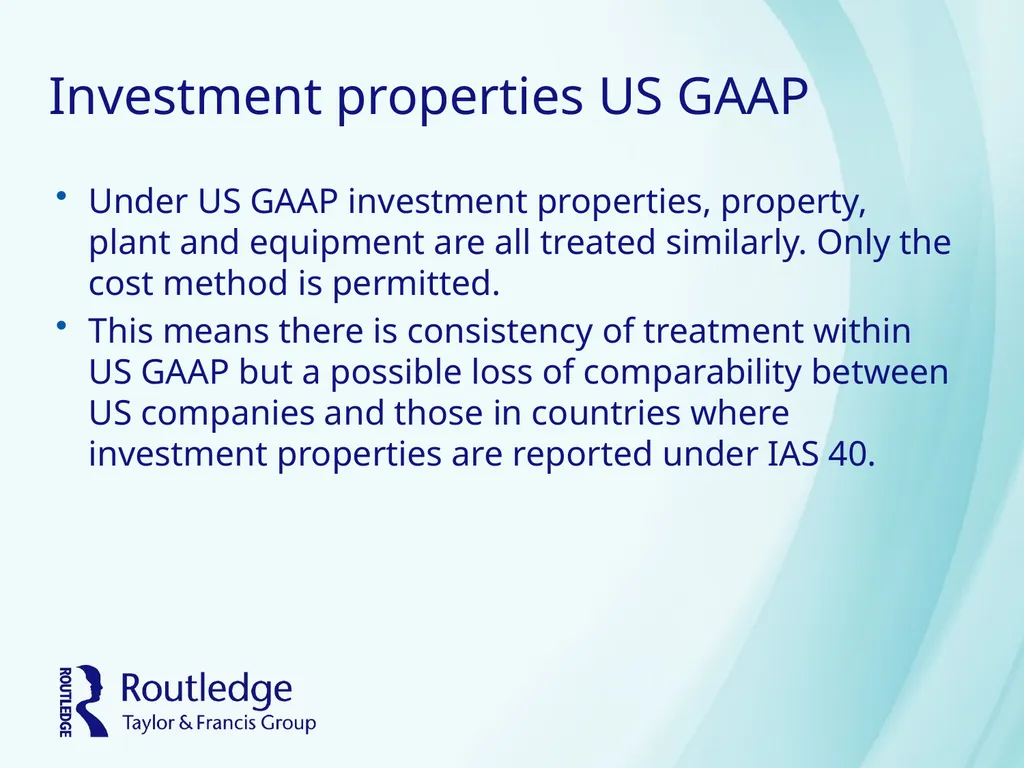
Investment properties US GAAP Under US GAAP investment properties, property, plant and equipment are all treated similarly. Only the cost method is permitted.
This means there is consistency of treatment within US GAAP but a possible loss of comparability between US companies and those in countries where investment properties are reported under IAS 40.<br>
This means there is consistency of treatment within US GAAP but a possible loss of comparability between US companies and those in countries where investment properties are reported under IAS 40.<br>
10
Revenue recognition<br>
11
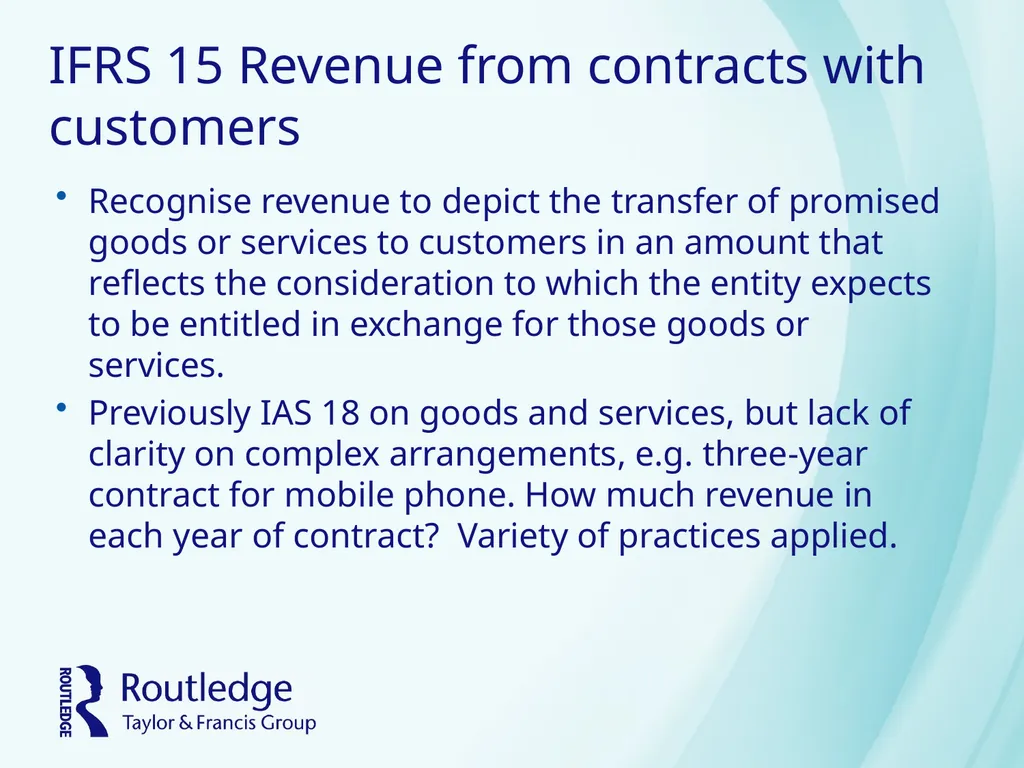
IFRS 15 Revenue from contracts with customers Recognise revenue to depict the transfer of promised goods or services to customers in an amount that reflects the consideration to which the entity expects to be entitled in exchange for those goods or services.
Previously IAS 18 on goods and services, but lack of clarity on complex arrangements, e.g. three-year contract for mobile phone. How much revenue in each year of contract? Variety of practices applied.<br>
Previously IAS 18 on goods and services, but lack of clarity on complex arrangements, e.g. three-year contract for mobile phone. How much revenue in each year of contract? Variety of practices applied.<br>
12
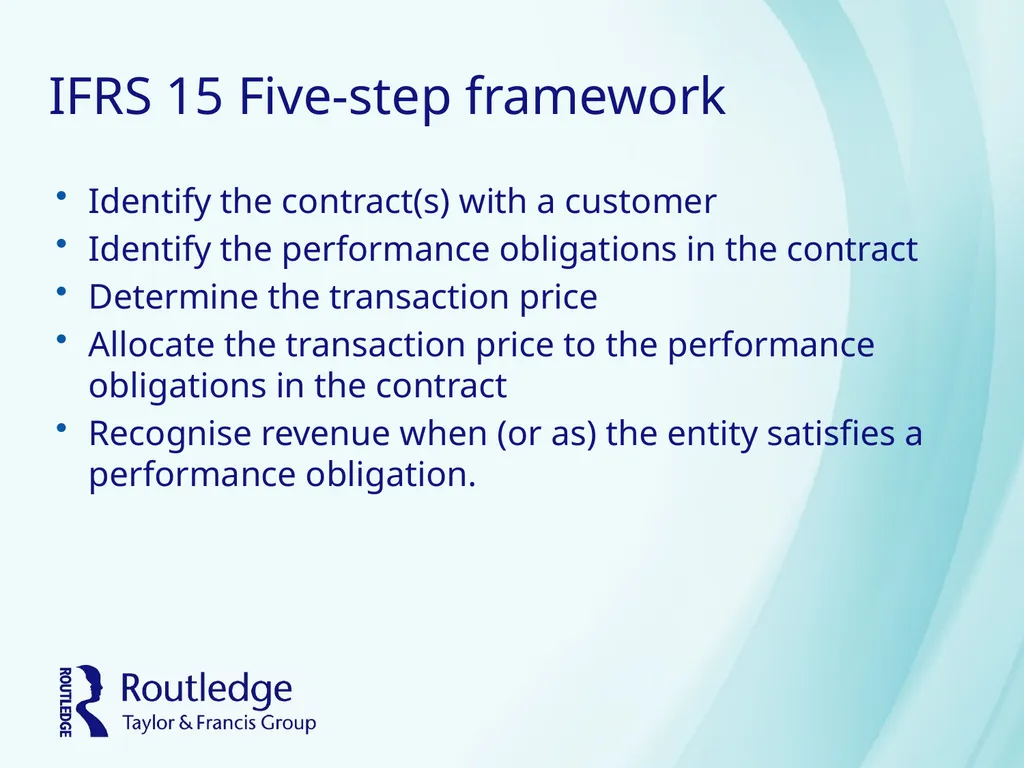
IFRS 15 Five-step framework Identify the contract(s) with a customer
Identify the performance obligations in the contract
Determine the transaction price
Allocate the transaction price to the performance obligations in the contract
Recognise revenue when (or as) the entity satisfies a performance obligation.<br>
Identify the performance obligations in the contract
Determine the transaction price
Allocate the transaction price to the performance obligations in the contract
Recognise revenue when (or as) the entity satisfies a performance obligation.<br>
13
US GAAP FASB ASC 606 aligned with IFRS 15.
Major joint project under Joint Transition Resource Group.
Previously in US detailed rules, specific to different industries.
Lack of comparability across industries.
New transactions had emerged in US not covered by existing standards.<br>
Major joint project under Joint Transition Resource Group.
Previously in US detailed rules, specific to different industries.
Lack of comparability across industries.
New transactions had emerged in US not covered by existing standards.<br>
14
Major retail chains may have agreements with suppliers whereby volume-related allowances, promotional and marketing allowances and various other fees and discounts are received in connection with the purchase of goods for resale from those suppliers. There are two accounting questions here:
Are these amounts received from suppliers an addition to revenue or a reduction in cost of sales?
What are the risks or uncertainties in measurement of these amounts, where estimates may be required at the accounting year-end? Case study, revenue recognition, 2018<br>
Are these amounts received from suppliers an addition to revenue or a reduction in cost of sales?
What are the risks or uncertainties in measurement of these amounts, where estimates may be required at the accounting year-end? Case study, revenue recognition, 2018<br>
15
(US company) Walmart: Payments from Suppliers
Payments from suppliers are accounted for as a reduction of cost of sales, except in certain limited situations when the payment is a reimbursement of specific, incremental and identifiable costs, and are recognized in the Company's Consolidated Statements of Income when the related inventory is sold.<br>
Payments from suppliers are accounted for as a reduction of cost of sales, except in certain limited situations when the payment is a reimbursement of specific, incremental and identifiable costs, and are recognized in the Company's Consolidated Statements of Income when the related inventory is sold.<br>
16
(UK company) Tesco: Commercial income
Commercial income is recognised when earned by the Group, which occurs when all obligations conditional for earning income have been discharged, and the income can be measured reliably based on the terms of the contract. The income is recognised as a credit within cost of sales.<br>
Commercial income is recognised when earned by the Group, which occurs when all obligations conditional for earning income have been discharged, and the income can be measured reliably based on the terms of the contract. The income is recognised as a credit within cost of sales.<br>
17
Statements of accounting policy appear relatively similar and both give information that confirms comparability in reducing the cost of sales.
Use different terminology.
Neither indicates the risks attached to the measurement of this income.
US company:
Audit report in the US is unqualified, relatively short and there is no discussion of key audit matters.
Form 10-K report includes a section on Critical Accounting Estimates but there is no reference to payments from suppliers.
UK company:
Search for words ‘commercial income’.
Report of the Audit committee confirms focus of attention on management processes in this area.
Report of the Independent Auditor is unqualified. Notes that recognition of commercial income is one of the key audit matters identified for the report.
Conclusion: Accounting policies aligned, narrative information differs.<br>
18
Research and development expenditure<br>
19
Nature of R&D R&D activity carried out within an entity is an example of an internally generated intangible asset.
Sometimes research and development activity may be acquired in a transaction such as an acquisition. The accounting treatment of internally generated intangibles is different from that of externally acquired intangibles.
IASB treatment of internally generated development expenditure is different from that of US GAAP.<br>
20
Research is different from Development Research costs
must be reported as expenses, both in IAS 38 Intangible assets and in US GAAP.
cannot be reported as assets.
Development costs
are capitalised as assets under IAS 38 if specified criteria are met, then amortised.
US GAAP prohibits, with limited exceptions, the capitalisation of development costs.<br>
21
IAS 38, six conditions to capitalise development Must demonstrate all six:
The technical feasibility of completing the intangible asset;
The intention to complete the intangible asset;
The ability to use or sell the intangible asset;
How the intangible asset will generate probable future economic benefits (there is an external market or an internal use);
The availability of adequate resources to complete the development and to use or sell it; and
The ability to measure reliably the expenditure attributable to the intangible asset during its development.<br>
22
US GAAP In general development costs must be reported as expenses of the period.
exceptions, such as software development costs, which are capitalised. US GAAP provides specific detailed guidance but with different conditions depending on whether the software is for internal use or for sale. Other industries also have specialised capitalisation guidance under US GAAP.<br>
exceptions, such as software development costs, which are capitalised. US GAAP provides specific detailed guidance but with different conditions depending on whether the software is for internal use or for sale. Other industries also have specialised capitalisation guidance under US GAAP.<br>
23
IAS 38, externally acquired R&D acquired research and development assets are capitalised if is probable that they will have future economic benefits. T
Price paid reflects expectations about the probability that the future economic benefits of the asset will flow to the entity.
The probability recognition criterion is always assumed to be met for separately acquired intangible assets.<br>
Price paid reflects expectations about the probability that the future economic benefits of the asset will flow to the entity.
The probability recognition criterion is always assumed to be met for separately acquired intangible assets.<br>
24
US GAAP capitalisation depends on both the type of acquisition (asset acquisition or business combination) as well as whether the asset has an alternative future use.
for an asset to have alternative future use, it must be reasonably expected (greater than a 50% chance) that an entity will achieve economic benefit from such alternative use and further development is not needed at the acquisition date to use the asset.<br>
for an asset to have alternative future use, it must be reasonably expected (greater than a 50% chance) that an entity will achieve economic benefit from such alternative use and further development is not needed at the acquisition date to use the asset.<br>
25
Pharmaceuticals, high ratio of R&D intensity,
Might expect that the impact on capitalisation of development costs by companies in that sector would be of significant.
Compare Roche and Novartis (Switzerland, both using IFRS) with Johnson & Johnson and Pfizer (US),
Find that neither Roche nor Novartis have capitalised development costs so effectively both the US and European companies have applied similar accounting methods.
Typical accounting policy note under IFRS:
‘We consider that regulatory and other uncertainties inherent in the development of new products preclude the capitalization of internal development expenses as an intangible asset.’
Comparable because all take similar approach.<br>
26
Compare vehicle manufacturing companies in Europe and the US, the impact of capitalisation of development costs in this sector appears to be material.
Typical accounting policy note under IFRS:
‘Development costs for future products are capitalized at cost providing the products is likely to bring economic benefit. If the criteria for recognition as assets are not met, the expenses are recognized in the income statement in the year in which they are incurred.’<br>
27
Case study:
Compare the ratio of profit before tax to sales for four companies:
Column A: As reported by US companies applying US GAAP
Column B: As reported by European companies applying IFRS
Column C: Recalculated for European companies based on US GAAP, for comparison.<br>
Compare the ratio of profit before tax to sales for four companies:
Column A: As reported by US companies applying US GAAP
Column B: As reported by European companies applying IFRS
Column C: Recalculated for European companies based on US GAAP, for comparison.<br>
28
Profit before tax as % of sales revenue, adjusting R&D costs from capitalisation to full expense Question: How to make comparisons of performance (i) within EU (ii) between EU and US companies?<br>
29
Leases<br>
30
Previous practice Different treatments depending on type of lease
Finance lease
asset and liability on balance sheet
Interest expense and depreciation in income statement
Operating lease
Nothing on balance sheet
Rental charge in income statement<br>
Finance lease
asset and liability on balance sheet
Interest expense and depreciation in income statement
Operating lease
Nothing on balance sheet
Rental charge in income statement<br>
31
Changing practice Finance lease transfers substantially all the risks and rewards of to ownership. Similar to purchase of an asset using a loan
All other leases are classified as operating leases.
Distinguished by conditions of lease contract, but scope for selective drafting of contracts.
Concerns about off-balance-sheet finance
Lack of transparency
IASB and FASB started project together but completed separately, effective 2019.<br>
All other leases are classified as operating leases.
Distinguished by conditions of lease contract, but scope for selective drafting of contracts.
Concerns about off-balance-sheet finance
Lack of transparency
IASB and FASB started project together but completed separately, effective 2019.<br>
32
IFRS 16 Lessee, all leases Must recognise assets and liabilities for all leases with a term of more than 12 months, unless the underlying asset is of low value; and to report depreciation of lease assets separately from interest on lease liabilities in the income statement.
The asset is reported at its right-of-use value which is measured as the present value of the lease payments.
Right-of-use value of the asset becomes the cost for the purposes of complying with IAS 16.
Balance sheet recognises a financial liability representing its obligation to make future lease payments.
Income statement reports depreciation and interest expense<br>
33
US GAAP, Lessees, ASC 842 Lessee may identify either a finance or operating lease, similar to criteria used previously,
Lease classification affects subsequent measurement of the right-of-use asset, lease expense and income statement presentation.
Day one the lessee accounting treatment of all leases will report an asset and a liability in a manner similar to IFRS 16 but
From day two the treatment of the operating lease will diverge.
Finance lease will apply a financing model in which the expense resulting from the lease declines during the lease term
Operating leases will result in lease expense recognised on a straight -line basis, by amortising the leased asset more slowly than a finance leased asset. Outcome will be a straight-line expense in the income statement, similar to that previously reported for an operating lease.<br>
34
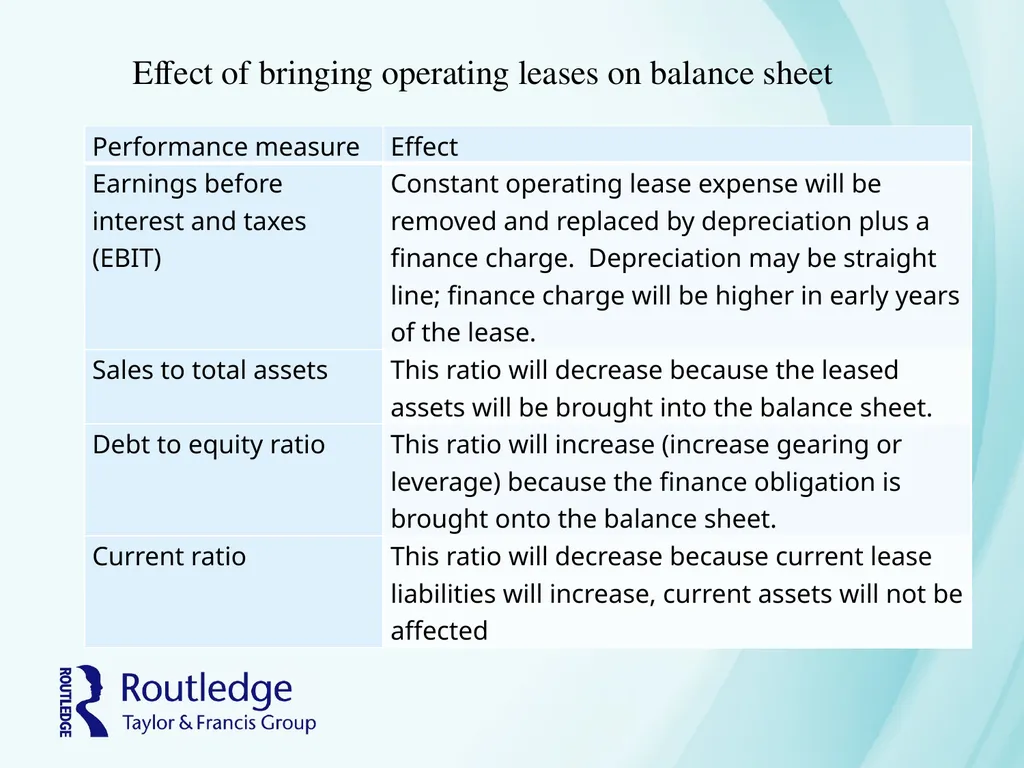
Effect of bringing operating leases on balance sheet<br>
35
Alternative performance measures (non-GAAP reporting)<br>
36
Alternative Performance Measure, Non-GAAP Measure Non-GAAP as ‘a numerical measure of an issuer’s current, historical or future financial performance, financial position or cash flow that is not a GAAP measure’ (IOSCO)
APM as ‘a financial measure of historical or future financial performance, financial position, or cash flows, other than a financial measure defined or specified in the applicable financial reporting framework’ (ESMA)
SEC also defines and describes non-GAAP<br>
APM as ‘a financial measure of historical or future financial performance, financial position, or cash flows, other than a financial measure defined or specified in the applicable financial reporting framework’ (ESMA)
SEC also defines and describes non-GAAP<br>
37
SEC studies report non-GAAP measures are prevalent, and they generally present a more positive financial picture than their GAAP counterparts.
Common adjustment in arriving at non-GAAP profit are the exclusion of:
costs of fundamental reorganisation;
impairment;
amortisation;
gain or loss on asset disposal;
changes in value of financial assets and liabilities.<br>
Common adjustment in arriving at non-GAAP profit are the exclusion of:
costs of fundamental reorganisation;
impairment;
amortisation;
gain or loss on asset disposal;
changes in value of financial assets and liabilities.<br>
38
Variety of descriptions of non-GAAP profit underlying performance or profit,
profit before exceptional items,
profit excluding exceptional items,
pre-exceptional item profit,
profit before special items,
EBITDA (earnings before interest, taxation, depreciation and amortisation),
adjusted earnings per share
street earnings
pro forma earnings<br>
profit before exceptional items,
profit excluding exceptional items,
pre-exceptional item profit,
profit before special items,
EBITDA (earnings before interest, taxation, depreciation and amortisation),
adjusted earnings per share
street earnings
pro forma earnings<br>
39
For and against positive view -it allows a company to provide a better understanding of its financial performance.
negative view - it allows a company to confuse investors by presenting performance in a way that favours the company.
IASB has made no recommendation.
IOSCO guidance - transparency, consistency, and comparability are key to the appropriate use of non-GAAP measures.
Other jurisdictions have provided guidance.<br>
40
Define each non-GAAP financial measure and explain the basis of calculation.
Distinguish non-GAAP from GAAP measures by using meaningful labels
Explain the reason for presenting the non-GAAP financial measure, why it is useful to investors, and how management uses the measure.
State that the non-GAAP financial measure does not have a standardised meaning prescribed by the issuer’s GAAP and therefore may not be comparable to similar measures presented by other issuers.
Non-GAAP financial measures should not be used to avoid presenting adverse information to the market. IOSCO Guidance<br>
41
Non-GAAP financial measures should not be more prominent than the most directly comparable measure calculated and presented in accordance with GAAP.
Provide a quantitative reconciliation from the non-GAAP financial measure to the most directly comparable GAAP measure presented in the financial statements.
Ensure the reconciliation is clear.
Provide the non-GAAP measure for comparative periods.
Present non-GAAP measures consistently from period to period, and explain any changes. IOSCO Guidance (contd)<br>
42
Research examples Fair value accounting
Who uses FVA? Interview research with investors and analysts
Experience of FVA in China? Archival records and studies of social movements.
Pressure in financial crisis, Korea.
Investment properties
Which companies use FV option? Study from annual reports<br>
Who uses FVA? Interview research with investors and analysts
Experience of FVA in China? Archival records and studies of social movements.
Pressure in financial crisis, Korea.
Investment properties
Which companies use FV option? Study from annual reports<br>
43
Research examples (contd) Revenue recognition
Documentary evidence on development of a standard
Research and development expenditure
Comparison of profitability with capitalisation across 19 countries. Relate to corruption index.
Motives for capitalising where discretion exists
Leases
Previous studies on comparisons finance and operating leases. Evidence awaited on IFRS 16.<br>
44
Research examples (contd) Alternative performance measures (non-GAAP)
UK-based review of prior research to examine motives for APM.
US-based review on prior work and guide to future directions<br>
UK-based review of prior research to examine motives for APM.
US-based review on prior work and guide to future directions<br>