
Making Sense of Blockchain, Bitcoin, and Digital

Description: Making Sense of Blockchain, Bitcoin, and Digital Assets Brad T. Gregory Senior Portfolio Manager Research Analyst Investment Operations Manager Ryan P. Johnson, CFA, CFP Director of Portfolio Management Research Welcome Brad recently
Related Topics
Download Presentation
"Making Sense of Blockchain, Bitcoin, and Digital" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Making Sense of
Blockchain,
Bitcoin, and Digital Assets Brad T. Gregory
Senior Portfolio Manager & Research Analyst
Investment Operations Manager Ryan P. Johnson, CFA, CFP®
Director of Portfolio Management & Research<br>
slide2. Welcome Brad recently earned the Certificate in Blockchain and Digital Assets® presented by the Digital Assets Council of Financial Professionals (DACFP).
Bitcoin and Digital Assets continue to be a discussion that is making its way into traditional investment management.
This presentation will give you a basic knowledge of what Bitcoin and other Digital Assets are, and how we think of them in the scope of traditional investing, financial planning, and tax strategies.<br>
slide3. Fast Facts “Blockchain has the potential to add $1.76 trillion dollars to the global economy by 2030” – PwC “Time for trust” report published in 2020
6% of U.S. investors own cryptocurrency, up from just 2% in 2018.
More than 100 million people own cryptocurrency worldwide.
The number of accounts at cryptocurrency exchange Coinbase (73 million) more than doubles the accounts at Charles Schwab (33 million).<br>
slide4. What is Blockchain Technology? Blockchain technology is a collection of records, also known as distributed ledger technology.
Think of blockchain as a database of transactions, like a checkbook register or Excel spreadsheet.
Blockchain databases are open and available to anyone who wants to use them.
Data is recorded to the database in batches called blocks, blocks are then linked together in chronological order. This is how the term blockchain was derived.<br>
slide5. How is Blockchain Different From Other Databases? Blockchain technology is designed to be decentralized, meaning the ledger is not controlled or owned by any one person or entity.
Information added to the blockchain is managed and verified by users of the network. Meaning transactions can happen peer-to-peer without relying on a third party to verify.
Before a block can be added to the chain, a computer connected to the network must solve a cryptographic puzzle. Cryptography used in this process is how the terms cryptocurrency and crypto were derived.<br>
slide6. How is Blockchain Different From Other Databases? The first computer to solve the cryptographic puzzle broadcasts the answer to all other computers on the network.
Once the solution is confirmed by a consensus, the block can be added to the chain.
Users are financially incentivized to contribute computer resources to manage and verify the network.
The computer that solved the puzzle first receives the block reward.<br>
slide7. For example, if you help maintain the Bitcoin network, you receive Bitcoin.
This process is more commonly known as “mining” in the cryptocurrency world.
Data on the blockchain is immutable, once a block is added to the chain, it cannot be deleted or changed. How is Blockchain Different From Other Databases?<br>
slide8. Decentralization – Reduces the risk of corruption, fraud, and manipulation.
Increased Transparency – All participants have access to the blockchain data/records.
Removes Intermediaries from Systems – Typically results in lower costs and faster speeds.
Example: Cross Boarder Remittances
The average fee for remittances is 6.5% and the transaction takes 5 days to complete on average Why is Blockchain Technology Useful?<br>
slide9. The First Use Case of Blockchain Technology Researchers began working on the concept of blockchain technology in the early 1990s, but few had success applying it in a real-world application.
In late 2008, Satoshi Nakamoto released a whitepaper titled “Bitcoin: A Peer-to-Peer Electronic Cash System” and blockchain technology came to life.
Bitcoin was the first successful implementation of blockchain because it solved the problem of double spending.
Example: Writing the same check twice<br>
slide10. Bitcoin (BTC) Overview No one knows the identity of Satoshi Nakamoto.
The first block of Bitcoin was mined on January 3rd, 2009.
A new block is mined roughly every 10 minutes and each block contains about 4,000 transactions.
Visa completes roughly 1,700 transactions per second.
The block reward began at 50 BTC but was programed to halve every 210,000 blocks (about every 4 years).
The current block reward is 6.25 BTC (~$255,000).<br>
slide11. Bitcoin (BTC) Overview In addition to the block reward, miners are also incentivized by receiving transaction fees contained in the block.
Users pay transaction fees dependent on the traffic within the network.
The current average fee for a BTC transaction is $1.51.
The Bitcoin system was created so there will only ever be 21 million Bitcoins.
To date almost 19 million have been mined and it's estimated that 3 to 4 million BTC have been lost forever.
The last Bitcoin will be mined in year 2140.<br>
slide12. Bitcoin (BTC) Overview Bitcoin transactions are processed 24 hours a day, 7 days a week, 365 days a year.
Cryptocurrency exchanges likewise operate on this 24/7/365 schedule.
Bitcoin transactions do not need to be completed in whole numbers and can be divided down as far as 8 decimal places.<br>
slide13. How is Bitcoin Valued? Bitcoin is currently priced around $38,000 giving it a market capitalization of $725 billion dollars. (5/3/2022)
Short Answer: Bitcoin is not valued, it is priced.
Prices are set by supply and demand for Bitcoin.
Long Answer: Traditional financial valuation systems don't work perfectly for Bitcoin, but there are several methods to determining its price.<br>
slide14. How is Bitcoin Valued? Market Substitutes
Gold Total Market Cap: ~$10 trillion
Fiat Currencies Total Market Cap: ~$60 trillion
Global Real Estate Total Value: ~$250 trillion
Speculation
Short-Term Trading and Technical Analysis<br>
slide15. Bitcoin Performance and Price Volatility Bitcoin has a history of strong price appreciation combined with extreme volatility
Yearly Price Performance
2018: -72.6%
2019: +87.2%
2020: +302.8%
2021: +60.1%
4-Year Average Return: +94.4%
Volatility
On average BTC moves +/- 3% daily
In the past 10 years BTC has seen 8 price crashes of 50% or more and 3 of those instances saw declines of more than 80%<br>
slide16. Intro to Stablecoins Stablecoins were created to take advantage of cryptocurrency's unrestricted ability to transact without a third-party, but with the stability of other assets.
Stablecoins derive their value from an underlying reserve asset like U.S. Dollars, other currencies, and commodities like gold.
Each coin is backed by the underlying reserve asset.
The most popular stablecoins are pegged to the U.S. Dollar and their price remains constant at $1.
They essentially function like money market mutual funds.<br>
slide17. Intro to Central Bank Digital Currency (CBDC) Building upon the idea of stablecoins, many central banks have started to research and even launch their own digital currencies called Central Bank Digital Currency (CBDC).
The Federal Reserve is expected to release a white paper on CBDCs in the coming weeks, although a digital dollar is not expected anytime soon.
China is currently running a pilot program for a digital Yuan and could become the first country to launch a CBDC.
Sweden, Russia, Japan, and Canada among others are researching or considering CBDCs.<br>
slide18. Intro to Central Bank Digital Currency (CBDC) Adoption of a CBDC as legal tender could result in benefits such as faster transactions, reduced costs, and increased financial inclusion.
Example: Stimulus Checks
About 10% of U.S. adults don't have a savings or checking account.
Important to note that CBDCs would likely not be created in a decentralized nature.<br>
slide19. Intro to Smart Contracts The concept of smart contracts was made popular with the creation of Ethereum (ETH), the 2nd largest cryptocurrency by market capitalization.
Smart contracts are tools that can automatically execute transactions when certain conditions are met, also referred to as "programable money".
Example: Buying a Home, Tracking Titles on the Blockchain
The term digital assets derives from the fact that blockchain technology can be used to store many different types of assets outside of money.<br>
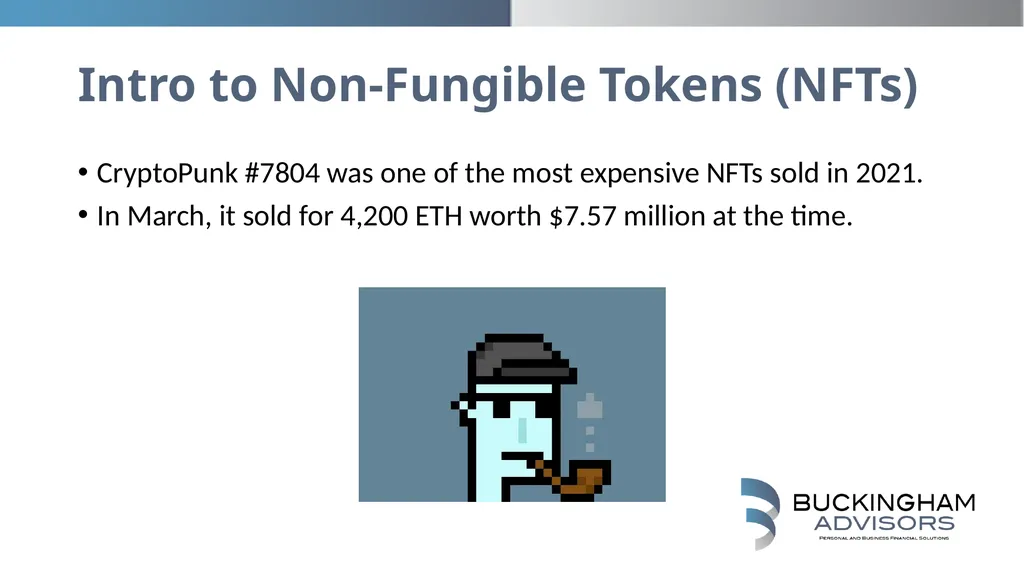
slide20. Intro to Non-Fungible Tokens (NFTs) CryptoPunk #7804 was one of the most expensive NFTs sold in 2021.
In March, it sold for 4,200 ETH worth $7.57 million at the time.<br>
slide21. Intro to Non-Fungible Tokens (NFTs) The best way to think about NFTs is digital art or digital collectables.
Non-fungible means they are unique and cannot be interchanged.
Ownership of these one-of-a-kind collectables is recorded and verified by the blockchain, increasing security and portability of assets.
NFTs are issued with smart contract technology and don't need to involve traditional media distribution, allowing content creators to monetize directly from their audience.
Example: Royalties for Secondary Sales<br>
slide22. Digital Assets Market There are more than 17,000 cryptocurrencies and tokens totaling more than $1.7 trillion market capitalization in U.S. Dollars.
Bitcoin (BTC) accounts for about 40% of the market and Ethereum (ETH) accounts for about 20% of the market.
Any coins or tokens that are not Bitcoin are called "altcoins", a short-hand version of alternative coins.<br>
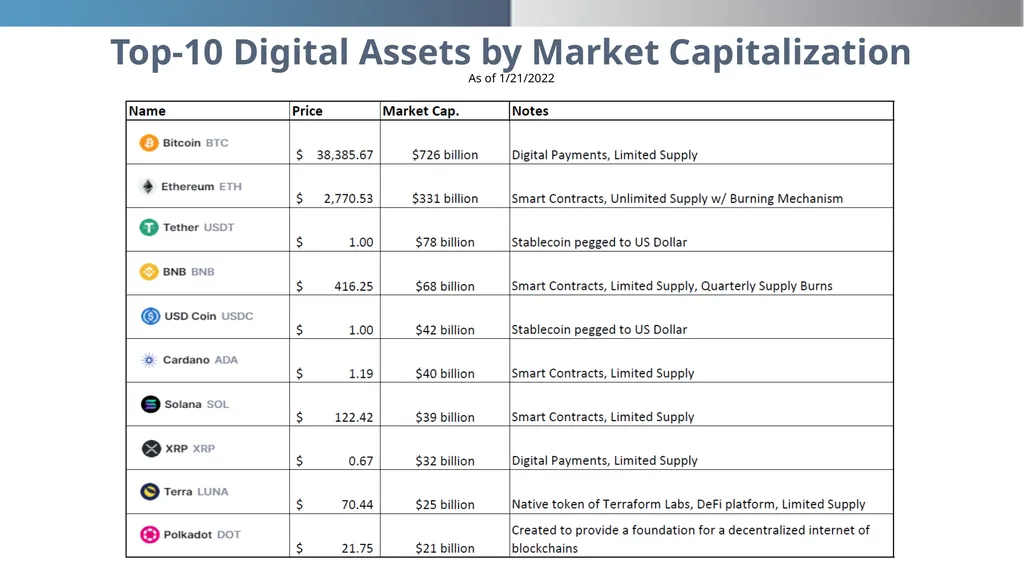
slide23. Top-10 Digital Assets by Market Capitalization As of 1/21/2022<br>
slide24. Digital Assets Outside the Top-10 Dogecoin (DOGE) - 11th largest cryptocurrency, based on an internet dog meme and created as a joke between friends.
In 2021, the price of DOGE surged from a fraction of a penny to nearly $0.70. The price subsequently fell and is currently trading around $0.15.
There are more than 132 billion DOGE in circulation.<br>
slide25. Digital Assets Outside the Top-10 A competing dog-based coin Shiba Inu (SHIB) is the 14th largest cryptocurrency.
The coin currently trades for a fraction of a penny with a supply of more than 549 trillion.
Many smaller coins have no or low utility and are often targets of pump-and-dump schemes.
Proceed with caution when hearing about the hot new cryptocurrency.
Coinmarketcap.com is a great starting point to research information about cryptocurrencies.<br>
slide26. Investing in Digital Assets Buying directly from an exchange. Examples: Binanace, Coinbase, and FTX.
Buying from a fintech platform. Examples: PayPal, Robinhood, and SoFi.
Purchasing a publicly traded trust or partnership. Examples: Grayscale Bitcoin Trust (GBTC), Grayscale Ethereum Trust (ETHE), and Bitwise 10 Crypto Index Fund (BITW).
Exchange Traded Funds (ETFs). Examples: Proshares Bitcoin Strategy ETF (BITO) and GlobalX Blockchain ETF (BKCH).<br>
slide27. TAXATION OF CRYPTOCURRENCIES<br>
slide28. Maintain Good Records Record cost basis
The cash paid for the cryptocurrency, or
The fair market value when virtual currency received, and
Cryptocurrency received as a gift; the grantor’s cost basis is transferred to the grantee.
Record sales
Cash received, or
Cryptocurrency used to purchase property or services
Exchange of one cryptocurrency for other types of virtual currency
Other receipts of virtual currency<br>
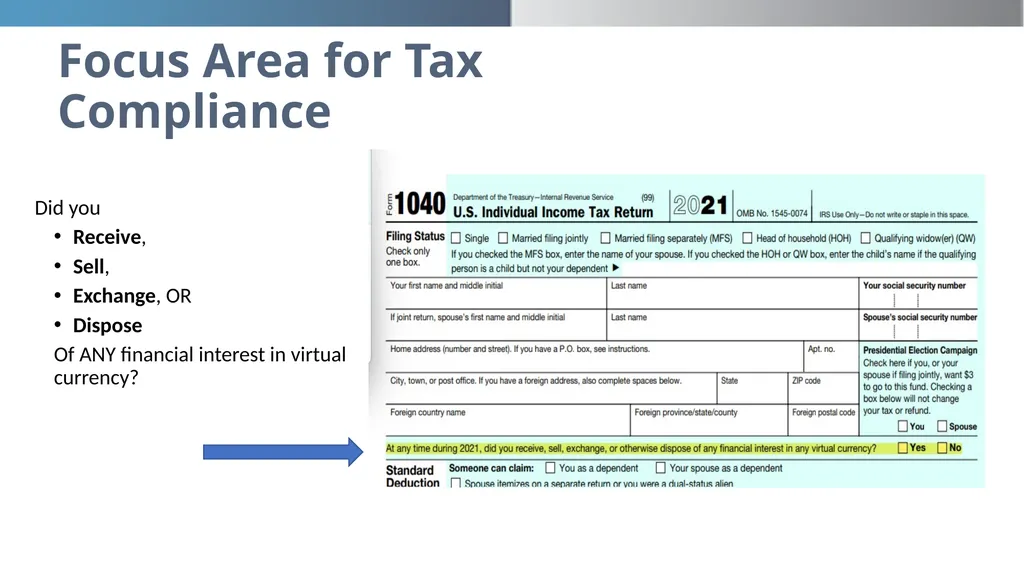
slide29. Did you
Receive,
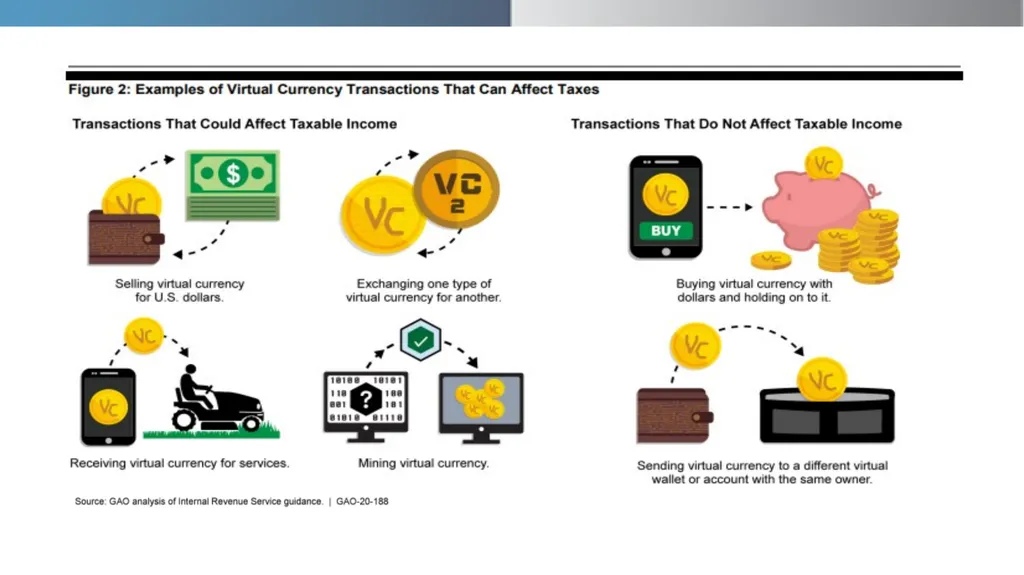
Sell,
Exchange, OR
Dispose
Of ANY financial interest in virtual currency? Focus Area for Tax Compliance<br>
slide30. RECEIVE VIRTUAL CURRENCY Through Mining
Report as income at fair market value day received (this becomes the cost basis of the cryptocurrency).
For payment of services
Report as income at fair market value when received (record the cost basis).
As gift
Record cost basis of grantor and fair market value at date of receipt.
From staking your cryptocurrency
Report rewards as income at fair market value on day received (record the cost basis).
From a prize, air drop, hard fork, interest income
Report as income at fair market value on day received (record the cost basis).<br>
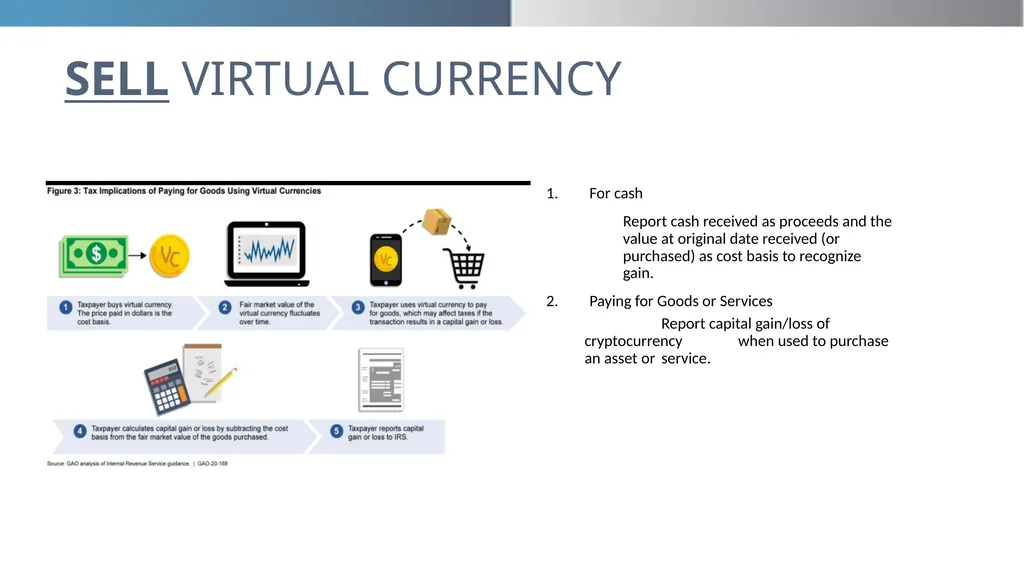
slide31. SELL VIRTUAL CURRENCY For cash
Report cash received as proceeds and the value at original date received (or purchased) as cost basis to recognize gain.
Paying for Goods or Services
Report capital gain/loss of cryptocurrency when used to purchase an asset or service.<br>
slide32. EXCHANGE VIRTUAL CURRENCY Exchange one virtual currency for another
Report the cryptocurrency given up as a sale and offset with its cost basis to calculate the capital gain.
Record the cost basis of the cryptocurrency received (the sales price of the virtual currency given).<br>
slide33. DISPOSE VIRTUAL CURRENCY Gifted
Report on a gift tax return (if applicable) the value at date of the gift and your cost basis. Provide the information to the grantee.
Donated
Report the deduction at FMV if the cryptocurrency was held for more than a year. If held for less than a year, the amount of the charitable deduction is the lesser of the basis in the cryptocurrency or the FMV at the date of donation.
Lost
Theft/Casualty Losses are no longer deductible as a casualty loss.<br>
slide35. WASH SALES Cryptocurrency is considered property and currently is not subject to wash sales rules.* This means you may sell holdings at a loss and report the loss on your tax return even if you repurchase the same type of virtual currency within 30 days.
*The Build Back Better Act that the House passed in November included a provision to make cryptocurrency sales subject to Wash Sale Rules. It is currently stalled in the Senate, but this is something to monitor.<br>
slide36. Should You/Clients Invest in Digital Assets? Buckingham does not currently recommend an allocation to digital assets.
We continue to monitor the digital assets space as an upcoming asset class that could one day become part of our portfolios.
Many clients already have exposure to digital assets so it's becoming more important to incorporate them into financial planning, tax strategies, and investment portfolios.<br>
slide37. Questions?<br>
slide38. Thank You For Joining Us! www.mybuckingham.com
service@mybuckingham.com
937.435.2742 Brad T. Gregory
Senior Portfolio Manager & Research Analyst
Investment Operations Manager
bgregory@mybuckingham.com Ryan P. Johnson, CFA, CFP®
Director of Portfolio Management & Research
rjohnson@mybuckingham.com<br>
Senior Portfolio Manager & Research Analyst
Investment Operations Manager Ryan P. Johnson, CFA, CFP®
Director of Portfolio Management & Research<br>
slide2. Welcome Brad recently earned the Certificate in Blockchain and Digital Assets® presented by the Digital Assets Council of Financial Professionals (DACFP).
Bitcoin and Digital Assets continue to be a discussion that is making its way into traditional investment management.
This presentation will give you a basic knowledge of what Bitcoin and other Digital Assets are, and how we think of them in the scope of traditional investing, financial planning, and tax strategies.<br>
slide3. Fast Facts “Blockchain has the potential to add $1.76 trillion dollars to the global economy by 2030” – PwC “Time for trust” report published in 2020
6% of U.S. investors own cryptocurrency, up from just 2% in 2018.
More than 100 million people own cryptocurrency worldwide.
The number of accounts at cryptocurrency exchange Coinbase (73 million) more than doubles the accounts at Charles Schwab (33 million).<br>
slide4. What is Blockchain Technology? Blockchain technology is a collection of records, also known as distributed ledger technology.
Think of blockchain as a database of transactions, like a checkbook register or Excel spreadsheet.
Blockchain databases are open and available to anyone who wants to use them.
Data is recorded to the database in batches called blocks, blocks are then linked together in chronological order. This is how the term blockchain was derived.<br>
slide5. How is Blockchain Different From Other Databases? Blockchain technology is designed to be decentralized, meaning the ledger is not controlled or owned by any one person or entity.
Information added to the blockchain is managed and verified by users of the network. Meaning transactions can happen peer-to-peer without relying on a third party to verify.
Before a block can be added to the chain, a computer connected to the network must solve a cryptographic puzzle. Cryptography used in this process is how the terms cryptocurrency and crypto were derived.<br>
slide6. How is Blockchain Different From Other Databases? The first computer to solve the cryptographic puzzle broadcasts the answer to all other computers on the network.
Once the solution is confirmed by a consensus, the block can be added to the chain.
Users are financially incentivized to contribute computer resources to manage and verify the network.
The computer that solved the puzzle first receives the block reward.<br>
slide7. For example, if you help maintain the Bitcoin network, you receive Bitcoin.
This process is more commonly known as “mining” in the cryptocurrency world.
Data on the blockchain is immutable, once a block is added to the chain, it cannot be deleted or changed. How is Blockchain Different From Other Databases?<br>
slide8. Decentralization – Reduces the risk of corruption, fraud, and manipulation.
Increased Transparency – All participants have access to the blockchain data/records.
Removes Intermediaries from Systems – Typically results in lower costs and faster speeds.
Example: Cross Boarder Remittances
The average fee for remittances is 6.5% and the transaction takes 5 days to complete on average Why is Blockchain Technology Useful?<br>
slide9. The First Use Case of Blockchain Technology Researchers began working on the concept of blockchain technology in the early 1990s, but few had success applying it in a real-world application.
In late 2008, Satoshi Nakamoto released a whitepaper titled “Bitcoin: A Peer-to-Peer Electronic Cash System” and blockchain technology came to life.
Bitcoin was the first successful implementation of blockchain because it solved the problem of double spending.
Example: Writing the same check twice<br>
slide10. Bitcoin (BTC) Overview No one knows the identity of Satoshi Nakamoto.
The first block of Bitcoin was mined on January 3rd, 2009.
A new block is mined roughly every 10 minutes and each block contains about 4,000 transactions.
Visa completes roughly 1,700 transactions per second.
The block reward began at 50 BTC but was programed to halve every 210,000 blocks (about every 4 years).
The current block reward is 6.25 BTC (~$255,000).<br>
slide11. Bitcoin (BTC) Overview In addition to the block reward, miners are also incentivized by receiving transaction fees contained in the block.
Users pay transaction fees dependent on the traffic within the network.
The current average fee for a BTC transaction is $1.51.
The Bitcoin system was created so there will only ever be 21 million Bitcoins.
To date almost 19 million have been mined and it's estimated that 3 to 4 million BTC have been lost forever.
The last Bitcoin will be mined in year 2140.<br>
slide12. Bitcoin (BTC) Overview Bitcoin transactions are processed 24 hours a day, 7 days a week, 365 days a year.
Cryptocurrency exchanges likewise operate on this 24/7/365 schedule.
Bitcoin transactions do not need to be completed in whole numbers and can be divided down as far as 8 decimal places.<br>
slide13. How is Bitcoin Valued? Bitcoin is currently priced around $38,000 giving it a market capitalization of $725 billion dollars. (5/3/2022)
Short Answer: Bitcoin is not valued, it is priced.
Prices are set by supply and demand for Bitcoin.
Long Answer: Traditional financial valuation systems don't work perfectly for Bitcoin, but there are several methods to determining its price.<br>
slide14. How is Bitcoin Valued? Market Substitutes
Gold Total Market Cap: ~$10 trillion
Fiat Currencies Total Market Cap: ~$60 trillion
Global Real Estate Total Value: ~$250 trillion
Speculation
Short-Term Trading and Technical Analysis<br>
slide15. Bitcoin Performance and Price Volatility Bitcoin has a history of strong price appreciation combined with extreme volatility
Yearly Price Performance
2018: -72.6%
2019: +87.2%
2020: +302.8%
2021: +60.1%
4-Year Average Return: +94.4%
Volatility
On average BTC moves +/- 3% daily
In the past 10 years BTC has seen 8 price crashes of 50% or more and 3 of those instances saw declines of more than 80%<br>
slide16. Intro to Stablecoins Stablecoins were created to take advantage of cryptocurrency's unrestricted ability to transact without a third-party, but with the stability of other assets.
Stablecoins derive their value from an underlying reserve asset like U.S. Dollars, other currencies, and commodities like gold.
Each coin is backed by the underlying reserve asset.
The most popular stablecoins are pegged to the U.S. Dollar and their price remains constant at $1.
They essentially function like money market mutual funds.<br>
slide17. Intro to Central Bank Digital Currency (CBDC) Building upon the idea of stablecoins, many central banks have started to research and even launch their own digital currencies called Central Bank Digital Currency (CBDC).
The Federal Reserve is expected to release a white paper on CBDCs in the coming weeks, although a digital dollar is not expected anytime soon.
China is currently running a pilot program for a digital Yuan and could become the first country to launch a CBDC.
Sweden, Russia, Japan, and Canada among others are researching or considering CBDCs.<br>
slide18. Intro to Central Bank Digital Currency (CBDC) Adoption of a CBDC as legal tender could result in benefits such as faster transactions, reduced costs, and increased financial inclusion.
Example: Stimulus Checks
About 10% of U.S. adults don't have a savings or checking account.
Important to note that CBDCs would likely not be created in a decentralized nature.<br>
slide19. Intro to Smart Contracts The concept of smart contracts was made popular with the creation of Ethereum (ETH), the 2nd largest cryptocurrency by market capitalization.
Smart contracts are tools that can automatically execute transactions when certain conditions are met, also referred to as "programable money".
Example: Buying a Home, Tracking Titles on the Blockchain
The term digital assets derives from the fact that blockchain technology can be used to store many different types of assets outside of money.<br>
slide20. Intro to Non-Fungible Tokens (NFTs) CryptoPunk #7804 was one of the most expensive NFTs sold in 2021.
In March, it sold for 4,200 ETH worth $7.57 million at the time.<br>
slide21. Intro to Non-Fungible Tokens (NFTs) The best way to think about NFTs is digital art or digital collectables.
Non-fungible means they are unique and cannot be interchanged.
Ownership of these one-of-a-kind collectables is recorded and verified by the blockchain, increasing security and portability of assets.
NFTs are issued with smart contract technology and don't need to involve traditional media distribution, allowing content creators to monetize directly from their audience.
Example: Royalties for Secondary Sales<br>
slide22. Digital Assets Market There are more than 17,000 cryptocurrencies and tokens totaling more than $1.7 trillion market capitalization in U.S. Dollars.
Bitcoin (BTC) accounts for about 40% of the market and Ethereum (ETH) accounts for about 20% of the market.
Any coins or tokens that are not Bitcoin are called "altcoins", a short-hand version of alternative coins.<br>
slide23. Top-10 Digital Assets by Market Capitalization As of 1/21/2022<br>
slide24. Digital Assets Outside the Top-10 Dogecoin (DOGE) - 11th largest cryptocurrency, based on an internet dog meme and created as a joke between friends.
In 2021, the price of DOGE surged from a fraction of a penny to nearly $0.70. The price subsequently fell and is currently trading around $0.15.
There are more than 132 billion DOGE in circulation.<br>
slide25. Digital Assets Outside the Top-10 A competing dog-based coin Shiba Inu (SHIB) is the 14th largest cryptocurrency.
The coin currently trades for a fraction of a penny with a supply of more than 549 trillion.
Many smaller coins have no or low utility and are often targets of pump-and-dump schemes.
Proceed with caution when hearing about the hot new cryptocurrency.
Coinmarketcap.com is a great starting point to research information about cryptocurrencies.<br>
slide26. Investing in Digital Assets Buying directly from an exchange. Examples: Binanace, Coinbase, and FTX.
Buying from a fintech platform. Examples: PayPal, Robinhood, and SoFi.
Purchasing a publicly traded trust or partnership. Examples: Grayscale Bitcoin Trust (GBTC), Grayscale Ethereum Trust (ETHE), and Bitwise 10 Crypto Index Fund (BITW).
Exchange Traded Funds (ETFs). Examples: Proshares Bitcoin Strategy ETF (BITO) and GlobalX Blockchain ETF (BKCH).<br>
slide27. TAXATION OF CRYPTOCURRENCIES<br>
slide28. Maintain Good Records Record cost basis
The cash paid for the cryptocurrency, or
The fair market value when virtual currency received, and
Cryptocurrency received as a gift; the grantor’s cost basis is transferred to the grantee.
Record sales
Cash received, or
Cryptocurrency used to purchase property or services
Exchange of one cryptocurrency for other types of virtual currency
Other receipts of virtual currency<br>
slide29. Did you
Receive,
Sell,
Exchange, OR
Dispose
Of ANY financial interest in virtual currency? Focus Area for Tax Compliance<br>
slide30. RECEIVE VIRTUAL CURRENCY Through Mining
Report as income at fair market value day received (this becomes the cost basis of the cryptocurrency).
For payment of services
Report as income at fair market value when received (record the cost basis).
As gift
Record cost basis of grantor and fair market value at date of receipt.
From staking your cryptocurrency
Report rewards as income at fair market value on day received (record the cost basis).
From a prize, air drop, hard fork, interest income
Report as income at fair market value on day received (record the cost basis).<br>
slide31. SELL VIRTUAL CURRENCY For cash
Report cash received as proceeds and the value at original date received (or purchased) as cost basis to recognize gain.
Paying for Goods or Services
Report capital gain/loss of cryptocurrency when used to purchase an asset or service.<br>
slide32. EXCHANGE VIRTUAL CURRENCY Exchange one virtual currency for another
Report the cryptocurrency given up as a sale and offset with its cost basis to calculate the capital gain.
Record the cost basis of the cryptocurrency received (the sales price of the virtual currency given).<br>
slide33. DISPOSE VIRTUAL CURRENCY Gifted
Report on a gift tax return (if applicable) the value at date of the gift and your cost basis. Provide the information to the grantee.
Donated
Report the deduction at FMV if the cryptocurrency was held for more than a year. If held for less than a year, the amount of the charitable deduction is the lesser of the basis in the cryptocurrency or the FMV at the date of donation.
Lost
Theft/Casualty Losses are no longer deductible as a casualty loss.<br>
slide35. WASH SALES Cryptocurrency is considered property and currently is not subject to wash sales rules.* This means you may sell holdings at a loss and report the loss on your tax return even if you repurchase the same type of virtual currency within 30 days.
*The Build Back Better Act that the House passed in November included a provision to make cryptocurrency sales subject to Wash Sale Rules. It is currently stalled in the Senate, but this is something to monitor.<br>
slide36. Should You/Clients Invest in Digital Assets? Buckingham does not currently recommend an allocation to digital assets.
We continue to monitor the digital assets space as an upcoming asset class that could one day become part of our portfolios.
Many clients already have exposure to digital assets so it's becoming more important to incorporate them into financial planning, tax strategies, and investment portfolios.<br>
slide37. Questions?<br>
slide38. Thank You For Joining Us! www.mybuckingham.com
service@mybuckingham.com
937.435.2742 Brad T. Gregory
Senior Portfolio Manager & Research Analyst
Investment Operations Manager
bgregory@mybuckingham.com Ryan P. Johnson, CFA, CFP®
Director of Portfolio Management & Research
rjohnson@mybuckingham.com<br>