
Representativeness shortcuts and errors Question
SN
Published · 60 slides · 0 views
1 / 1

Description
Representativeness shortcuts and errors Question Which of the following is more likely, a or b? Why? a. A war between the U.S. and Iran b. Neither the U.S. nor Iran intended to attack the other, but Israeli Air Force jets blew up nuclear
Related Topics
Share
Embed code
Download this presentation From Below
"Representativeness shortcuts and errors Question" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Representativeness shortcuts and errors Question
Which of the following is more likely, a or b? Why?
a. A war between the U.S. and Iran
b. Neither the U.S. nor Iran intended to attack the other, but Israeli Air Force jets blew up nuclear facilities in Bushehr, Fordow, and Natanz. Iran responded with a barrage of Hezbollah rockets in northern Israel and Hamas rained rockets on Tel Aviv. American embassies were torched in Paris and Berlin, and the American ambassador in Japan was assassinated, drawing the U.S. into a war with Iran<br>
02
Representativeness shortcuts and errors Question:
A certain town is served by two hospitals
In the larger hospital about 45 babies are born each day, and in the smaller hospital about 15 babies are born each day
As you know, about 50% of all babies are boys, but the exact percentage varies from day to day
Sometimes it is higher than 50%, sometimes lower<br>
03
Finance for Normal People
Chapter 3 – Cognitive Shortcuts and Errors<br>
Chapter 3 – Cognitive Shortcuts and Errors<br>
04
Cognitive shortcuts and errors Cognitive shortcuts are part of the intuitive “blink” System 1 in our minds, leading to good choices in most of life
But shortcuts turn into errors when they mislead us into poor choices. System 2, the reflective “think” system in our minds, leads to better choices when System 1 misleads
People with knowledge of human behavior and financial facts employ cognitive shortcuts correctly, whereas people lacking such knowledge commit cognitive errors as they employ them incorrectly
We know cognitive shortcuts also as cognitive rules-of-thumb and as cognitive heuristics<br>
05
Cognitive shortcuts and errors There is no uniform list of cognitive shortcuts and associated errors, and not all cognitive shortcuts and associated errors on lists are distinct from one another
The chapter describes cognitive shortcuts and associated errors most relevant in the context of finance, including:
Framing
Hindsight
Confirmation
Anchoring and adjustment
Representativeness
Availability
Confidence<br>
The chapter describes cognitive shortcuts and associated errors most relevant in the context of finance, including:
Framing
Hindsight
Confirmation
Anchoring and adjustment
Representativeness
Availability
Confidence<br>
06
Framing shortcuts and errors We use framing shortcuts when we simplify complex problems and substitute solutions to the simplified problems for solutions to the complex problems
We use framing shortcuts well when the solutions to the simplified problems are close to the solutions to the complex problems
We commit cognitive errors when the solutions to the simplified problems are far from the solutions to the complex problems<br>
We use framing shortcuts well when the solutions to the simplified problems are close to the solutions to the complex problems
We commit cognitive errors when the solutions to the simplified problems are far from the solutions to the complex problems<br>
07
Framing shortcuts and errors A commercial for running shoes illustrates framing shortcuts and errors
Watch the video clip:
https://www.youtube.com/watch?v=D-ie_aFsfb8<br>
Watch the video clip:
https://www.youtube.com/watch?v=D-ie_aFsfb8<br>
08
Framing shortcuts and errors Question:
Surgeons get better at surgery when they perform many surgeries
Automobile mechanics get better at fixing cars when they fix many cars
Students get better grades when they study hard
Framing trading as equivalent to surgery, car fixing, and studying is a framing shortcut
Why can it lead to a framing error?
Why might traders not get better at trading even when they perform many trades?<br>
09
Frames in mental accounting We commonly frame monies into distinctly labeled mental accounts and treat them accordingly
Mental accounts resemble checking accounts, and money in mental accounts resembles money in checking accounts
Mental accounts help us keep track of our money and direct it to where we want it to go<br>
Mental accounts resemble checking accounts, and money in mental accounts resembles money in checking accounts
Mental accounts help us keep track of our money and direct it to where we want it to go<br>
10
Frames in mental accounting Mental accounting is common to all, from Hollywood movie stars to rural people in China’s regions of Gansu and Inner Mongolia
Watch the video clip of Gene Hackman, star of the film “The French Connection” and Dustin Hoffman, star of the film “The Graduate”
https://www.youtube.com/watch?v=t96LNX6tk0U<br>
Watch the video clip of Gene Hackman, star of the film “The French Connection” and Dustin Hoffman, star of the film “The Graduate”
https://www.youtube.com/watch?v=t96LNX6tk0U<br>
11
Frames in mental accounting We regularly distinguish income earned with much effort, such as salaries, from unearned income obtained with little effort, such as gifts
We tend to place earned income in one mental account and unearned income in another, and we spend unearned income more easily than earned income.
The expression “Easy come, easy go” is common across languages: “Как нажито, так ипрожито” in Russian, “Lai de rong yi, qu de kuai” in Chinese, “Lo que ilega fácil, fácil se va“ in Spanish, and “Bekelalu Yemta, Bekalau Yehedal” in Amharic, spoken in Ethiopia
That distinction is evident among rural people in China and Tanzania who spend earned income on staple foods and education, while spending unearned income on clothing, alcohol, tobacco, and non-staple foods<br>
12
Frames in mental accounting Question:
Do you distinguish money earned with effort from money you receive as a gift?
Does “easy come, easy go” describe your behavior?
Do you use mental accounts to keep track of spending and control it?
How do you use them?<br>
Do you distinguish money earned with effort from money you receive as a gift?
Does “easy come, easy go” describe your behavior?
Do you use mental accounts to keep track of spending and control it?
How do you use them?<br>
13
Frames in mental accounting The source of money also affect willingness to take risk
People in the hard-earner groups received an amount of money for completing work requiring physical effort - peeling 25 potatoes or making nine envelopes within 30 minutes
People in the windfall-receiver groups received the same amount of money as a gift, with no work requirement
Subsequently, people in the hard-earner groups made less risky and more patient choices than people in the windfall-receiver groups<br>
14
Frames in the winner’s curse Framing errors underlie the “winner’s curse,” where winners of auctions pay too much for what they buy, such as oil wells
Think of many bidders who estimate the value of an oil well yet to be drilled
Each estimate combines the yet unknown $100 million true value of the well with an error that makes the estimate too high or too low
The cursed winner is the one whose estimation error is too high by the most, perhaps paying $200 million<br>
15
Frames in the winner’s curse Bidders who frame auctions correctly are aware of the winners’ curse
Therefore, they scale back their bids below their estimates
Bidders who frame to auction incorrectly commit a framing error, failing to scale back their bids and likely cursed with overpayment when their bids turn out to be the winning ones<br>
Therefore, they scale back their bids below their estimates
Bidders who frame to auction incorrectly commit a framing error, failing to scale back their bids and likely cursed with overpayment when their bids turn out to be the winning ones<br>
16
Framing and the winner’s curse Question:
The winner’s curse can occur in a “sealed first-price auction,” also known as a “blind auction,” and as “first-price sealed-bid auction”
How is this type of auction different from an “English auction,” also known as “open ascending price auction”?
How does an English auction protect bidders against the winner’s curse?<br>
17
Frames in the money illusion Framing shortcuts turn into framing errors in the money illusion, where we use nominal units of money in place of “real” - inflation-adjusted - units of money
A 2% nominal pay raise when inflation is at 3% is a 1% real pay cut, whereas a 1% nominal pay raise when inflation is at zero is a 1% real pay raise
Yet we often perceive the first as better than the second because we frame pay cuts and raises in nominal money units where a 2% raise is better than a 1% raise, rather than in real money units where a 1% cut is worse than a 1% raise<br>
18
Frames in the money illusion People are compelled to overcome money illusion when gaps between nominal money units and real ones grow big and have major life consequences
Inflation in Israel increased to 111% in 1979 and 445% in 1984
Israelis responded by pricing everything in American dollars, from houses to cars and many less costly items
Yet in the process of overcoming one money illusion Israelis succumbed to another, albeit smaller, money illusion as they overlooked inflation in the U.S. That inflation was at 11.3% in 1979 and 4.3% in 1984<br>
19
Frames in the money illusion Question:
Ann and Barbara graduated from the same college a year apart
Upon graduation, both took similar jobs with publishing firms
Ann started with a yearly salary of $50,000
During her first year on the job there was no inflation, and in her second year Ann received a 2% ($1,000) raise in salary
Barbara also started with a yearly salary of $50,000
During her first year on the job there was 4% inflation, and in her second year Barbara received a 5% ($2,500) raise in salary.
As they entered their second year on the job, who was doing better in economic terms? Why?
As they entered their second year on the job, who do you think was happier? Why?
As they entered their second year on the job, each received a job offer from another firm. Who do you think was more likely to leave her present position for another job? Why?<br>
20
Hindsight shortcuts and errors We use hindsight shortcuts when we predict future events from past event, and when we predict outcomes of actions
We use hindsight shortcuts well when we can reliably predict future events from past event and when we can reliably predict outcomes of actions
We commit hindsight errors when we believe, erroneously, that we can reliably predict future events from past event, and when we believe, erroneously, that we can predict reliably outcomes of actions<br>
21
Hindsight shortcuts and errors Good hindsight shortcuts lead us to repeat actions that brought good outcomes and avoid actions that brought bad ones
We did favors for friends and they subsequently returned them
We learned that reciprocated favors are the likely outcomes of doing favors
Hindsight shortcuts can turn into hindsight errors, however, where randomness and luck are prominent, loosening associations between past events and future events and between actions and outcomes<br>
22
Hindsight shortcuts and errors Fast driving when luck is good gets us faster to our destination, but fast driving when luck is bad gets us a speeding ticket or worse
Hindsight errors can mislead lucky drivers into thinking that fast driving always gets them to their destinations more quickly, and mislead unlucky drivers into thinking that fast driving always gets them a speeding ticket
Hindsight errors also mislead lucky traders into thinking that fast trading always gets them to their profit destinations more quickly and mislead unlucky traders into thinking that fast trading always inflicts losses<br>
23
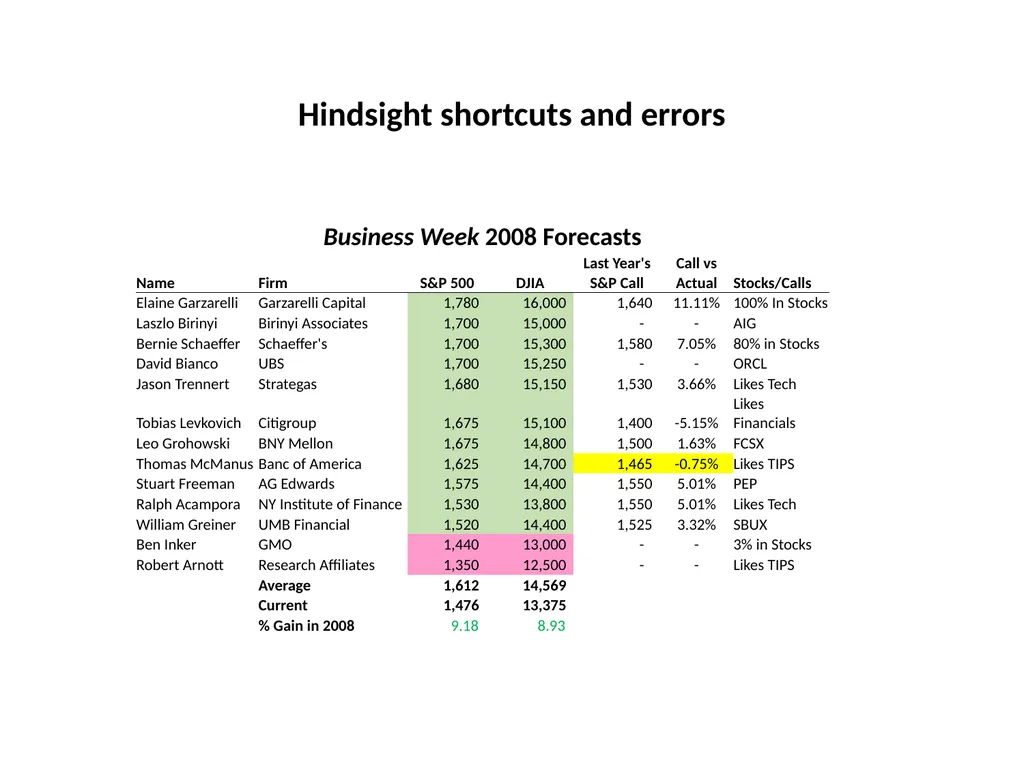
Hindsight shortcuts and errors<br>
24
Hindsight shortcuts and errors Question:
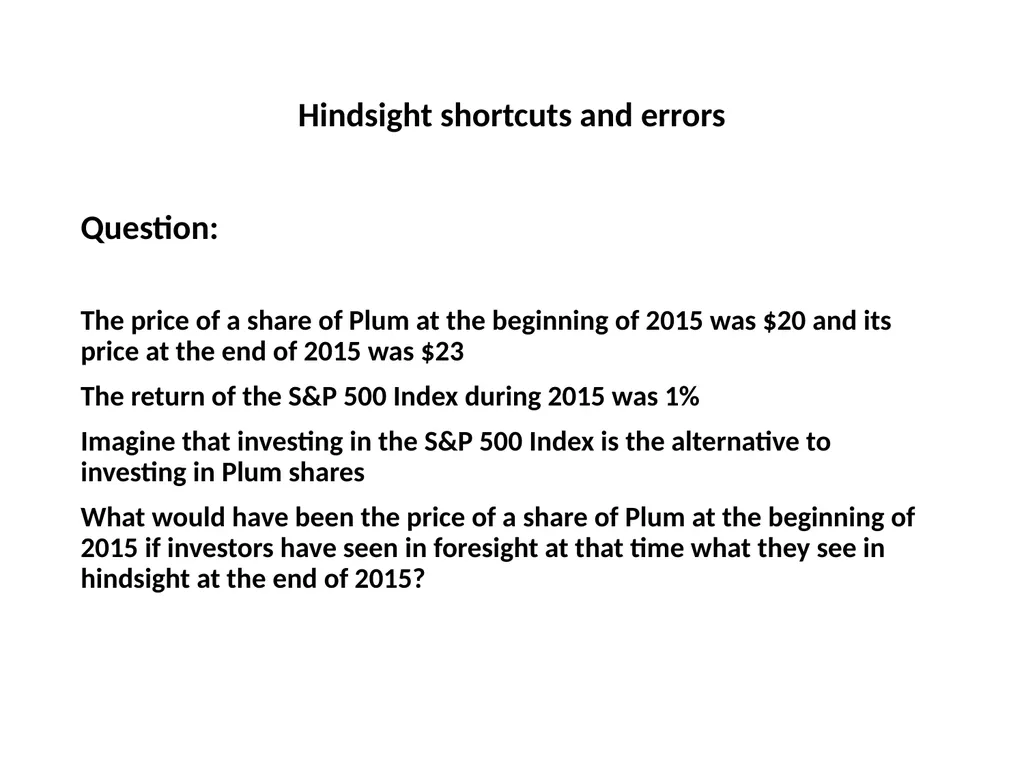
The price of a share of Plum at the beginning of 2015 was $20 and its price at the end of 2015 was $23
The return of the S&P 500 Index during 2015 was 1%
Imagine that investing in the S&P 500 Index is the alternative to investing in Plum shares
What would have been the price of a share of Plum at the beginning of 2015 if investors have seen in foresight at that time what they see in hindsight at the end of 2015?<br>
25
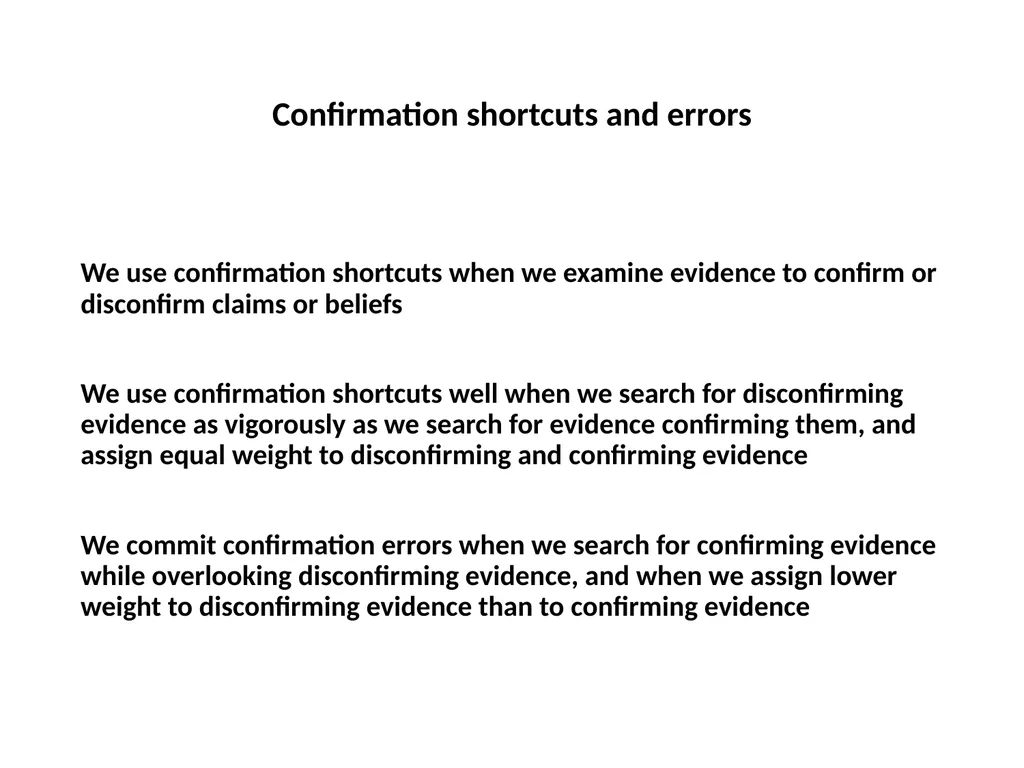
Confirmation shortcuts and errors We use confirmation shortcuts when we examine evidence to confirm or disconfirm claims or beliefs
We use confirmation shortcuts well when we search for disconfirming evidence as vigorously as we search for evidence confirming them, and assign equal weight to disconfirming and confirming evidence
We commit confirmation errors when we search for confirming evidence while overlooking disconfirming evidence, and when we assign lower weight to disconfirming evidence than to confirming evidence<br>
26
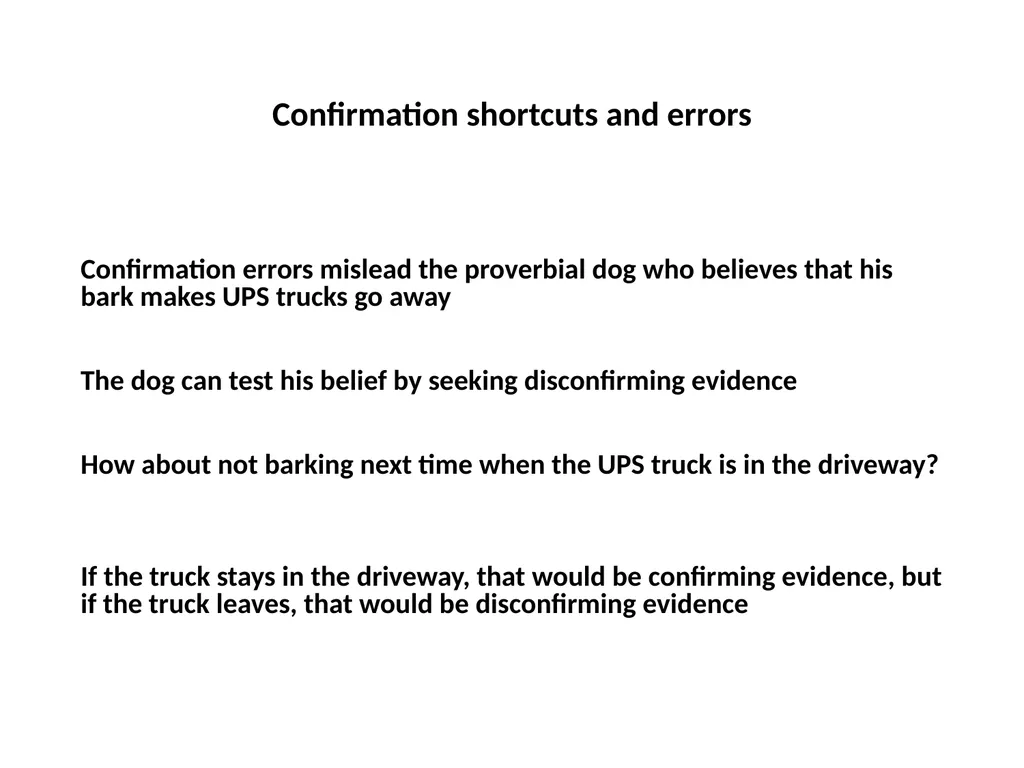
Confirmation shortcuts and errors Confirmation errors mislead the proverbial dog who believes that his bark makes UPS trucks go away
The dog can test his belief by seeking disconfirming evidence
How about not barking next time when the UPS truck is in the driveway?
If the truck stays in the driveway, that would be confirming evidence, but if the truck leaves, that would be disconfirming evidence<br>
The dog can test his belief by seeking disconfirming evidence
How about not barking next time when the UPS truck is in the driveway?
If the truck stays in the driveway, that would be confirming evidence, but if the truck leaves, that would be disconfirming evidence<br>
27
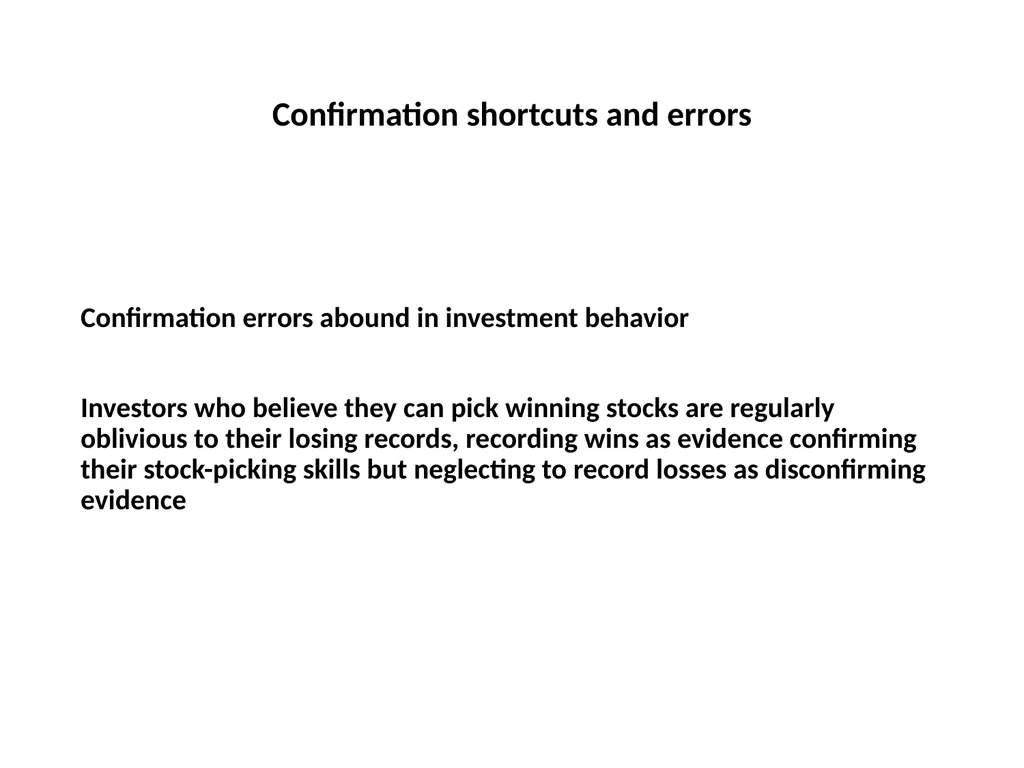
Confirmation shortcuts and errors Confirmation errors abound in investment behavior
Investors who believe they can pick winning stocks are regularly oblivious to their losing records, recording wins as evidence confirming their stock-picking skills but neglecting to record losses as disconfirming evidence<br>
Investors who believe they can pick winning stocks are regularly oblivious to their losing records, recording wins as evidence confirming their stock-picking skills but neglecting to record losses as disconfirming evidence<br>
28
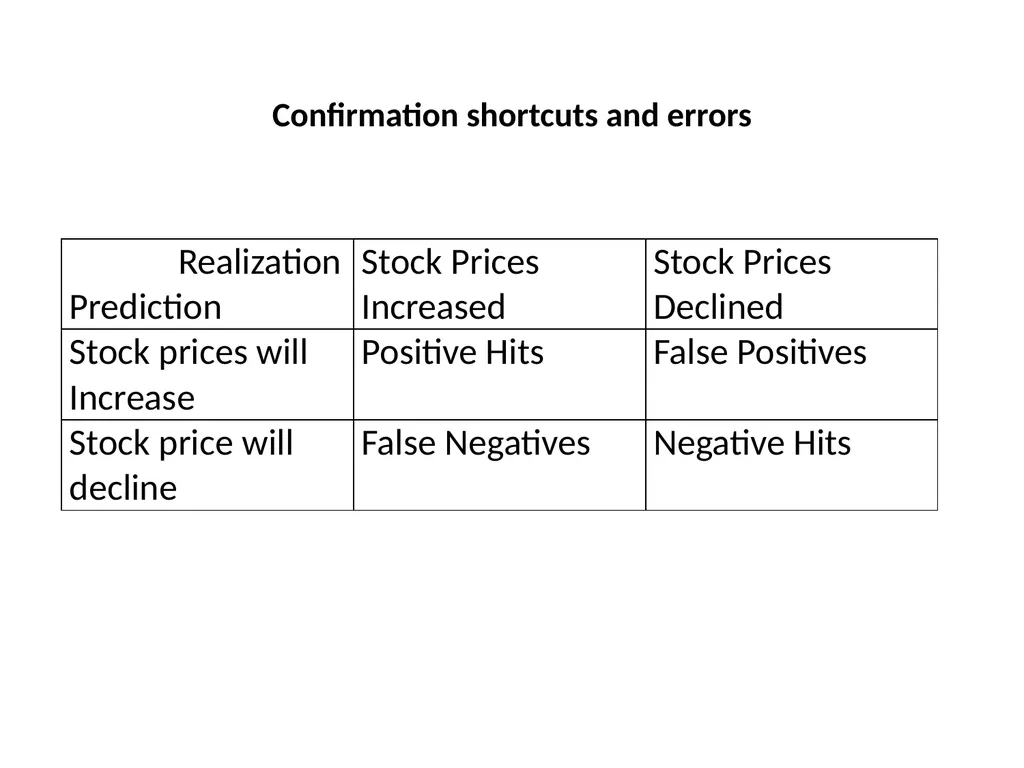
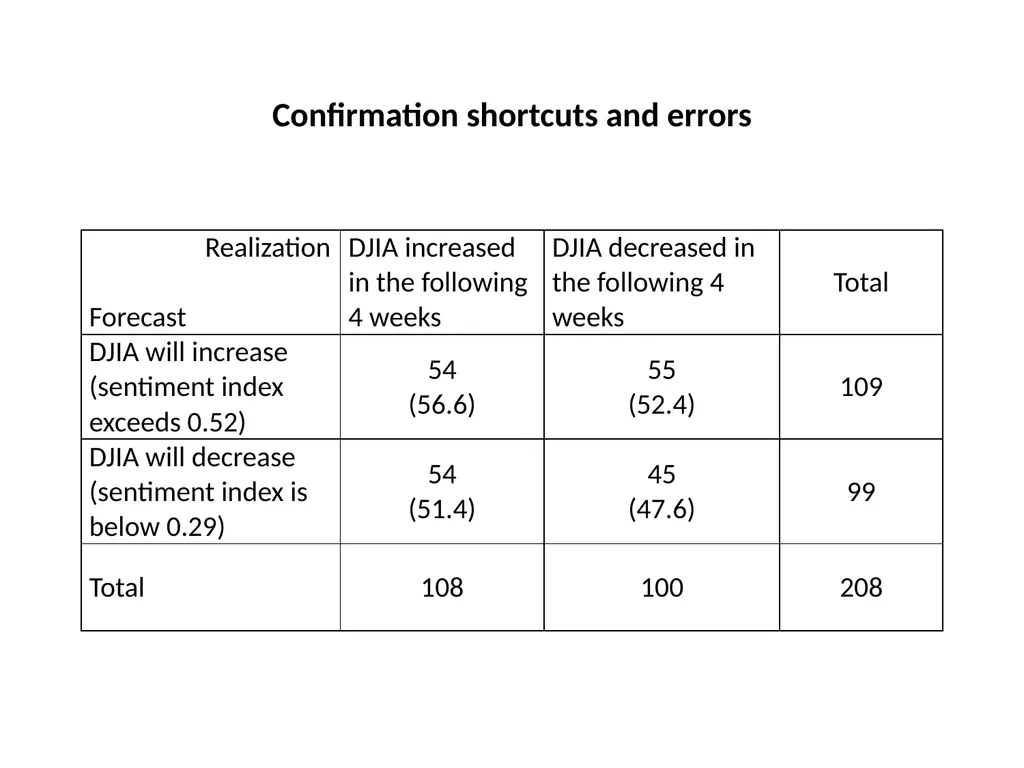
Confirmation shortcuts and errors Confirmation errors are evident in assessment of the usefulness of trading rules
One such rule is based on the Bearish Sentiment Index, compiled from stock market recommendations of writers of investment newsletters
The Bearish Sentiment Index is the ratio of the number of writers of investment newsletters who are bearish, expecting stock-market declines, to the number of writers expressing an opinion, bullish or bearish, about the stock-market’s future direction
A contrarian use of the Bearish Sentiment Index calls for buying stocks when bearish sentiment is high and selling when it is low<br>
29
Confirmation shortcuts and errors<br>
30
Confirmation shortcuts and errors<br>
31
Anchoring and adjustment shortcuts and errors We use anchoring and adjustment shortcuts when we estimate prices, distances, weights, and other numerical values
We use anchoring and adjustment shortcuts well when we begin with proper anchors and adjust from them properly
We commit anchoring and adjustment errors when we begin with faulty anchors and adjust from them improperly<br>
We use anchoring and adjustment shortcuts well when we begin with proper anchors and adjust from them properly
We commit anchoring and adjustment errors when we begin with faulty anchors and adjust from them improperly<br>
32
Anchoring and adjustment shortcuts and errors We begin the process of estimating the value of a house for sale by finding the average price of houses sold recently in the same neighborhood
We use that average price as an anchor and adjust our value estimate up or down to account for the fact that this house has four bedrooms, whereas the average house has only three, and the fact that this house is situated on a less desirable street than the average house<br>
We use that average price as an anchor and adjust our value estimate up or down to account for the fact that this house has four bedrooms, whereas the average house has only three, and the fact that this house is situated on a less desirable street than the average house<br>
33
Anchoring and adjustment shortcuts and errors The S&P 500 Index increased at an annualized rate of 5.836% during the 90 years from the end of December 31, 1925 to the end of December 31, 2015
The S&P 500 Index does not include dividends and their reinvestment
Suppose that you invested $1,000 in the S&P 500 Index at the end of December 31, 1925
You would have had $162,820 by the end of December 31, 2015 if you spent all dividends when you received them during the period
1,000 x (1+0.05836)**90=$162,820<br>
34
Anchoring and adjustment shortcuts and errors Question:
Now suppose that you invested $1,000 in the S&P 500 Index at the end of December 31, 1925, and reinvested the dividends during the entire 90-year period, rather than spend them
The annualized rate when dividends and their reinvestment are included during the period was 9.980%.
What is your guess (not calculation) of the amount you would have had at the end of December 31, 2015?
Now calculate the amount
How similar is the calculated amount to your guessed amount?<br>
35
Representativeness shortcuts and errors We use representativeness shortcuts when we assess the probability of events by their similarity or representativeness to other events
We use representativeness shortcuts well when we consider both representativeness-information and base-rate information
We commit representativeness errors when we assign too much weight to representativeness information and too little to base-rate information<br>
We use representativeness shortcuts well when we consider both representativeness-information and base-rate information
We commit representativeness errors when we assign too much weight to representativeness information and too little to base-rate information<br>
36
Representativeness shortcuts and errors You received a call from a telemarketer interrupting your dinner with an offer of a free trip
Do you listen to the entire pitch or do you quickly put down the phone?<br>
Do you listen to the entire pitch or do you quickly put down the phone?<br>
37
Representativeness shortcuts and errors As you make your decision to listen or quit, you properly take into account two pieces of information
First is representativeness information—how representative is this particular telemarketer of the group of telemarketers who were worth listening to
Second is base-rate information—the proportion of the many telemarketers who have interrupted our dinners yet were worth listening to
You put down the phone because base-rate information tells you that few sales pitches are worth listening to, even though the voice of this particular telemarketer is pleasant<br>
38
Representativeness shortcuts and errors Elizabeth Holmes established a company, Theranos, offering a technology whereby a wide range of laboratory tests can be performed on a tiny sample of blood from a finger prick, eliminating the need for intravenous blood draws
The company raised more than $400 million in venture capital and Holmes’ personal stake amounted to $4.5 billion
Subsequently, doubts were raised about the effectiveness of the technology and the viability of the company<br>
The company raised more than $400 million in venture capital and Holmes’ personal stake amounted to $4.5 billion
Subsequently, doubts were raised about the effectiveness of the technology and the viability of the company<br>
39
Representativeness shortcuts and errors “Like Bill Gates, Steve Jobs and Mark Zuckerberg, Ms. Holmes dropped out of college
Like Steve Jobs, she wears a uniform of black turtlenecks, suggesting she has loftier things to think about than what to wear...
Like Mr. Jobs, she's picky about her diet…
And like Google's co-founders, Larry Page and Sergey Brin (Don't Be Evil), and Mark Zuckerberg (Connect the World), her mission is lofty…“One tiny drop changes everything"
But investors in Holmes’ Theranos might have neglected to examine base-rate information, the ratio of the number of ventures that fail to the number of ventures that succeed as much as those of Bill Gates, Steve Jobs, Mark Zuckerberg, and Larry Page and Sergey Brin<br>
40
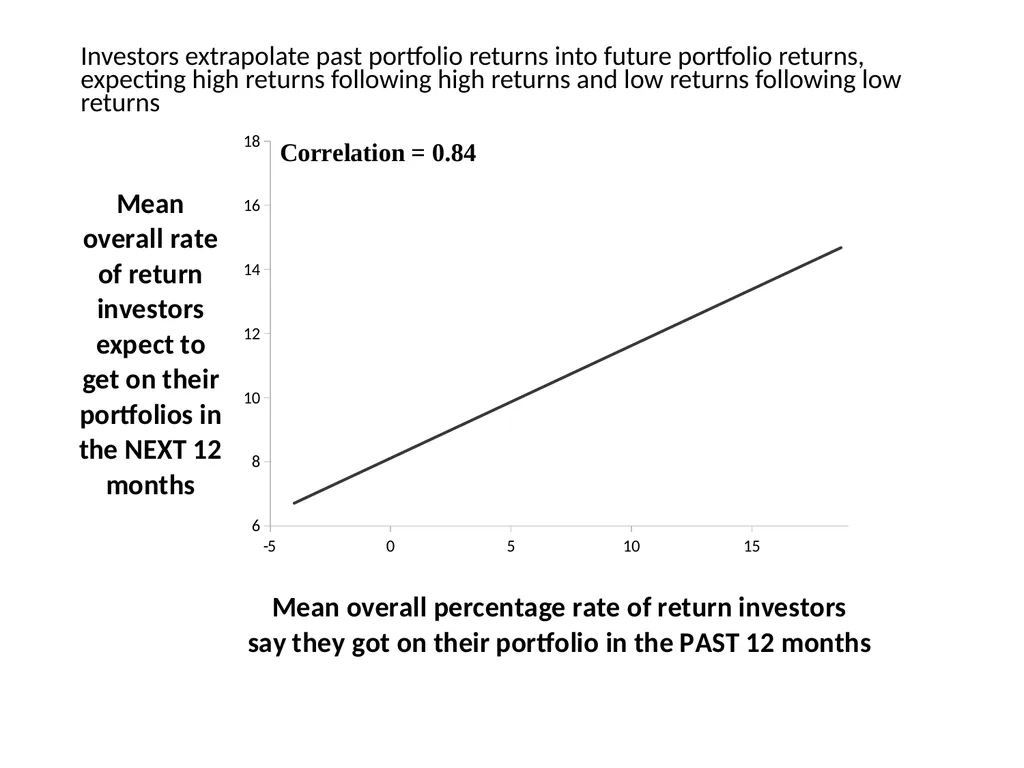
Investors extrapolate past portfolio returns into future portfolio returns, expecting high returns following high returns and low returns following low returns<br>
41
Representativeness shortcuts and errors Imagine that you toss a coin 10 times in a row
Write down your guess of a typical sequence of heads and tails
(Mark H for heads and T for tails)<br>
Write down your guess of a typical sequence of heads and tails
(Mark H for heads and T for tails)<br>
42
Representativeness shortcuts and errors Now toss a coin 10 times in a row and write down the outcome of each toss as H or T.
Compare the number of “reversals” in the guessed toss and the actual toss
A reversal is H followed by T, or T followed by H
For example, HHHTTH has 2 reversals
How does the number of reversals in your guessed sequence differ from the number of reversals in your actual sequence?
What does the difference tell you about what we see as representative of a random sequence?<br>
43
Representativeness shortcuts and errors Question
Which of the following is more likely, a or b? Why?
a. A war between the U.S. and Iran
b. Neither the U.S. nor Iran intended to attack the other, but Israeli Air Force jets blew up nuclear facilities in Bushehr, Fordow, and Natanz. Iran responded with a barrage of Hezbollah rockets in northern Israel and Hamas rained rockets on Tel Aviv. American embassies were torched in Paris and Berlin, and the American ambassador in Japan was assassinated, drawing the U.S. into a war with Iran<br>
Which of the following is more likely, a or b? Why?
a. A war between the U.S. and Iran
b. Neither the U.S. nor Iran intended to attack the other, but Israeli Air Force jets blew up nuclear facilities in Bushehr, Fordow, and Natanz. Iran responded with a barrage of Hezbollah rockets in northern Israel and Hamas rained rockets on Tel Aviv. American embassies were torched in Paris and Berlin, and the American ambassador in Japan was assassinated, drawing the U.S. into a war with Iran<br>
44
Representativeness shortcuts and errors Question:
A certain town is served by two hospitals
In the larger hospital about 45 babies are born each day, and in the smaller hospital about 15 babies are born each day
As you know, about 50% of all babies are boys, but the exact percentage varies from day to day
Sometimes it is higher than 50%, sometimes lower<br>
A certain town is served by two hospitals
In the larger hospital about 45 babies are born each day, and in the smaller hospital about 15 babies are born each day
As you know, about 50% of all babies are boys, but the exact percentage varies from day to day
Sometimes it is higher than 50%, sometimes lower<br>
45
Representativeness shortcuts and errors Question:
For a period of 1 year, each hospital recorded the days on which more than 60% of the babies born were boys
Which hospital do you think recorded more such days?
a. The larger hospital
b. The smaller hospital
c. About the same (that is, within 5% of each other)<br>
For a period of 1 year, each hospital recorded the days on which more than 60% of the babies born were boys
Which hospital do you think recorded more such days?
a. The larger hospital
b. The smaller hospital
c. About the same (that is, within 5% of each other)<br>
46
Availability shortcuts and errors We use availability shortcuts when we assess the probability of events by information that is readily available in our minds
We use availability shortcuts well when all the information is available in our minds, or when we are aware that not all the information is available in our minds
We commit availability errors when not all the information is available in our minds, but or we are not aware of its absence<br>
We use availability shortcuts well when all the information is available in our minds, or when we are aware that not all the information is available in our minds
We commit availability errors when not all the information is available in our minds, but or we are not aware of its absence<br>
47
Availability shortcuts and errors We use availability shortcuts when we assess the probability that our airplane would arrive on time by retrieving from our minds the proportion of our flights that have arrived on time, yet aware that the proportion among all flights is likely different.
We commit availability errors when we assess that probability by our flight experience, yet unaware that the proportion among all flights is likely different<br>
We commit availability errors when we assess that probability by our flight experience, yet unaware that the proportion among all flights is likely different<br>
48
Availability shortcuts and errors We commit availability errors when our retrieval process is biased, as when friends who beat the market share their stories with us but friends who lag the market do not
And we commit availability errors when our search processes are ineffective, as when we fail to search the performance records of all funds, not only those readily available in our minds<br>
And we commit availability errors when our search processes are ineffective, as when we fail to search the performance records of all funds, not only those readily available in our minds<br>
49
Confidence shortcuts and errors Confidence shortcuts and errors are of three types – estimation shortcuts and errors, placement shortcuts and errors, and precision shortcuts and errors
We use confidence shortcuts well in estimation, placement, and precision when we assess them objectively and place objective confidence in them
We commit overconfidence errors when we place too much confidence in them, and we commit underconfidence errors when we place too little confidence in them<br>
50
Confidence shortcuts and errors We commit overestimation errors if we expect a 12% portfolio return when objective assessment indicates that its expected return is 8%
We commit underestimation errors if we expect a 6% portfolio return<br>
We commit underestimation errors if we expect a 6% portfolio return<br>
51
Confidence shortcuts and errors We commit overplacement errors if we expect our portfolio return to place us among the top 10% of investor, when objective assessment would place us among the bottom 40%
We commit underplacement errors if we expect our return to place us among the bottom 30%<br>
We commit underplacement errors if we expect our return to place us among the bottom 30%<br>
52
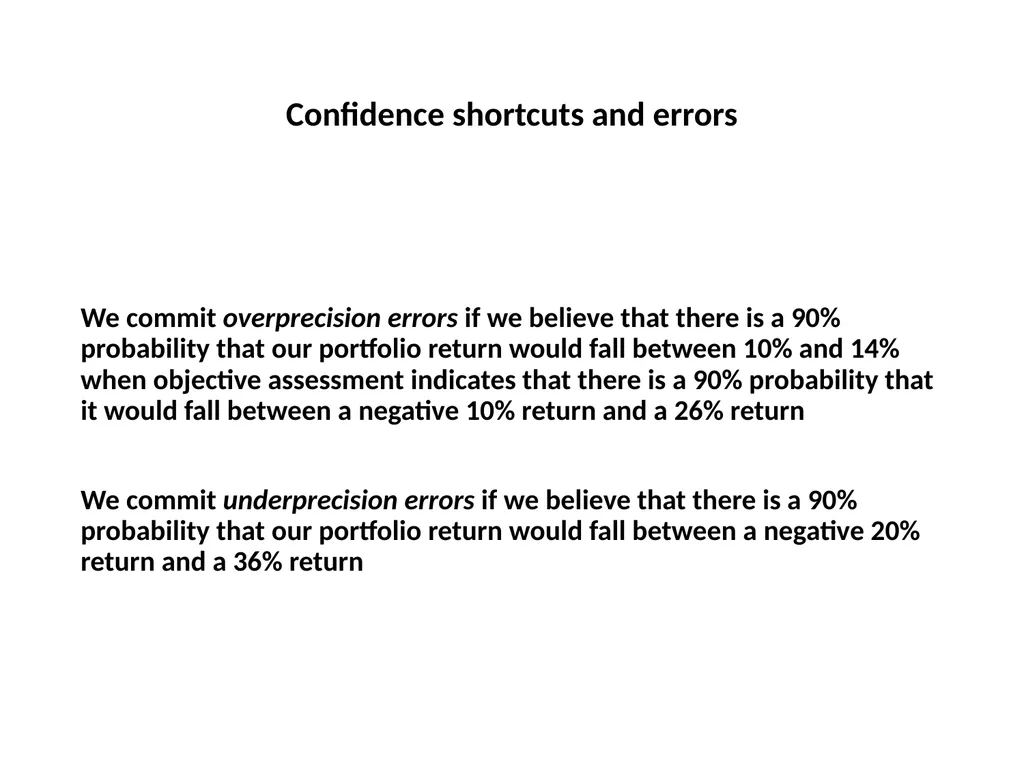
Confidence shortcuts and errors We commit overprecision errors if we believe that there is a 90% probability that our portfolio return would fall between 10% and 14% when objective assessment indicates that there is a 90% probability that it would fall between a negative 10% return and a 26% return
We commit underprecision errors if we believe that there is a 90% probability that our portfolio return would fall between a negative 20% return and a 36% return<br>
We commit underprecision errors if we believe that there is a 90% probability that our portfolio return would fall between a negative 20% return and a 36% return<br>
53
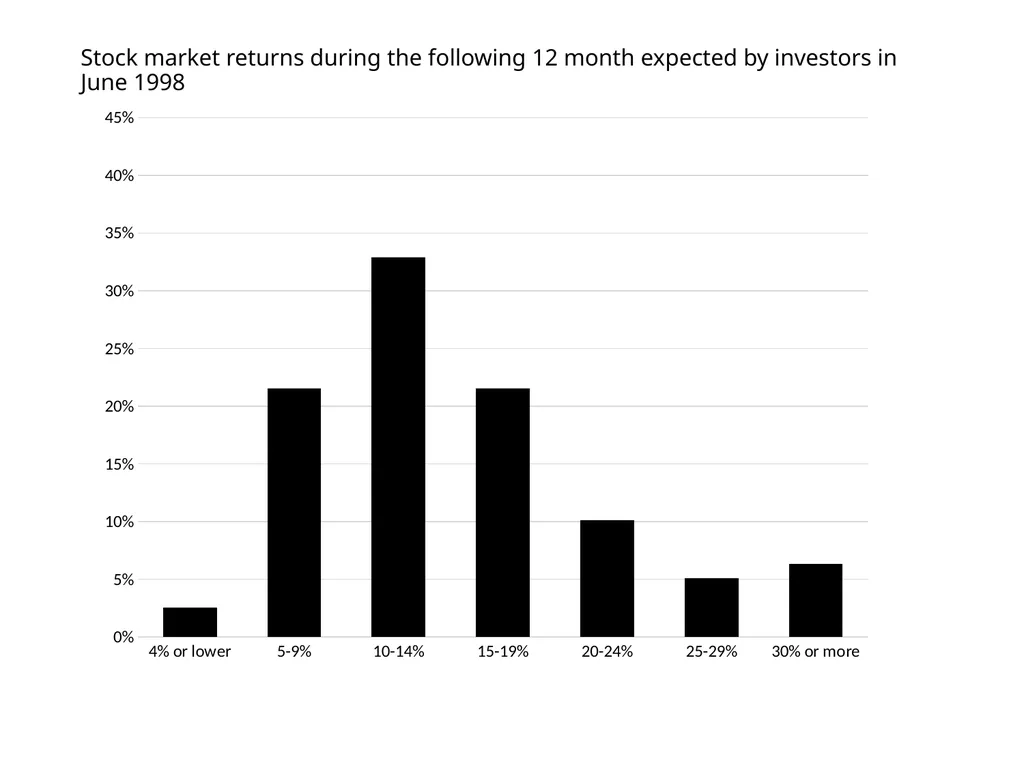
Stock market returns during the following 12 month expected by investors in June 1998<br>
54
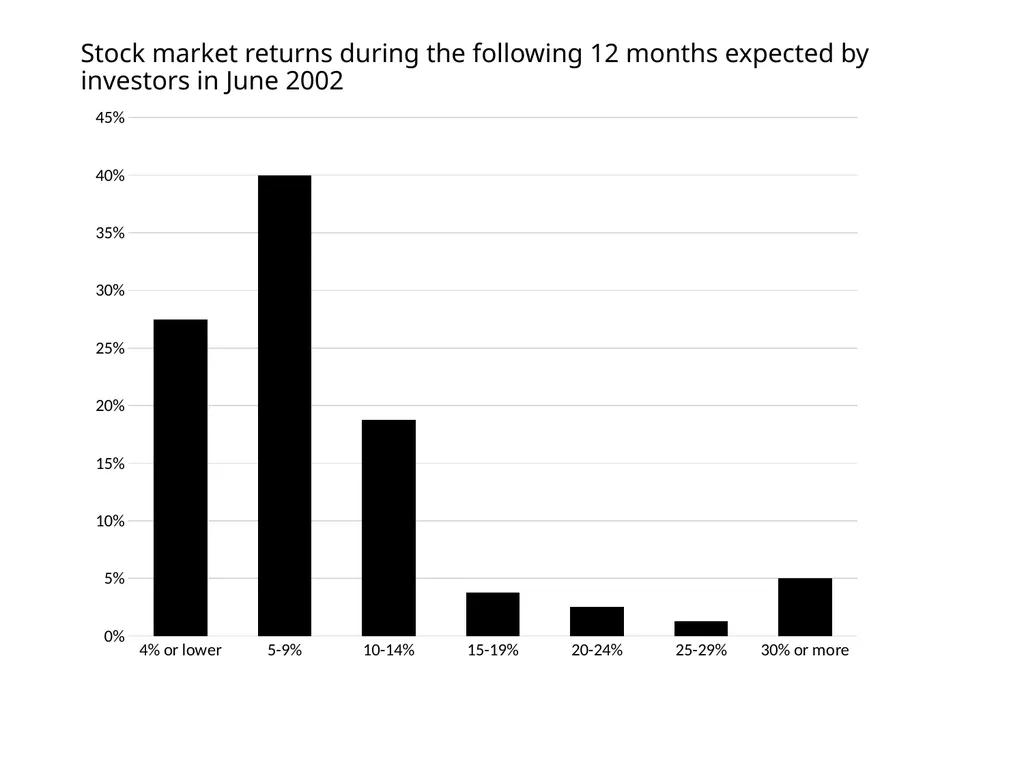
Stock market returns during the following 12 months expected by investors in June 2002<br>
55
6-month moving median of investors’ expectations of returns of their own portfolios and the stock market<br>
56
Confidence shortcuts and errors Question:
Do you think that your skills at juggling 3 oranges places you above or below average among amateur jugglers of 3 oranges?
Do you think that your skills at driving a car place you above or below average among drivers of your age?
Do you think that your skills at selecting investments with high returns place you at above or below investors of your age and level of formal education?<br>
57
Confidence shortcuts and errors Question:
Rank the tasks of juggling, driving, and selecting investments with high returns, by their difficulty, from easiest to most difficult.
How is task-difficulty associated with tendencies for overplacement and underplacement?<br>
Rank the tasks of juggling, driving, and selecting investments with high returns, by their difficulty, from easiest to most difficult.
How is task-difficulty associated with tendencies for overplacement and underplacement?<br>
58
Confidence shortcuts and errors Consider traveling to a job interview for a job you would really like to have
On average, it takes 30 minutes to get there (including time necessary to park your car and find the office where the interview is to be conducted)
The lower bound of a 99% confidence interval of travel time is 20 minutes, and the higher bound is 80 minutes
How long before the interview time do you begin to drive?<br>
59
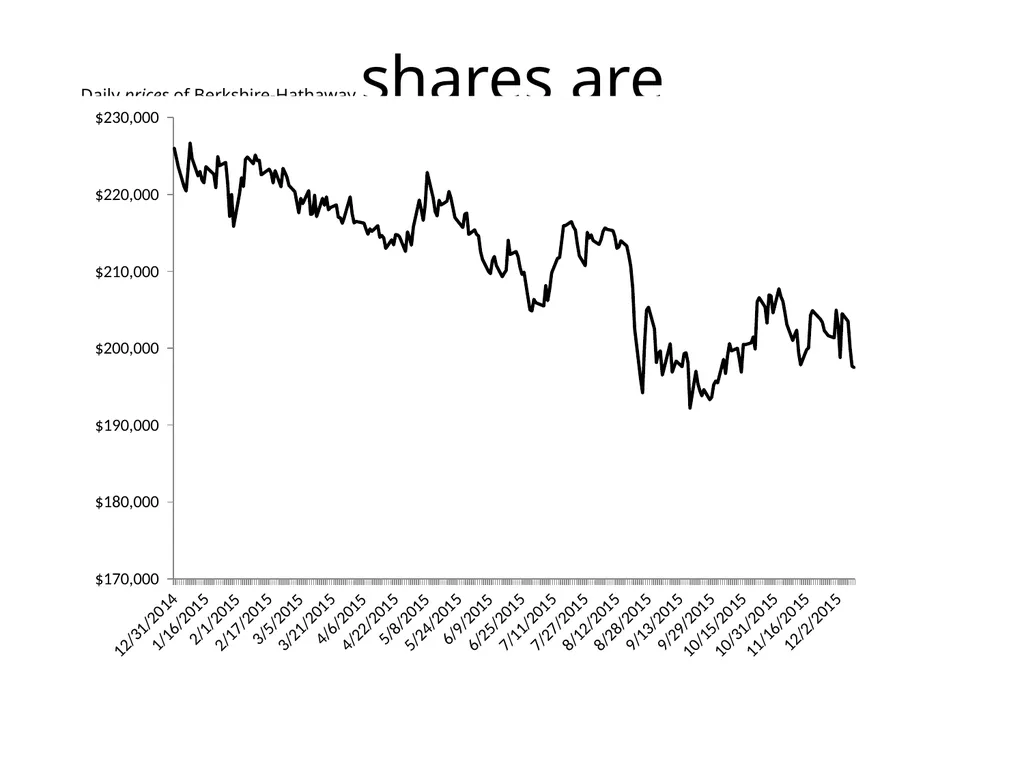
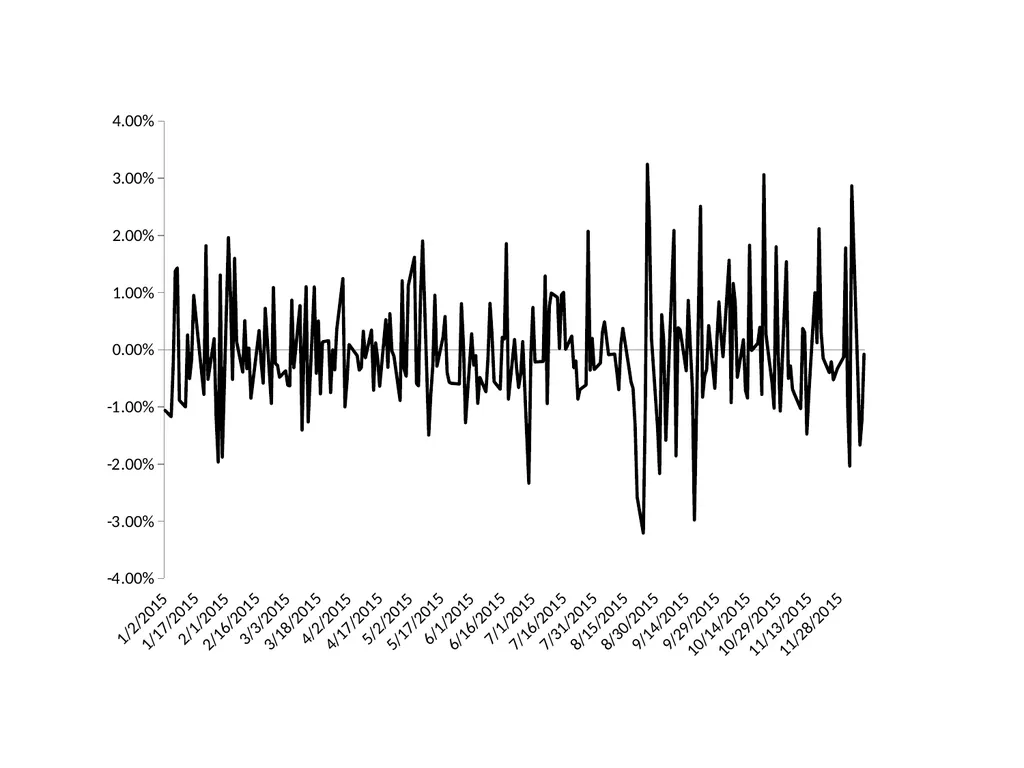
Daily prices of Berkshire-Hathaway shares are representative of a pattern<br>