
SICCFIN Supervisory Findings (FIs) 18 April 2023

Description: SICCFIN Supervisory Findings (FIs) 18 April 2023 Importance of feedback on Supervisory Findings Ensure clear line of communication Highlight common weaknesses Promote understanding of MLTF risks Awareness of any emerging risks Understand
Related Topics
Download Presentation
"SICCFIN Supervisory Findings (FIs) 18 April 2023" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. SICCFIN Supervisory Findings (FIs) 18 April 2023<br>
slide2. Importance of feedback on Supervisory Findings Ensure clear line of communication
Highlight common weaknesses
Promote understanding of ML/TF risks
Awareness of any emerging risks
Understand the expectations of SICCFIN
SICCFIN will inspect whether such findings have been considered as part of compliance framework
Review own internal framework and identify if any improvements required
Improve level of compliance across all sectors
Avoid supervisory action © Financial Transparency Advisors<br>
slide3. Supervisory Findings to be issued by SICCFIN Inspection Report
Supervisory Findings Paper will be issued by SICCFIN at end of 2023/early 2024
Also discussed during outreach events, workshops and meetings with FIs
Supervisory findings also inform targeted guidance issued by SICCFIN © Financial Transparency Advisors<br>
slide4. Basis for Supervisory Findings From Supervisory Engagement:
E.g…..
On-site examinations
Thematic reviews
Risk and compliance meetings
Also:
Data Questionnaires, Returns etc submitted to SICCFIN by FIs.
Strix Questionnaires © Financial Transparency Advisors<br>
slide5. Supervisory Findings Some examples of common findings in FIs …… © Financial Transparency Advisors<br>
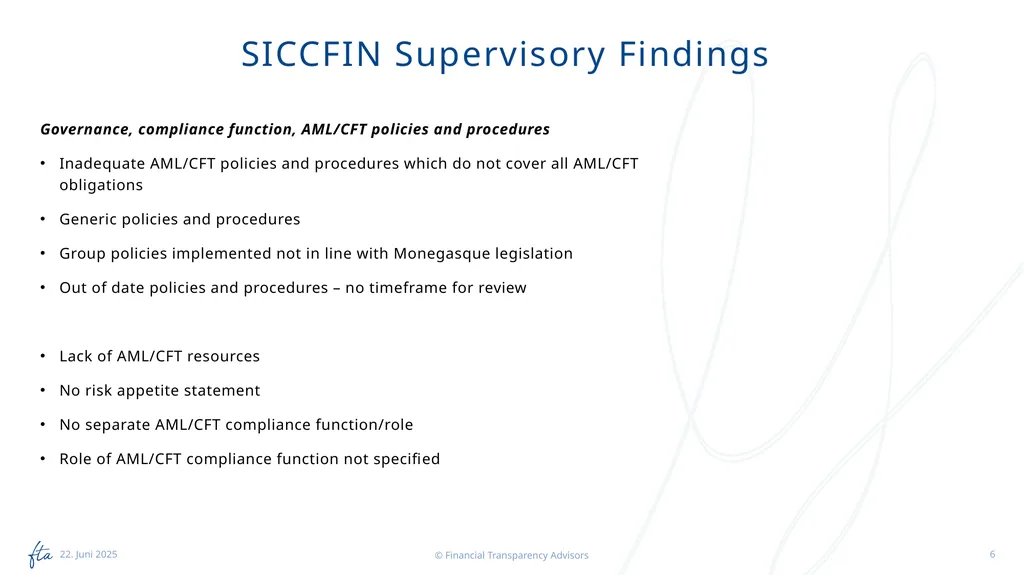
slide6. SICCFIN Supervisory Findings Governance, compliance function, AML/CFT policies and procedures
Inadequate AML/CFT policies and procedures which do not cover all AML/CFT obligations
Generic policies and procedures
Group policies implemented not in line with Monegasque legislation
Out of date policies and procedures – no timeframe for review
Lack of AML/CFT resources
No risk appetite statement
No separate AML/CFT compliance function/role
Role of AML/CFT compliance function not specified © Financial Transparency Advisors<br>
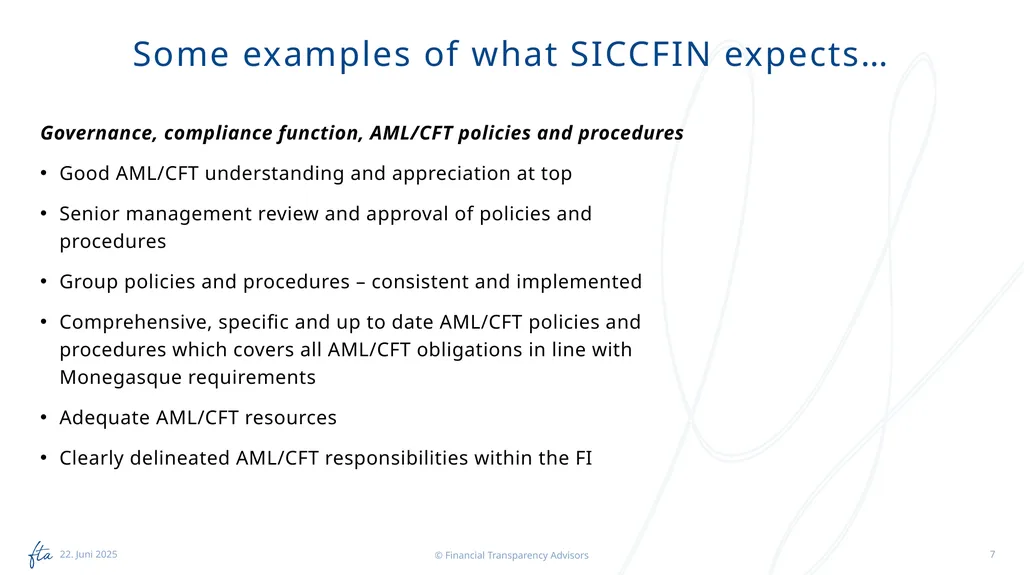
slide7. Some examples of what SICCFIN expects… Governance, compliance function, AML/CFT policies and procedures
Good AML/CFT understanding and appreciation at top
Senior management review and approval of policies and procedures
Group policies and procedures – consistent and implemented
Comprehensive, specific and up to date AML/CFT policies and procedures which covers all AML/CFT obligations in line with Monegasque requirements
Adequate AML/CFT resources
Clearly delineated AML/CFT responsibilities within the FI © Financial Transparency Advisors<br>
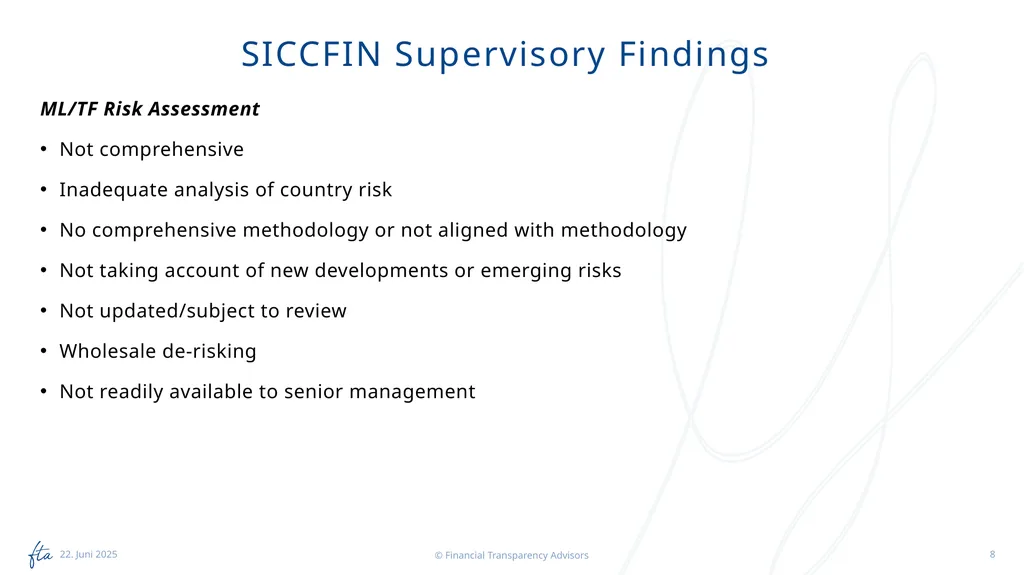
slide8. SICCFIN Supervisory Findings ML/TF Risk Assessment
Not comprehensive
Inadequate analysis of country risk
No comprehensive methodology or not aligned with methodology
Not taking account of new developments or emerging risks
Not updated/subject to review
Wholesale de-risking
Not readily available to senior management © Financial Transparency Advisors<br>
slide9. Some examples of what SICCFIN expects…. ML/TF Risk Assessment
Comprehensive ML/TF risk assessment
Regularly reviewed and updated
Take into account core risk factors: customer risk, product, service and transaction risk, geographic risk, delivery channel risk.
Comprehensive methodology
Conclusions supported by quantitative and qualitative data
Consideration of TFS (TF and PF)
ML and TF risks differentiated
New and emerging risks assessed
Approval by Senior management © Financial Transparency Advisors<br>
slide10. SICCFIN Supervisory Findings Customer Risk Profile
No customer risk profiles/incomplete risk profiling/ inadequate risk profiling
Inadequate risk ratings of high risk customers
No review of customer risk profile following a change
No regular review of customer risk profiles
No access to customer risk ratings by first line of defence staff © Financial Transparency Advisors<br>
slide11. Some examples of what SICCFIN expects…… Customer Risk Profile
Clear criteria for customer risk assessments
Documented
Scope of CDD and monitoring based on customer risk profile
Frequency and scope of CDD review based on risk profile and approved list of triggers © Financial Transparency Advisors<br>
slide12. SICCFIN Supervisory Findings CDD
Incomplete CDD gathered
Failure to identify the BO
No screening of customers
Third party CDD
No/insufficient procedures in place to identify and verify if a BO of a legal entity is a PEP, family member or close associate © Financial Transparency Advisors<br>
slide13. Some examples of what SICCFIN expects….. CDD
Full CDD gathered
Sanction, PEP and negative media screening prior to establishing business relationship
Clear procedure to identify and verify BO
EDD
Documentary evidence on SOW and SOF in high risk situations
Review © Financial Transparency Advisors<br>
slide14. SICCFIN Supervisory Findings Ongoing monitoring and identification of suspicious activity
Ongoing monitoring not conducted
Failure to identify repeated transactions
Insufficient handling of alerts
Failure to update customer profile and customer due diligence with details received during assessment or investigations.
No documentation re closure of alerts © Financial Transparency Advisors<br>
slide15. SICCFIN Supervisory Findings Ongoing monitoring and identification of suspicious activity
No RBA for scenarios
No visibility by FI on alerts and their processing
Number of false positive alerts not clear
Inadequate screening at onboarding stage
Infrequent screening of customers and transactions
No training/inadequate training on screening tool
Delay in resolving/processing sanction screening alerts © Financial Transparency Advisors<br>
slide16. Some examples of what SICCFIN expects….. Ongoing monitoring and identification of suspicious activity
Customers subjected to ongoing monitoring in line with RBA.
Enhanced monitoring where required
Monitoring scenarios adapted in line with risk
Comprehensive analysis of potentially suspicious transactions
Adequate human resources for monitoring © Financial Transparency Advisors<br>
slide17. SICCFIN Supervisory Findings Suspicious Transaction Reporting
Failure to report
Inordinate delays in reporting
Failure to update customer profile and customer due diligence with details received during assessment or investigations.
No documentary evidence for closure of alerts © Financial Transparency Advisors<br>
slide18. Some examples of what SICCFIN expects…. Suspicious Transaction Reporting
Structured internal process to report suspicious transactions
Documented
Attempted and completed transactions
Written procedure to avoid tipping off - which is followed
Specific indicators and red flags
Timely responses to requests for further information
Training on suspicious transaction reporting © Financial Transparency Advisors<br>
slide19. SICCFIN Supervisory Findings Training and Human Resources
No training/training not conducted on regular basis/long time since previous training was conducted.
Training not specific
Training not included in policies and procedures
Not specific or comprehensive enough
Lack of focus on TF
Lack of AML/CFT resources
Submission of Reports to SICCFIN
Very poor © Financial Transparency Advisors<br>
slide20. Some examples of what SICCFIN expects…. Training and Human Resources
Comprehensive training which is conducted on regular basis
Specific and targeted to role
Documented record of training
Specific training for senior management and Board members
Training included in policies and procedures
Adequate AML/CFT resources
Submission of Reports to SICCFIN
Must be submitted by all FIs © Financial Transparency Advisors<br>
slide21. What FI’s need to do now…. Have regard to these findings and review own internal AML/CFT control framework to identify if any improvements required. © Financial Transparency Advisors<br>
slide22. Thank You © Financial Transparency Advisors<br>
slide2. Importance of feedback on Supervisory Findings Ensure clear line of communication
Highlight common weaknesses
Promote understanding of ML/TF risks
Awareness of any emerging risks
Understand the expectations of SICCFIN
SICCFIN will inspect whether such findings have been considered as part of compliance framework
Review own internal framework and identify if any improvements required
Improve level of compliance across all sectors
Avoid supervisory action © Financial Transparency Advisors<br>
slide3. Supervisory Findings to be issued by SICCFIN Inspection Report
Supervisory Findings Paper will be issued by SICCFIN at end of 2023/early 2024
Also discussed during outreach events, workshops and meetings with FIs
Supervisory findings also inform targeted guidance issued by SICCFIN © Financial Transparency Advisors<br>
slide4. Basis for Supervisory Findings From Supervisory Engagement:
E.g…..
On-site examinations
Thematic reviews
Risk and compliance meetings
Also:
Data Questionnaires, Returns etc submitted to SICCFIN by FIs.
Strix Questionnaires © Financial Transparency Advisors<br>
slide5. Supervisory Findings Some examples of common findings in FIs …… © Financial Transparency Advisors<br>
slide6. SICCFIN Supervisory Findings Governance, compliance function, AML/CFT policies and procedures
Inadequate AML/CFT policies and procedures which do not cover all AML/CFT obligations
Generic policies and procedures
Group policies implemented not in line with Monegasque legislation
Out of date policies and procedures – no timeframe for review
Lack of AML/CFT resources
No risk appetite statement
No separate AML/CFT compliance function/role
Role of AML/CFT compliance function not specified © Financial Transparency Advisors<br>
slide7. Some examples of what SICCFIN expects… Governance, compliance function, AML/CFT policies and procedures
Good AML/CFT understanding and appreciation at top
Senior management review and approval of policies and procedures
Group policies and procedures – consistent and implemented
Comprehensive, specific and up to date AML/CFT policies and procedures which covers all AML/CFT obligations in line with Monegasque requirements
Adequate AML/CFT resources
Clearly delineated AML/CFT responsibilities within the FI © Financial Transparency Advisors<br>
slide8. SICCFIN Supervisory Findings ML/TF Risk Assessment
Not comprehensive
Inadequate analysis of country risk
No comprehensive methodology or not aligned with methodology
Not taking account of new developments or emerging risks
Not updated/subject to review
Wholesale de-risking
Not readily available to senior management © Financial Transparency Advisors<br>
slide9. Some examples of what SICCFIN expects…. ML/TF Risk Assessment
Comprehensive ML/TF risk assessment
Regularly reviewed and updated
Take into account core risk factors: customer risk, product, service and transaction risk, geographic risk, delivery channel risk.
Comprehensive methodology
Conclusions supported by quantitative and qualitative data
Consideration of TFS (TF and PF)
ML and TF risks differentiated
New and emerging risks assessed
Approval by Senior management © Financial Transparency Advisors<br>
slide10. SICCFIN Supervisory Findings Customer Risk Profile
No customer risk profiles/incomplete risk profiling/ inadequate risk profiling
Inadequate risk ratings of high risk customers
No review of customer risk profile following a change
No regular review of customer risk profiles
No access to customer risk ratings by first line of defence staff © Financial Transparency Advisors<br>
slide11. Some examples of what SICCFIN expects…… Customer Risk Profile
Clear criteria for customer risk assessments
Documented
Scope of CDD and monitoring based on customer risk profile
Frequency and scope of CDD review based on risk profile and approved list of triggers © Financial Transparency Advisors<br>
slide12. SICCFIN Supervisory Findings CDD
Incomplete CDD gathered
Failure to identify the BO
No screening of customers
Third party CDD
No/insufficient procedures in place to identify and verify if a BO of a legal entity is a PEP, family member or close associate © Financial Transparency Advisors<br>
slide13. Some examples of what SICCFIN expects….. CDD
Full CDD gathered
Sanction, PEP and negative media screening prior to establishing business relationship
Clear procedure to identify and verify BO
EDD
Documentary evidence on SOW and SOF in high risk situations
Review © Financial Transparency Advisors<br>
slide14. SICCFIN Supervisory Findings Ongoing monitoring and identification of suspicious activity
Ongoing monitoring not conducted
Failure to identify repeated transactions
Insufficient handling of alerts
Failure to update customer profile and customer due diligence with details received during assessment or investigations.
No documentation re closure of alerts © Financial Transparency Advisors<br>
slide15. SICCFIN Supervisory Findings Ongoing monitoring and identification of suspicious activity
No RBA for scenarios
No visibility by FI on alerts and their processing
Number of false positive alerts not clear
Inadequate screening at onboarding stage
Infrequent screening of customers and transactions
No training/inadequate training on screening tool
Delay in resolving/processing sanction screening alerts © Financial Transparency Advisors<br>
slide16. Some examples of what SICCFIN expects….. Ongoing monitoring and identification of suspicious activity
Customers subjected to ongoing monitoring in line with RBA.
Enhanced monitoring where required
Monitoring scenarios adapted in line with risk
Comprehensive analysis of potentially suspicious transactions
Adequate human resources for monitoring © Financial Transparency Advisors<br>
slide17. SICCFIN Supervisory Findings Suspicious Transaction Reporting
Failure to report
Inordinate delays in reporting
Failure to update customer profile and customer due diligence with details received during assessment or investigations.
No documentary evidence for closure of alerts © Financial Transparency Advisors<br>
slide18. Some examples of what SICCFIN expects…. Suspicious Transaction Reporting
Structured internal process to report suspicious transactions
Documented
Attempted and completed transactions
Written procedure to avoid tipping off - which is followed
Specific indicators and red flags
Timely responses to requests for further information
Training on suspicious transaction reporting © Financial Transparency Advisors<br>
slide19. SICCFIN Supervisory Findings Training and Human Resources
No training/training not conducted on regular basis/long time since previous training was conducted.
Training not specific
Training not included in policies and procedures
Not specific or comprehensive enough
Lack of focus on TF
Lack of AML/CFT resources
Submission of Reports to SICCFIN
Very poor © Financial Transparency Advisors<br>
slide20. Some examples of what SICCFIN expects…. Training and Human Resources
Comprehensive training which is conducted on regular basis
Specific and targeted to role
Documented record of training
Specific training for senior management and Board members
Training included in policies and procedures
Adequate AML/CFT resources
Submission of Reports to SICCFIN
Must be submitted by all FIs © Financial Transparency Advisors<br>
slide21. What FI’s need to do now…. Have regard to these findings and review own internal AML/CFT control framework to identify if any improvements required. © Financial Transparency Advisors<br>
slide22. Thank You © Financial Transparency Advisors<br>