
Using Innovative Sukuk Structures to finance
Description: Using Innovative Sukuk Structures to finance development Infrastructure. A New Asset Class. Obiyathulla Ismath Bacha INCEIF, Malaysia presentation at OIC Exchanges Forum, 12th Meeting, Istanbul, Turkey September 11th, 2018 Introduction :
Related Topics
Download Presentation
"Using Innovative Sukuk Structures to finance" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Using Innovative Sukuk Structures to finance development Infrastructure. A New Asset Class. Obiyathulla Ismath Bacha
INCEIF, Malaysia
presentation at
OIC Exchanges Forum, 12th Meeting, Istanbul, Turkey
September 11th, 2018<br>
slide2. Introduction : The missing link between development needs and Islamic Finance. “ Economic growth is the most powerful tool we have to end poverty, yet without infrastructure- electricity, water and roads – growth will never take off.” – W.B. President Jim Yong Kim at launch Global Infrastructure Facility (GIF)
The majority of emerging market and developing economies (EMDE) in Asia and Africa are Muslim countries.
The 57 countries of OIC, with a combined population 1.6 billion people, fall within the EMDE category.
-51 of the 57 countries have budget deficits
- 19 of them are classified as HIPC (heavily indebted poor country).
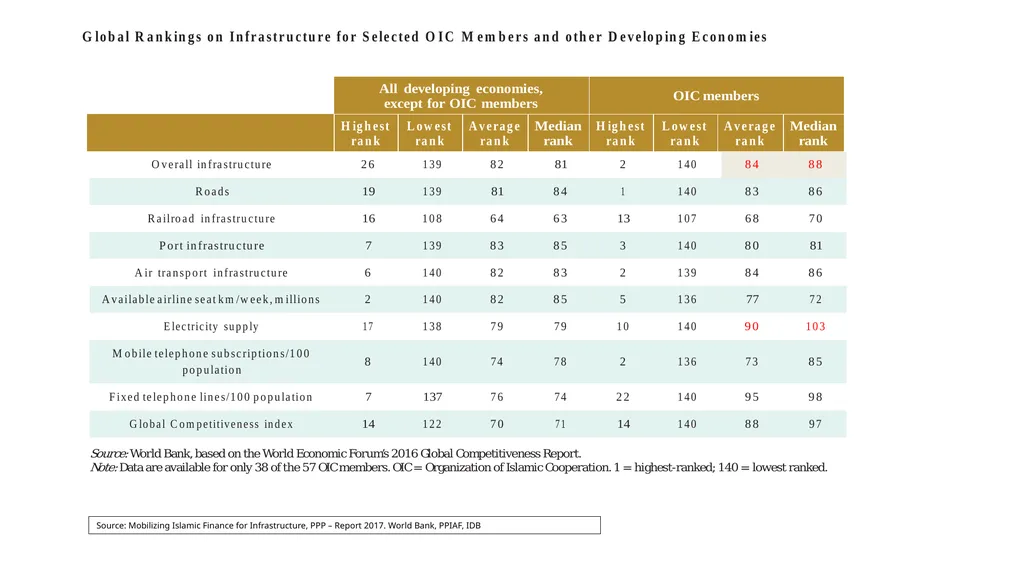
According to a World Bank report, the OIC countries,
- have years of pent-up deficits in infrastructure, inhibiting their ability to exploit their full development potential.
have very rapidly rising populations and very high youth unemployment.
have pressing need for socio-economic infrastructure
Mobilizing Islamic Finance for Infrastructure, PPP – Report 2017. World Bank, PPIAF, IDB<br>
slide3. Introduction : The missing link between development needs and Islamic Finance. Brookings Institution; over 2016−2030, needed global investment in infrastructure is around $90 trillion.
The need for development financing within the Islamic world is obvious.
Muslim nations like Turkey and Indonesia have massive infrastructure plans but lack the funding resource.
Many of the needed projects are low risk, potentially high return projects.
The low hanging fruits – of development economics.
But given very high levels of debt (debt to GDP ratios), these countries are in no position to fund development infrastructure with foreign debt.<br>
slide4. Source: Mobilizing Islamic Finance for Infrastructure, PPP – Report 2017. World Bank, PPIAF, IDB 2017<br>
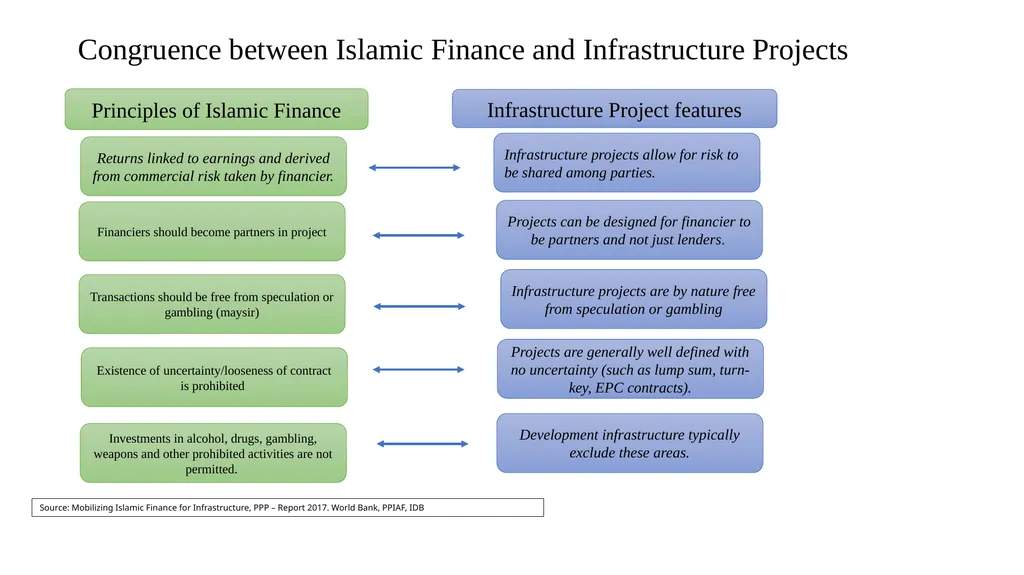
slide5. Congruence between Islamic Finance and Infrastructure Projects Returns linked to earnings and derived from commercial risk taken by financier. Transactions should be free from speculation or gambling (maysir) Infrastructure projects allow for risk to be shared among parties. Financiers should become partners in project Existence of uncertainty/looseness of contract is prohibited Investments in alcohol, drugs, gambling, weapons and other prohibited activities are not permitted. Projects can be designed for financier to be partners and not just lenders. Infrastructure projects are by nature free from speculation or gambling Projects are generally well defined with no uncertainty (such as lump sum, turn-key, EPC contracts). Development infrastructure typically exclude these areas. Principles of Islamic Finance Infrastructure Project features Source: Mobilizing Islamic Finance for Infrastructure, PPP – Report 2017. World Bank, PPIAF, IDB 2017<br>
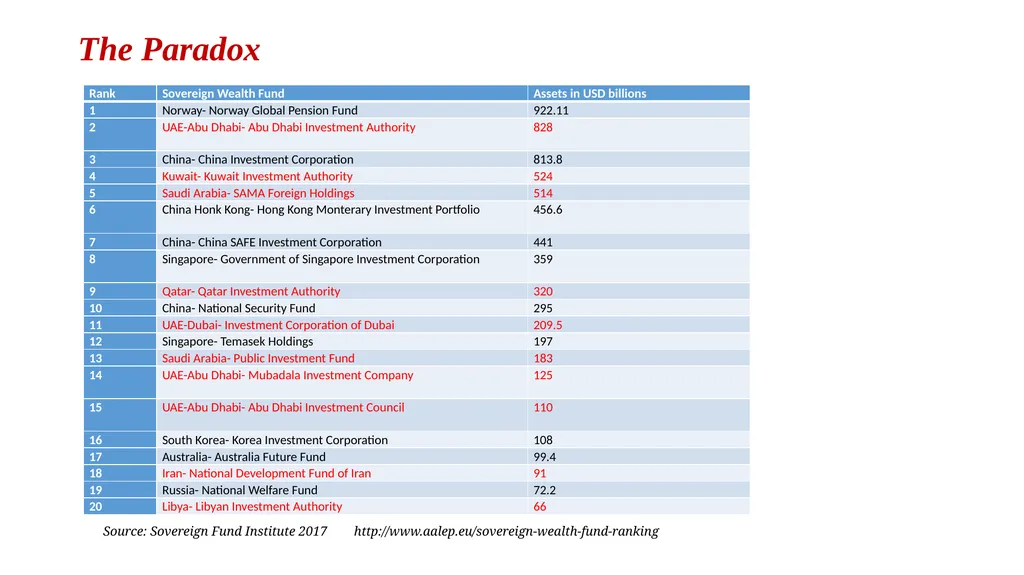
slide6. The Paradox Source: Sovereign Fund Institute 2017 http://www.aalep.eu/sovereign-wealth-fund-ranking<br>
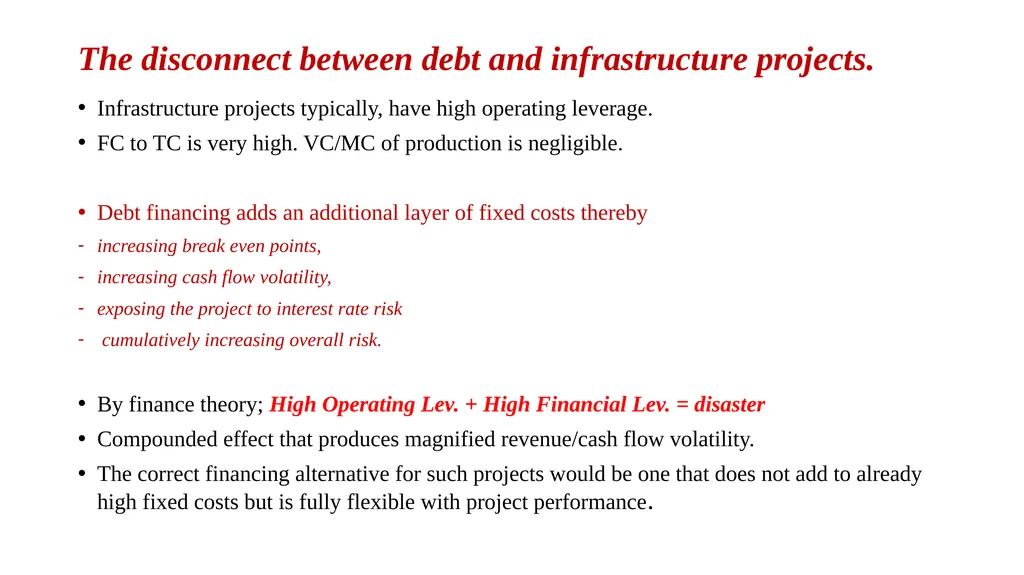
slide7. The disconnect between debt and infrastructure projects. Infrastructure projects typically, have high operating leverage.
FC to TC is very high. VC/MC of production is negligible.
Debt financing adds an additional layer of fixed costs thereby
increasing break even points,
increasing cash flow volatility,
exposing the project to interest rate risk
cumulatively increasing overall risk.
By finance theory; High Operating Lev. + High Financial Lev. = disaster
Compounded effect that produces magnified revenue/cash flow volatility.
The correct financing alternative for such projects would be one that does not add to already high fixed costs but is fully flexible with project performance.<br>
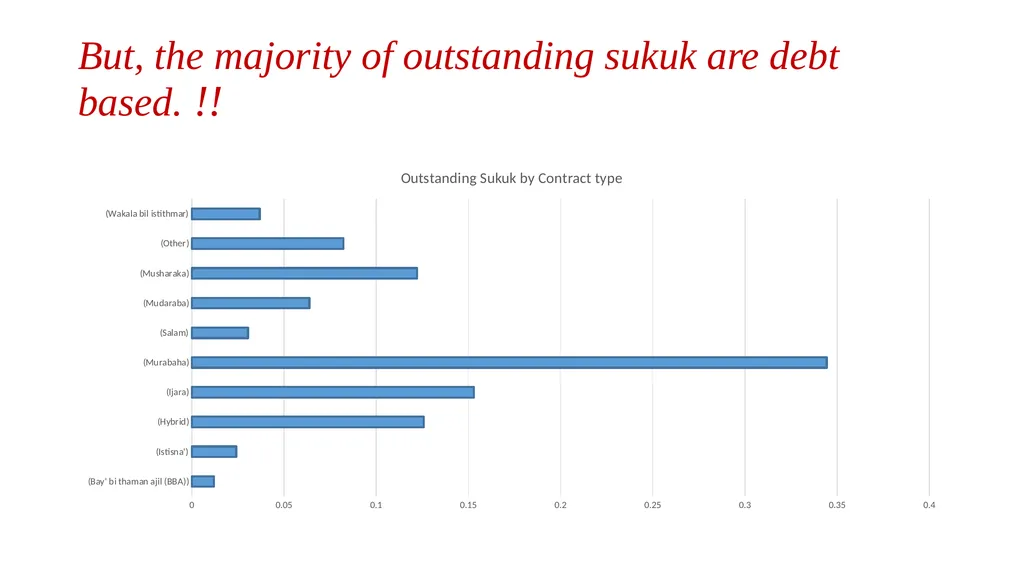
slide8. But, the majority of outstanding sukuk are debt based. !!<br>
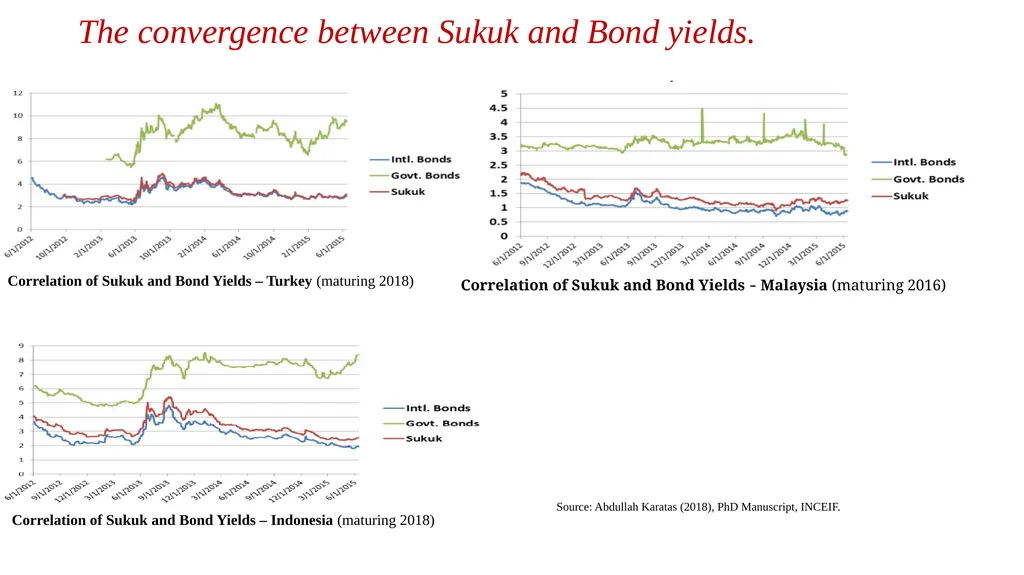
slide9. The convergence between Sukuk and Bond yields. Correlation of Sukuk and Bond Yields – Turkey (maturing 2018) Correlation of Sukuk and Bond Yields – Indonesia (maturing 2018) Correlation of Sukuk and Bond Yields – Malaysia (maturing 2016) Source: Abdullah Karatas (2018), PhD Manuscript, INCEIF.<br>
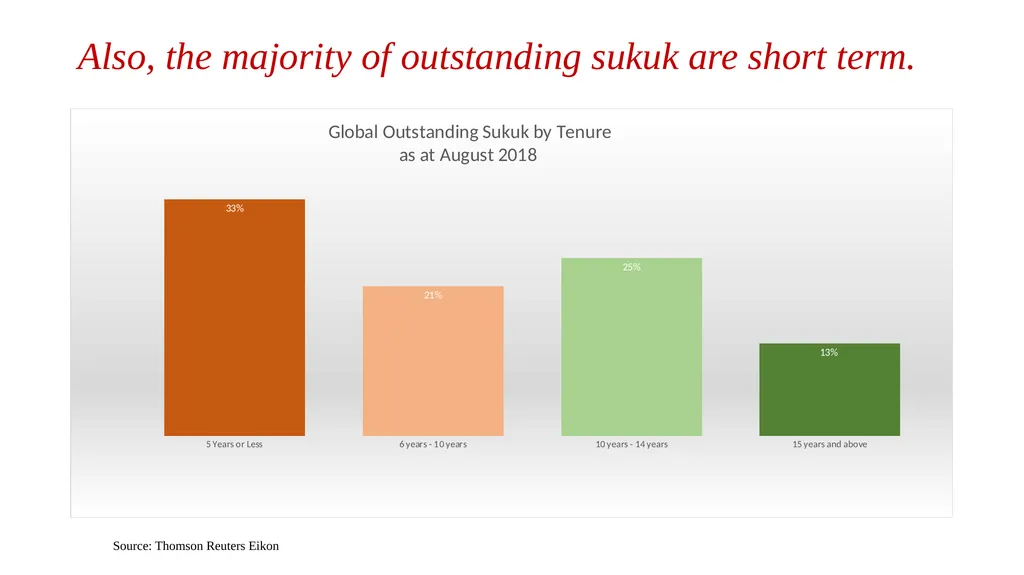
slide10. Also, the majority of outstanding sukuk are short term. Source: Thomson Reuters Eikon<br>
slide11. For emerging countries, development without debt may not be possible, for unlike private entities, which can raise funding through either debt or equity, governments cannot issue equity.
So, debt financing is often the only alternative.
- increases leverage, debt capacity
- macro vulnerability, rate risk, contagion
- currency exposure
However, Rogoff (2010) shows that every one of the last 100 financial crises have had a single root cause, excessive debt.
Key Challenge
How do we fund growth/development without debt??<br>
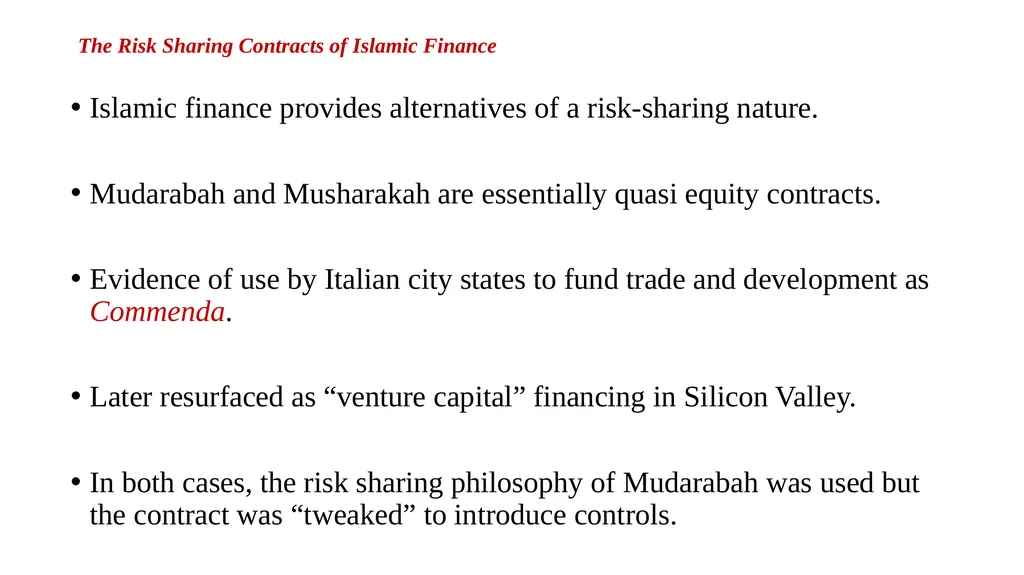
slide12. The Risk Sharing Contracts of Islamic Finance Islamic finance provides alternatives of a risk-sharing nature.
Mudarabah and Musharakah are essentially quasi equity contracts.
Evidence of use by Italian city states to fund trade and development as Commenda.
Later resurfaced as “venture capital” financing in Silicon Valley.
In both cases, the risk sharing philosophy of Mudarabah was used but the contract was “tweaked” to introduce controls.<br>
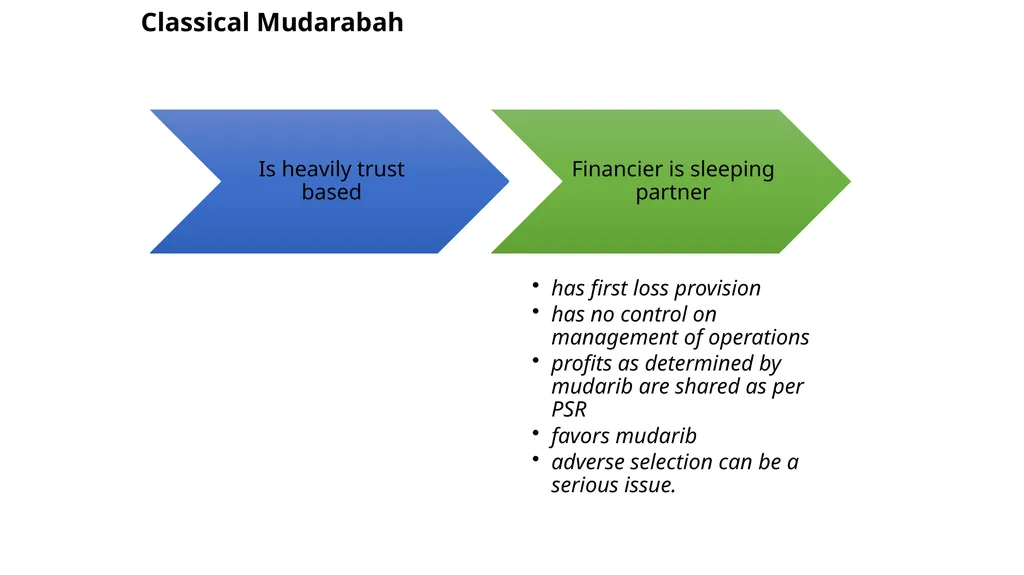
slide13. Classical Mudarabah<br>
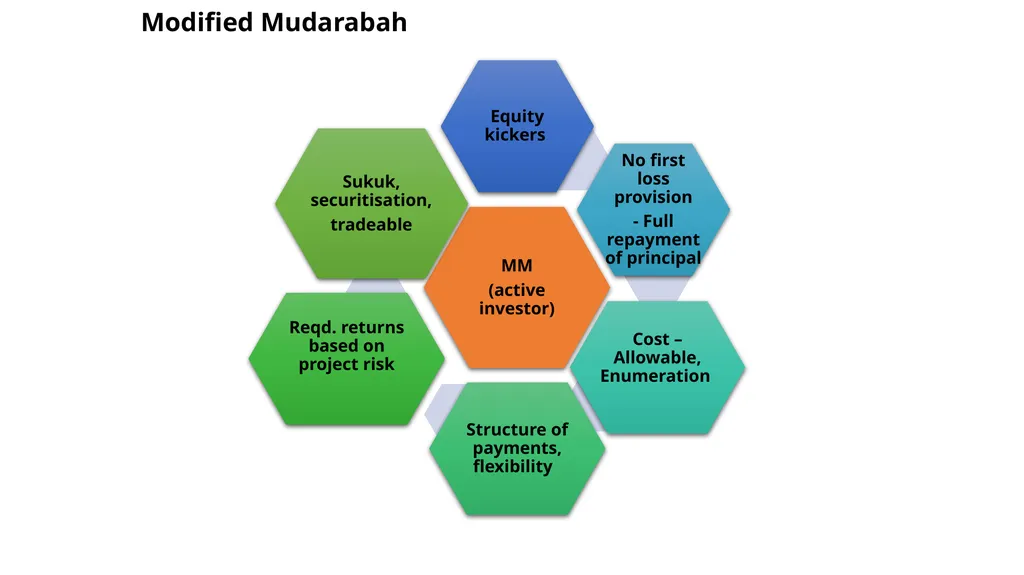
slide14. Modified Mudarabah<br>
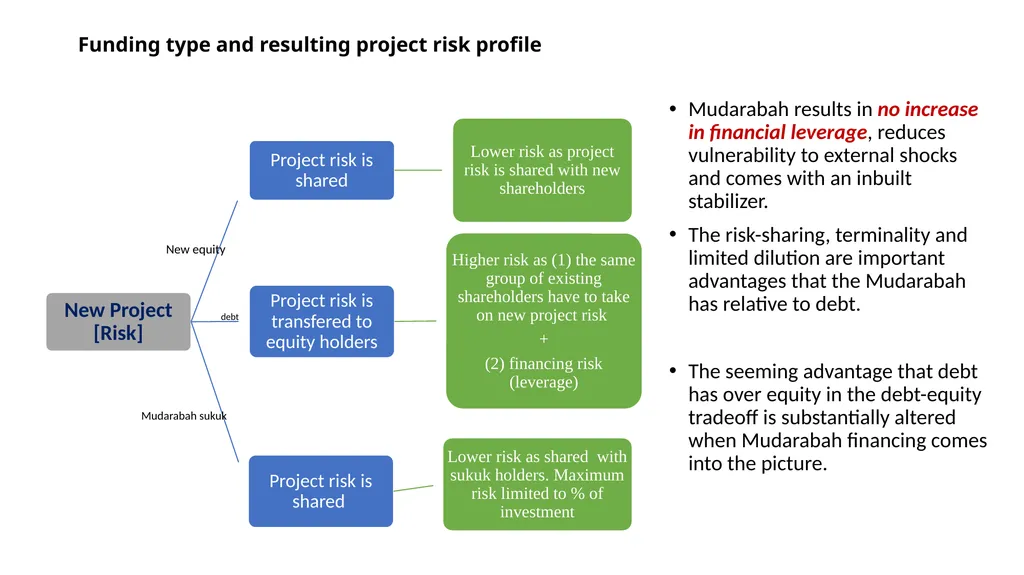
slide15. Funding type and resulting project risk profile Mudarabah results in no increase in financial leverage, reduces vulnerability to external shocks and comes with an inbuilt stabilizer.
The risk-sharing, terminality and limited dilution are important advantages that the Mudarabah has relative to debt.
The seeming advantage that debt has over equity in the debt-equity tradeoff is substantially altered when Mudarabah financing comes into the picture. New equity Mudarabah sukuk debt<br>
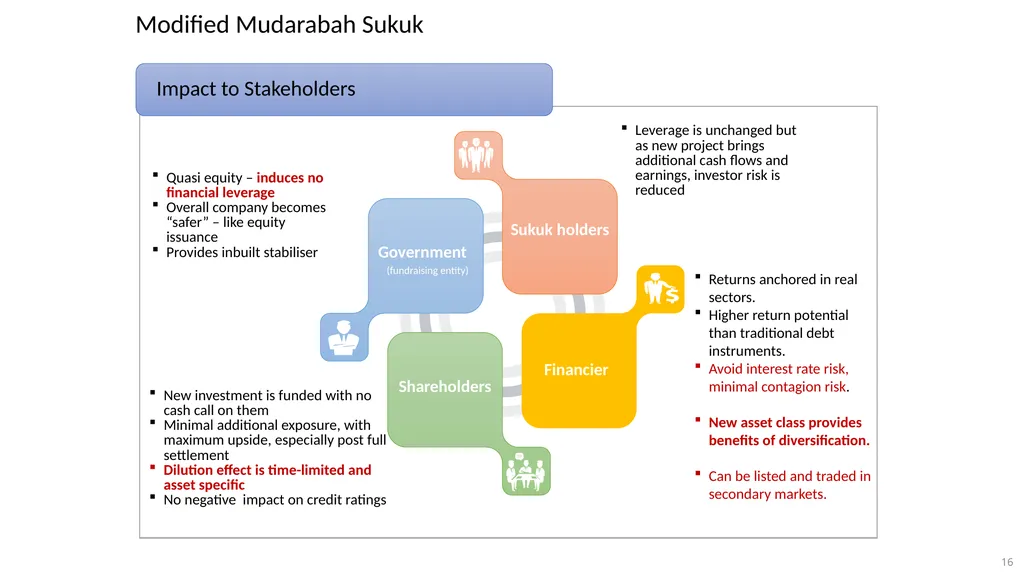
slide16. 16 Modified Mudarabah Sukuk Leverage is unchanged but as new project brings additional cash flows and earnings, investor risk is reduced Shareholders Financier Government Sukuk holders Quasi equity – induces no financial leverage
Overall company becomes “safer” – like equity issuance
Provides inbuilt stabiliser New investment is funded with no cash call on them
Minimal additional exposure, with maximum upside, especially post full settlement
Dilution effect is time-limited and asset specific
No negative impact on credit ratings (fundraising entity) Impact to Stakeholders Returns anchored in real sectors.
Higher return potential than traditional debt instruments.
Avoid interest rate risk, minimal contagion risk.
New asset class provides benefits of diversification.
Can be listed and traded in secondary markets.<br>
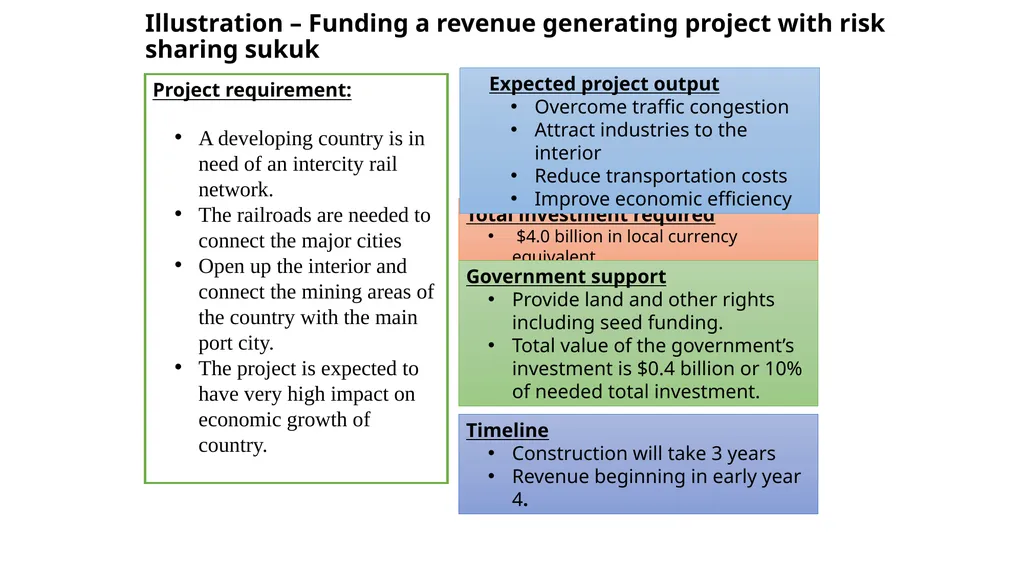
slide17. Illustration – Funding a revenue generating project with risk sharing sukuk Project requirement:
A developing country is in need of an intercity rail network.
The railroads are needed to connect the major cities
Open up the interior and connect the mining areas of the country with the main port city.
The project is expected to have very high impact on economic growth of country. Total investment required
$4.0 billion in local currency equivalent. Government support
Provide land and other rights including seed funding.
Total value of the government’s investment is $0.4 billion or 10% of needed total investment. Timeline
Construction will take 3 years
Revenue beginning in early year 4. Expected project output
Overcome traffic congestion
Attract industries to the interior
Reduce transportation costs
Improve economic efficiency<br>
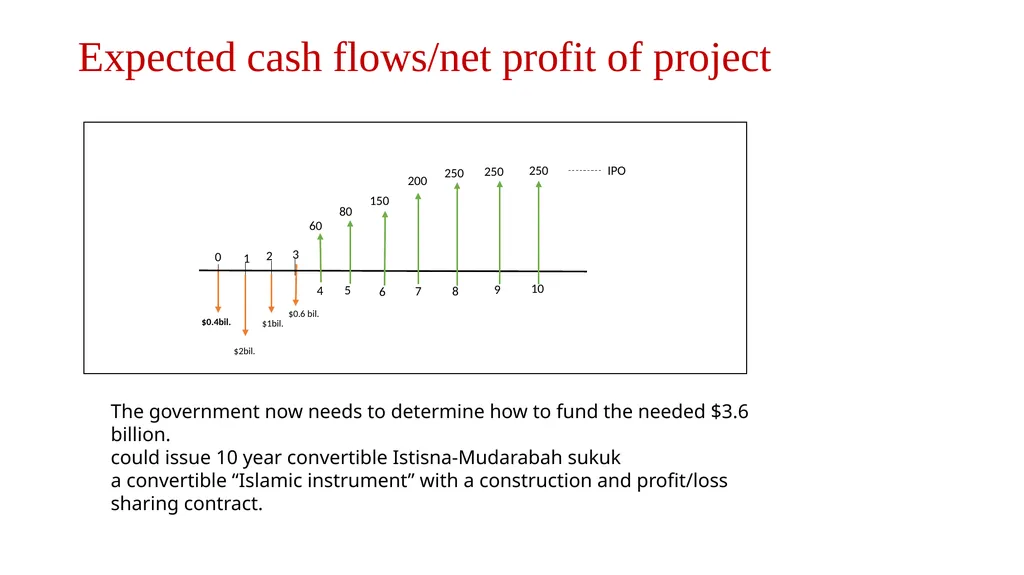
slide18. Expected cash flows/net profit of project $0.4bil. 1 10 2 3 4 5 6 7 8 9 150 0 60 80 250 250 200 250 $2bil. $1bil. $0.6 bil. IPO The government now needs to determine how to fund the needed $3.6 billion.
could issue 10 year convertible Istisna-Mudarabah sukuk
a convertible “Islamic instrument” with a construction and profit/loss sharing contract.<br>
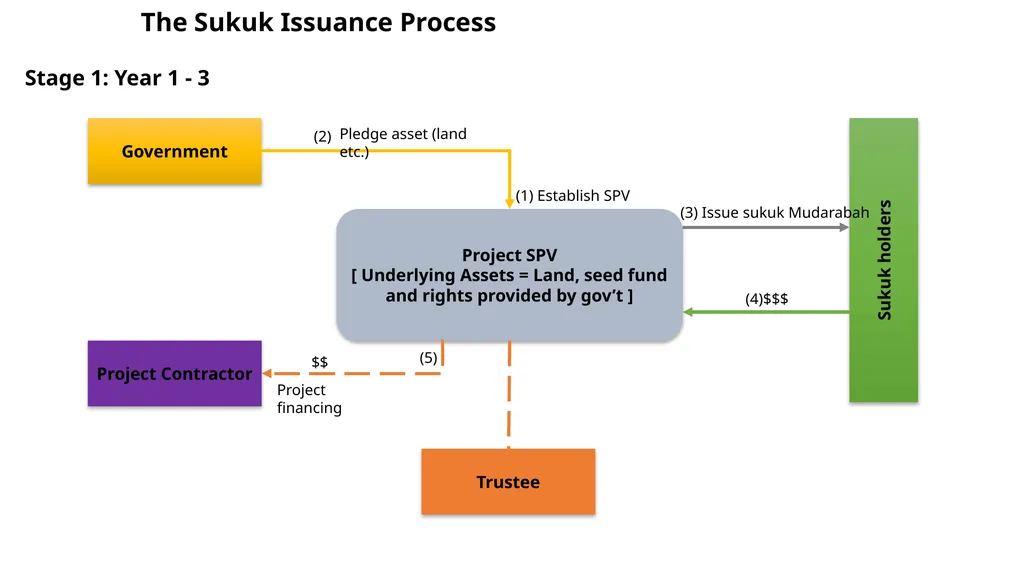
slide19. The Sukuk Issuance Process Sukuk holders Government Project SPV
[ Underlying Assets = Land, seed fund and rights provided by gov’t ] Trustee Project Contractor (3) Issue sukuk Mudarabah (1) Establish SPV (2) Pledge asset (land etc.) Project financing $$ (5) (4)$$$ Stage 1: Year 1 - 3<br>
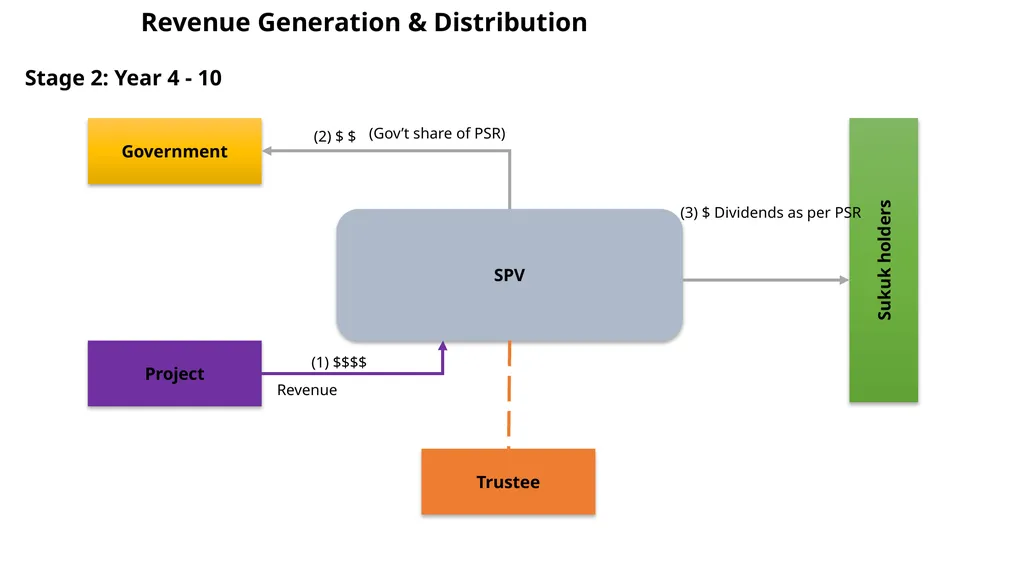
slide20. Revenue Generation & Distribution Sukuk holders Government SPV Trustee Project (3) $ Dividends as per PSR (2) $ $ (Gov’t share of PSR) Revenue (1) $$$$ Stage 2: Year 4 - 10<br>
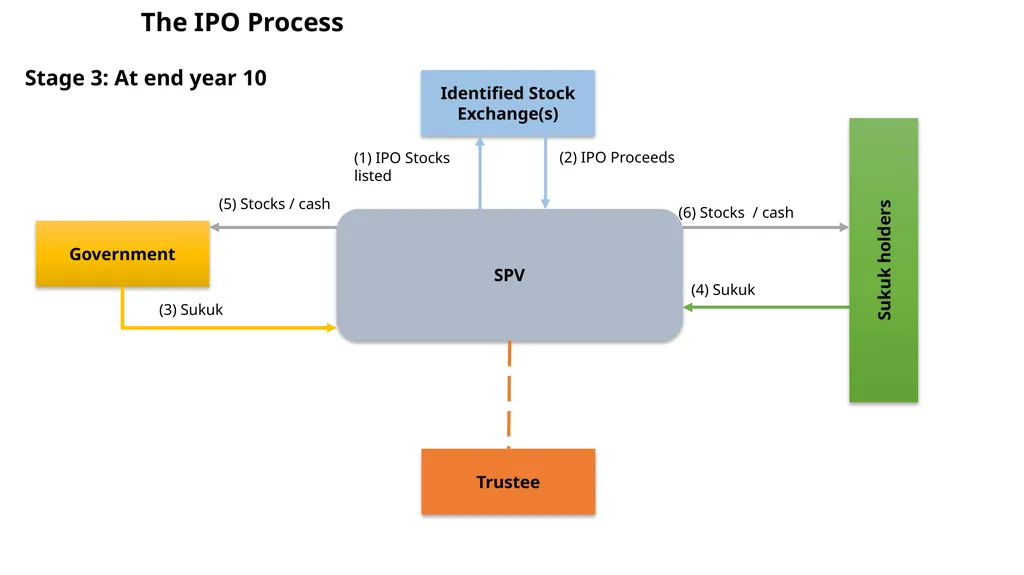
slide21. The IPO Process Sukuk holders Government SPV Trustee Identified Stock Exchange(s) (6) Stocks / cash (1) IPO Stocks listed (5) Stocks / cash Stage 3: At end year 10 (2) IPO Proceeds (3) Sukuk (4) Sukuk<br>
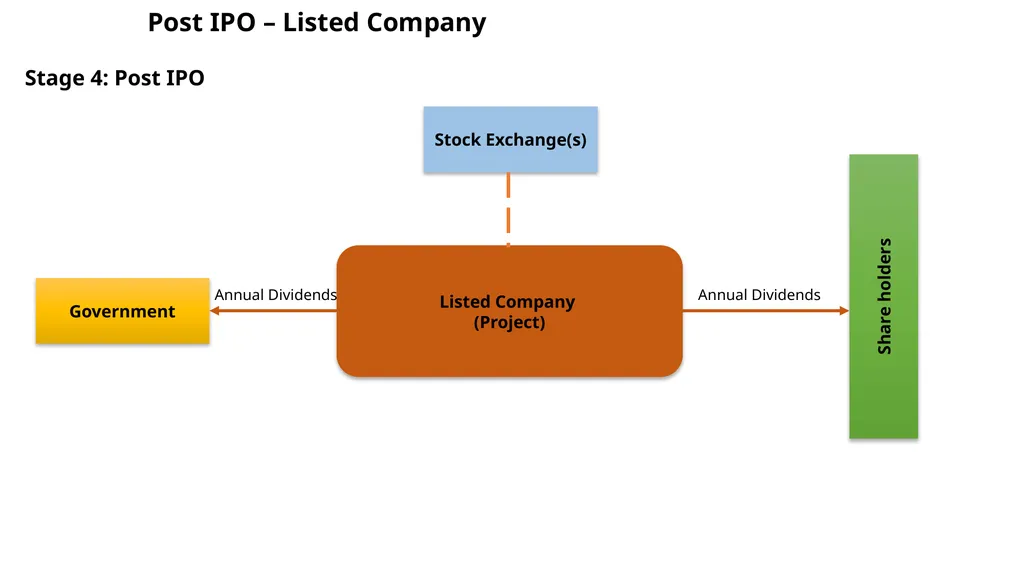
slide22. Post IPO – Listed Company Share holders Government Listed Company
(Project) Stock Exchange(s) Annual Dividends Stage 4: Post IPO Annual Dividends<br>
slide23. Risk Sharing Sukuk for Non Revenue Generating Projects.<br>
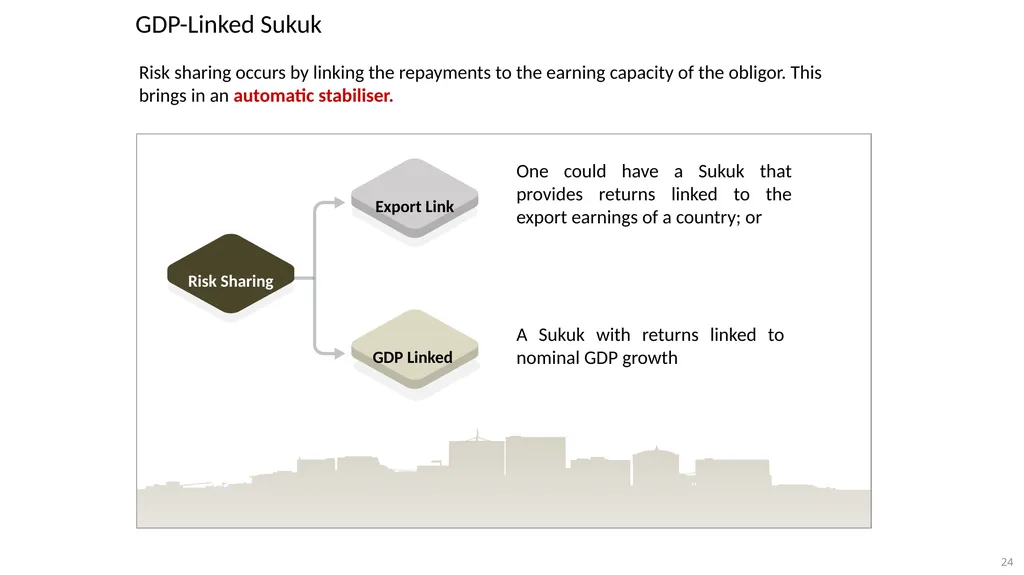
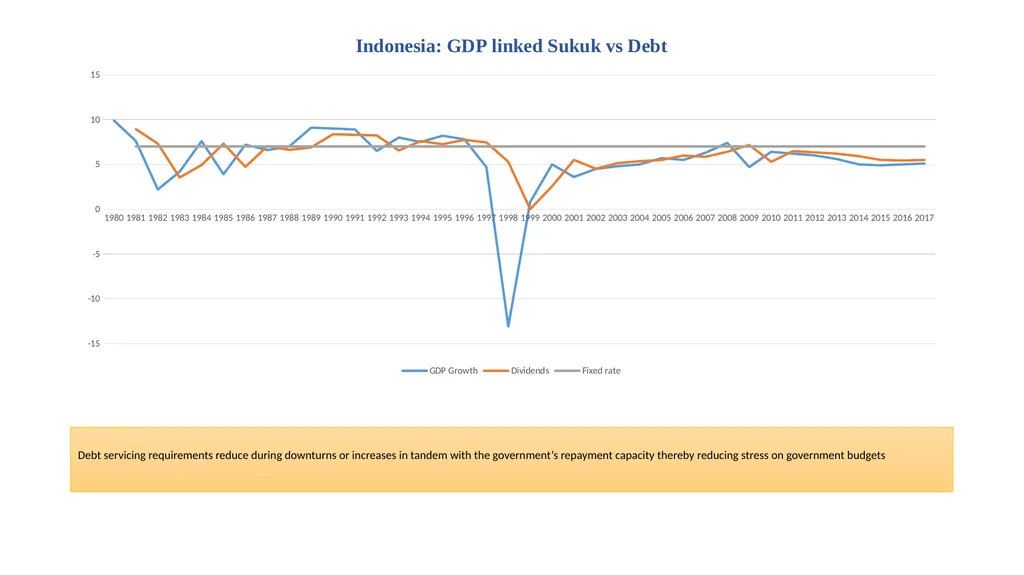
slide24. 24 Risk Sharing Export Link GDP Linked GDP-Linked Sukuk Risk sharing occurs by linking the repayments to the earning capacity of the obligor. This brings in an automatic stabiliser. One could have a Sukuk that provides returns linked to the export earnings of a country; or A Sukuk with returns linked to nominal GDP growth<br>
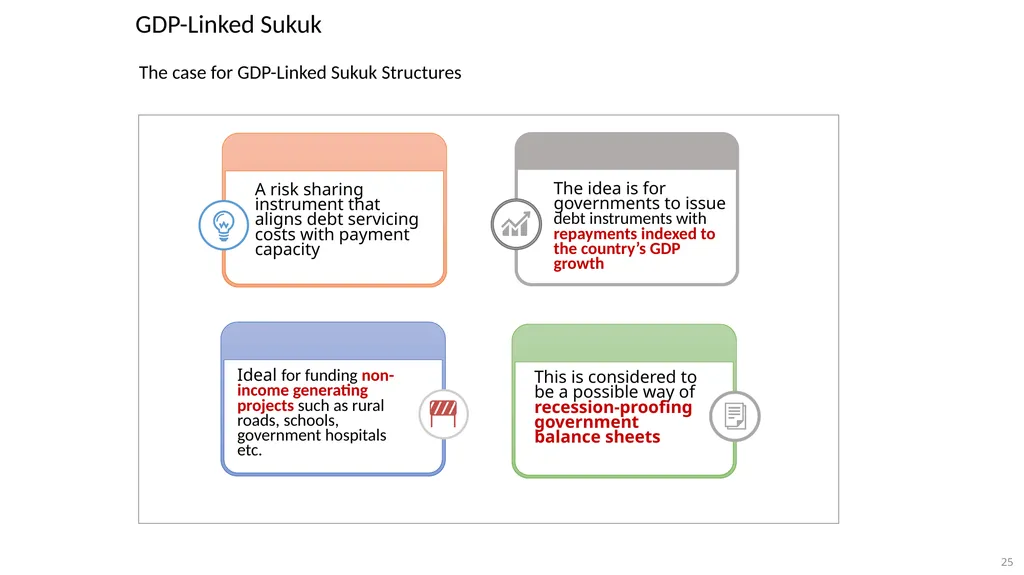
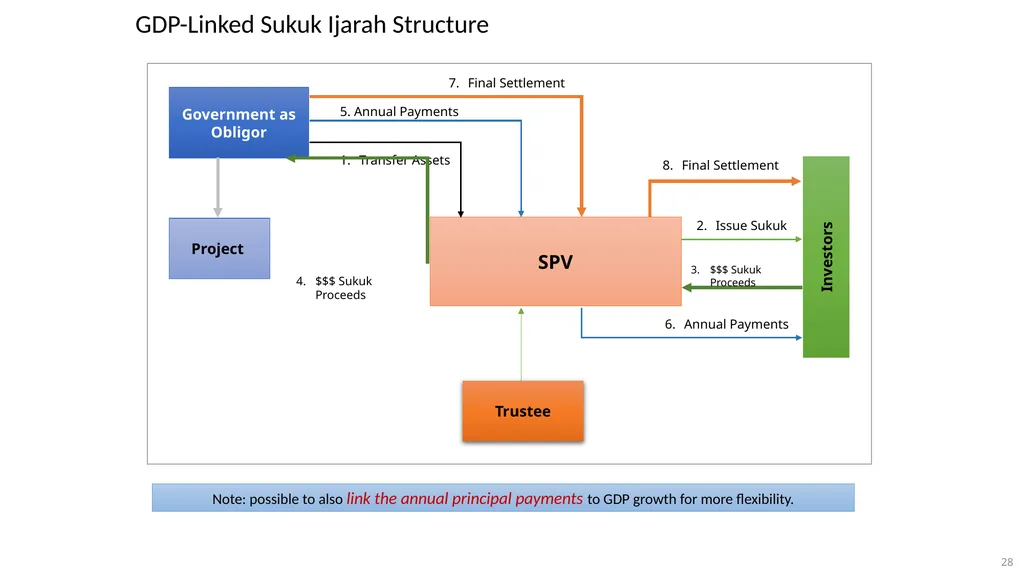
slide25. 25 Ideal for funding non-income generating projects such as rural roads, schools, government hospitals etc. The idea is for governments to issue debt instruments with repayments indexed to the country’s GDP growth This is considered to be a possible way of recession-proofing government balance sheets GDP-Linked Sukuk The case for GDP-Linked Sukuk Structures<br>
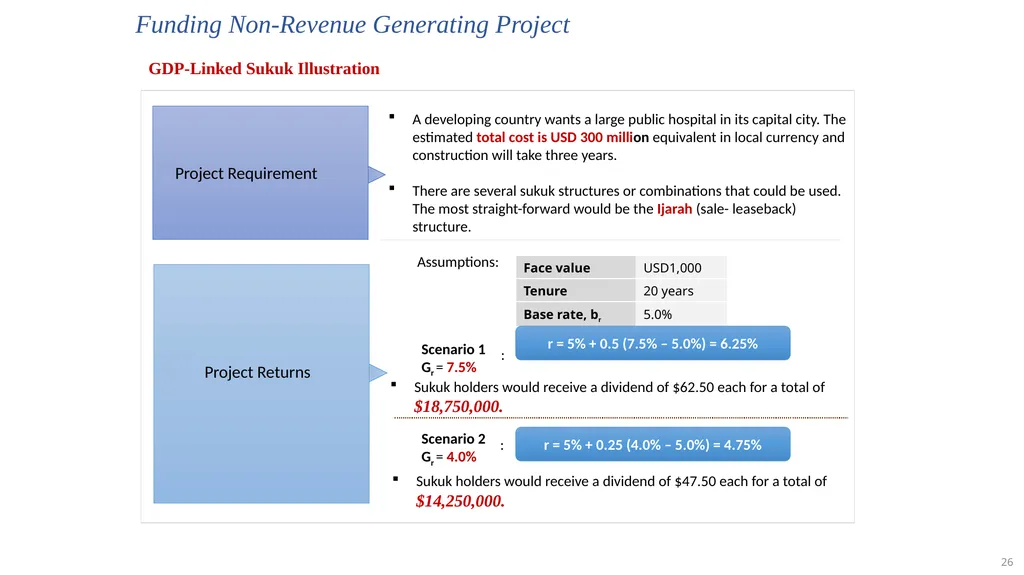
slide26. 26 GDP-Linked Sukuk Illustration Project Requirement A developing country wants a large public hospital in its capital city. The estimated total cost is USD 300 million equivalent in local currency and construction will take three years.
There are several sukuk structures or combinations that could be used. The most straight-forward would be the Ijarah (sale- leaseback) structure. Project Returns Sukuk holders would receive a dividend of $62.50 each for a total of $18,750,000. Assumptions: Scenario 1
Gr = 7.5% r = 5% + 0.5 (7.5% – 5.0%) = 6.25% : Scenario 2
Gr = 4.0% r = 5% + 0.25 (4.0% – 5.0%) = 4.75% : Sukuk holders would receive a dividend of $47.50 each for a total of $14,250,000. Funding Non-Revenue Generating Project<br>
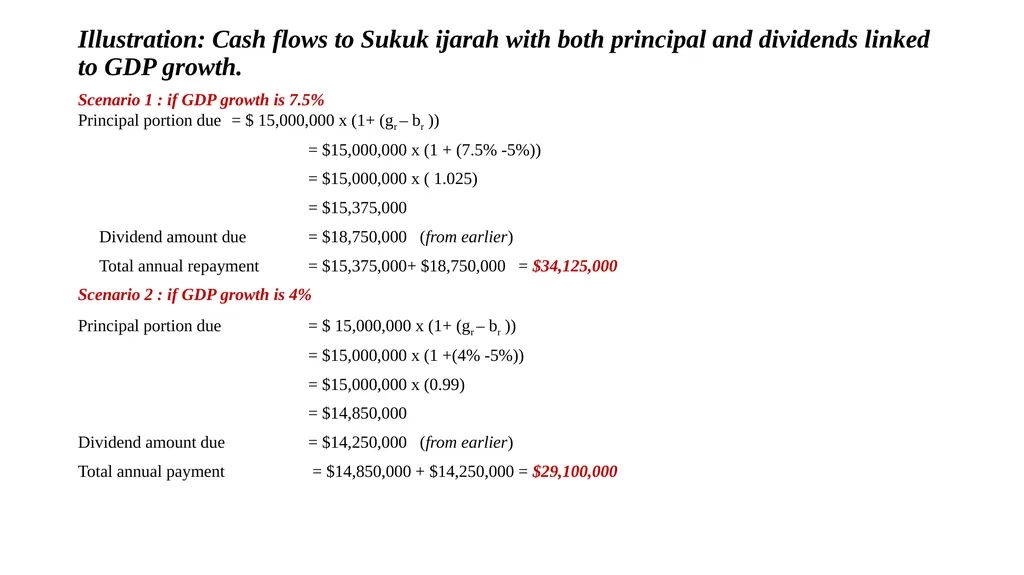
slide27. Illustration: Cash flows to Sukuk ijarah with both principal and dividends linked to GDP growth. Scenario 1 : if GDP growth is 7.5% Principal portion due = $ 15,000,000 x (1+ (gr – br ))
= $15,000,000 x (1 + (7.5% -5%))
= $15,000,000 x ( 1.025)
= $15,375,000
Dividend amount due = $18,750,000 (from earlier)
Total annual repayment = $15,375,000+ $18,750,000 = $34,125,000
Scenario 2 : if GDP growth is 4%
Principal portion due = $ 15,000,000 x (1+ (gr – br ))
= $15,000,000 x (1 +(4% -5%))
= $15,000,000 x (0.99)
= $14,850,000
Dividend amount due = $14,250,000 (from earlier)
Total annual payment = $14,850,000 + $14,250,000 = $29,100,000<br>
slide28. 28 Investors SPV Government as Obligor Project 5. Annual Payments Trustee Transfer Assets Final Settlement $$$ Sukuk Proceeds Final Settlement Issue Sukuk $$$ Sukuk Proceeds Annual Payments Note: possible to also link the annual principal payments to GDP growth for more flexibility. GDP-Linked Sukuk Ijarah Structure<br>
slide29. Debt servicing requirements reduce during downturns or increases in tandem with the government’s repayment capacity thereby reducing stress on government budgets<br>
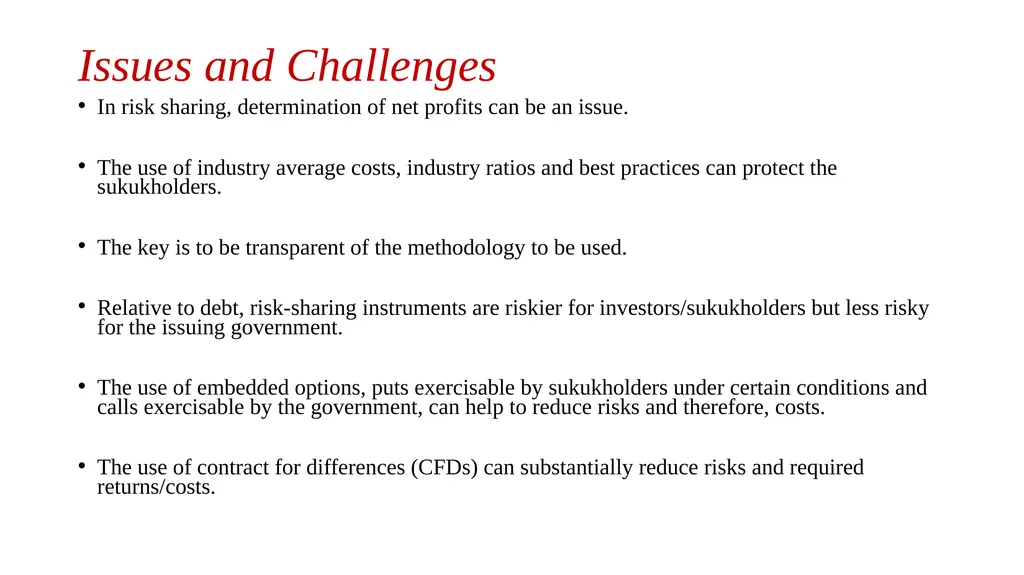
slide30. Issues and Challenges In risk sharing, determination of net profits can be an issue.
The use of industry average costs, industry ratios and best practices can protect the sukukholders.
The key is to be transparent of the methodology to be used.
Relative to debt, risk-sharing instruments are riskier for investors/sukukholders but less risky for the issuing government.
The use of embedded options, puts exercisable by sukukholders under certain conditions and calls exercisable by the government, can help to reduce risks and therefore, costs.
The use of contract for differences (CFDs) can substantially reduce risks and required returns/costs.<br>
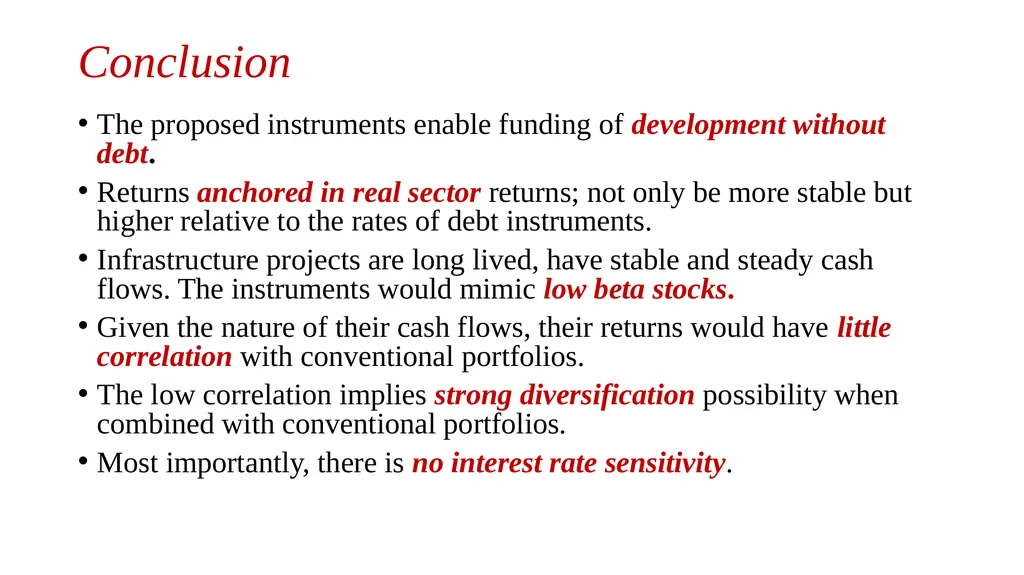
slide31. Conclusion The proposed instruments enable funding of development without debt.
Returns anchored in real sector returns; not only be more stable but higher relative to the rates of debt instruments.
Infrastructure projects are long lived, have stable and steady cash flows. The instruments would mimic low beta stocks.
Given the nature of their cash flows, their returns would have little correlation with conventional portfolios.
The low correlation implies strong diversification possibility when combined with conventional portfolios.
Most importantly, there is no interest rate sensitivity.<br>
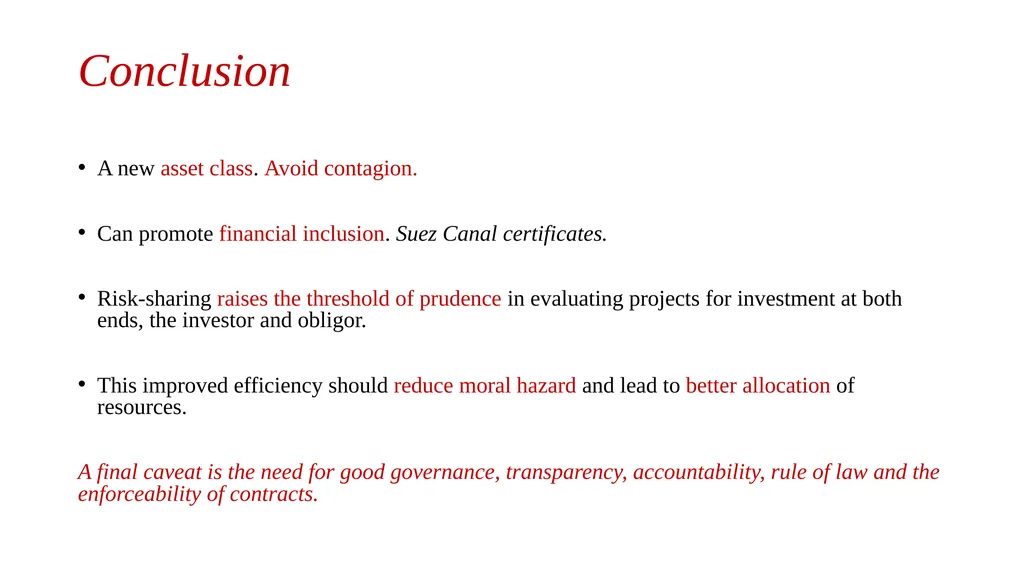
slide32. Conclusion A new asset class. Avoid contagion.
Can promote financial inclusion. Suez Canal certificates.
Risk-sharing raises the threshold of prudence in evaluating projects for investment at both ends, the investor and obligor.
This improved efficiency should reduce moral hazard and lead to better allocation of resources.
A final caveat is the need for good governance, transparency, accountability, rule of law and the enforceability of contracts.<br>
slide33. INCEIF, The Global University of Islamic Finance Lorong Universiti A,
59100 Kuala Lumpur, Malaysia Thank you
obiya@inceif.org<br>
INCEIF, Malaysia
presentation at
OIC Exchanges Forum, 12th Meeting, Istanbul, Turkey
September 11th, 2018<br>
slide2. Introduction : The missing link between development needs and Islamic Finance. “ Economic growth is the most powerful tool we have to end poverty, yet without infrastructure- electricity, water and roads – growth will never take off.” – W.B. President Jim Yong Kim at launch Global Infrastructure Facility (GIF)
The majority of emerging market and developing economies (EMDE) in Asia and Africa are Muslim countries.
The 57 countries of OIC, with a combined population 1.6 billion people, fall within the EMDE category.
-51 of the 57 countries have budget deficits
- 19 of them are classified as HIPC (heavily indebted poor country).
According to a World Bank report, the OIC countries,
- have years of pent-up deficits in infrastructure, inhibiting their ability to exploit their full development potential.
have very rapidly rising populations and very high youth unemployment.
have pressing need for socio-economic infrastructure
Mobilizing Islamic Finance for Infrastructure, PPP – Report 2017. World Bank, PPIAF, IDB<br>
slide3. Introduction : The missing link between development needs and Islamic Finance. Brookings Institution; over 2016−2030, needed global investment in infrastructure is around $90 trillion.
The need for development financing within the Islamic world is obvious.
Muslim nations like Turkey and Indonesia have massive infrastructure plans but lack the funding resource.
Many of the needed projects are low risk, potentially high return projects.
The low hanging fruits – of development economics.
But given very high levels of debt (debt to GDP ratios), these countries are in no position to fund development infrastructure with foreign debt.<br>
slide4. Source: Mobilizing Islamic Finance for Infrastructure, PPP – Report 2017. World Bank, PPIAF, IDB 2017<br>
slide5. Congruence between Islamic Finance and Infrastructure Projects Returns linked to earnings and derived from commercial risk taken by financier. Transactions should be free from speculation or gambling (maysir) Infrastructure projects allow for risk to be shared among parties. Financiers should become partners in project Existence of uncertainty/looseness of contract is prohibited Investments in alcohol, drugs, gambling, weapons and other prohibited activities are not permitted. Projects can be designed for financier to be partners and not just lenders. Infrastructure projects are by nature free from speculation or gambling Projects are generally well defined with no uncertainty (such as lump sum, turn-key, EPC contracts). Development infrastructure typically exclude these areas. Principles of Islamic Finance Infrastructure Project features Source: Mobilizing Islamic Finance for Infrastructure, PPP – Report 2017. World Bank, PPIAF, IDB 2017<br>
slide6. The Paradox Source: Sovereign Fund Institute 2017 http://www.aalep.eu/sovereign-wealth-fund-ranking<br>
slide7. The disconnect between debt and infrastructure projects. Infrastructure projects typically, have high operating leverage.
FC to TC is very high. VC/MC of production is negligible.
Debt financing adds an additional layer of fixed costs thereby
increasing break even points,
increasing cash flow volatility,
exposing the project to interest rate risk
cumulatively increasing overall risk.
By finance theory; High Operating Lev. + High Financial Lev. = disaster
Compounded effect that produces magnified revenue/cash flow volatility.
The correct financing alternative for such projects would be one that does not add to already high fixed costs but is fully flexible with project performance.<br>
slide8. But, the majority of outstanding sukuk are debt based. !!<br>
slide9. The convergence between Sukuk and Bond yields. Correlation of Sukuk and Bond Yields – Turkey (maturing 2018) Correlation of Sukuk and Bond Yields – Indonesia (maturing 2018) Correlation of Sukuk and Bond Yields – Malaysia (maturing 2016) Source: Abdullah Karatas (2018), PhD Manuscript, INCEIF.<br>
slide10. Also, the majority of outstanding sukuk are short term. Source: Thomson Reuters Eikon<br>
slide11. For emerging countries, development without debt may not be possible, for unlike private entities, which can raise funding through either debt or equity, governments cannot issue equity.
So, debt financing is often the only alternative.
- increases leverage, debt capacity
- macro vulnerability, rate risk, contagion
- currency exposure
However, Rogoff (2010) shows that every one of the last 100 financial crises have had a single root cause, excessive debt.
Key Challenge
How do we fund growth/development without debt??<br>
slide12. The Risk Sharing Contracts of Islamic Finance Islamic finance provides alternatives of a risk-sharing nature.
Mudarabah and Musharakah are essentially quasi equity contracts.
Evidence of use by Italian city states to fund trade and development as Commenda.
Later resurfaced as “venture capital” financing in Silicon Valley.
In both cases, the risk sharing philosophy of Mudarabah was used but the contract was “tweaked” to introduce controls.<br>
slide13. Classical Mudarabah<br>
slide14. Modified Mudarabah<br>
slide15. Funding type and resulting project risk profile Mudarabah results in no increase in financial leverage, reduces vulnerability to external shocks and comes with an inbuilt stabilizer.
The risk-sharing, terminality and limited dilution are important advantages that the Mudarabah has relative to debt.
The seeming advantage that debt has over equity in the debt-equity tradeoff is substantially altered when Mudarabah financing comes into the picture. New equity Mudarabah sukuk debt<br>
slide16. 16 Modified Mudarabah Sukuk Leverage is unchanged but as new project brings additional cash flows and earnings, investor risk is reduced Shareholders Financier Government Sukuk holders Quasi equity – induces no financial leverage
Overall company becomes “safer” – like equity issuance
Provides inbuilt stabiliser New investment is funded with no cash call on them
Minimal additional exposure, with maximum upside, especially post full settlement
Dilution effect is time-limited and asset specific
No negative impact on credit ratings (fundraising entity) Impact to Stakeholders Returns anchored in real sectors.
Higher return potential than traditional debt instruments.
Avoid interest rate risk, minimal contagion risk.
New asset class provides benefits of diversification.
Can be listed and traded in secondary markets.<br>
slide17. Illustration – Funding a revenue generating project with risk sharing sukuk Project requirement:
A developing country is in need of an intercity rail network.
The railroads are needed to connect the major cities
Open up the interior and connect the mining areas of the country with the main port city.
The project is expected to have very high impact on economic growth of country. Total investment required
$4.0 billion in local currency equivalent. Government support
Provide land and other rights including seed funding.
Total value of the government’s investment is $0.4 billion or 10% of needed total investment. Timeline
Construction will take 3 years
Revenue beginning in early year 4. Expected project output
Overcome traffic congestion
Attract industries to the interior
Reduce transportation costs
Improve economic efficiency<br>
slide18. Expected cash flows/net profit of project $0.4bil. 1 10 2 3 4 5 6 7 8 9 150 0 60 80 250 250 200 250 $2bil. $1bil. $0.6 bil. IPO The government now needs to determine how to fund the needed $3.6 billion.
could issue 10 year convertible Istisna-Mudarabah sukuk
a convertible “Islamic instrument” with a construction and profit/loss sharing contract.<br>
slide19. The Sukuk Issuance Process Sukuk holders Government Project SPV
[ Underlying Assets = Land, seed fund and rights provided by gov’t ] Trustee Project Contractor (3) Issue sukuk Mudarabah (1) Establish SPV (2) Pledge asset (land etc.) Project financing $$ (5) (4)$$$ Stage 1: Year 1 - 3<br>
slide20. Revenue Generation & Distribution Sukuk holders Government SPV Trustee Project (3) $ Dividends as per PSR (2) $ $ (Gov’t share of PSR) Revenue (1) $$$$ Stage 2: Year 4 - 10<br>
slide21. The IPO Process Sukuk holders Government SPV Trustee Identified Stock Exchange(s) (6) Stocks / cash (1) IPO Stocks listed (5) Stocks / cash Stage 3: At end year 10 (2) IPO Proceeds (3) Sukuk (4) Sukuk<br>
slide22. Post IPO – Listed Company Share holders Government Listed Company
(Project) Stock Exchange(s) Annual Dividends Stage 4: Post IPO Annual Dividends<br>
slide23. Risk Sharing Sukuk for Non Revenue Generating Projects.<br>
slide24. 24 Risk Sharing Export Link GDP Linked GDP-Linked Sukuk Risk sharing occurs by linking the repayments to the earning capacity of the obligor. This brings in an automatic stabiliser. One could have a Sukuk that provides returns linked to the export earnings of a country; or A Sukuk with returns linked to nominal GDP growth<br>
slide25. 25 Ideal for funding non-income generating projects such as rural roads, schools, government hospitals etc. The idea is for governments to issue debt instruments with repayments indexed to the country’s GDP growth This is considered to be a possible way of recession-proofing government balance sheets GDP-Linked Sukuk The case for GDP-Linked Sukuk Structures<br>
slide26. 26 GDP-Linked Sukuk Illustration Project Requirement A developing country wants a large public hospital in its capital city. The estimated total cost is USD 300 million equivalent in local currency and construction will take three years.
There are several sukuk structures or combinations that could be used. The most straight-forward would be the Ijarah (sale- leaseback) structure. Project Returns Sukuk holders would receive a dividend of $62.50 each for a total of $18,750,000. Assumptions: Scenario 1
Gr = 7.5% r = 5% + 0.5 (7.5% – 5.0%) = 6.25% : Scenario 2
Gr = 4.0% r = 5% + 0.25 (4.0% – 5.0%) = 4.75% : Sukuk holders would receive a dividend of $47.50 each for a total of $14,250,000. Funding Non-Revenue Generating Project<br>
slide27. Illustration: Cash flows to Sukuk ijarah with both principal and dividends linked to GDP growth. Scenario 1 : if GDP growth is 7.5% Principal portion due = $ 15,000,000 x (1+ (gr – br ))
= $15,000,000 x (1 + (7.5% -5%))
= $15,000,000 x ( 1.025)
= $15,375,000
Dividend amount due = $18,750,000 (from earlier)
Total annual repayment = $15,375,000+ $18,750,000 = $34,125,000
Scenario 2 : if GDP growth is 4%
Principal portion due = $ 15,000,000 x (1+ (gr – br ))
= $15,000,000 x (1 +(4% -5%))
= $15,000,000 x (0.99)
= $14,850,000
Dividend amount due = $14,250,000 (from earlier)
Total annual payment = $14,850,000 + $14,250,000 = $29,100,000<br>
slide28. 28 Investors SPV Government as Obligor Project 5. Annual Payments Trustee Transfer Assets Final Settlement $$$ Sukuk Proceeds Final Settlement Issue Sukuk $$$ Sukuk Proceeds Annual Payments Note: possible to also link the annual principal payments to GDP growth for more flexibility. GDP-Linked Sukuk Ijarah Structure<br>
slide29. Debt servicing requirements reduce during downturns or increases in tandem with the government’s repayment capacity thereby reducing stress on government budgets<br>
slide30. Issues and Challenges In risk sharing, determination of net profits can be an issue.
The use of industry average costs, industry ratios and best practices can protect the sukukholders.
The key is to be transparent of the methodology to be used.
Relative to debt, risk-sharing instruments are riskier for investors/sukukholders but less risky for the issuing government.
The use of embedded options, puts exercisable by sukukholders under certain conditions and calls exercisable by the government, can help to reduce risks and therefore, costs.
The use of contract for differences (CFDs) can substantially reduce risks and required returns/costs.<br>
slide31. Conclusion The proposed instruments enable funding of development without debt.
Returns anchored in real sector returns; not only be more stable but higher relative to the rates of debt instruments.
Infrastructure projects are long lived, have stable and steady cash flows. The instruments would mimic low beta stocks.
Given the nature of their cash flows, their returns would have little correlation with conventional portfolios.
The low correlation implies strong diversification possibility when combined with conventional portfolios.
Most importantly, there is no interest rate sensitivity.<br>
slide32. Conclusion A new asset class. Avoid contagion.
Can promote financial inclusion. Suez Canal certificates.
Risk-sharing raises the threshold of prudence in evaluating projects for investment at both ends, the investor and obligor.
This improved efficiency should reduce moral hazard and lead to better allocation of resources.
A final caveat is the need for good governance, transparency, accountability, rule of law and the enforceability of contracts.<br>
slide33. INCEIF, The Global University of Islamic Finance Lorong Universiti A,
59100 Kuala Lumpur, Malaysia Thank you
obiya@inceif.org<br>