
WELCOME By: CMA Harshad S. Deshpande, Practicing
CP
Published · 41 slides · 0 views

1 / 1
Description
WELCOME By: CMA Harshad S. Deshpande, Practicing Cost Accountant M.com, ACMA, CS, CISA(USA),CIMA(UK) -: Presentation on :- Companies (Cost Records and Audit) Amendment Rules 2014 AGENDA Applicability of Cost Records Applicability of Cost
Related Topics
Share
Embed code
Download this presentation From Below
"WELCOME By: CMA Harshad S. Deshpande, Practicing" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
WELCOME By: CMA Harshad S. Deshpande,
Practicing Cost Accountant
M.com, ACMA, CS, CISA(USA),CIMA(UK) -: Presentation on :-
Companies (Cost Records and Audit) Amendment Rules 2014<br>
Practicing Cost Accountant
M.com, ACMA, CS, CISA(USA),CIMA(UK) -: Presentation on :-
Companies (Cost Records and Audit) Amendment Rules 2014<br>
02
AGENDA Applicability of Cost Records
Applicability of Cost Audit
3. Form CR-3 for Cost Audit Report
4. Annexure to Cost Audit Report<br>
Applicability of Cost Audit
3. Form CR-3 for Cost Audit Report
4. Annexure to Cost Audit Report<br>
03
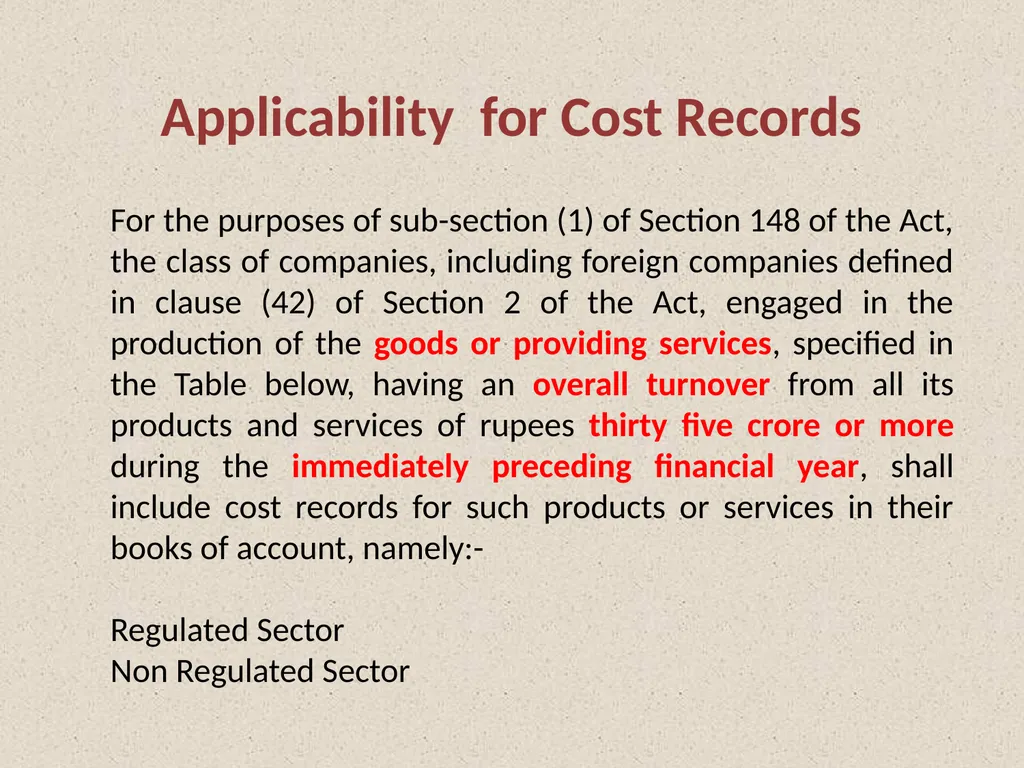
Applicability for Cost Records For the purposes of sub-section (1) of Section 148 of the Act, the class of companies, including foreign companies defined in clause (42) of Section 2 of the Act, engaged in the production of the goods or providing services, specified in the Table below, having an overall turnover from all its products and services of rupees thirty five crore or more during the immediately preceding financial year, shall include cost records for such products or services in their books of account, namely:-
Regulated Sector
Non Regulated Sector<br>
Regulated Sector
Non Regulated Sector<br>
04
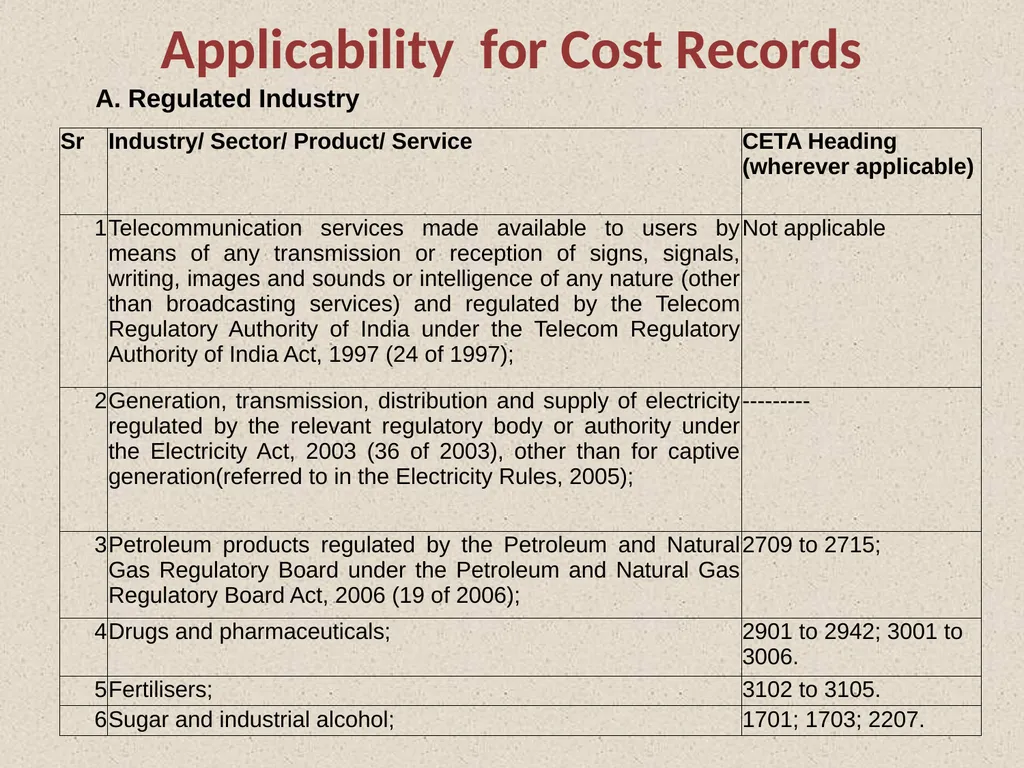
Applicability for Cost Records A. Regulated Industry<br>
05
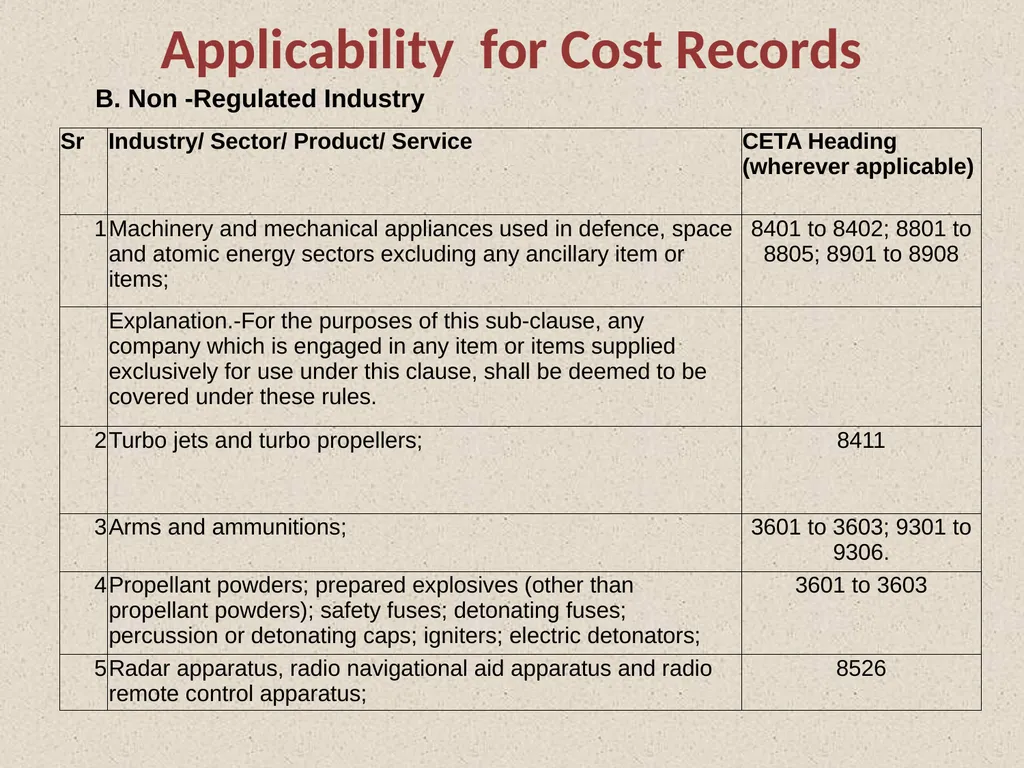
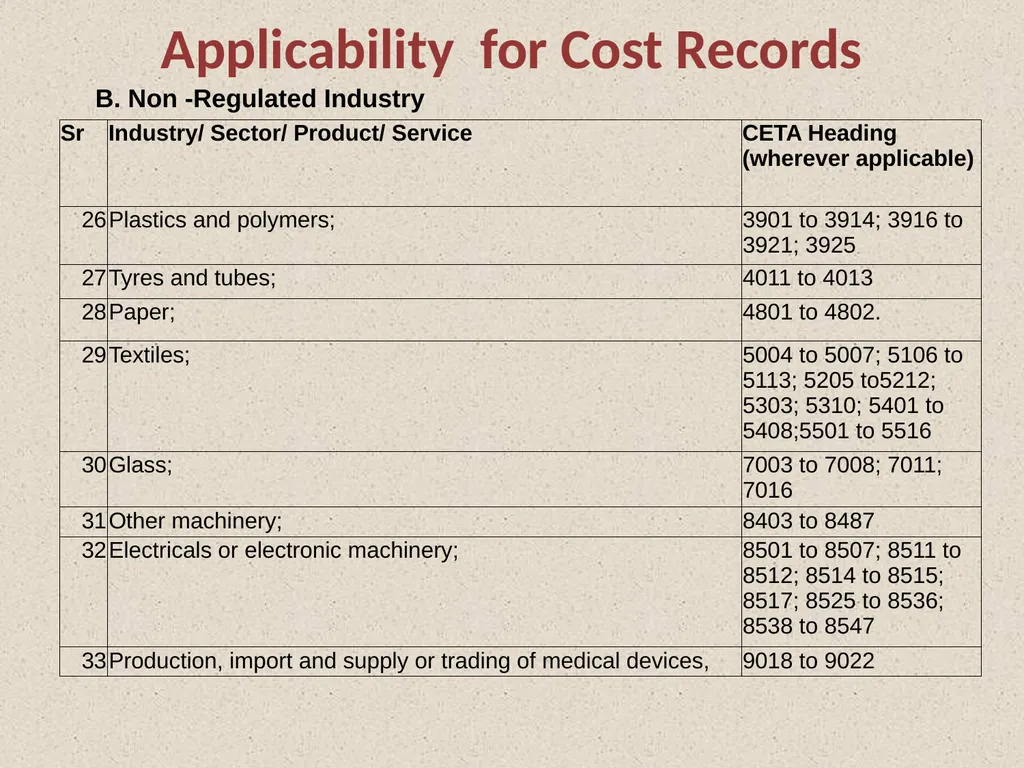
Applicability for Cost Records B. Non -Regulated Industry<br>
06
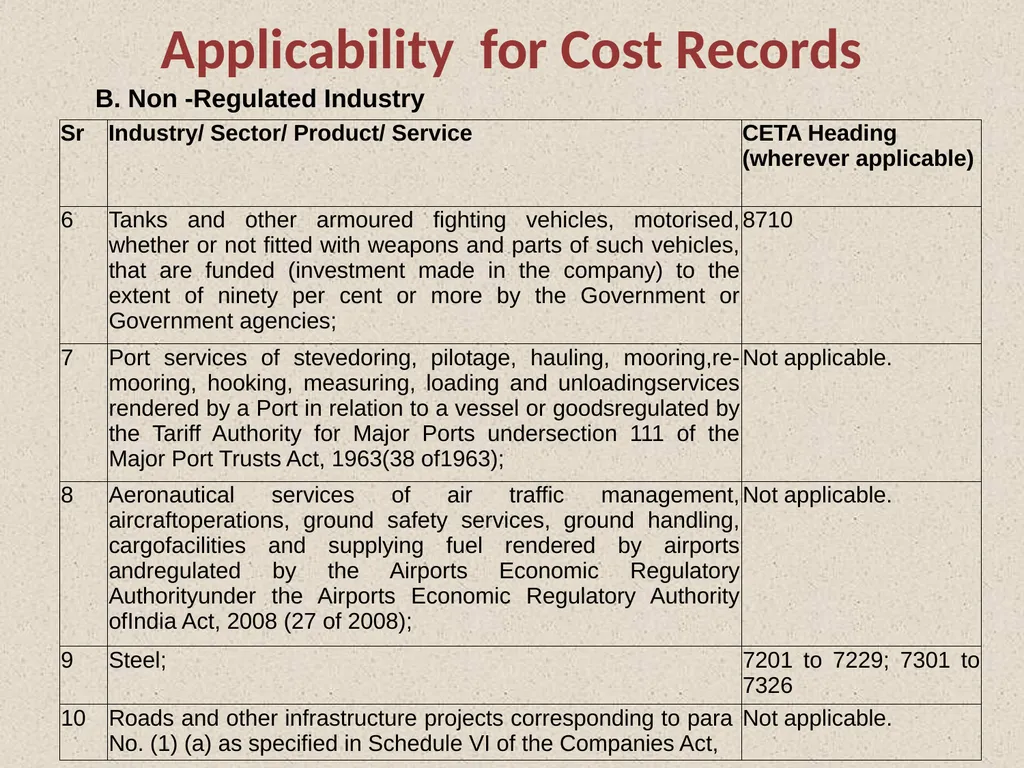
Applicability for Cost Records B. Non -Regulated Industry<br>
07
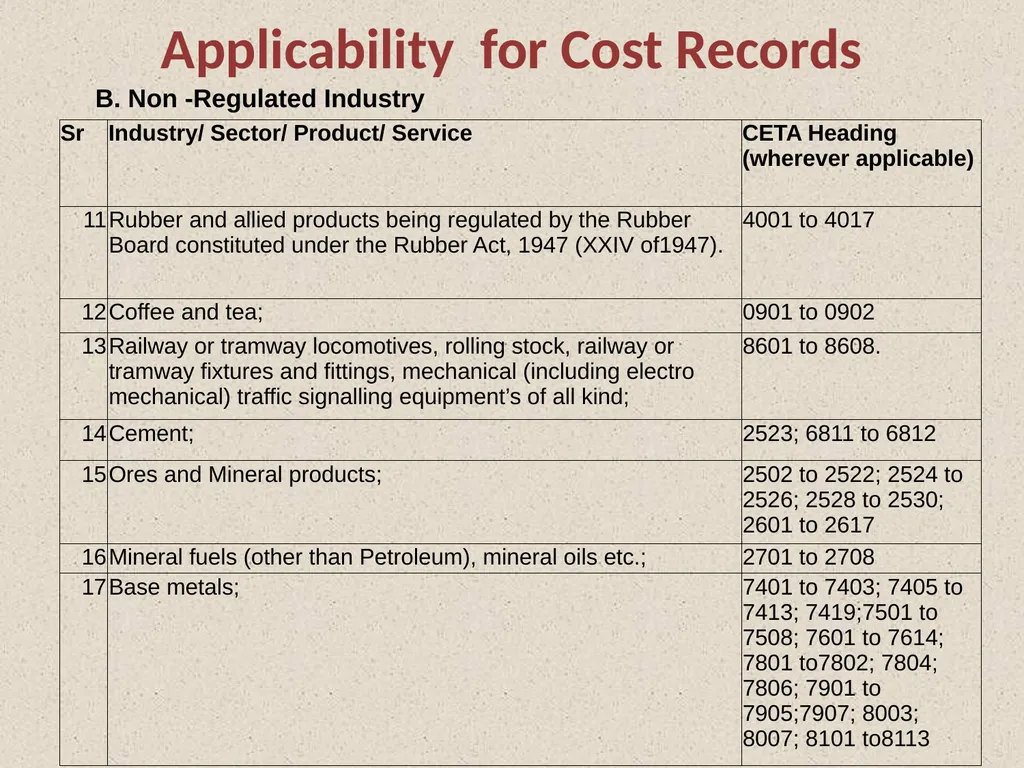
Applicability for Cost Records B. Non -Regulated Industry<br>
08
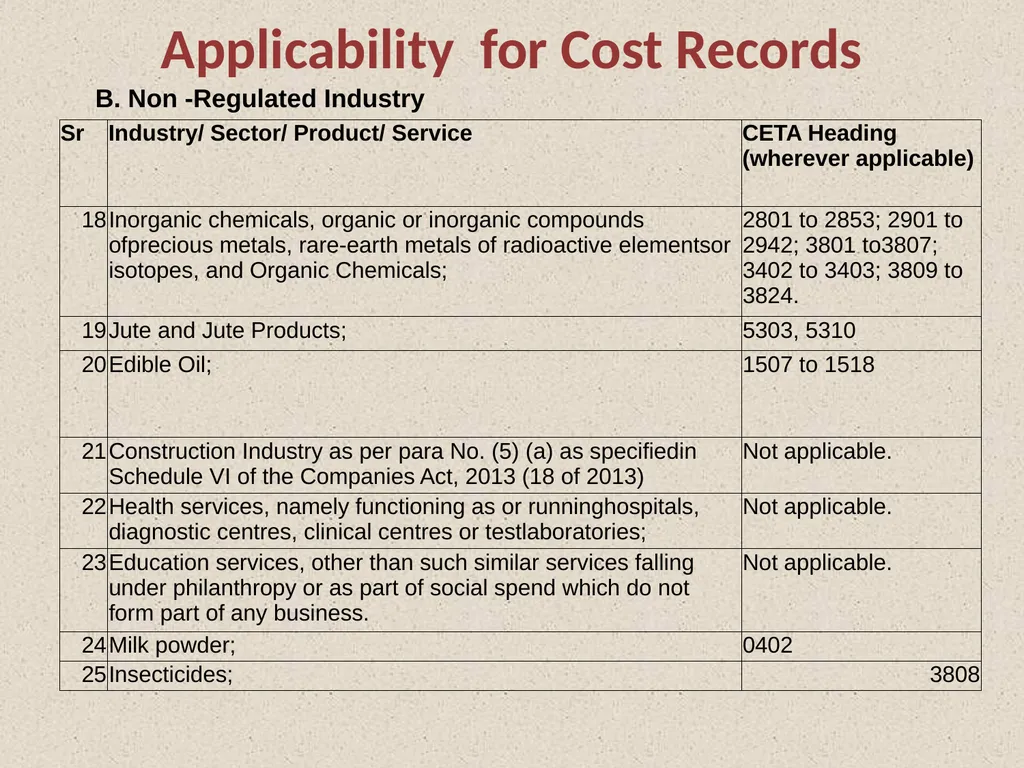
Applicability for Cost Records B. Non -Regulated Industry<br>
09
Applicability for Cost Records B. Non -Regulated Industry<br>
10
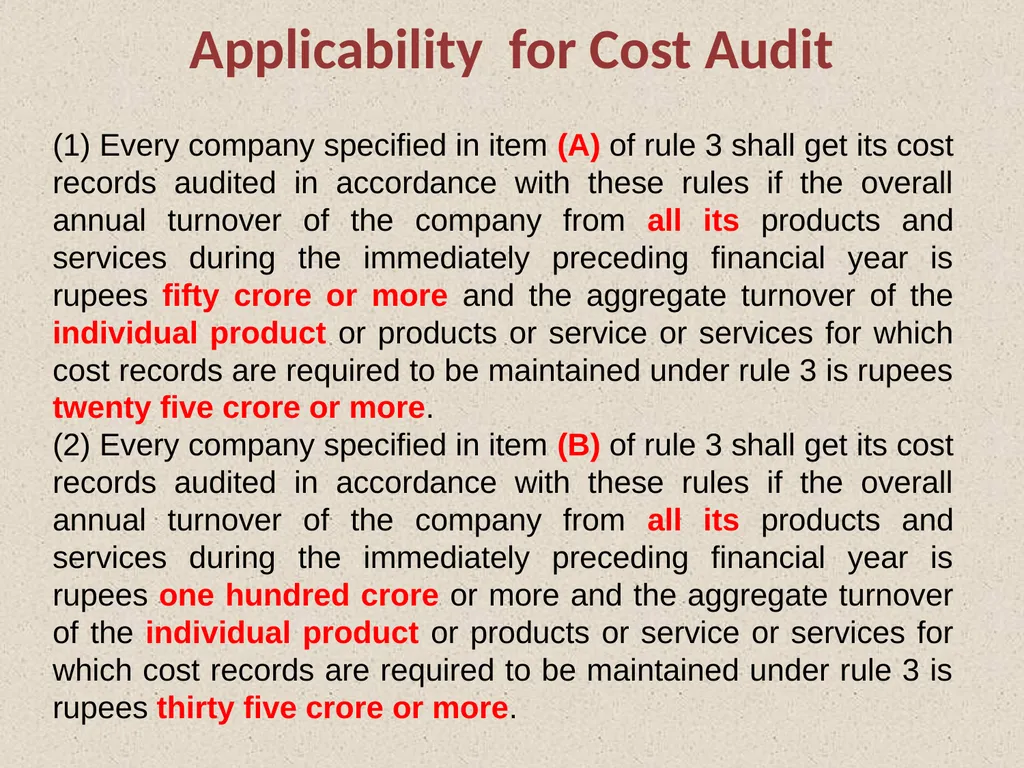
Applicability for Cost Audit (1) Every company specified in item (A) of rule 3 shall get its cost records audited in accordance with these rules if the overall annual turnover of the company from all its products and services during the immediately preceding financial year is rupees fifty crore or more and the aggregate turnover of the individual product or products or service or services for which cost records are required to be maintained under rule 3 is rupees twenty five crore or more.
(2) Every company specified in item (B) of rule 3 shall get its cost records audited in accordance with these rules if the overall annual turnover of the company from all its products and services during the immediately preceding financial year is rupees one hundred crore or more and the aggregate turnover of the individual product or products or service or services for which cost records are required to be maintained under rule 3 is rupees thirty five crore or more.<br>
(2) Every company specified in item (B) of rule 3 shall get its cost records audited in accordance with these rules if the overall annual turnover of the company from all its products and services during the immediately preceding financial year is rupees one hundred crore or more and the aggregate turnover of the individual product or products or service or services for which cost records are required to be maintained under rule 3 is rupees thirty five crore or more.<br>
11
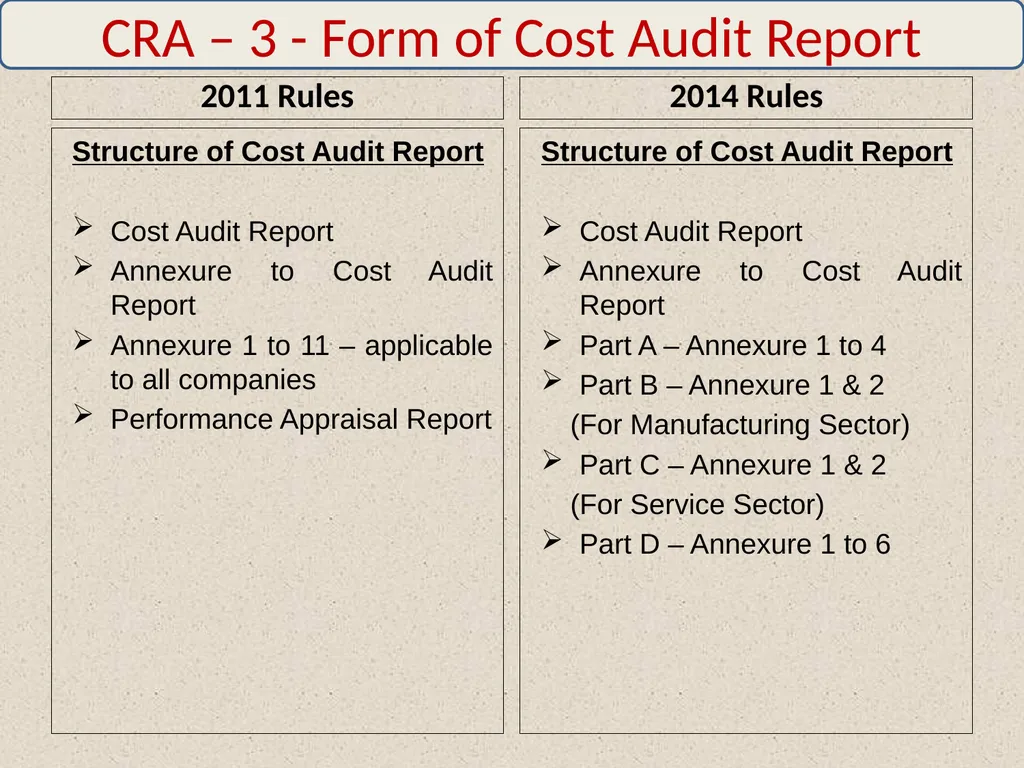
CRA – 3 - Form of Cost Audit Report 2011 Rules Structure of Cost Audit Report
Cost Audit Report
Annexure to Cost Audit Report
Annexure 1 to 11 – applicable to all companies
Performance Appraisal Report 2014 Rules Structure of Cost Audit Report
Cost Audit Report
Annexure to Cost Audit Report
Part A – Annexure 1 to 4
Part B – Annexure 1 & 2
(For Manufacturing Sector)
Part C – Annexure 1 & 2
(For Service Sector)
Part D – Annexure 1 to 6<br>
Cost Audit Report
Annexure to Cost Audit Report
Annexure 1 to 11 – applicable to all companies
Performance Appraisal Report 2014 Rules Structure of Cost Audit Report
Cost Audit Report
Annexure to Cost Audit Report
Part A – Annexure 1 to 4
Part B – Annexure 1 & 2
(For Manufacturing Sector)
Part C – Annexure 1 & 2
(For Service Sector)
Part D – Annexure 1 to 6<br>
12
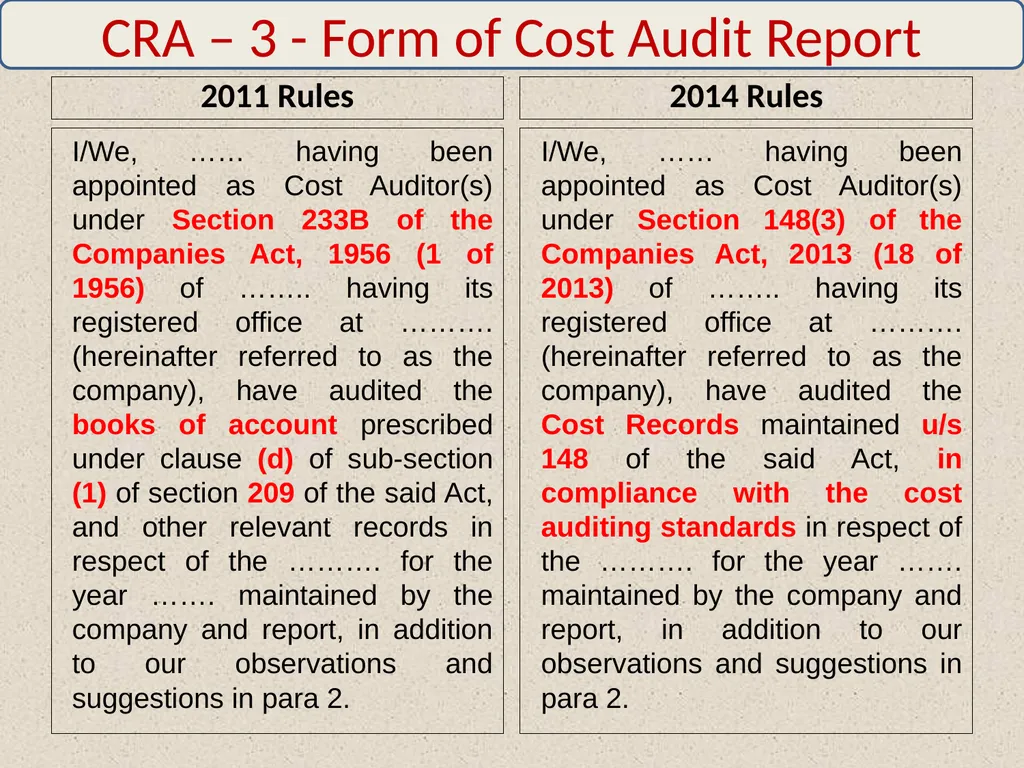
CRA – 3 - Form of Cost Audit Report 2011 Rules I/We, …… having been appointed as Cost Auditor(s) under Section 233B of the Companies Act, 1956 (1 of 1956) of …….. having its registered office at ………. (hereinafter referred to as the company), have audited the books of account prescribed under clause (d) of sub-section (1) of section 209 of the said Act, and other relevant records in respect of the ………. for the year ……. maintained by the company and report, in addition to our observations and suggestions in para 2. 2014 Rules I/We, …… having been appointed as Cost Auditor(s) under Section 148(3) of the Companies Act, 2013 (18 of 2013) of …….. having its registered office at ………. (hereinafter referred to as the company), have audited the Cost Records maintained u/s 148 of the said Act, in compliance with the cost auditing standards in respect of the ………. for the year ……. maintained by the company and report, in addition to our observations and suggestions in para 2.<br>
13
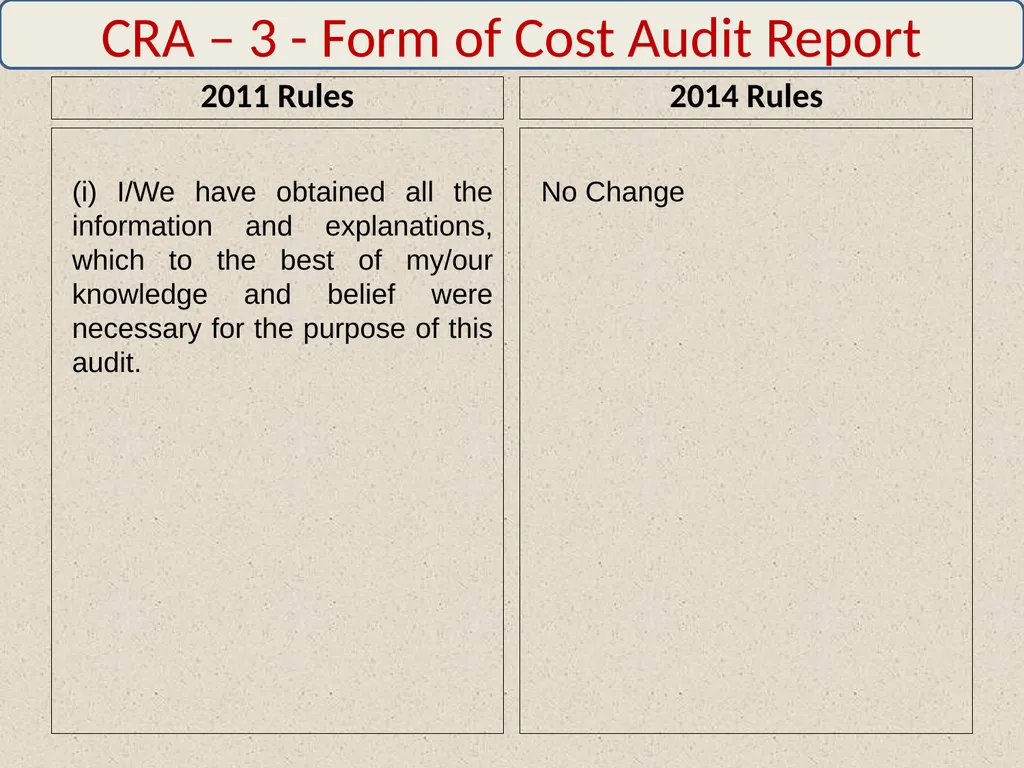
CRA – 3 - Form of Cost Audit Report 2011 Rules (i) I/We have obtained all the information and explanations, which to the best of my/our knowledge and belief were necessary for the purpose of this audit. 2014 Rules No Change<br>
14
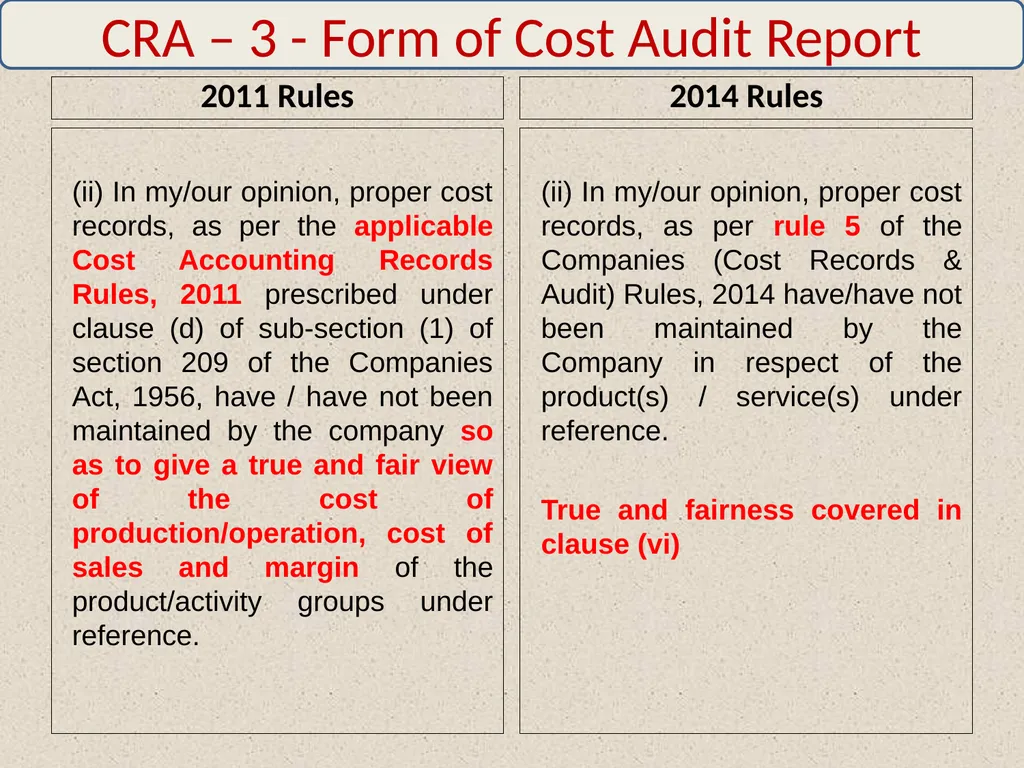
CRA – 3 - Form of Cost Audit Report 2011 Rules (ii) In my/our opinion, proper cost records, as per the applicable Cost Accounting Records Rules, 2011 prescribed under clause (d) of sub-section (1) of section 209 of the Companies Act, 1956, have / have not been maintained by the company so as to give a true and fair view of the cost of production/operation, cost of sales and margin of the product/activity groups under reference. 2014 Rules (ii) In my/our opinion, proper cost records, as per rule 5 of the Companies (Cost Records & Audit) Rules, 2014 have/have not been maintained by the Company in respect of the product(s) / service(s) under reference.
True and fairness covered in clause (vi)<br>
True and fairness covered in clause (vi)<br>
15
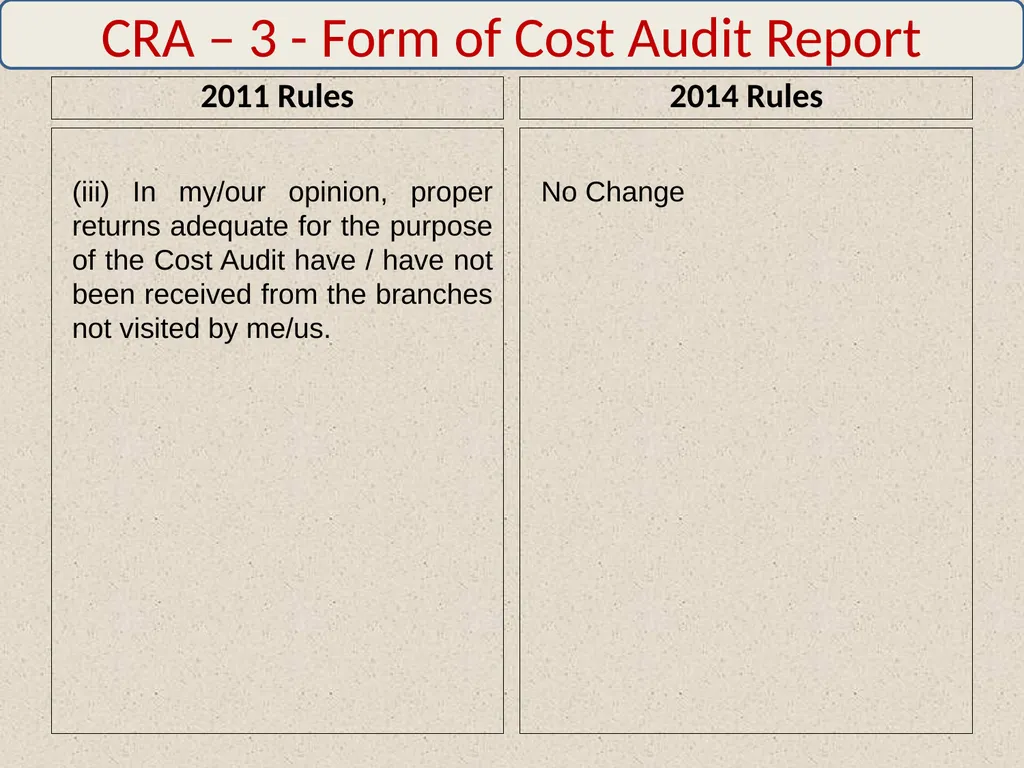
CRA – 3 - Form of Cost Audit Report 2011 Rules (iii) In my/our opinion, proper returns adequate for the purpose of the Cost Audit have / have not been received from the branches not visited by me/us. 2014 Rules No Change<br>
16
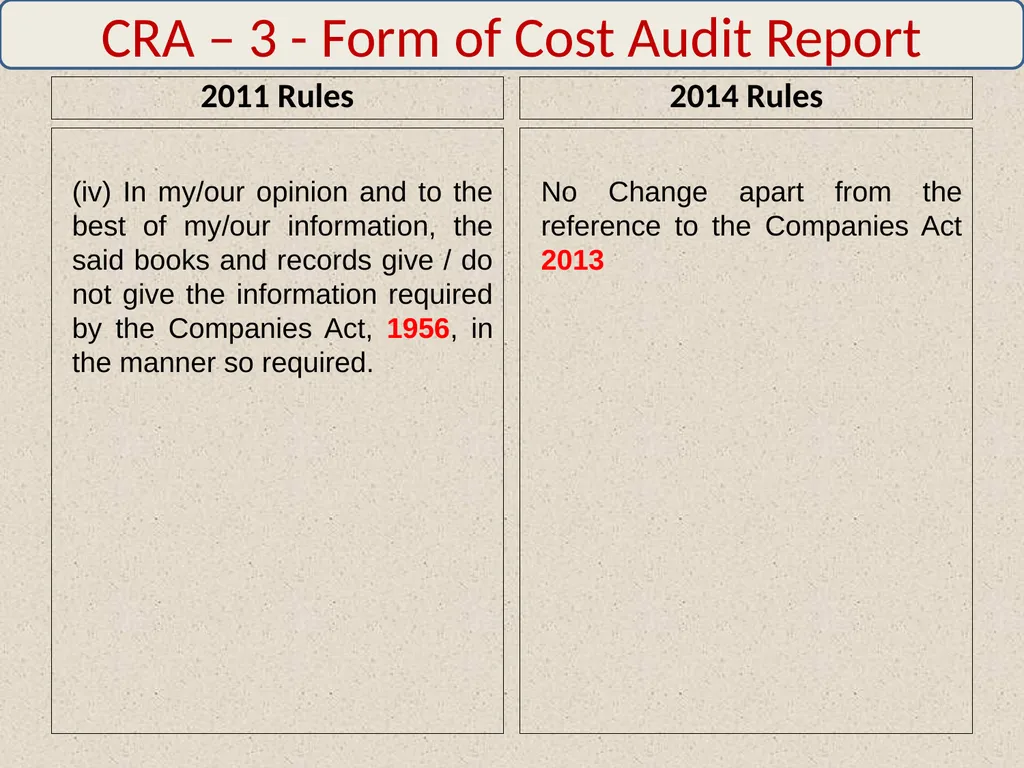
CRA – 3 - Form of Cost Audit Report 2011 Rules (iv) In my/our opinion and to the best of my/our information, the said books and records give / do not give the information required by the Companies Act, 1956, in the manner so required. 2014 Rules No Change apart from the reference to the Companies Act 2013<br>
17
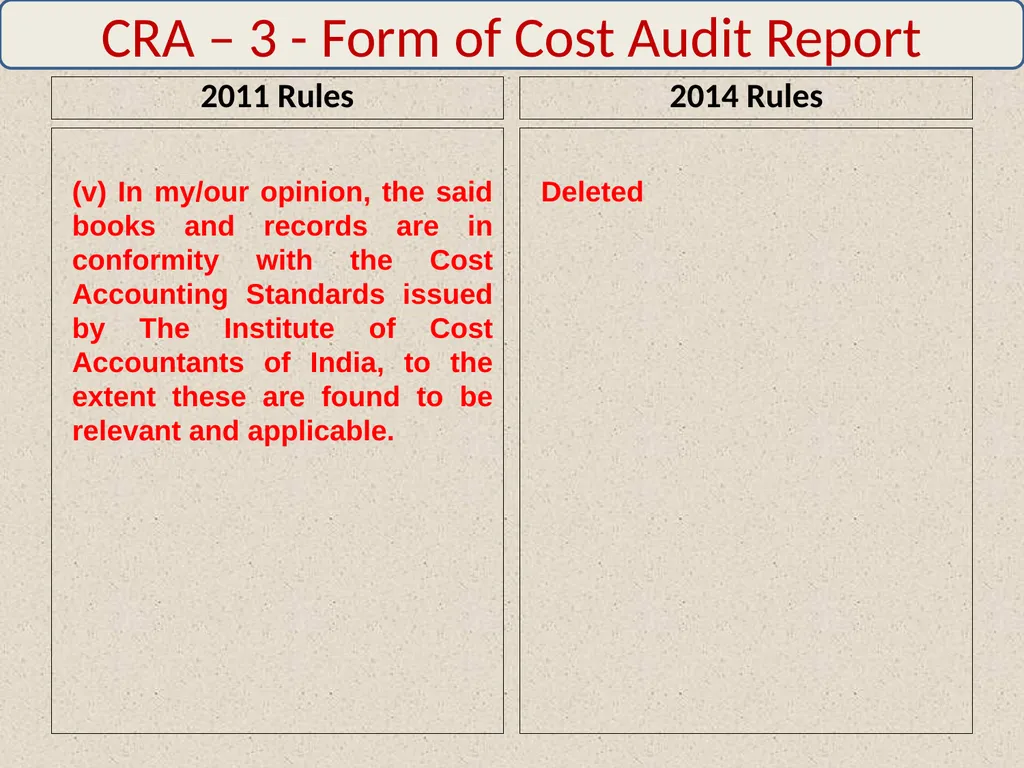
CRA – 3 - Form of Cost Audit Report 2011 Rules (v) In my/our opinion, the said books and records are in conformity with the Cost Accounting Standards issued by The Institute of Cost Accountants of India, to the extent these are found to be relevant and applicable. 2014 Rules Deleted<br>
18
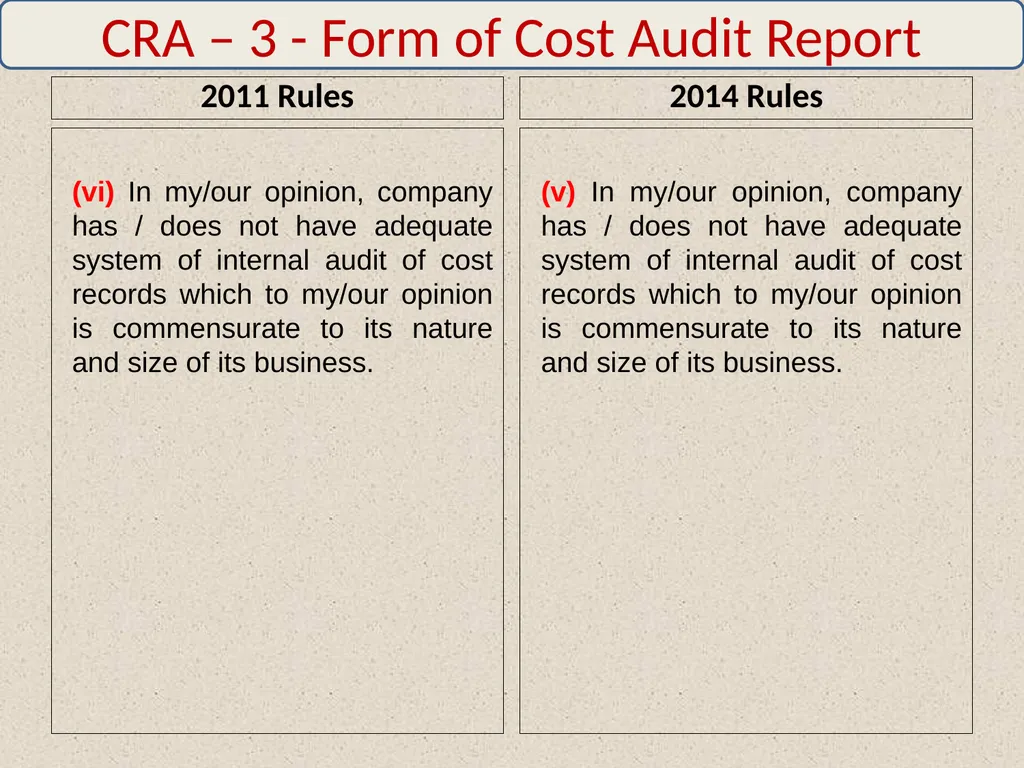
CRA – 3 - Form of Cost Audit Report 2011 Rules (vi) In my/our opinion, company has / does not have adequate system of internal audit of cost records which to my/our opinion is commensurate to its nature and size of its business. 2014 Rules (v) In my/our opinion, company has / does not have adequate system of internal audit of cost records which to my/our opinion is commensurate to its nature and size of its business.<br>
19
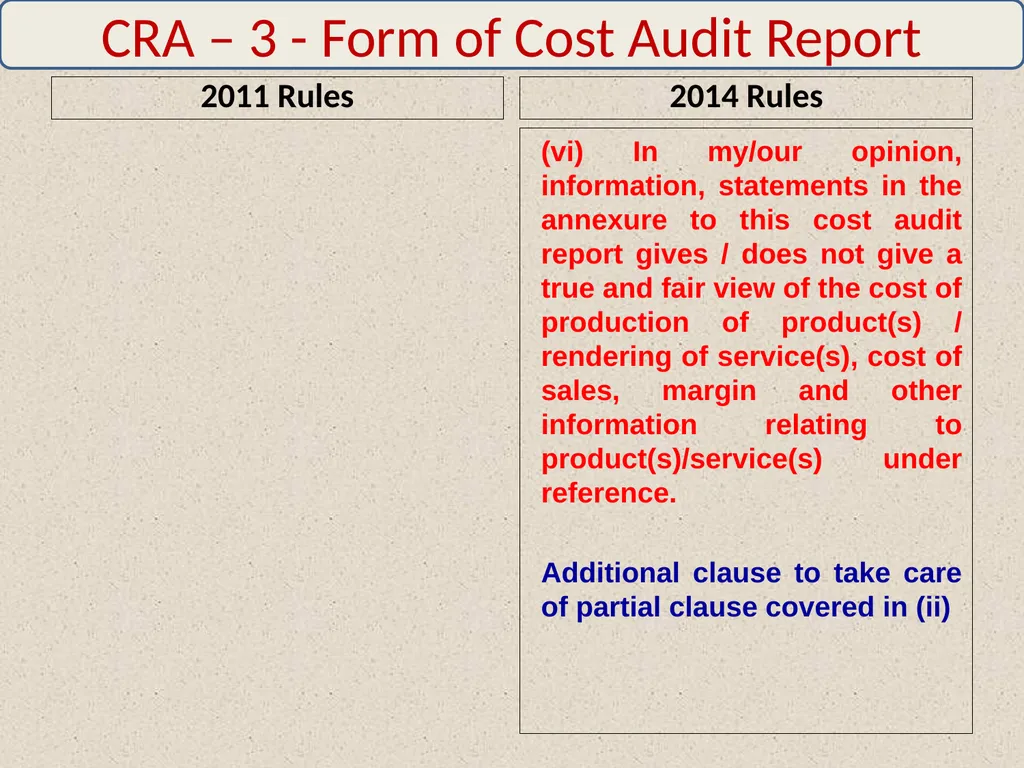
CRA – 3 - Form of Cost Audit Report 2011 Rules 2014 Rules (vi) In my/our opinion, information, statements in the annexure to this cost audit report gives / does not give a true and fair view of the cost of production of product(s) / rendering of service(s), cost of sales, margin and other information relating to product(s)/service(s) under reference.
Additional clause to take care of partial clause covered in (ii)<br>
Additional clause to take care of partial clause covered in (ii)<br>
20
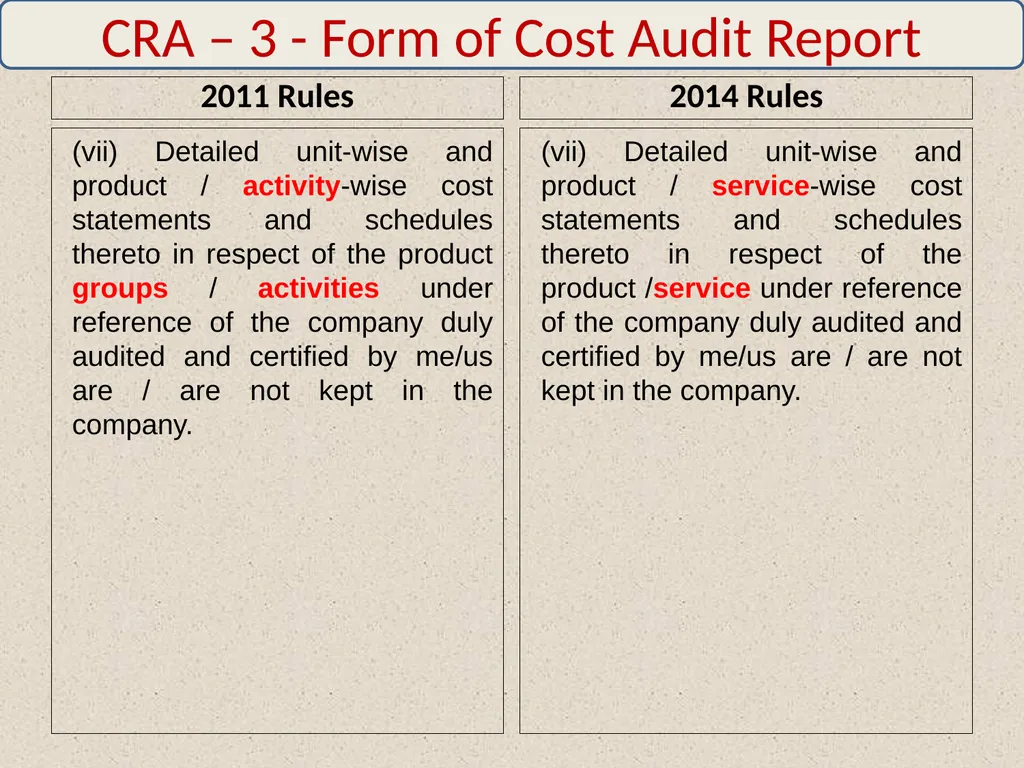
CRA – 3 - Form of Cost Audit Report 2011 Rules (vii) Detailed unit-wise and product / activity-wise cost statements and schedules thereto in respect of the product groups / activities under reference of the company duly audited and certified by me/us are / are not kept in the company. 2014 Rules (vii) Detailed unit-wise and product / service-wise cost statements and schedules thereto in respect of the product /service under reference of the company duly audited and certified by me/us are / are not kept in the company.<br>
21
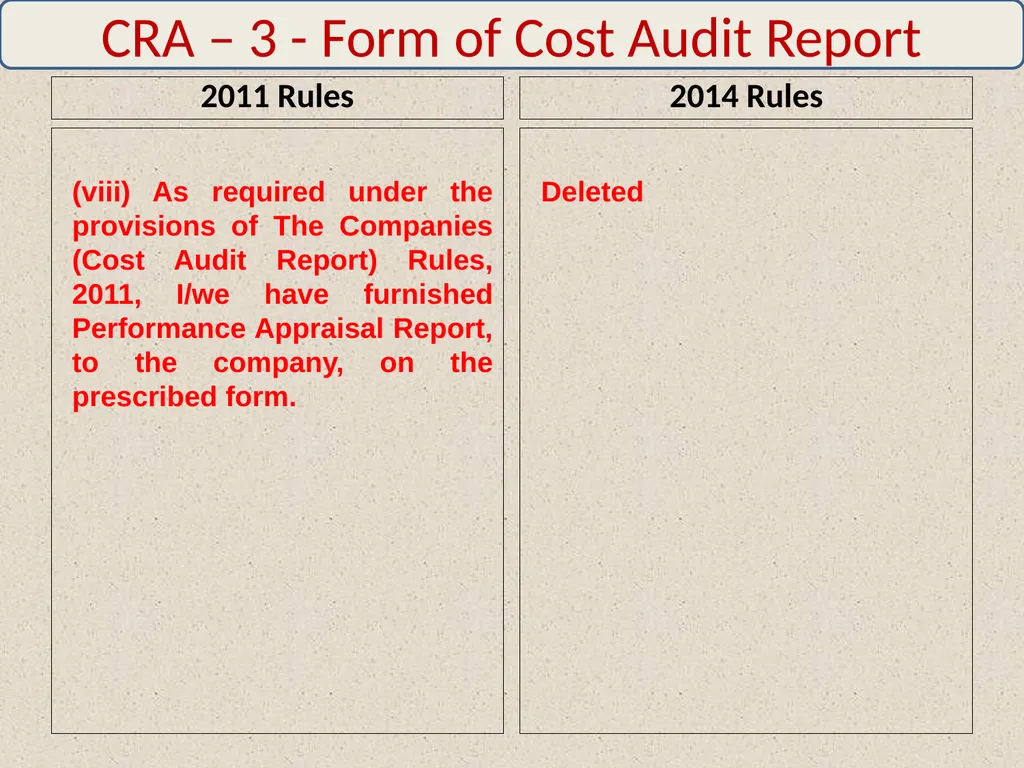
CRA – 3 - Form of Cost Audit Report 2011 Rules (viii) As required under the provisions of The Companies (Cost Audit Report) Rules, 2011, I/we have furnished Performance Appraisal Report, to the company, on the prescribed form. 2014 Rules Deleted<br>
22
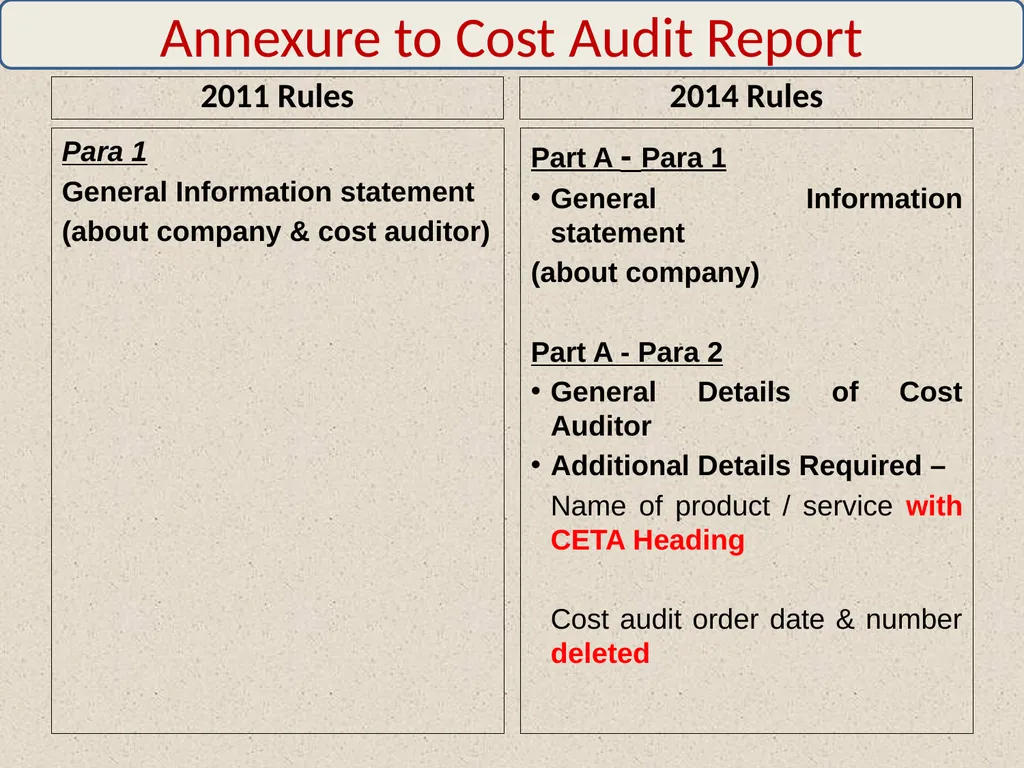
Annexure to Cost Audit Report 2011 Rules Para 1
General Information statement
(about company & cost auditor) 2014 Rules Part A - Para 1
General Information statement
(about company)
Part A - Para 2
General Details of Cost Auditor
Additional Details Required –
Name of product / service with CETA Heading
Cost audit order date & number deleted<br>
General Information statement
(about company & cost auditor) 2014 Rules Part A - Para 1
General Information statement
(about company)
Part A - Para 2
General Details of Cost Auditor
Additional Details Required –
Name of product / service with CETA Heading
Cost audit order date & number deleted<br>
23
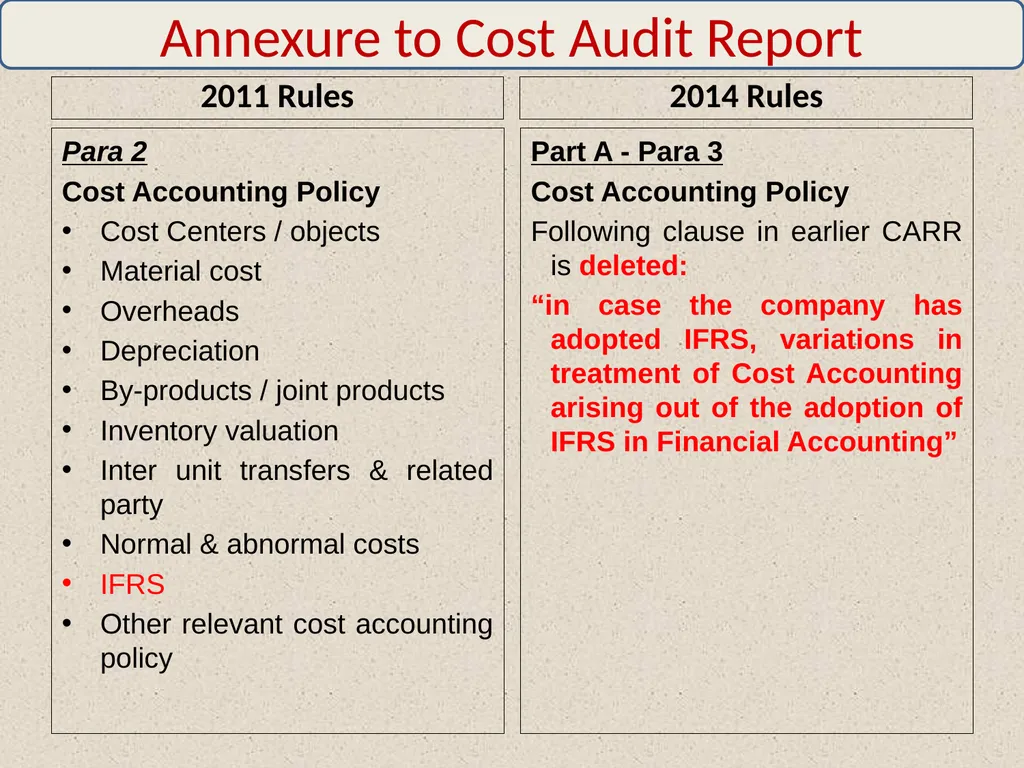
Annexure to Cost Audit Report 2011 Rules Para 2
Cost Accounting Policy
Cost Centers / objects
Material cost
Overheads
Depreciation
By-products / joint products
Inventory valuation
Inter unit transfers & related party
Normal & abnormal costs
IFRS
Other relevant cost accounting policy 2014 Rules Part A - Para 3
Cost Accounting Policy
Following clause in earlier CARR is deleted:
“in case the company has adopted IFRS, variations in treatment of Cost Accounting arising out of the adoption of IFRS in Financial Accounting”<br>
Cost Accounting Policy
Cost Centers / objects
Material cost
Overheads
Depreciation
By-products / joint products
Inventory valuation
Inter unit transfers & related party
Normal & abnormal costs
IFRS
Other relevant cost accounting policy 2014 Rules Part A - Para 3
Cost Accounting Policy
Following clause in earlier CARR is deleted:
“in case the company has adopted IFRS, variations in treatment of Cost Accounting arising out of the adoption of IFRS in Financial Accounting”<br>
24
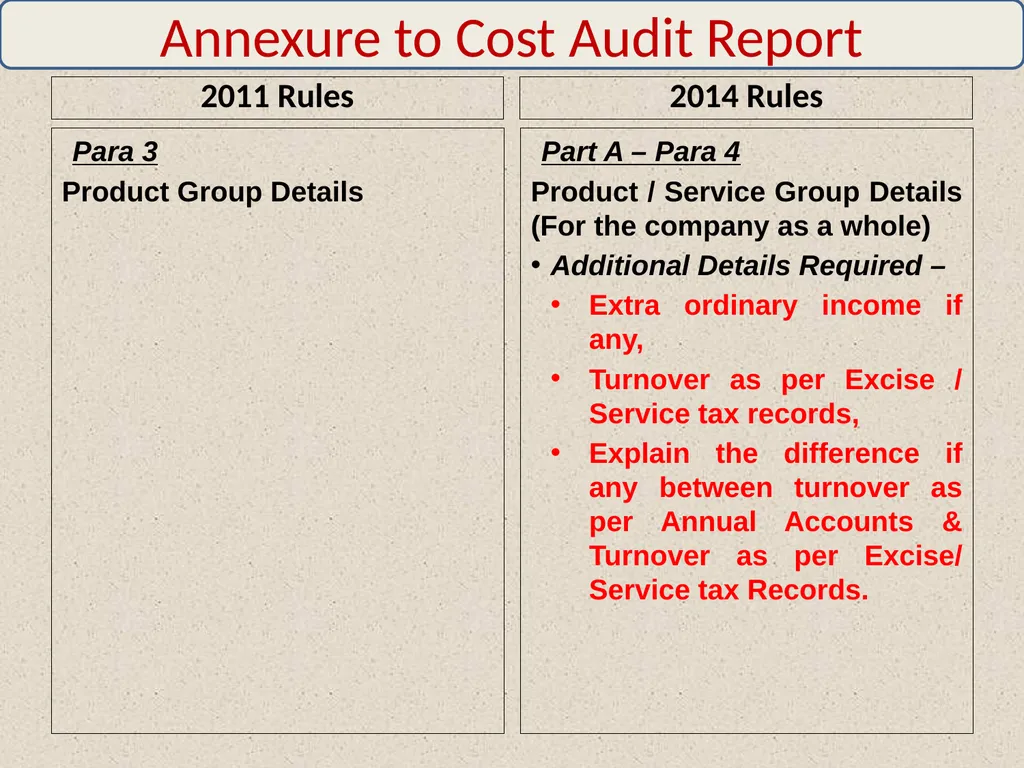
Annexure to Cost Audit Report 2011 Rules Para 3
Product Group Details 2014 Rules Part A – Para 4
Product / Service Group Details (For the company as a whole)
Additional Details Required –
Extra ordinary income if any,
Turnover as per Excise / Service tax records,
Explain the difference if any between turnover as per Annual Accounts & Turnover as per Excise/ Service tax Records.<br>
25
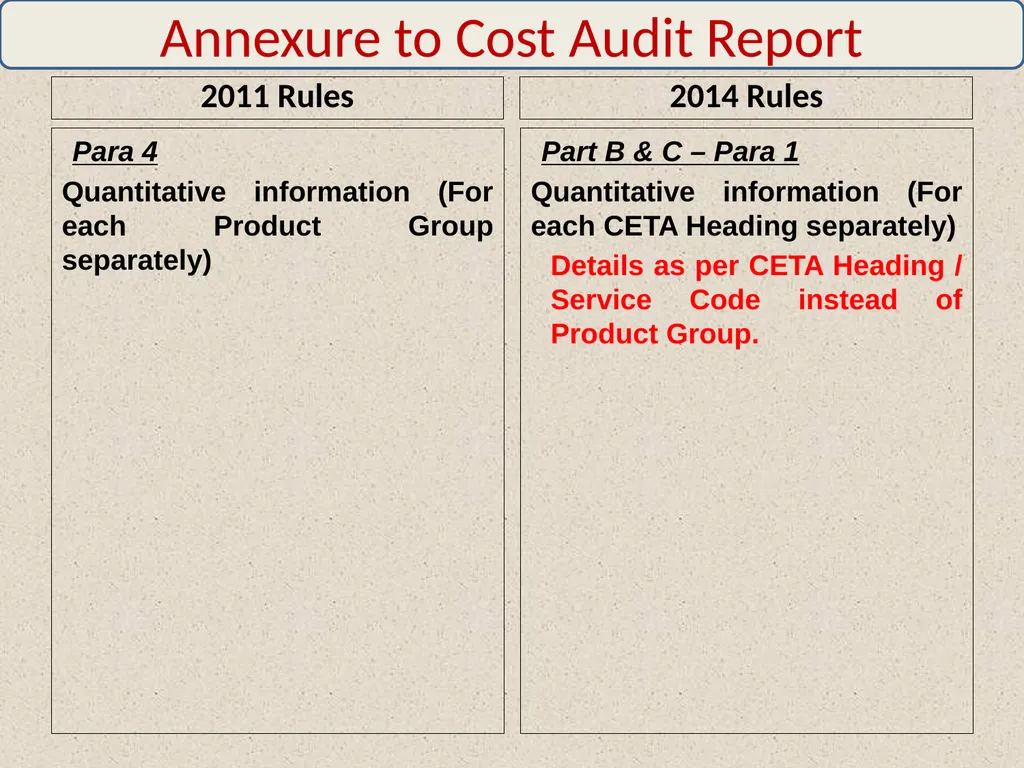
Annexure to Cost Audit Report 2011 Rules Para 4
Quantitative information (For each Product Group separately) 2014 Rules Part B & C – Para 1
Quantitative information (For each CETA Heading separately)
Details as per CETA Heading / Service Code instead of Product Group.<br>
Quantitative information (For each Product Group separately) 2014 Rules Part B & C – Para 1
Quantitative information (For each CETA Heading separately)
Details as per CETA Heading / Service Code instead of Product Group.<br>
26
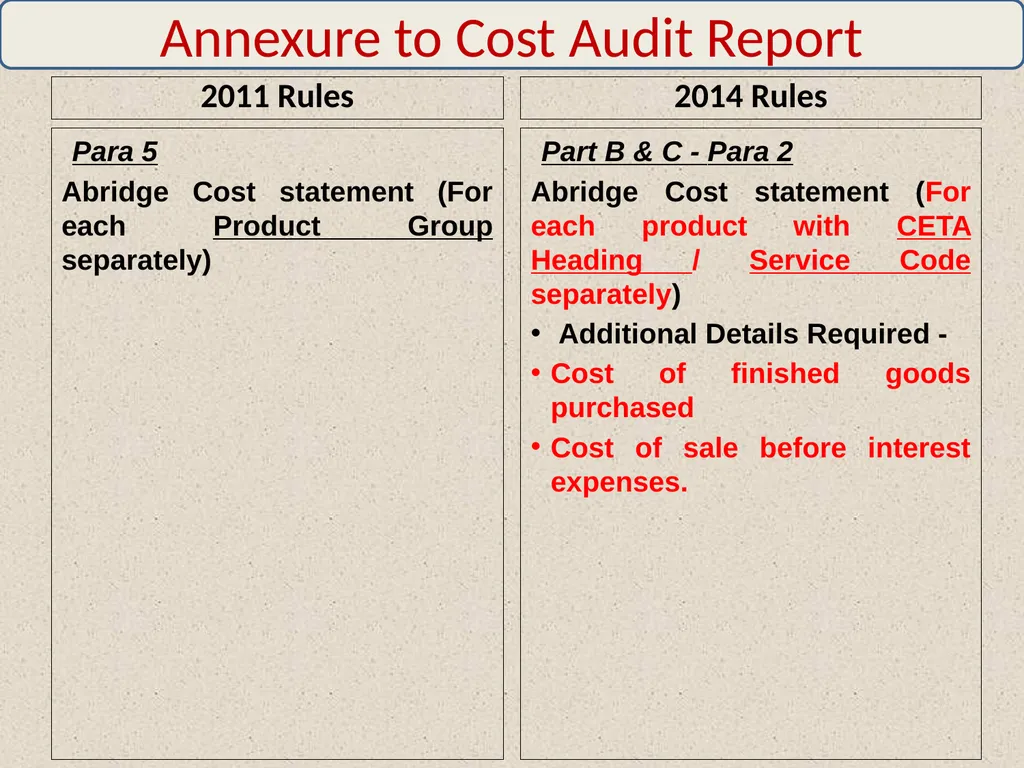
Annexure to Cost Audit Report 2011 Rules Para 5
Abridge Cost statement (For each Product Group separately) 2014 Rules Part B & C - Para 2
Abridge Cost statement (For each product with CETA Heading / Service Code separately)
Additional Details Required -
Cost of finished goods purchased
Cost of sale before interest expenses.<br>
Abridge Cost statement (For each Product Group separately) 2014 Rules Part B & C - Para 2
Abridge Cost statement (For each product with CETA Heading / Service Code separately)
Additional Details Required -
Cost of finished goods purchased
Cost of sale before interest expenses.<br>
27
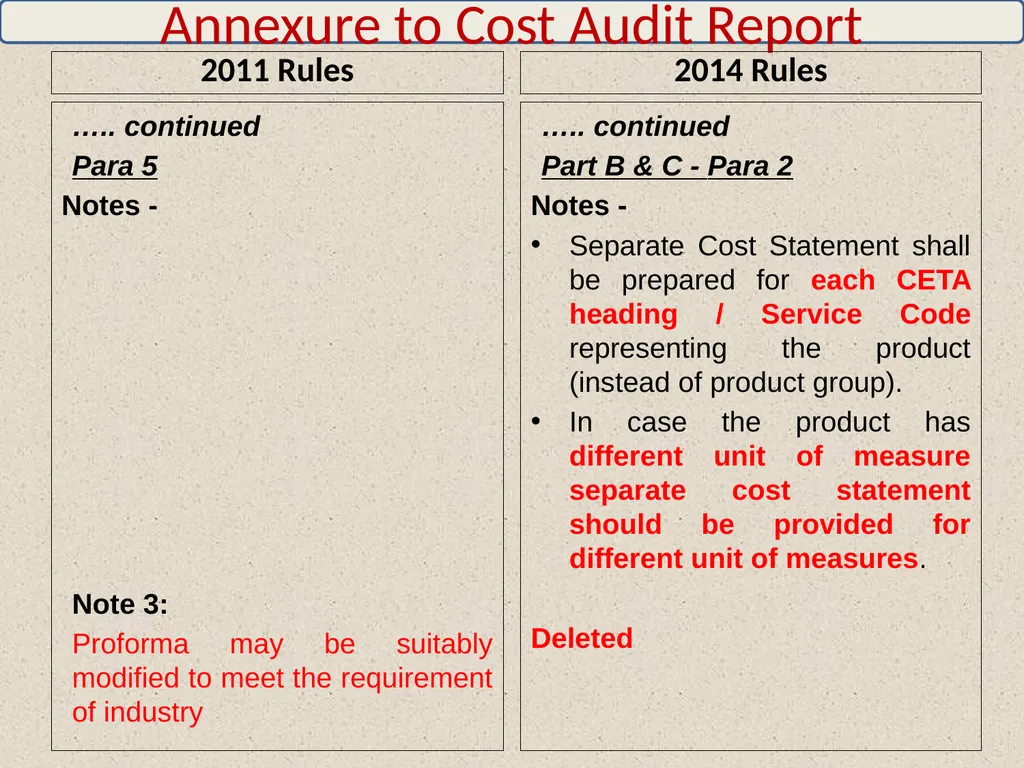
Annexure to Cost Audit Report 2011 Rules ….. continued
Para 5
Notes -
Note 3:
Proforma may be suitably modified to meet the requirement of industry 2014 Rules ….. continued
Part B & C - Para 2
Notes -
Separate Cost Statement shall be prepared for each CETA heading / Service Code representing the product (instead of product group).
In case the product has different unit of measure separate cost statement should be provided for different unit of measures.
Deleted<br>
28
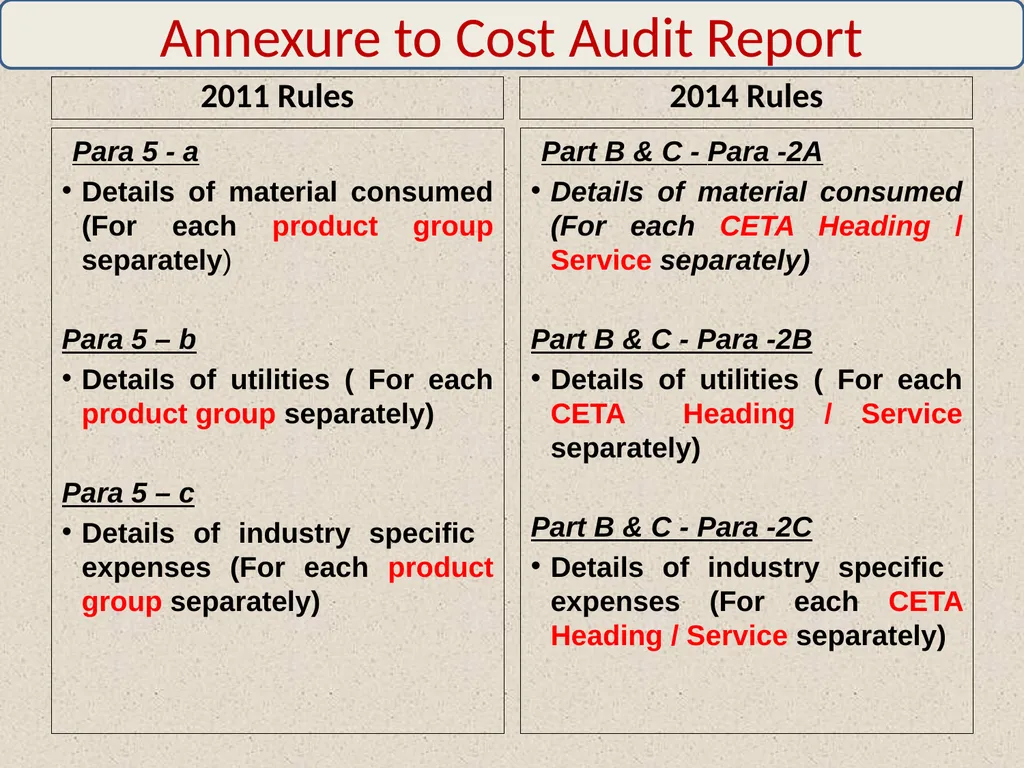
Annexure to Cost Audit Report 2011 Rules Para 5 - a
Details of material consumed (For each product group separately)
Para 5 – b
Details of utilities ( For each product group separately)
Para 5 – c
Details of industry specific expenses (For each product group separately) 2014 Rules Part B & C - Para -2A
Details of material consumed (For each CETA Heading / Service separately)
Part B & C - Para -2B
Details of utilities ( For each CETA Heading / Service separately)
Part B & C - Para -2C
Details of industry specific expenses (For each CETA Heading / Service separately)<br>
29
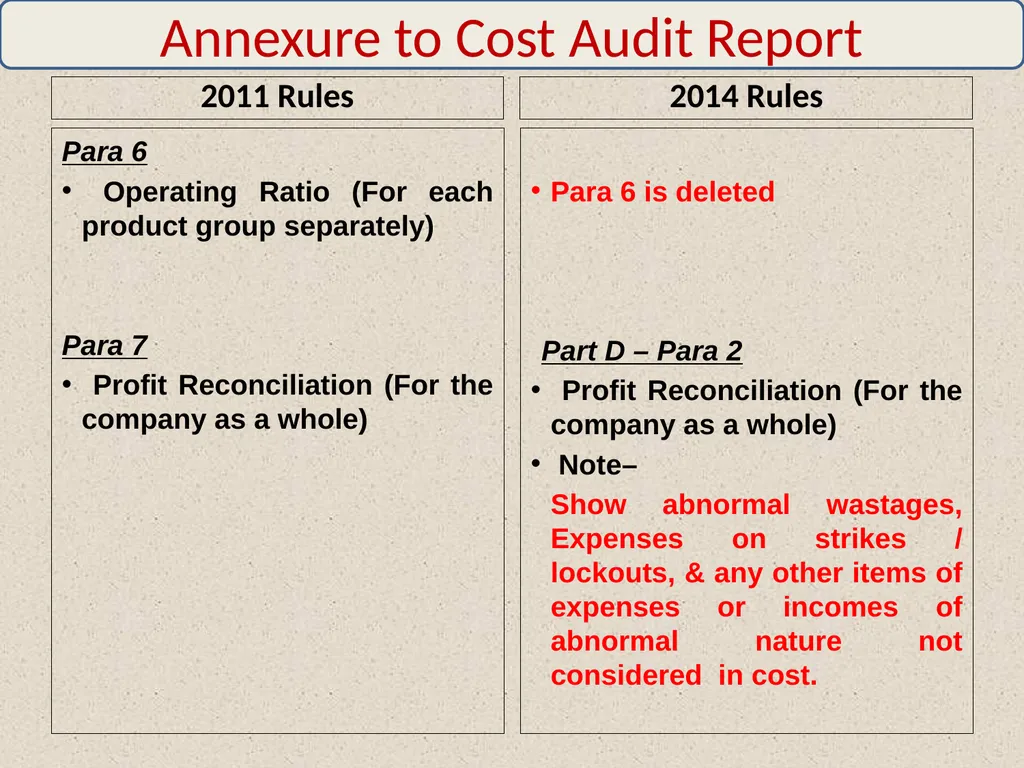
Annexure to Cost Audit Report 2011 Rules Para 6
Operating Ratio (For each product group separately)
Para 7
Profit Reconciliation (For the company as a whole) 2014 Rules Para 6 is deleted
Part D – Para 2
Profit Reconciliation (For the company as a whole)
Note–
Show abnormal wastages, Expenses on strikes / lockouts, & any other items of expenses or incomes of abnormal nature not considered in cost.<br>
30
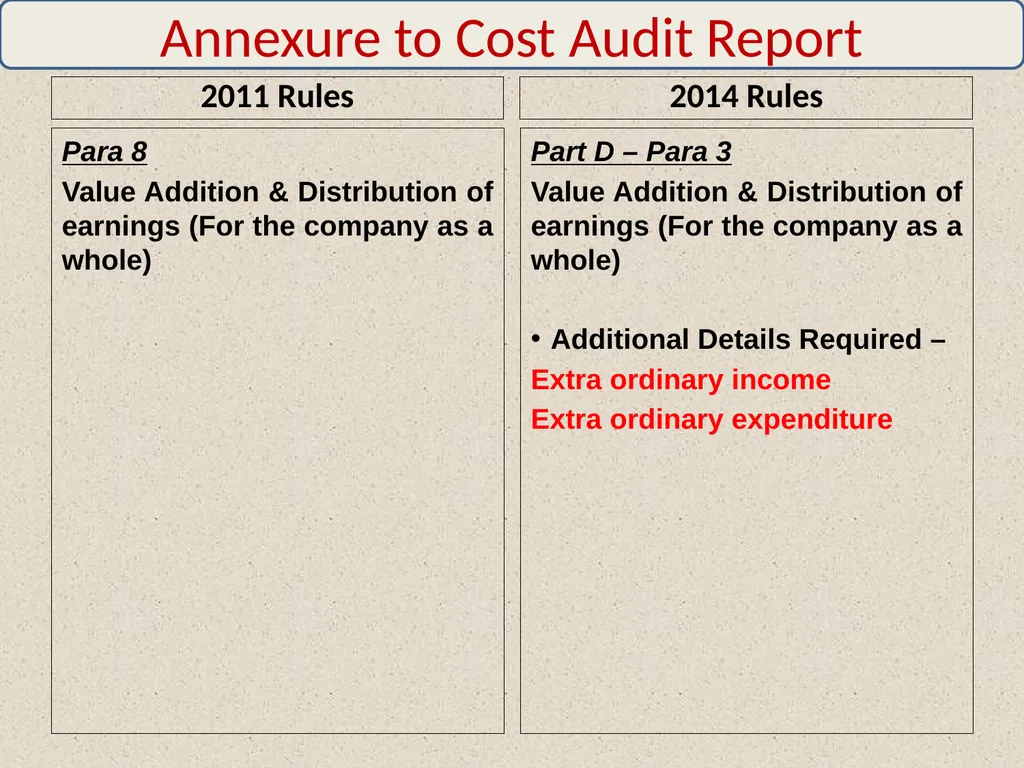
Annexure to Cost Audit Report 2011 Rules Para 8
Value Addition & Distribution of earnings (For the company as a whole) 2014 Rules Part D – Para 3
Value Addition & Distribution of earnings (For the company as a whole)
Additional Details Required –
Extra ordinary income
Extra ordinary expenditure<br>
Value Addition & Distribution of earnings (For the company as a whole) 2014 Rules Part D – Para 3
Value Addition & Distribution of earnings (For the company as a whole)
Additional Details Required –
Extra ordinary income
Extra ordinary expenditure<br>
31
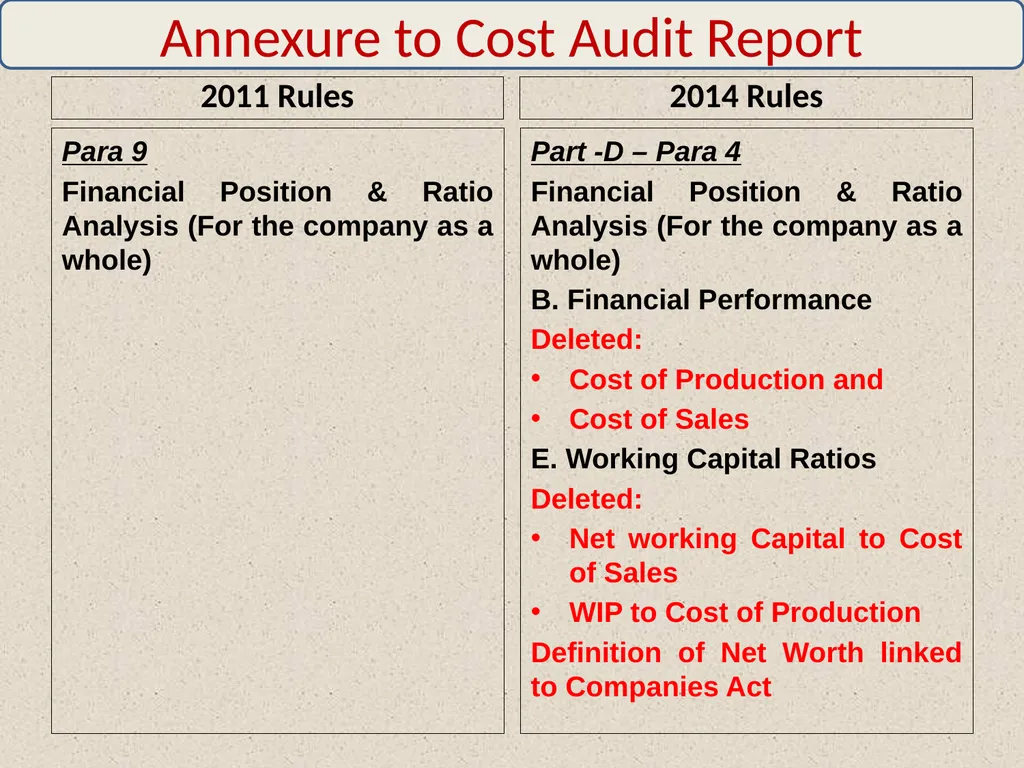
Annexure to Cost Audit Report 2011 Rules Para 9
Financial Position & Ratio Analysis (For the company as a whole) 2014 Rules Part -D – Para 4
Financial Position & Ratio Analysis (For the company as a whole)
B. Financial Performance
Deleted:
Cost of Production and
Cost of Sales
E. Working Capital Ratios
Deleted:
Net working Capital to Cost of Sales
WIP to Cost of Production
Definition of Net Worth linked to Companies Act<br>
32
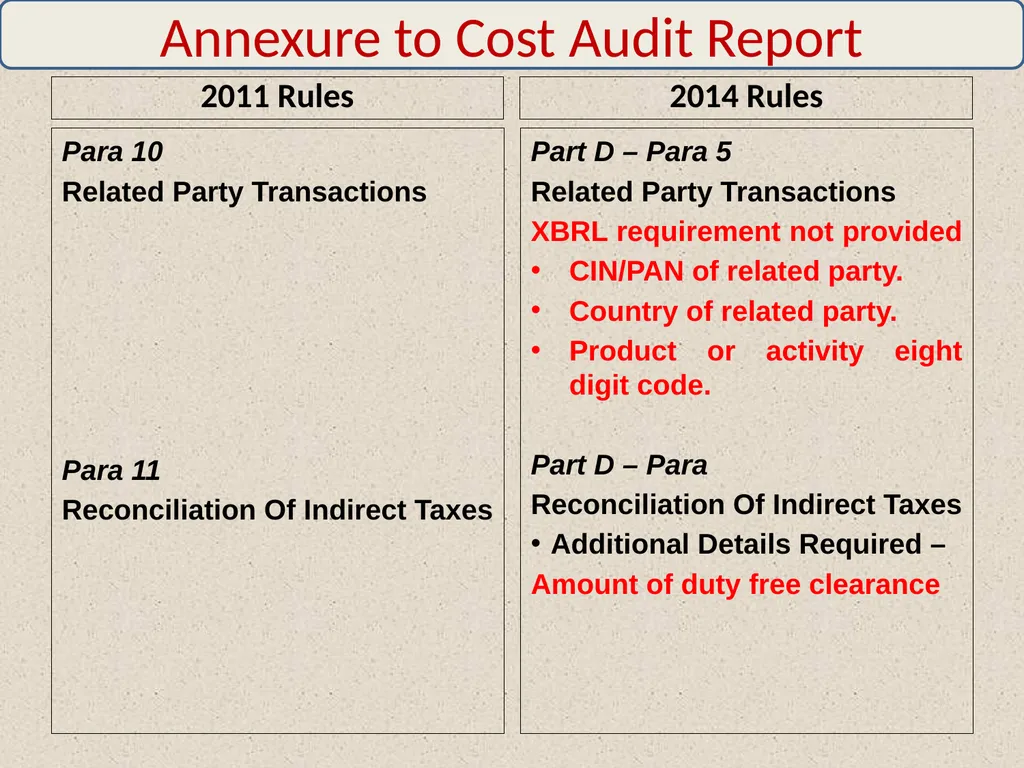
Annexure to Cost Audit Report 2011 Rules Para 10
Related Party Transactions
Para 11
Reconciliation Of Indirect Taxes 2014 Rules Part D – Para 5
Related Party Transactions
XBRL requirement not provided
CIN/PAN of related party.
Country of related party.
Product or activity eight digit code.
Part D – Para
Reconciliation Of Indirect Taxes
Additional Details Required –
Amount of duty free clearance<br>
Related Party Transactions
Para 11
Reconciliation Of Indirect Taxes 2014 Rules Part D – Para 5
Related Party Transactions
XBRL requirement not provided
CIN/PAN of related party.
Country of related party.
Product or activity eight digit code.
Part D – Para
Reconciliation Of Indirect Taxes
Additional Details Required –
Amount of duty free clearance<br>
33
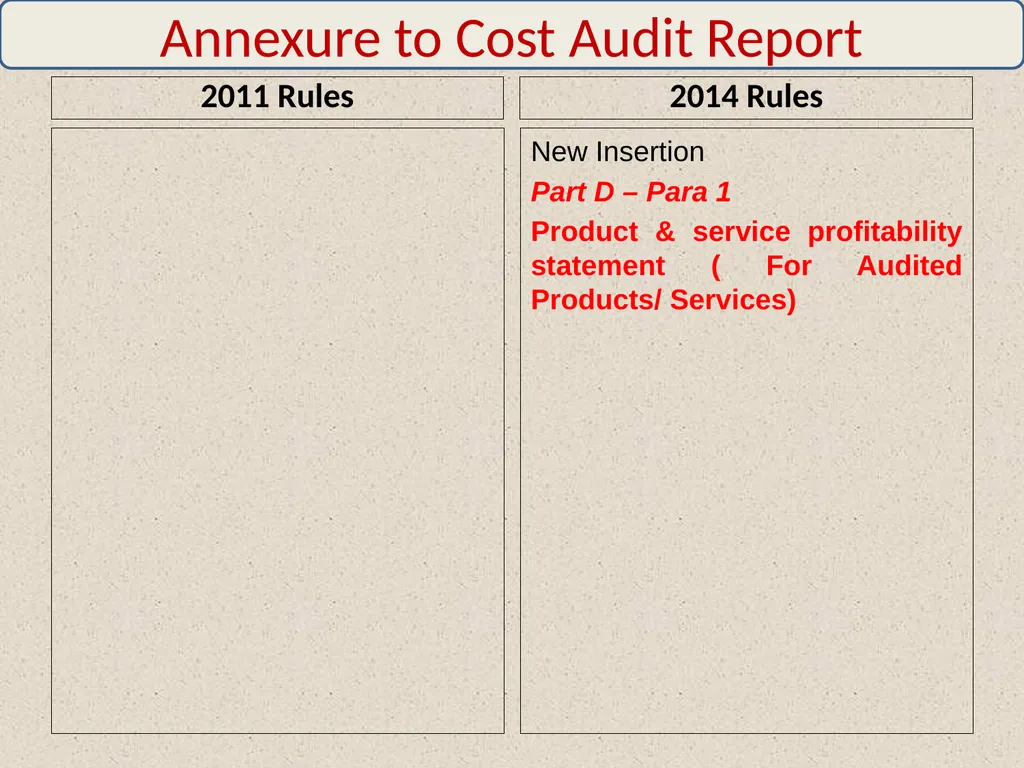
Annexure to Cost Audit Report 2011 Rules 2014 Rules New Insertion
Part D – Para 1
Product & service profitability statement ( For Audited Products/ Services)<br>
Part D – Para 1
Product & service profitability statement ( For Audited Products/ Services)<br>
34
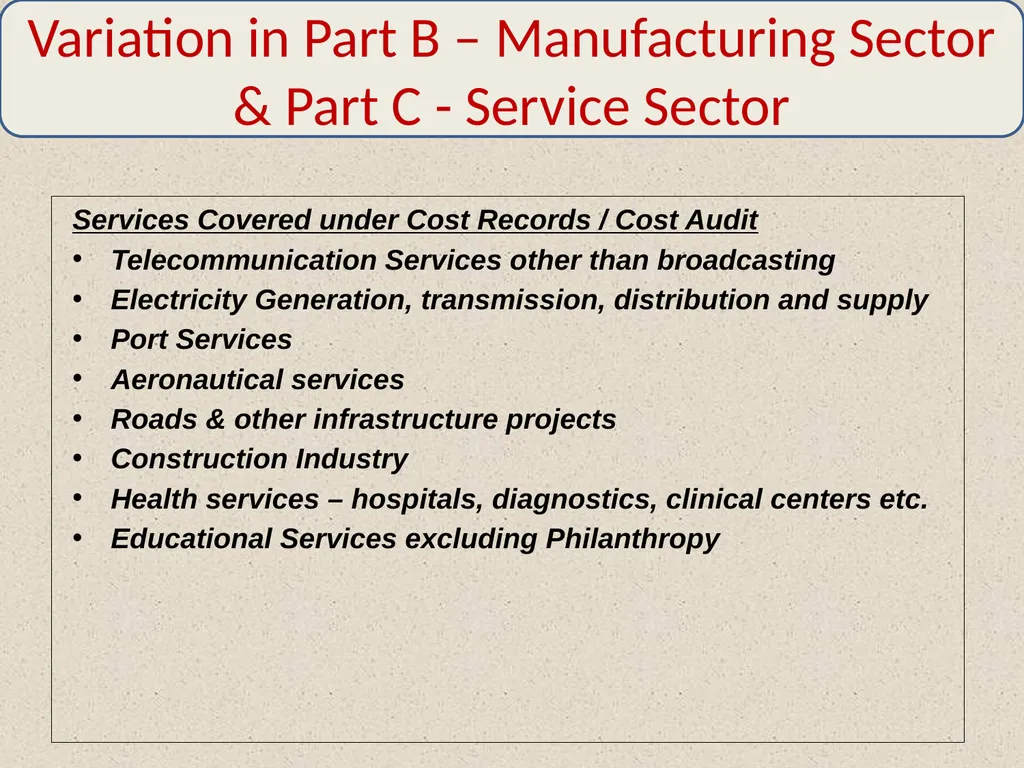
Variation in Part B – Manufacturing Sector & Part C - Service Sector Services Covered under Cost Records / Cost Audit
Telecommunication Services other than broadcasting
Electricity Generation, transmission, distribution and supply
Port Services
Aeronautical services
Roads & other infrastructure projects
Construction Industry
Health services – hospitals, diagnostics, clinical centers etc.
Educational Services excluding Philanthropy<br>
35
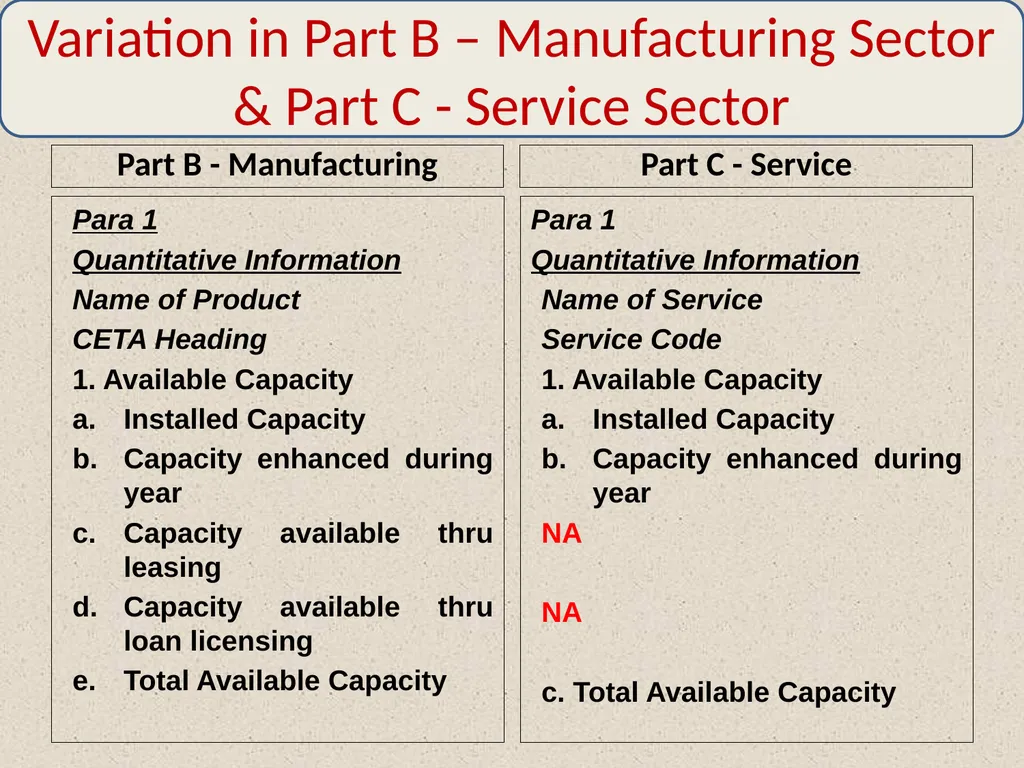
Variation in Part B – Manufacturing Sector & Part C - Service Sector Part B - Manufacturing Para 1
Quantitative Information
Name of Product
CETA Heading
1. Available Capacity
Installed Capacity
Capacity enhanced during year
Capacity available thru leasing
Capacity available thru loan licensing
Total Available Capacity Part C - Service Para 1
Quantitative Information
Name of Service
Service Code
1. Available Capacity
Installed Capacity
Capacity enhanced during year
NA
NA
c. Total Available Capacity<br>
Quantitative Information
Name of Product
CETA Heading
1. Available Capacity
Installed Capacity
Capacity enhanced during year
Capacity available thru leasing
Capacity available thru loan licensing
Total Available Capacity Part C - Service Para 1
Quantitative Information
Name of Service
Service Code
1. Available Capacity
Installed Capacity
Capacity enhanced during year
NA
NA
c. Total Available Capacity<br>
36
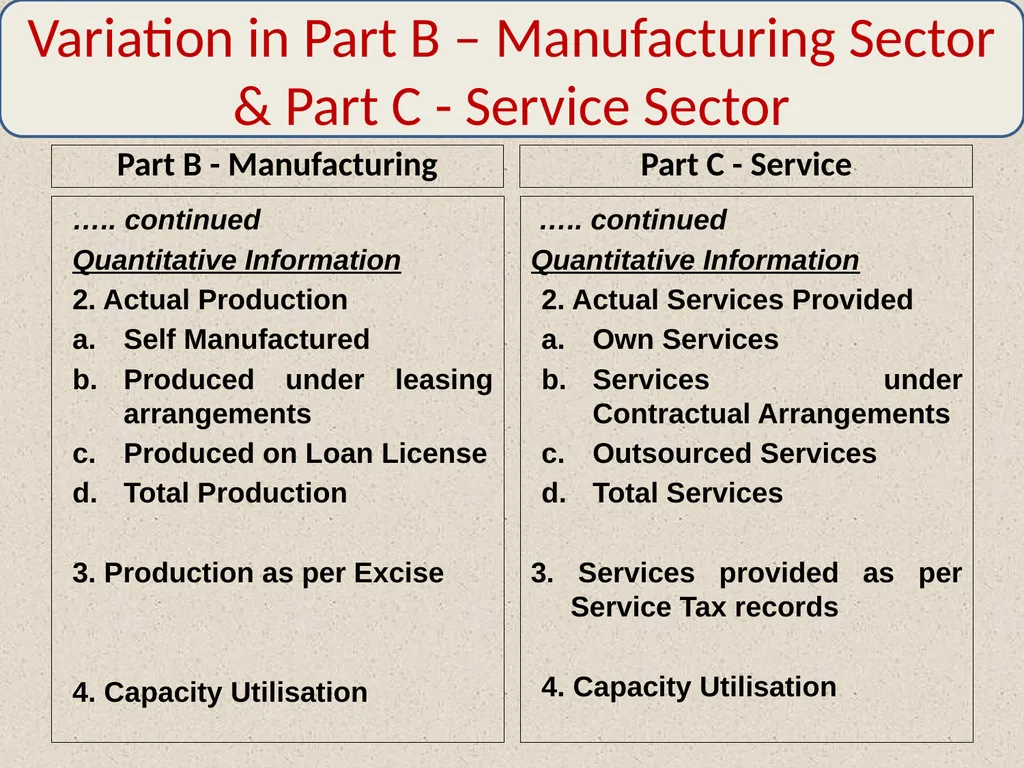
Variation in Part B – Manufacturing Sector & Part C - Service Sector Part B - Manufacturing ….. continued
Quantitative Information
2. Actual Production
Self Manufactured
Produced under leasing arrangements
Produced on Loan License
Total Production
3. Production as per Excise
4. Capacity Utilisation Part C - Service ….. continued
Quantitative Information
2. Actual Services Provided
Own Services
Services under Contractual Arrangements
Outsourced Services
Total Services
3. Services provided as per Service Tax records
4. Capacity Utilisation<br>
Quantitative Information
2. Actual Production
Self Manufactured
Produced under leasing arrangements
Produced on Loan License
Total Production
3. Production as per Excise
4. Capacity Utilisation Part C - Service ….. continued
Quantitative Information
2. Actual Services Provided
Own Services
Services under Contractual Arrangements
Outsourced Services
Total Services
3. Services provided as per Service Tax records
4. Capacity Utilisation<br>
37
Variation in Part B – Manufacturing Sector & Part C - Service Sector Part B - Manufacturing ….. continued
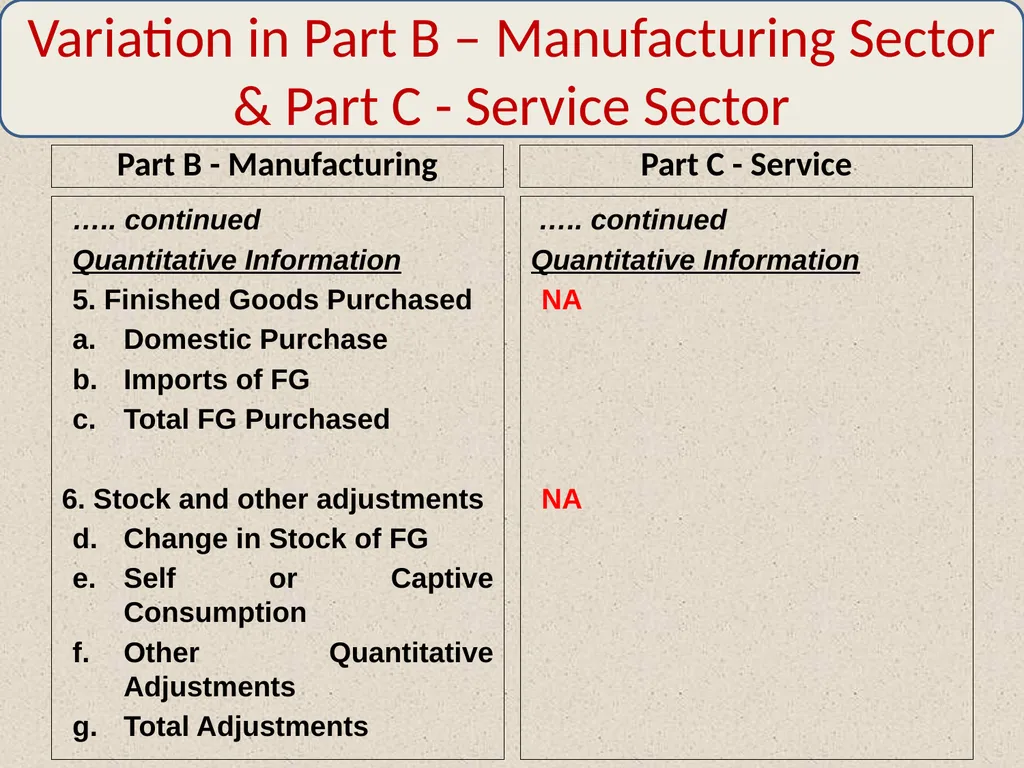
Quantitative Information
5. Finished Goods Purchased
Domestic Purchase
Imports of FG
Total FG Purchased
6. Stock and other adjustments
Change in Stock of FG
Self or Captive Consumption
Other Quantitative Adjustments
Total Adjustments Part C - Service ….. continued
Quantitative Information
NA
NA<br>
Quantitative Information
5. Finished Goods Purchased
Domestic Purchase
Imports of FG
Total FG Purchased
6. Stock and other adjustments
Change in Stock of FG
Self or Captive Consumption
Other Quantitative Adjustments
Total Adjustments Part C - Service ….. continued
Quantitative Information
NA
NA<br>
38
Variation in Part B – Manufacturing Sector & Part C - Service Sector Part B - Manufacturing ….. continued
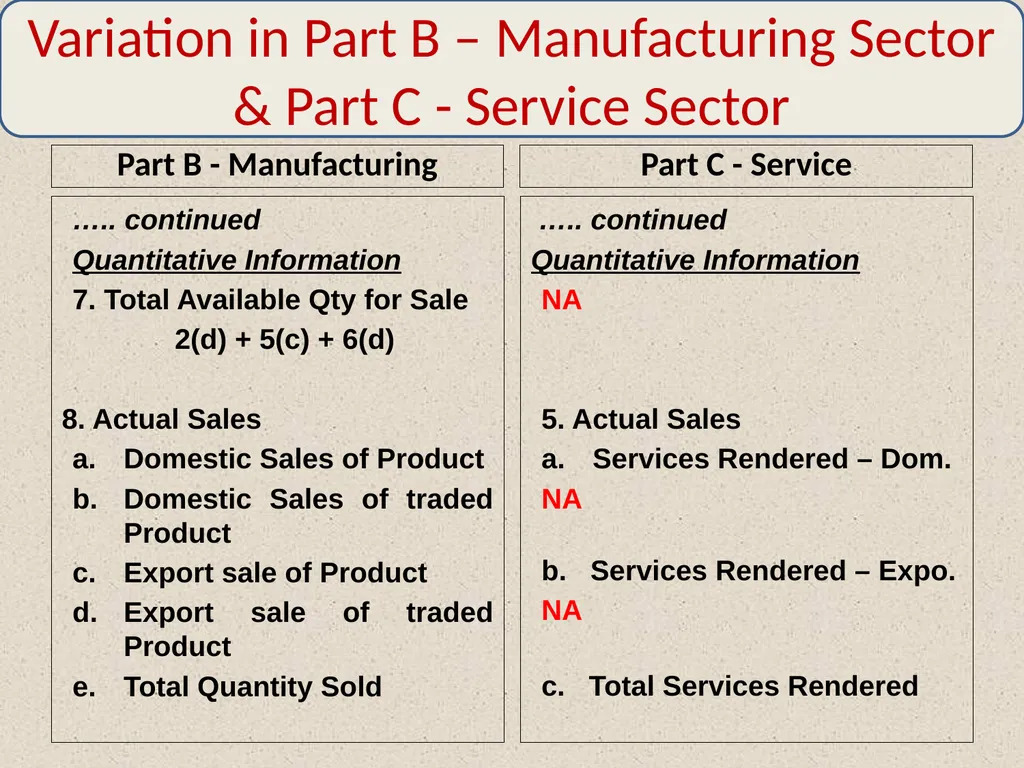
Quantitative Information
7. Total Available Qty for Sale
2(d) + 5(c) + 6(d)
8. Actual Sales
Domestic Sales of Product
Domestic Sales of traded Product
Export sale of Product
Export sale of traded Product
Total Quantity Sold Part C - Service ….. continued
Quantitative Information
NA
5. Actual Sales
Services Rendered – Dom.
NA
b. Services Rendered – Expo.
NA
c. Total Services Rendered<br>
Quantitative Information
7. Total Available Qty for Sale
2(d) + 5(c) + 6(d)
8. Actual Sales
Domestic Sales of Product
Domestic Sales of traded Product
Export sale of Product
Export sale of traded Product
Total Quantity Sold Part C - Service ….. continued
Quantitative Information
NA
5. Actual Sales
Services Rendered – Dom.
NA
b. Services Rendered – Expo.
NA
c. Total Services Rendered<br>
39
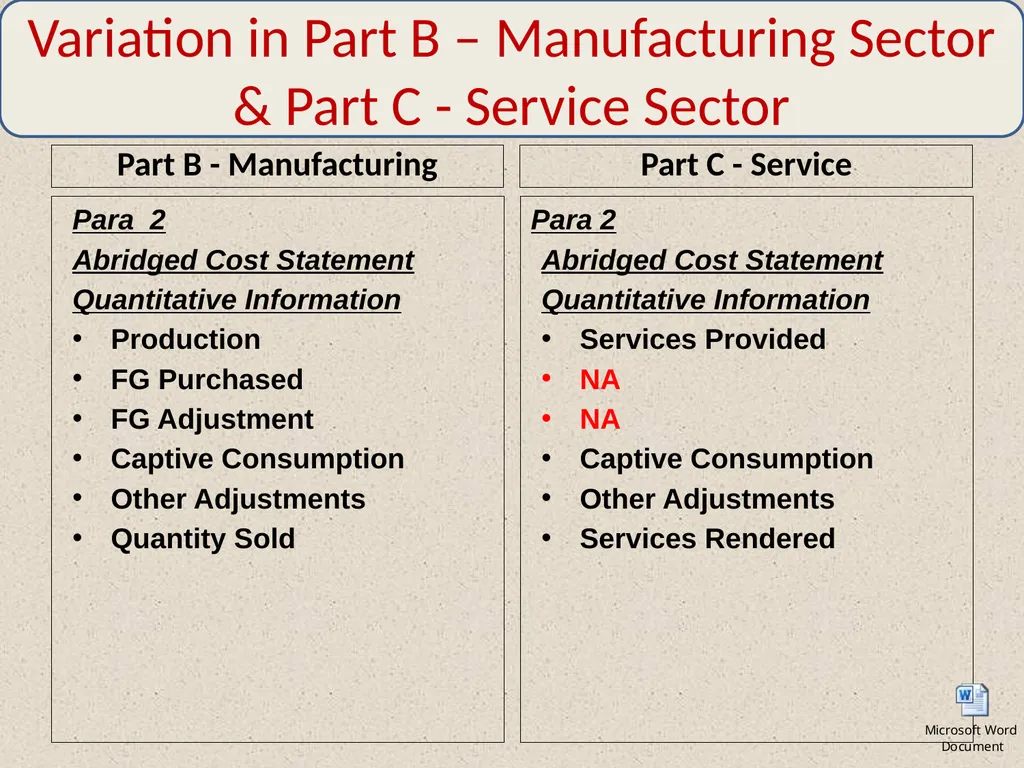
Variation in Part B – Manufacturing Sector & Part C - Service Sector Part B - Manufacturing Para 2
Abridged Cost Statement
Quantitative Information
Production
FG Purchased
FG Adjustment
Captive Consumption
Other Adjustments
Quantity Sold Part C - Service Para 2
Abridged Cost Statement
Quantitative Information
Services Provided
NA
NA
Captive Consumption
Other Adjustments
Services Rendered<br>
Abridged Cost Statement
Quantitative Information
Production
FG Purchased
FG Adjustment
Captive Consumption
Other Adjustments
Quantity Sold Part C - Service Para 2
Abridged Cost Statement
Quantitative Information
Services Provided
NA
NA
Captive Consumption
Other Adjustments
Services Rendered<br>
40
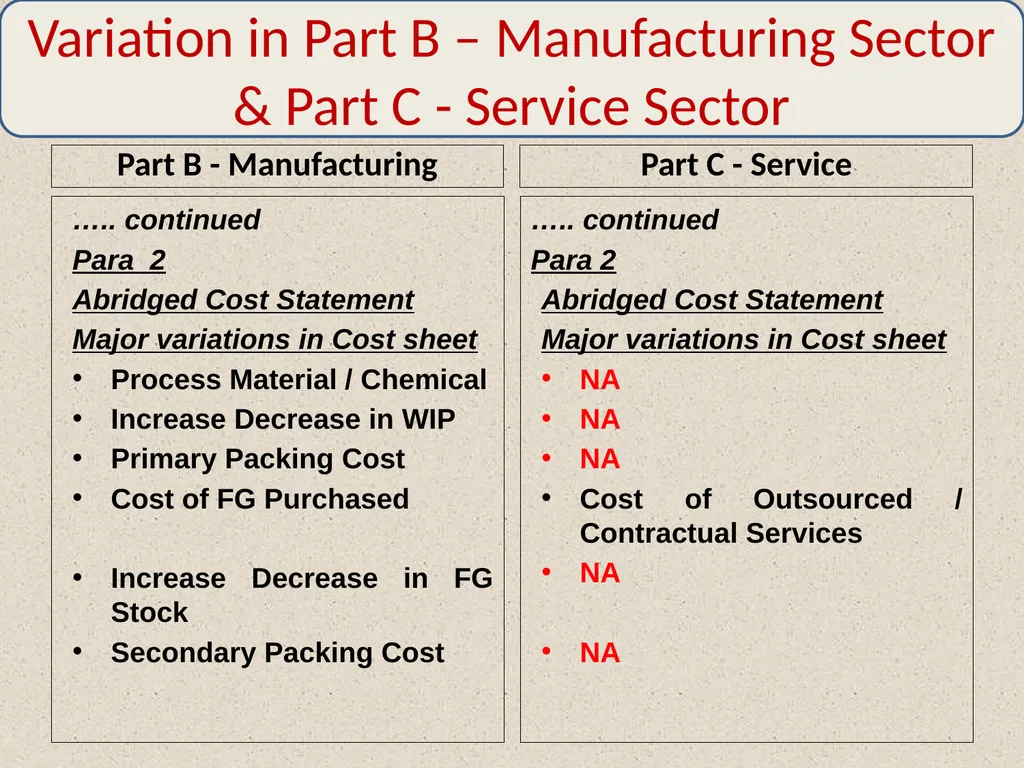
Variation in Part B – Manufacturing Sector & Part C - Service Sector Part B - Manufacturing ….. continued
Para 2
Abridged Cost Statement
Major variations in Cost sheet
Process Material / Chemical
Increase Decrease in WIP
Primary Packing Cost
Cost of FG Purchased
Increase Decrease in FG Stock
Secondary Packing Cost Part C - Service ….. continued
Para 2
Abridged Cost Statement
Major variations in Cost sheet
NA
NA
NA
Cost of Outsourced / Contractual Services
NA
NA<br>
Para 2
Abridged Cost Statement
Major variations in Cost sheet
Process Material / Chemical
Increase Decrease in WIP
Primary Packing Cost
Cost of FG Purchased
Increase Decrease in FG Stock
Secondary Packing Cost Part C - Service ….. continued
Para 2
Abridged Cost Statement
Major variations in Cost sheet
NA
NA
NA
Cost of Outsourced / Contractual Services
NA
NA<br>
41
THANK YOU ! Contact : CMA Harshad Deshpande,
Practicing Cost Accountant
Harshad S Deshpande & Associates
Email : harshadde@gmail.com
: harshadde<br>
Practicing Cost Accountant
Harshad S Deshpande & Associates
Email : harshadde@gmail.com
: harshadde<br>