
ADDRESSING COERCED DEBT IN DIVORCE A discussion of
CM
Published · 93 slides · 0 views

1 / 1
Description
ADDRESSING COERCED DEBT IN DIVORCE A discussion of findings from the first in-depth study of coerced debt in abusive marriages Adrienne Adams, Ph.D. Angela Littwin, J.D. Angie Kennedy, Ph.D. OVERVIEW OVERVIEW Study Purpose Answer
Related Topics
Share
Embed code
Download this presentation From Below
"ADDRESSING COERCED DEBT IN DIVORCE A discussion of" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
ADDRESSING
COERCED DEBT
IN DIVORCE A discussion of findings from the first in-depth study of coerced debt in abusive marriages Adrienne Adams, Ph.D.
Angela Littwin, J.D.
Angie Kennedy, Ph.D.<br>
Angela Littwin, J.D.
Angie Kennedy, Ph.D.<br>
02
OVERVIEW<br>
03
OVERVIEW<br>
04
Study Purpose Answer fundamental questions about how coerced debt operates in abusive relationships, how victims seek and attain legal help for coerced debt, and coerced debt's effects on women's recovery from an abusive relationship<br>
05
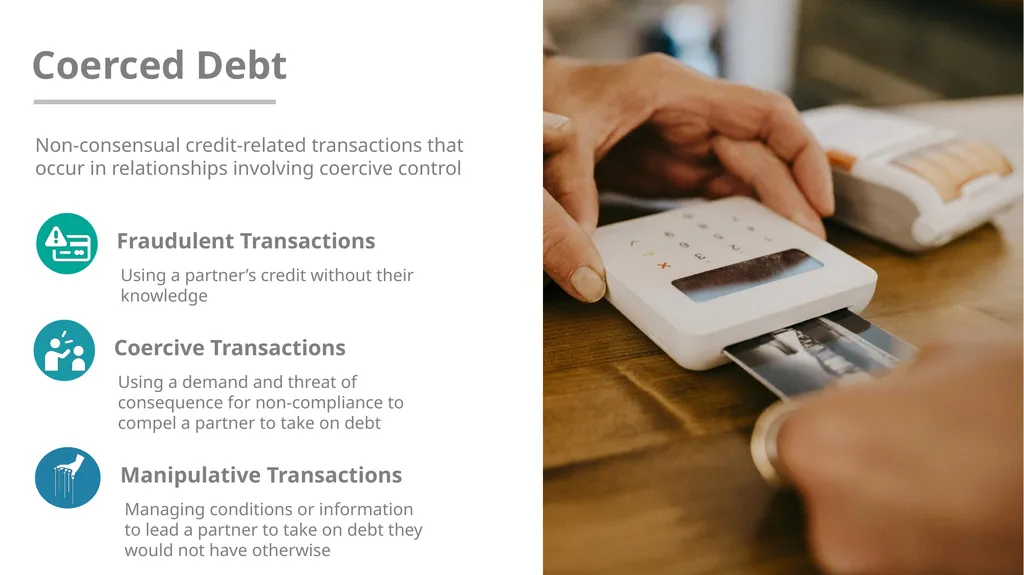
Coerced Debt Non-consensual credit-related transactions that occur in relationships involving coercive control<br>
06
Participant Recruitment Obtained list from public divorce records
Sent invitation letter
Followed up with non-respondents
Screened for eligibility<br>
Sent invitation letter
Followed up with non-respondents
Screened for eligibility<br>
07
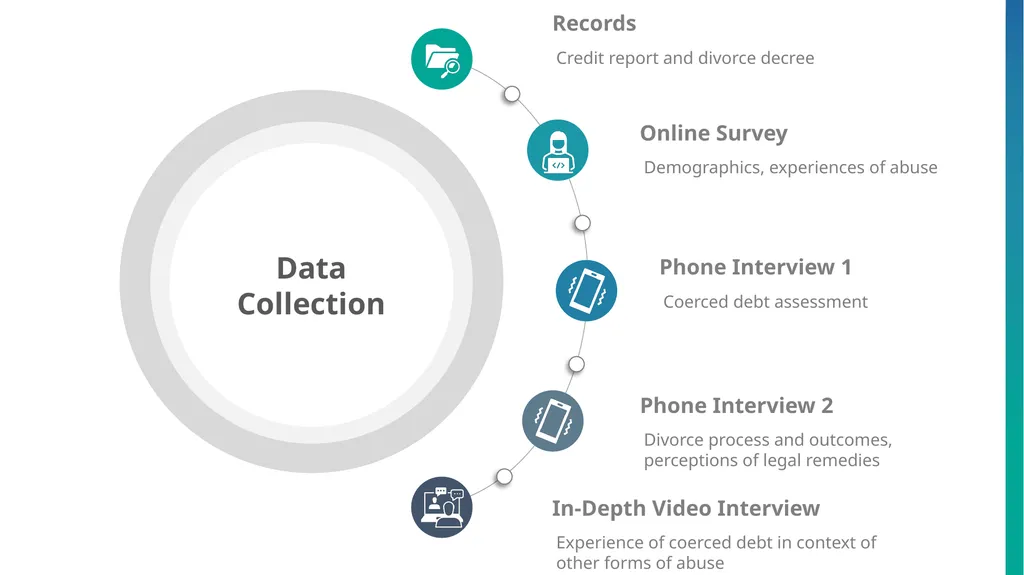
Data Collection<br>
08
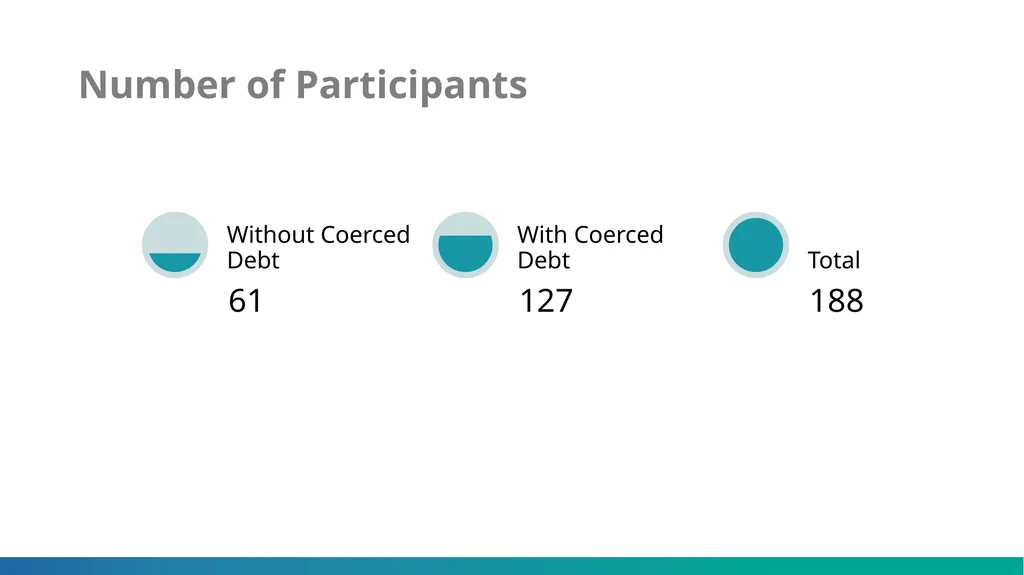
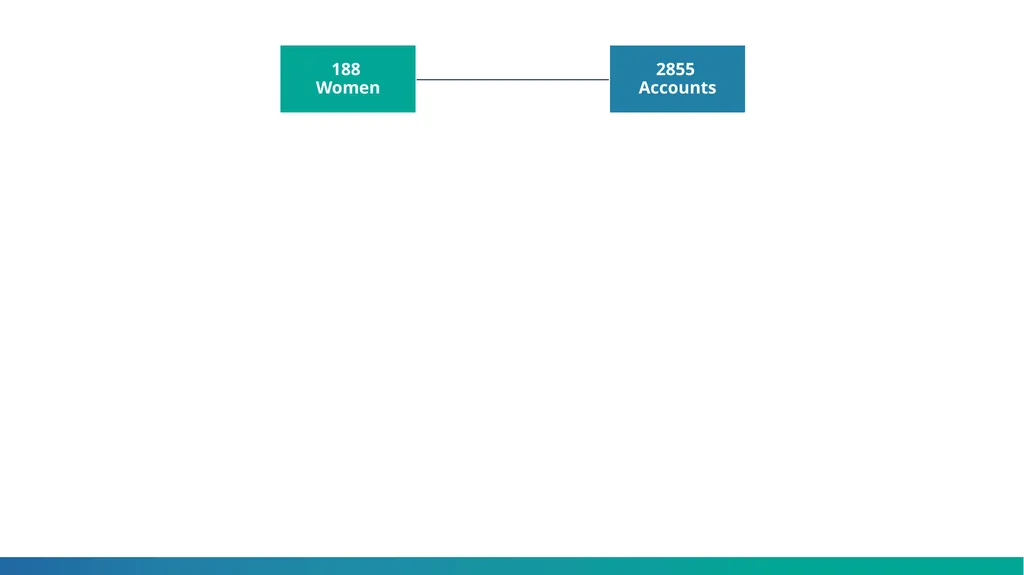
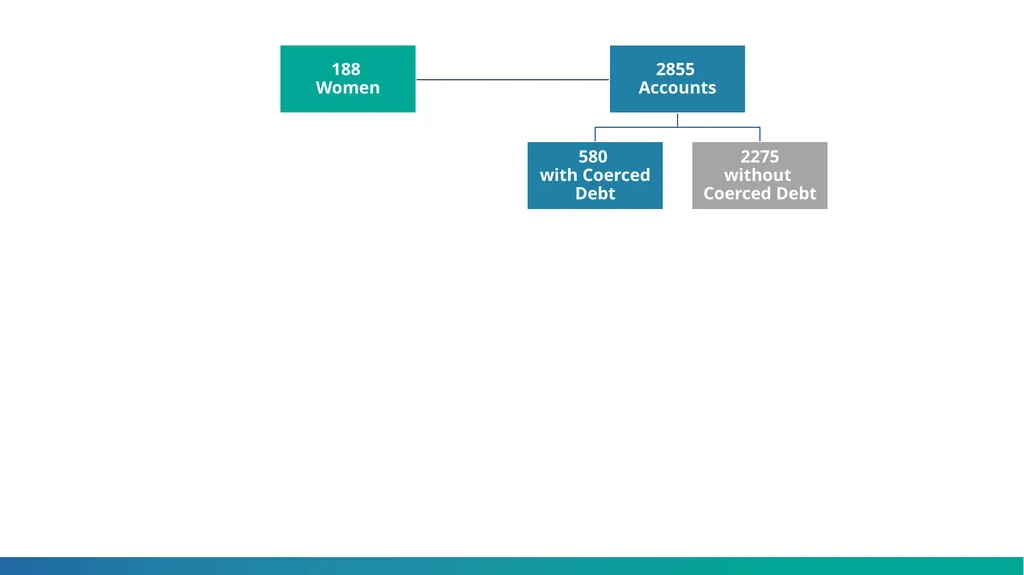
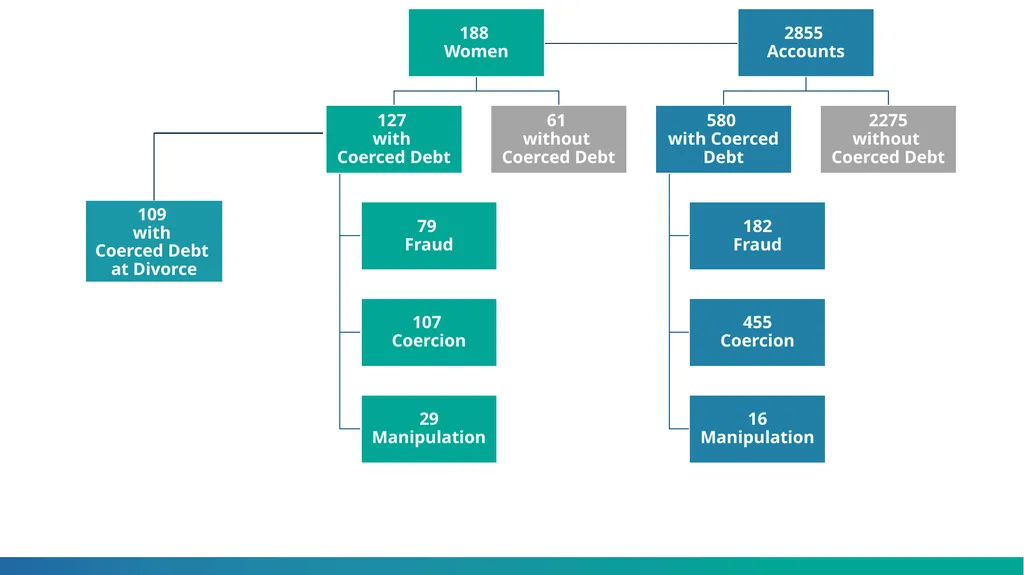
Number of Participants<br>
09
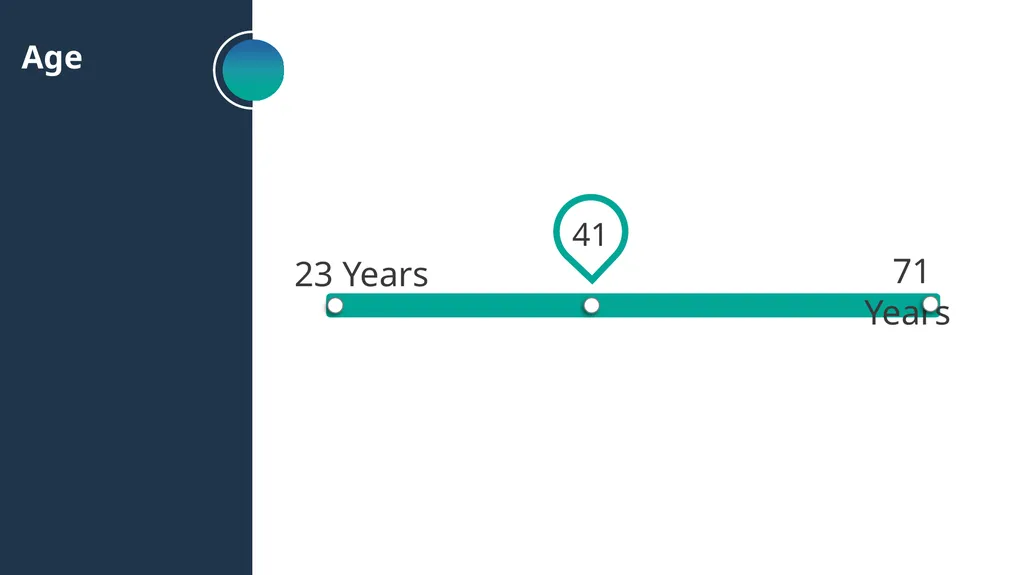
Age 23 Years 71 Years<br>
10
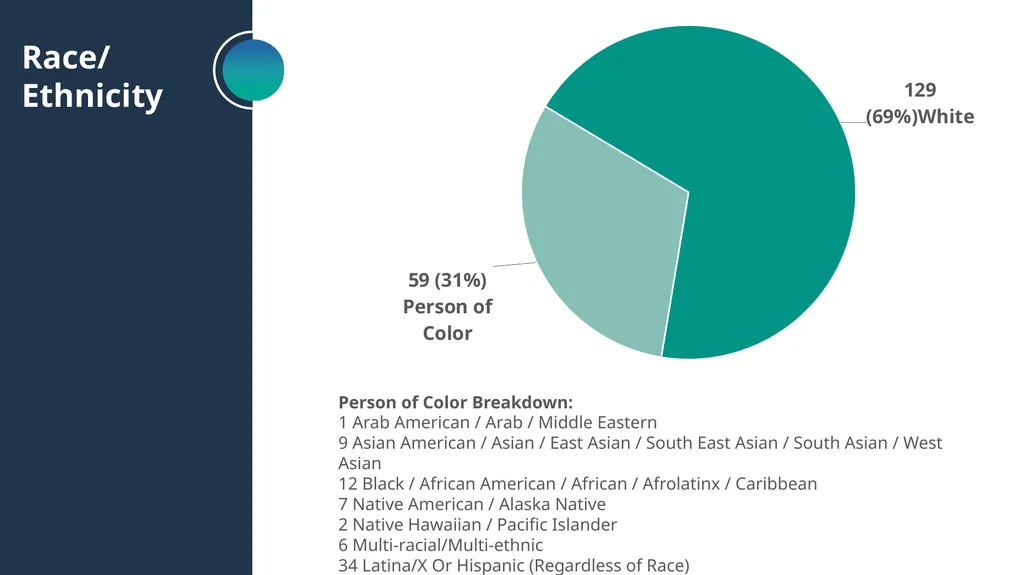
Race/
Ethnicity Person of Color Breakdown:
1 Arab American / Arab / Middle Eastern
9 Asian American / Asian / East Asian / South East Asian / South Asian / West Asian
12 Black / African American / African / Afrolatinx / Caribbean
7 Native American / Alaska Native
2 Native Hawaiian / Pacific Islander
6 Multi-racial/Multi-ethnic
34 Latina/X Or Hispanic (Regardless of Race)<br>
1 Arab American / Arab / Middle Eastern
9 Asian American / Asian / East Asian / South East Asian / South Asian / West Asian
12 Black / African American / African / Afrolatinx / Caribbean
7 Native American / Alaska Native
2 Native Hawaiian / Pacific Islander
6 Multi-racial/Multi-ethnic
34 Latina/X Or Hispanic (Regardless of Race)<br>
11
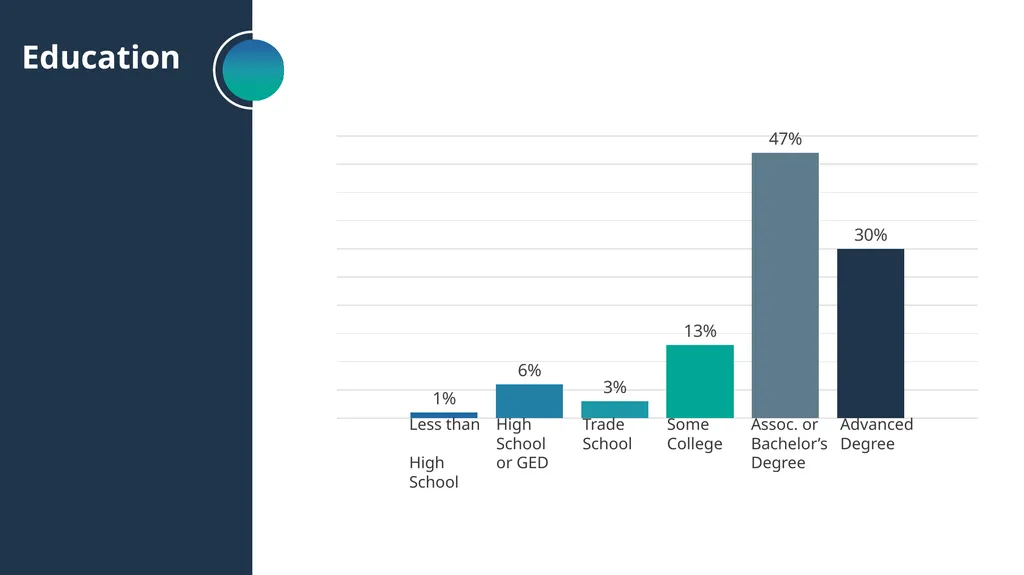
Education Less than
High School High School
or GED Trade School Some
College Assoc. or Bachelor’s
Degree Advanced
Degree<br>
12
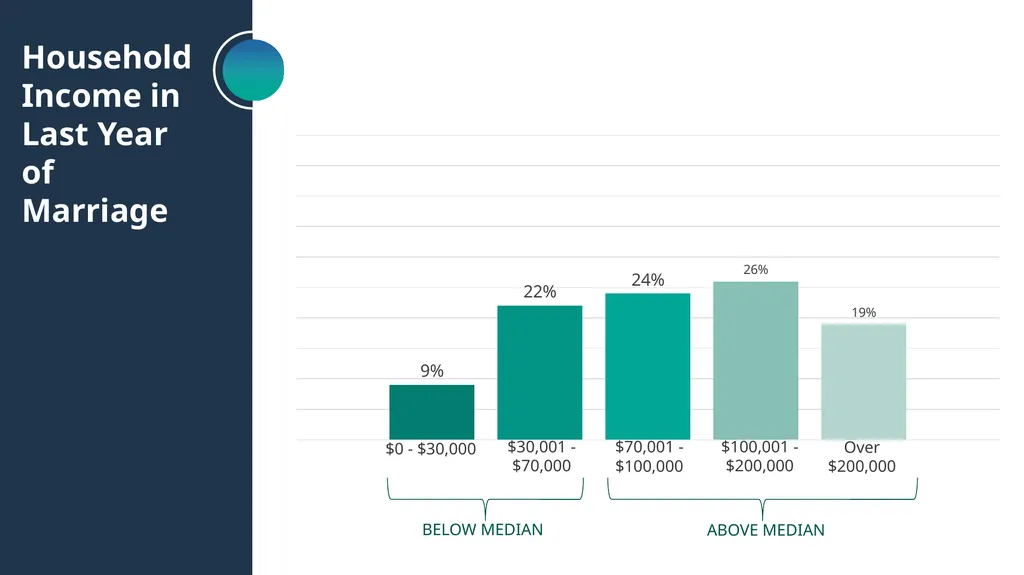
Household Income in Last Year of Marriage $0 - $30,000 $30,001 - $70,000 $70,001 - $100,000 BELOW MEDIAN ABOVE MEDIAN $100,001 - $200,000 Over $200,000<br>
13
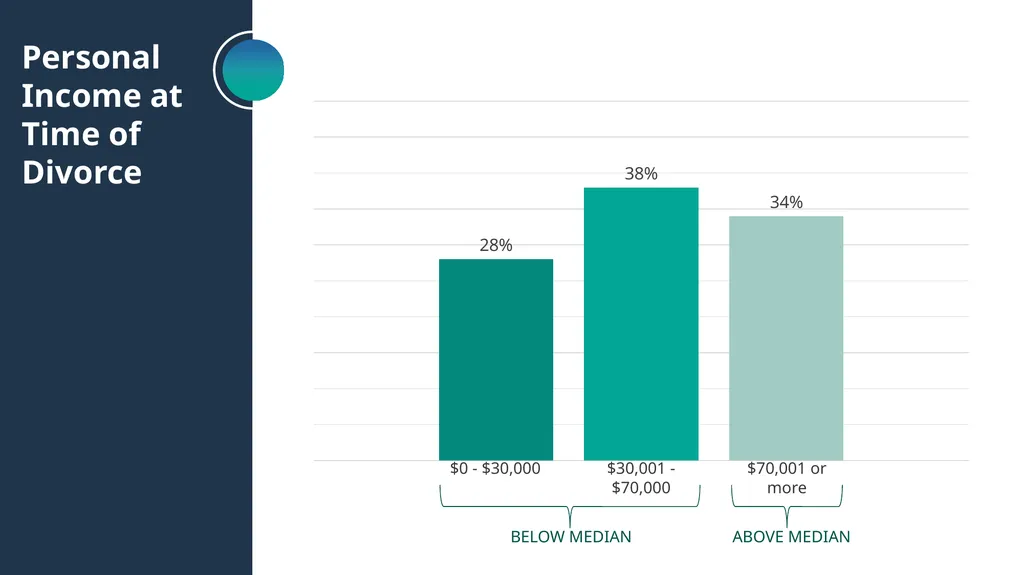
Personal Income at Time of Divorce $0 - $30,000 $30,001 - $70,000 $70,001 or more BELOW MEDIAN ABOVE MEDIAN<br>
14
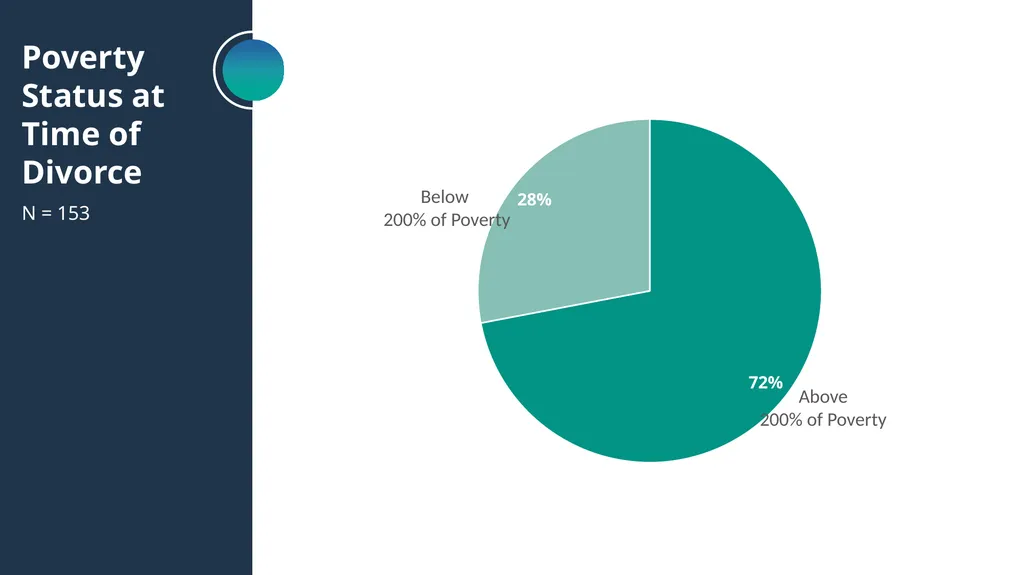
Poverty Status at Time of Divorce Above
200% of Poverty Below
200% of Poverty N = 153<br>
15
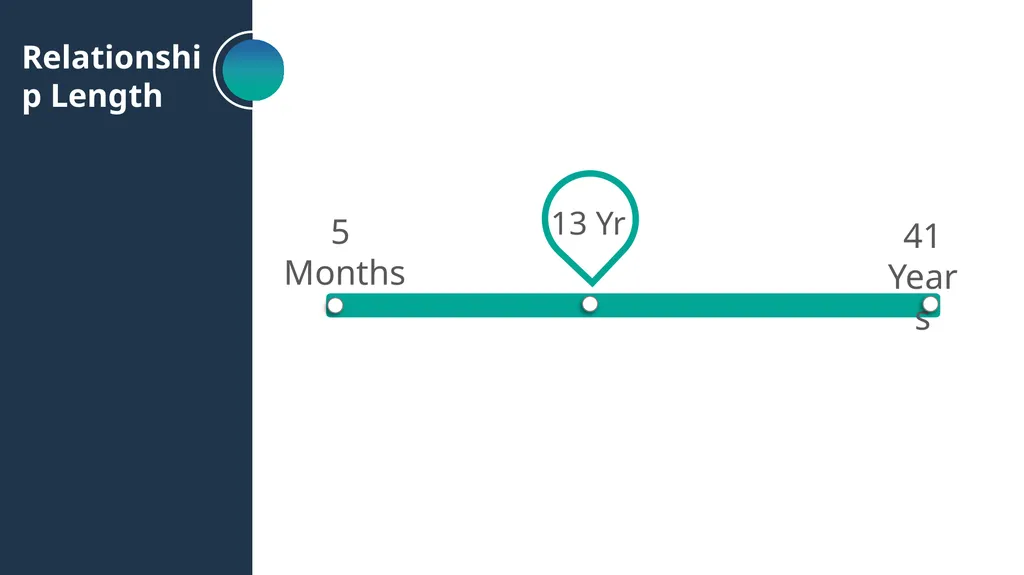
Relationship Length 5
Months 41
Years<br>
16
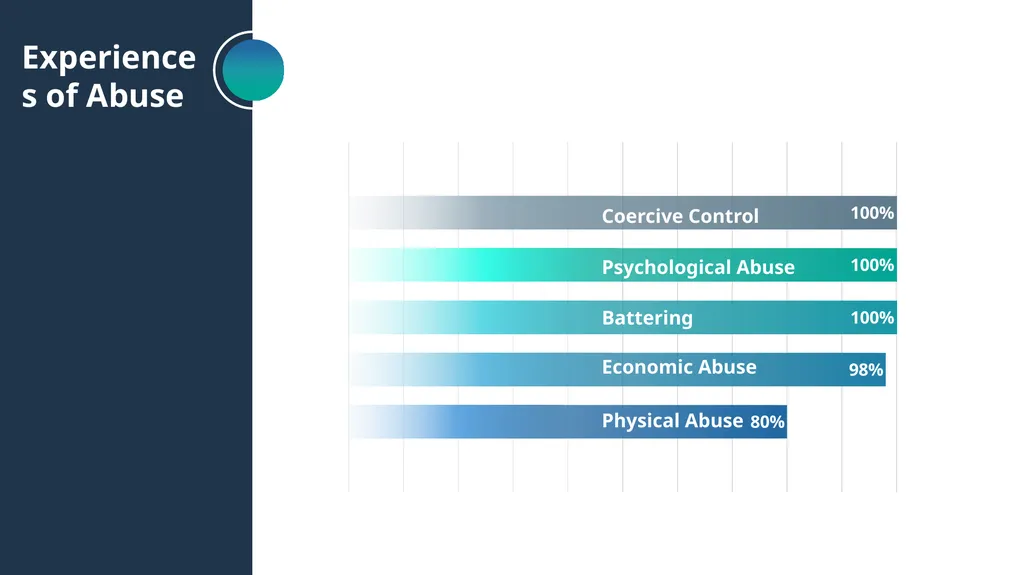
Experiences of Abuse Psychological Abuse Battering Economic Abuse Physical Abuse Coercive Control<br>
17
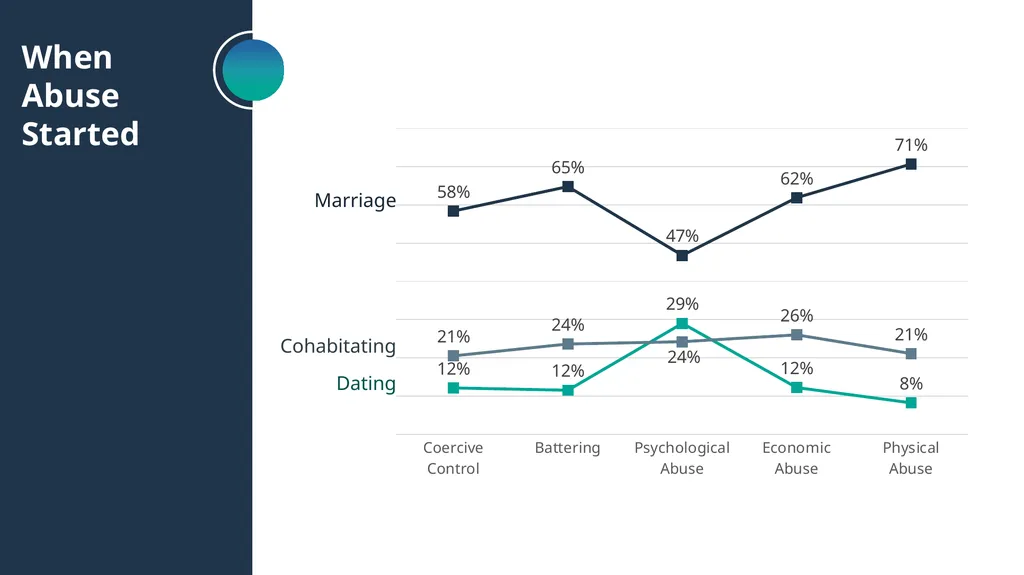
When Abuse Started Psychological Abuse Battering Economic Physical Marriage Cohabitating Dating<br>
18
OVERVIEW<br>
19
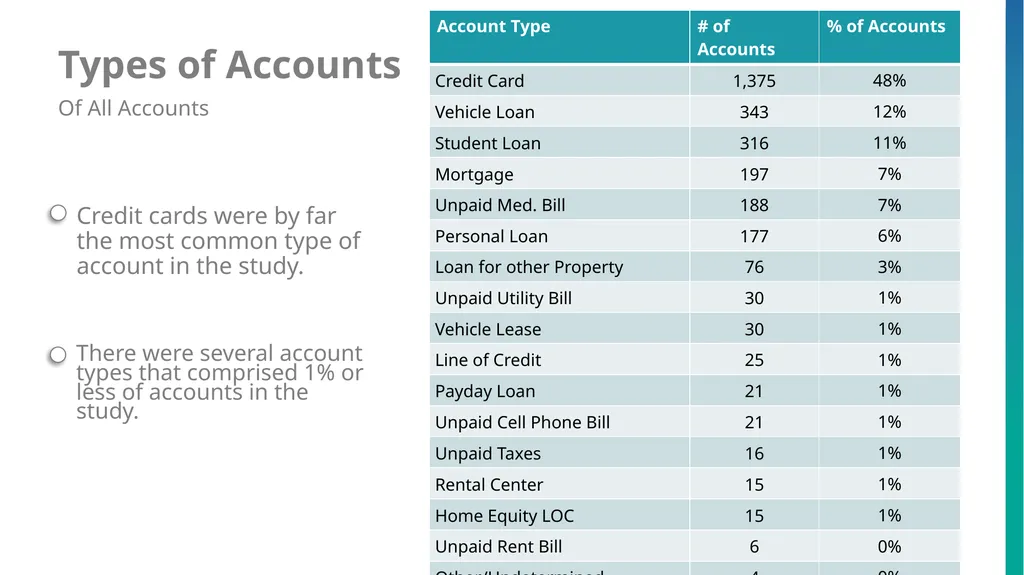
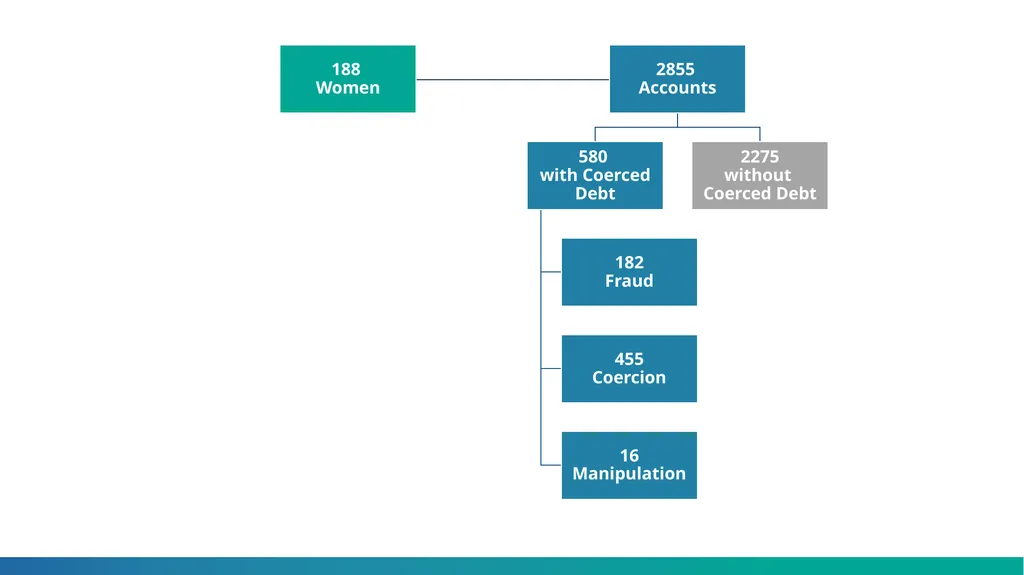
Types of Accounts Of All Accounts<br>
20
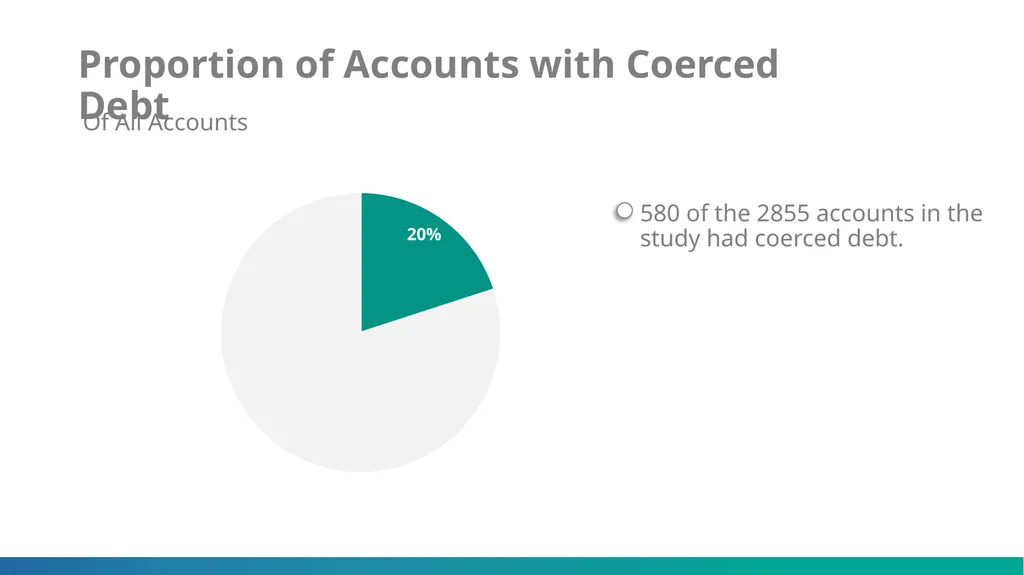
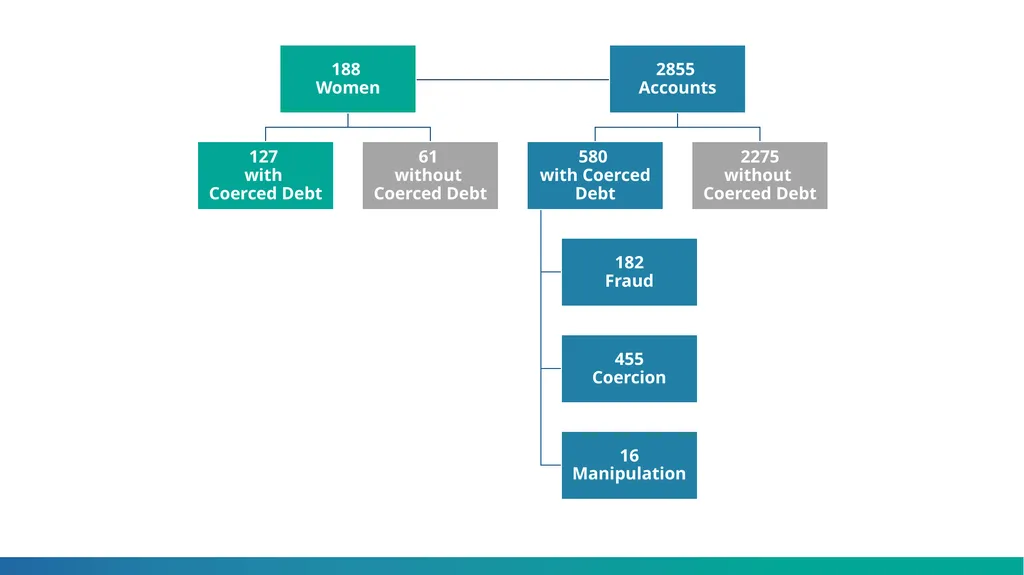
Proportion of Accounts with Coerced Debt Of All Accounts<br>
21
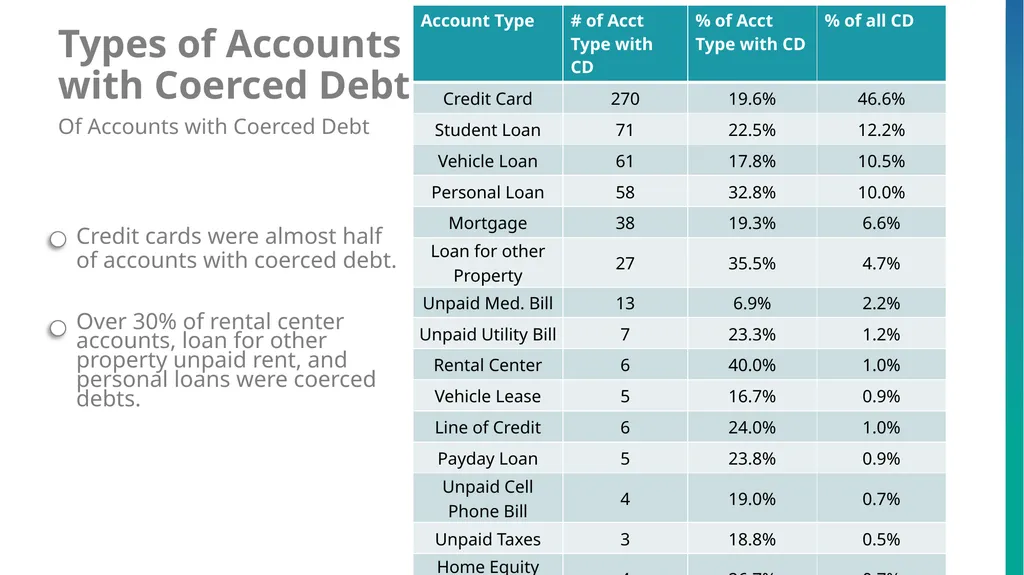
Types of Accounts
with Coerced Debt Of Accounts with Coerced Debt<br>
22
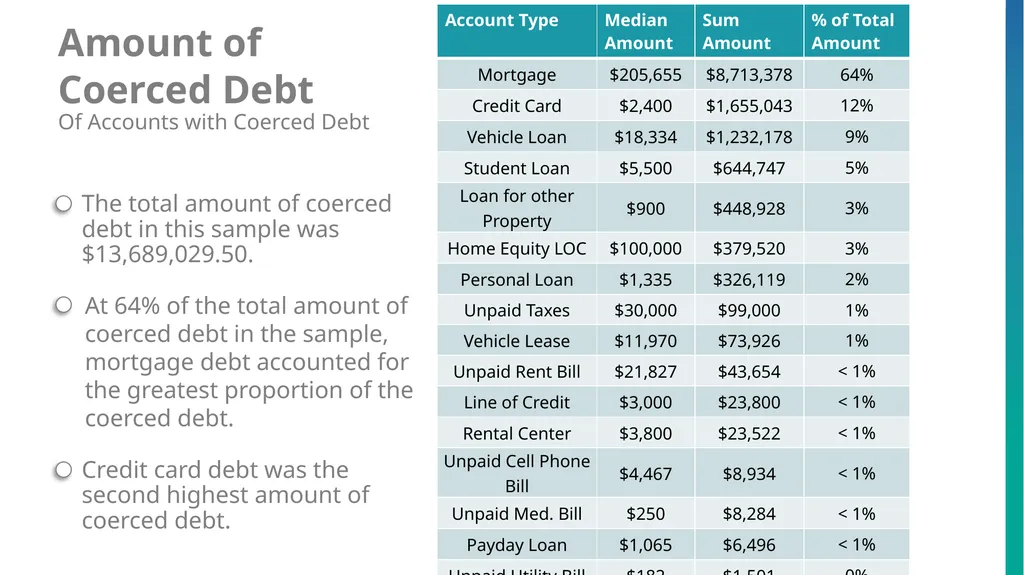
Amount of
Coerced Debt Of Accounts with Coerced Debt<br>
Coerced Debt Of Accounts with Coerced Debt<br>
23
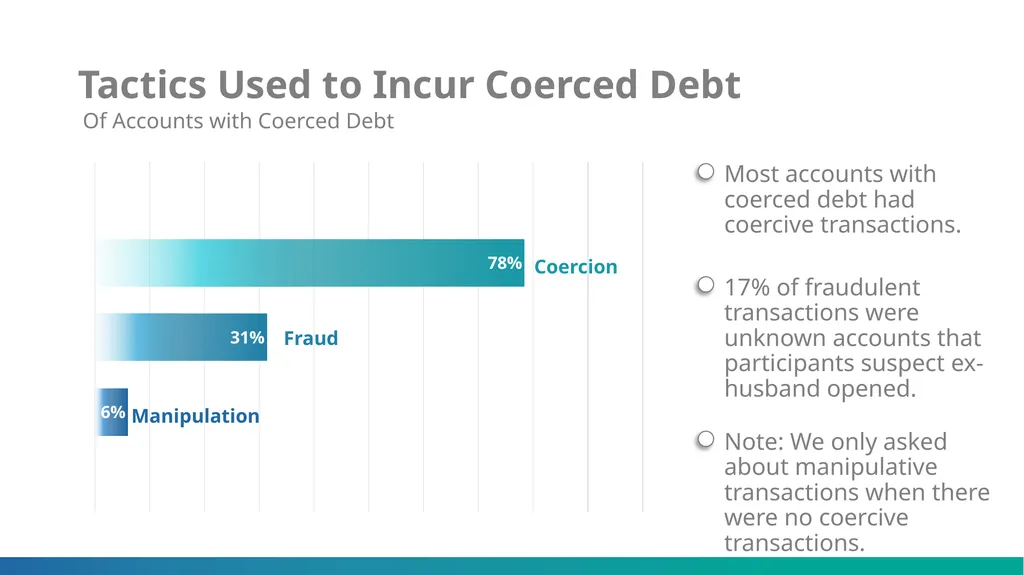
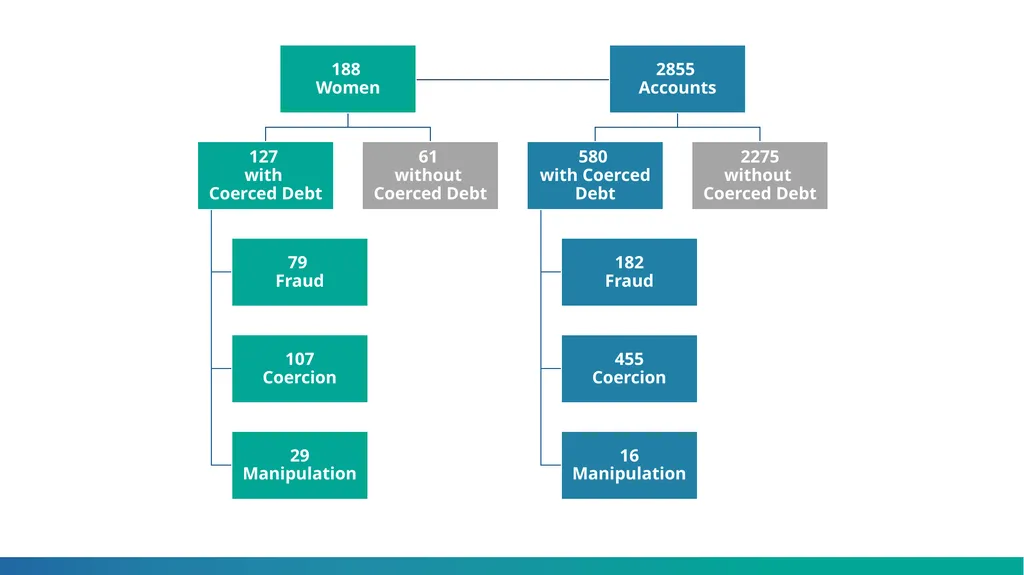
Tactics Used to Incur Coerced Debt Coercion Fraud Manipulation Of Accounts with Coerced Debt<br>
24
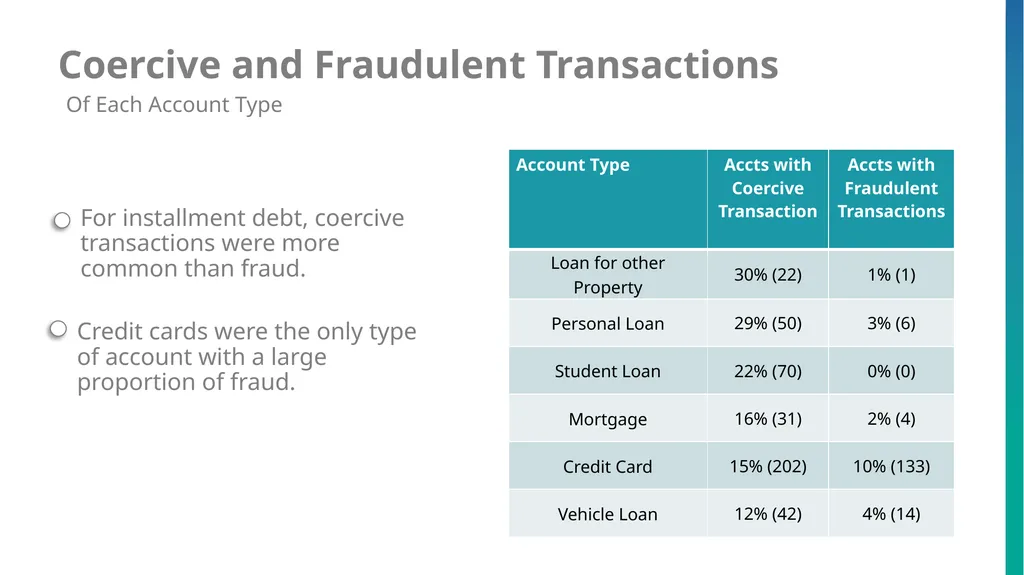
Coercive and Fraudulent Transactions Of Each Account Type<br>
25
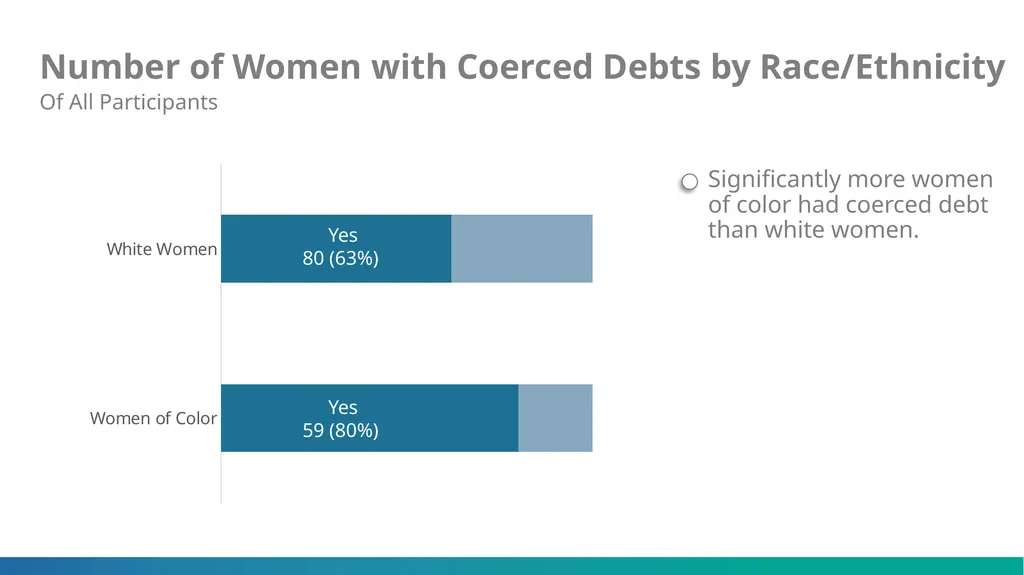
Number of Women with Coerced Debts by Race/Ethnicity Yes
80 (63%) Yes
59 (80%) Of All Participants<br>
26
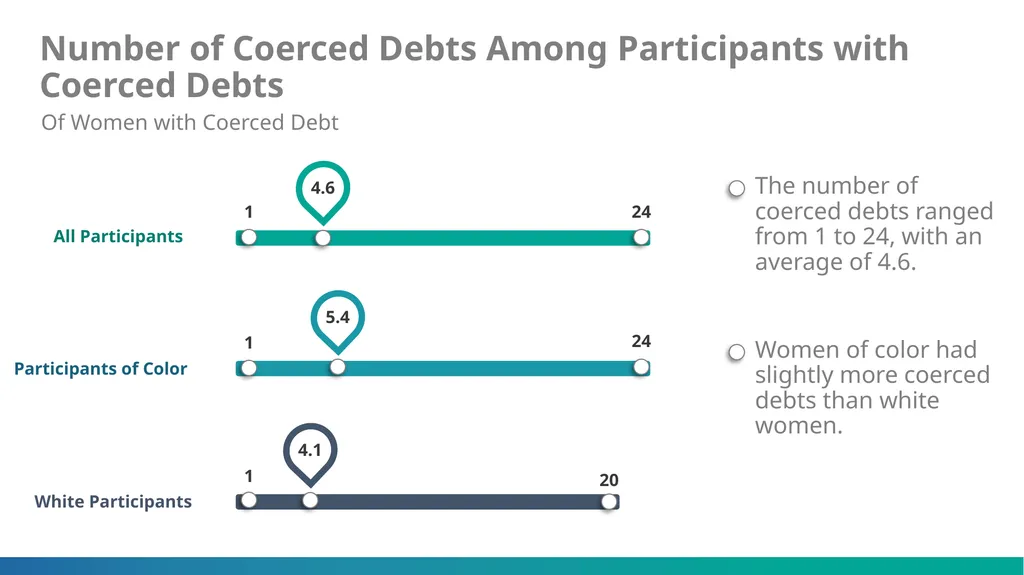
1 24 1 24 1 20 All Participants Participants of Color White Participants Number of Coerced Debts Among Participants with
Coerced Debts Of Women with Coerced Debt<br>
27
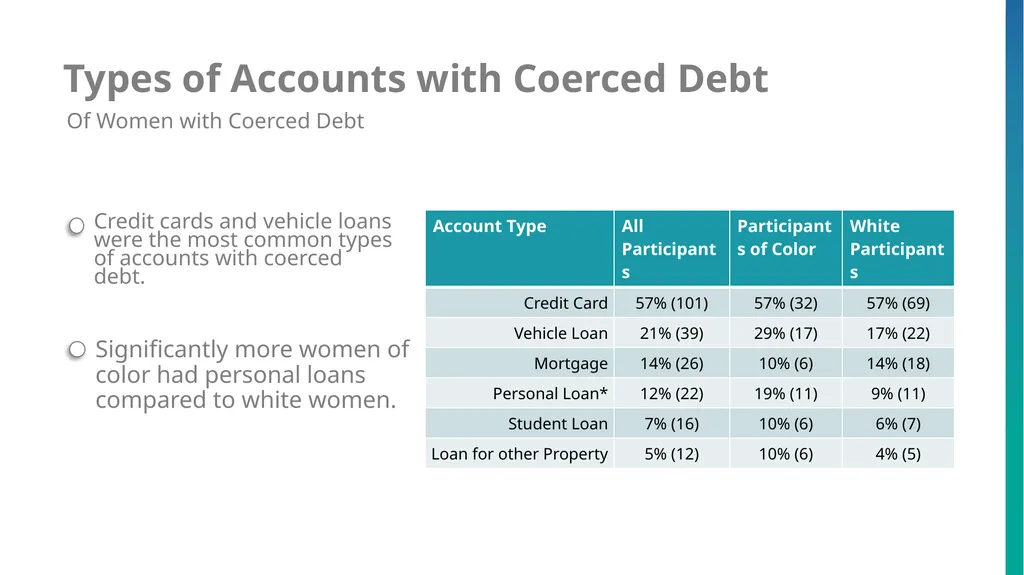
Types of Accounts with Coerced Debt Of Women with Coerced Debt<br>
28
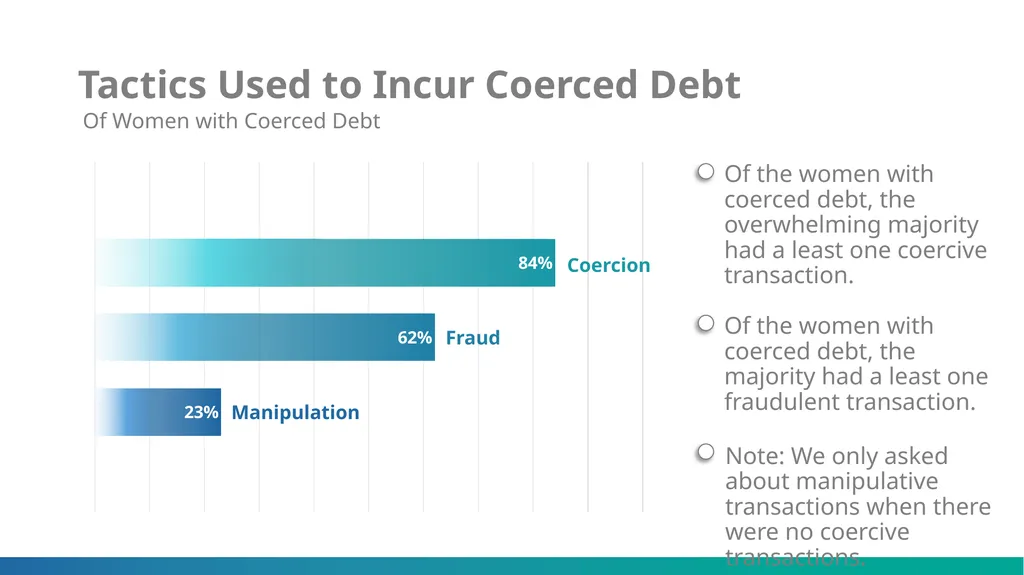
Tactics Used to Incur Coerced Debt Coercion Fraud Manipulation Of Women with Coerced Debt<br>
29
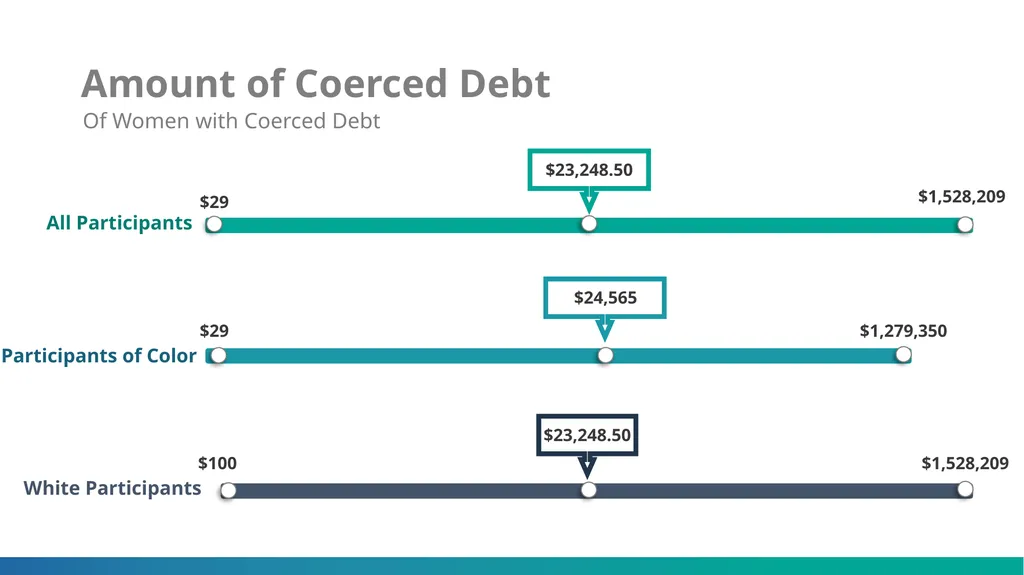
Amount of Coerced Debt $29 $1,528,209 $23,248.50 $29 $1,279,350 $24,565 $100 $23,248.50 All Participants Participants of Color White Participants Of Women with Coerced Debt $1,528,209<br>
30
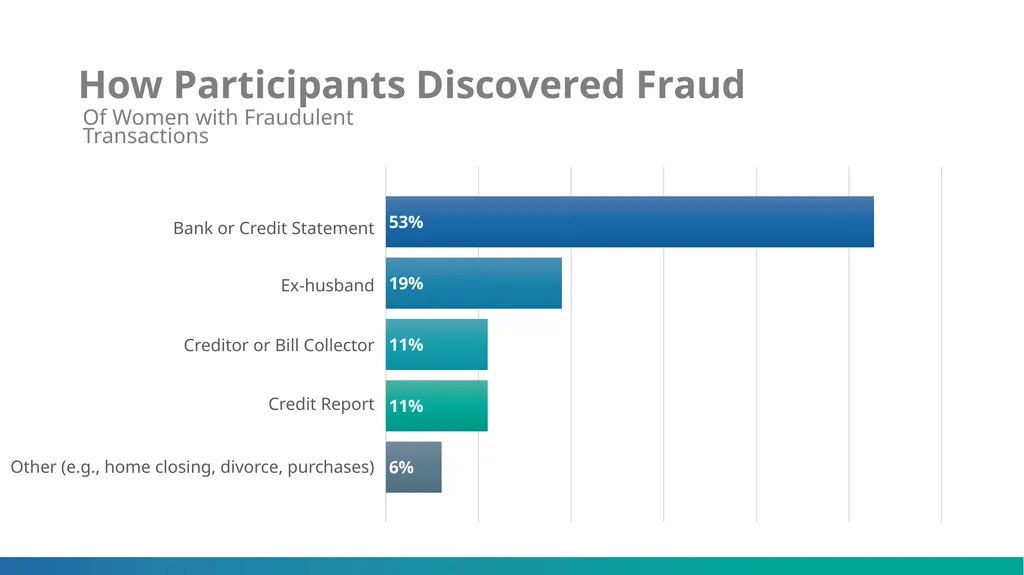
How Participants Discovered Fraud Bank or Credit Statement Ex-husband Creditor or Bill Collector Credit Report Other (e.g., home closing, divorce, purchases) Of Women with Fraudulent Transactions<br>
31
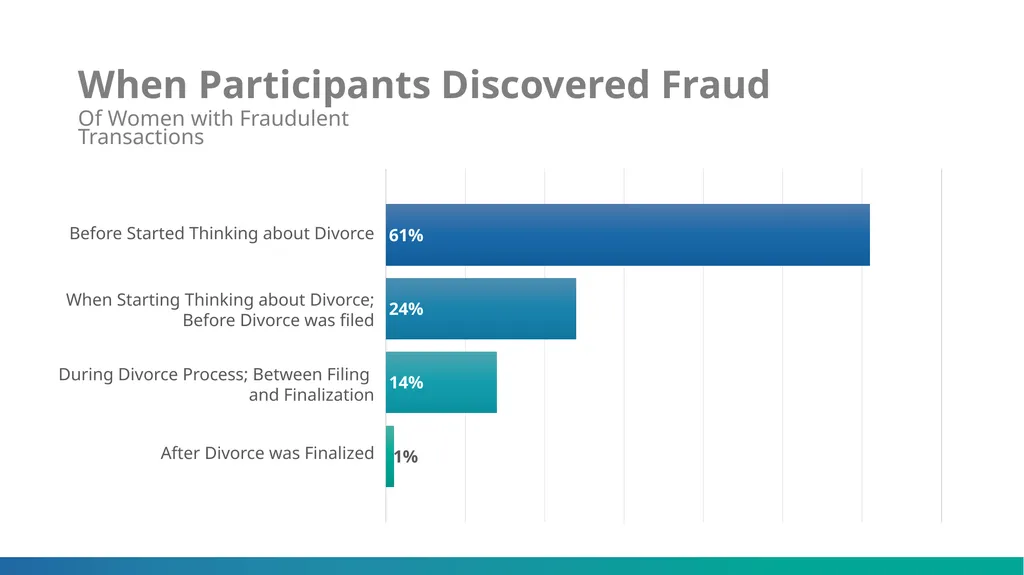
When Participants Discovered Fraud Before Started Thinking about Divorce During Divorce Process; Between Filing
and Finalization After Divorce was Finalized When Starting Thinking about Divorce; Before Divorce was filed Of Women with Fraudulent Transactions<br>
32
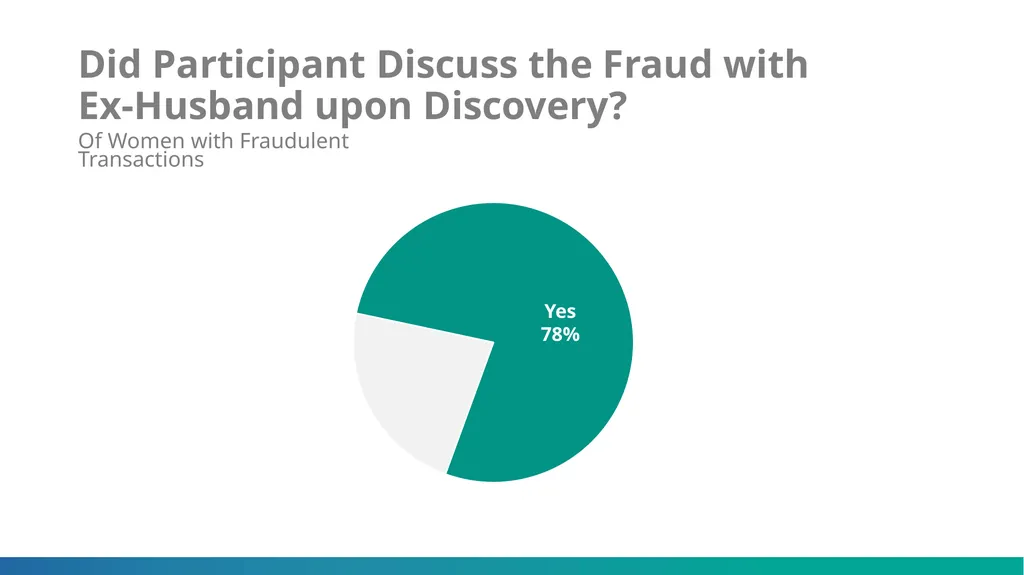
Did Participant Discuss the Fraud with Ex-Husband upon Discovery? Yes
78% Of Women with Fraudulent Transactions<br>
33
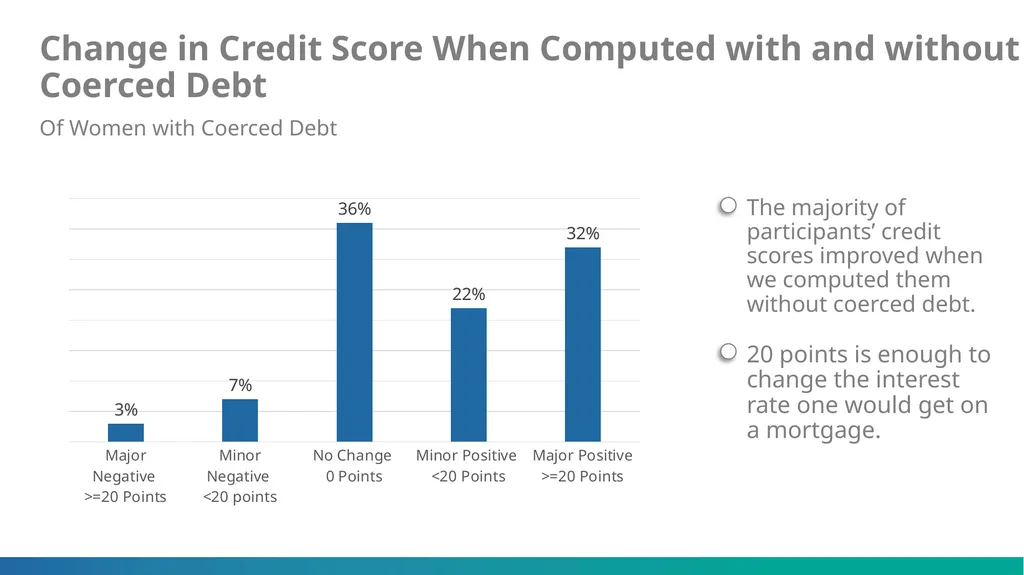
Change in Credit Score When Computed with and without Coerced Debt Of Women with Coerced Debt<br>
34
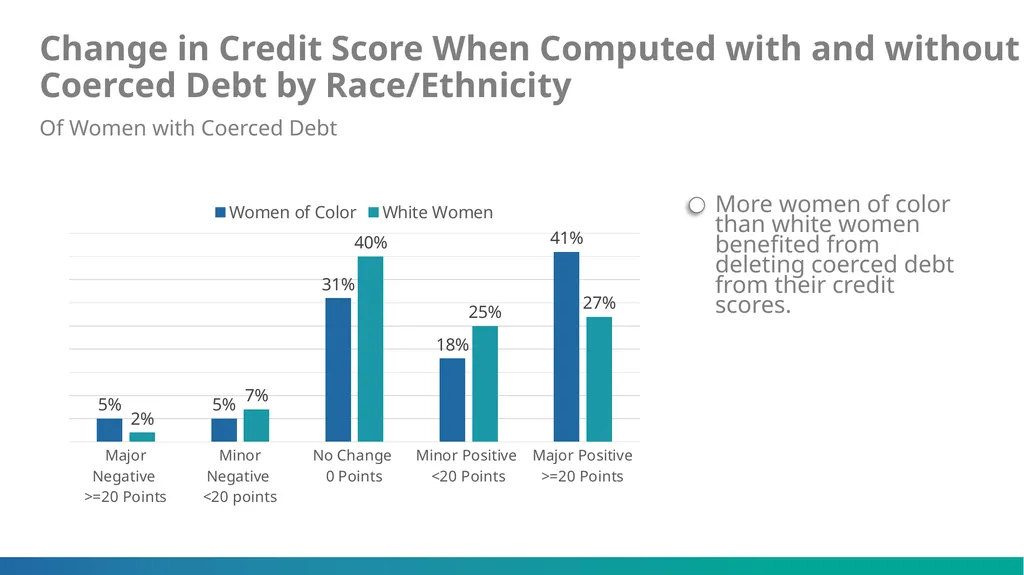
Change in Credit Score When Computed with and without Coerced Debt by Race/Ethnicity Of Women with Coerced Debt<br>
35
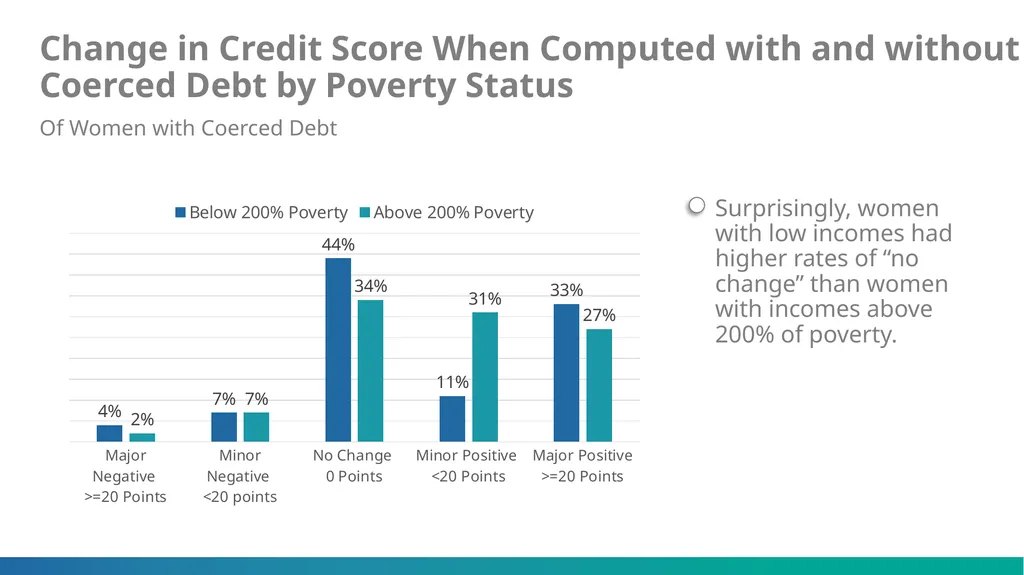
Change in Credit Score When Computed with and without Coerced Debt by Poverty Status Of Women with Coerced Debt<br>
36
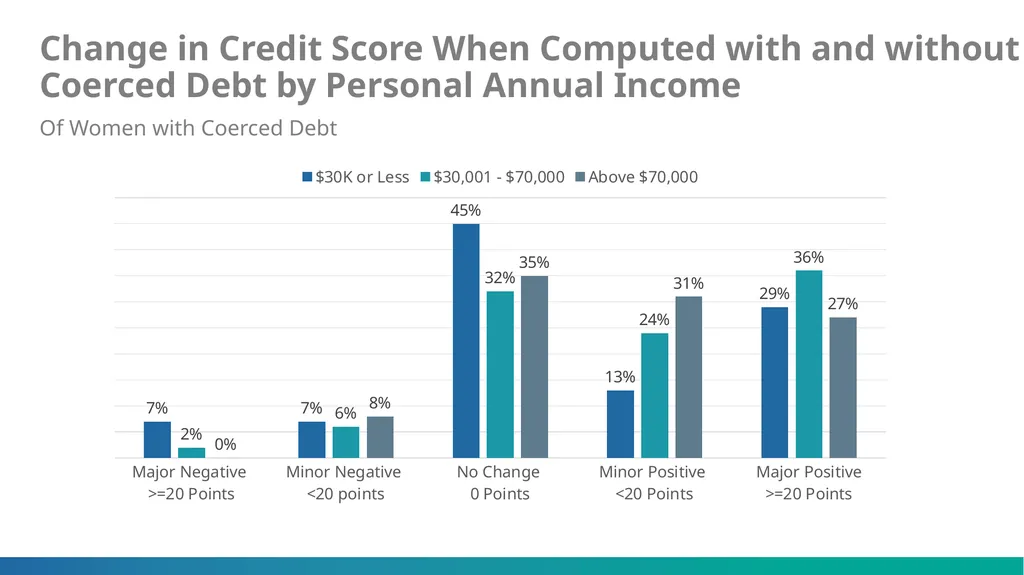
Change in Credit Score When Computed with and without Coerced Debt by Personal Annual Income Of Women with Coerced Debt<br>
37
Discussion<br>
38
OVERVIEW<br>
39
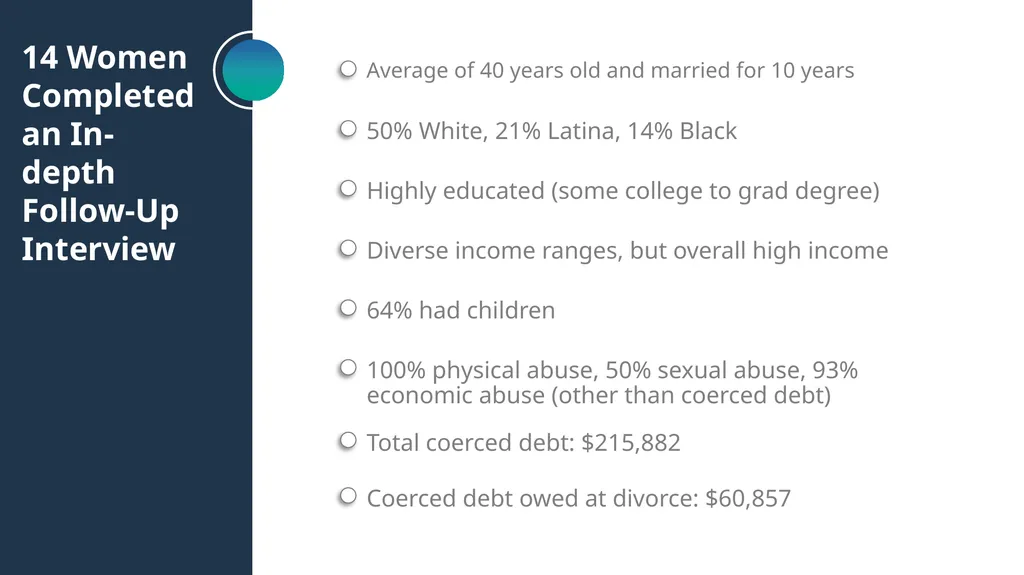
14 Women Completed an In-depth Follow-Up Interview<br>
40
Coercive Control Behaviors and Tactics Controlling, monitoring & surveilling, belittling & humiliating, behaving erratically, instilling fear, gaslighting, isolating, punishing, sabotaging, threatening, making unrelenting demands, including double binds<br>
41
Coerced Debt via
Manipulation, Coercion & Fraud<br>
42
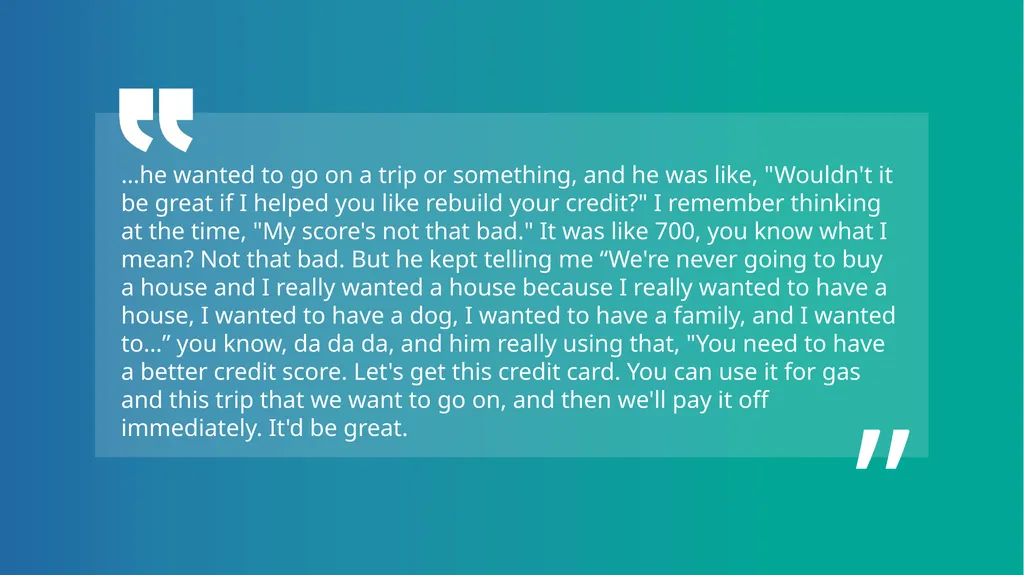
“ …he wanted to go on a trip or something, and he was like, "Wouldn't it be great if I helped you like rebuild your credit?" I remember thinking at the time, "My score's not that bad." It was like 700, you know what I mean? Not that bad. But he kept telling me “We're never going to buy a house and I really wanted a house because I really wanted to have a house, I wanted to have a dog, I wanted to have a family, and I wanted to…” you know, da da da, and him really using that, "You need to have a better credit score. Let's get this credit card. You can use it for gas and this trip that we want to go on, and then we'll pay it off immediately. It'd be great.<br>
43
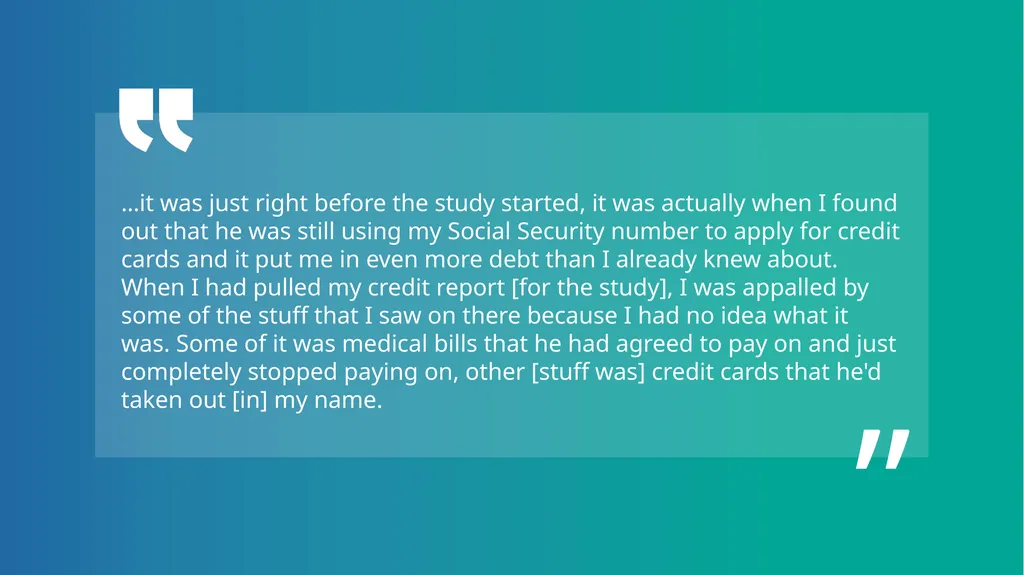
“ …it was just right before the study started, it was actually when I found out that he was still using my Social Security number to apply for credit cards and it put me in even more debt than I already knew about. When I had pulled my credit report [for the study], I was appalled by some of the stuff that I saw on there because I had no idea what it was. Some of it was medical bills that he had agreed to pay on and just completely stopped paying on, other [stuff was] credit cards that he'd taken out [in] my name.<br>
44
Coerced Debt as an Extension of Coercive Control<br>
45
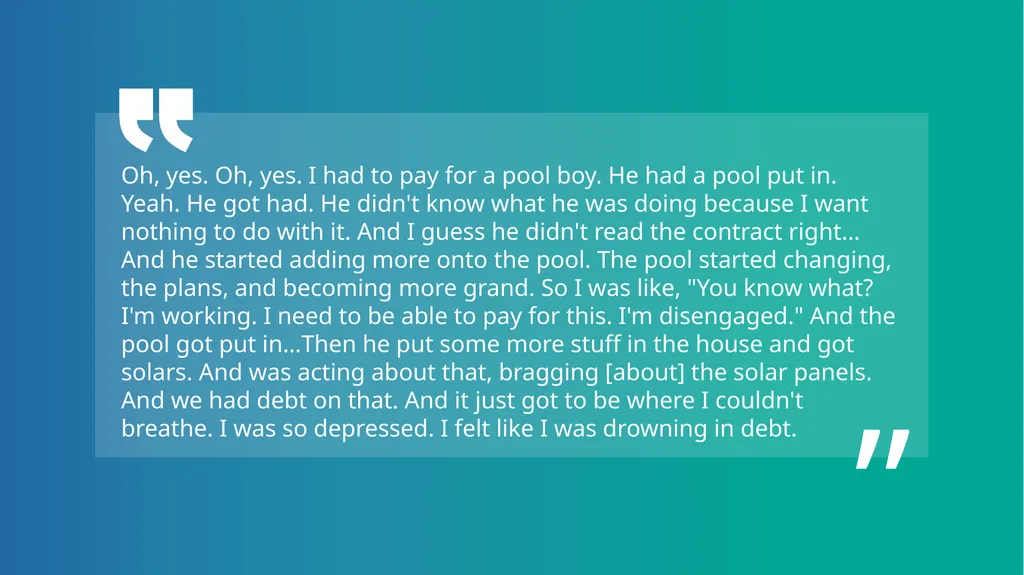
“ Oh, yes. Oh, yes. I had to pay for a pool boy. He had a pool put in. Yeah. He got had. He didn't know what he was doing because I want nothing to do with it. And I guess he didn't read the contract right…And he started adding more onto the pool. The pool started changing, the plans, and becoming more grand. So I was like, "You know what? I'm working. I need to be able to pay for this. I'm disengaged." And the pool got put in…Then he put some more stuff in the house and got solars. And was acting about that, bragging [about] the solar panels. And we had debt on that. And it just got to be where I couldn't breathe. I was so depressed. I felt like I was drowning in debt.<br>
46
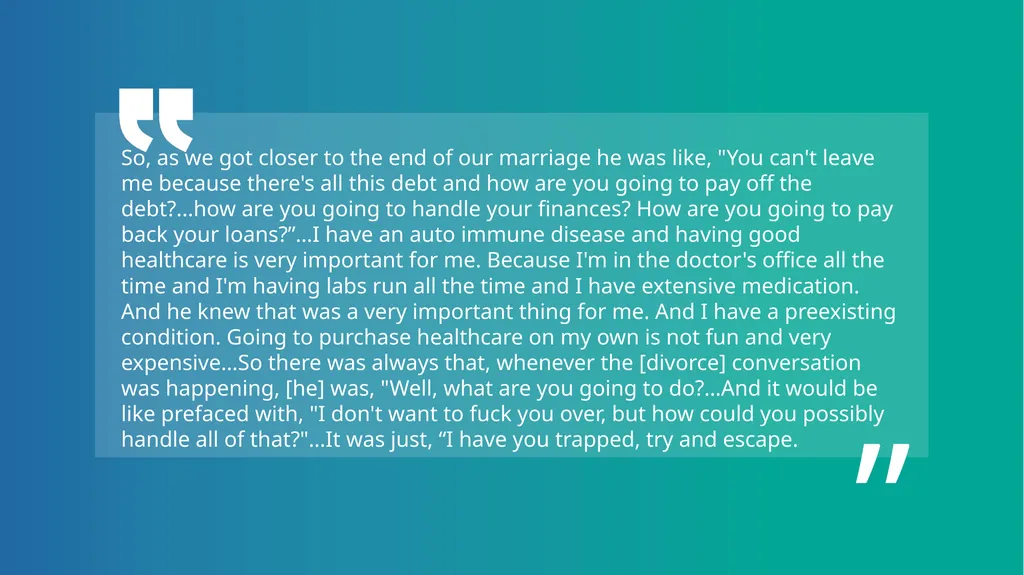
“ So, as we got closer to the end of our marriage he was like, "You can't leave me because there's all this debt and how are you going to pay off the debt?...how are you going to handle your finances? How are you going to pay back your loans?”…I have an auto immune disease and having good healthcare is very important for me. Because I'm in the doctor's office all the time and I'm having labs run all the time and I have extensive medication. And he knew that was a very important thing for me. And I have a preexisting condition. Going to purchase healthcare on my own is not fun and very expensive…So there was always that, whenever the [divorce] conversation was happening, [he] was, "Well, what are you going to do?…And it would be like prefaced with, "I don't want to fuck you over, but how could you possibly handle all of that?"…It was just, “I have you trapped, try and escape.<br>
47
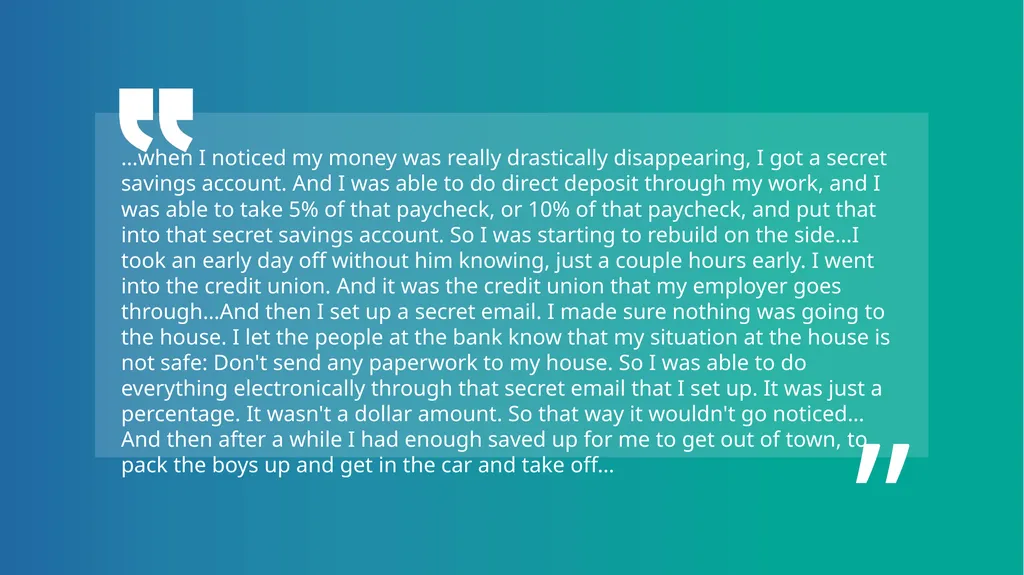
“ …when I noticed my money was really drastically disappearing, I got a secret savings account. And I was able to do direct deposit through my work, and I was able to take 5% of that paycheck, or 10% of that paycheck, and put that into that secret savings account. So I was starting to rebuild on the side…I took an early day off without him knowing, just a couple hours early. I went into the credit union. And it was the credit union that my employer goes through…And then I set up a secret email. I made sure nothing was going to the house. I let the people at the bank know that my situation at the house is not safe: Don't send any paperwork to my house. So I was able to do everything electronically through that secret email that I set up. It was just a percentage. It wasn't a dollar amount. So that way it wouldn't go noticed…And then after a while I had enough saved up for me to get out of town, to pack the boys up and get in the car and take off…<br>
48
OVERVIEW<br>
49
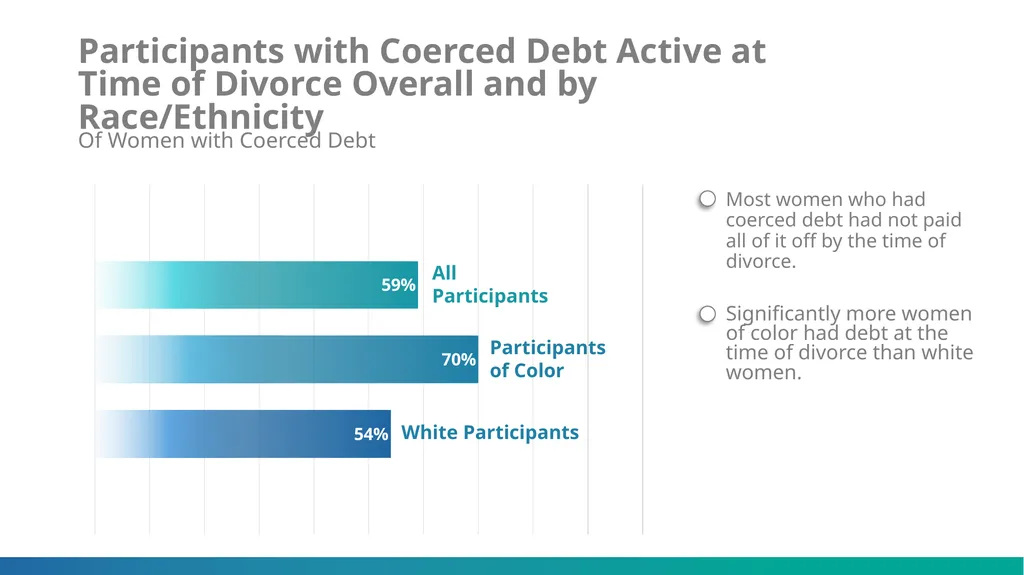
Participants with Coerced Debt Active at Time of Divorce Overall and by Race/Ethnicity All
Participants Participants
of Color White Participants Of Women with Coerced Debt<br>
50
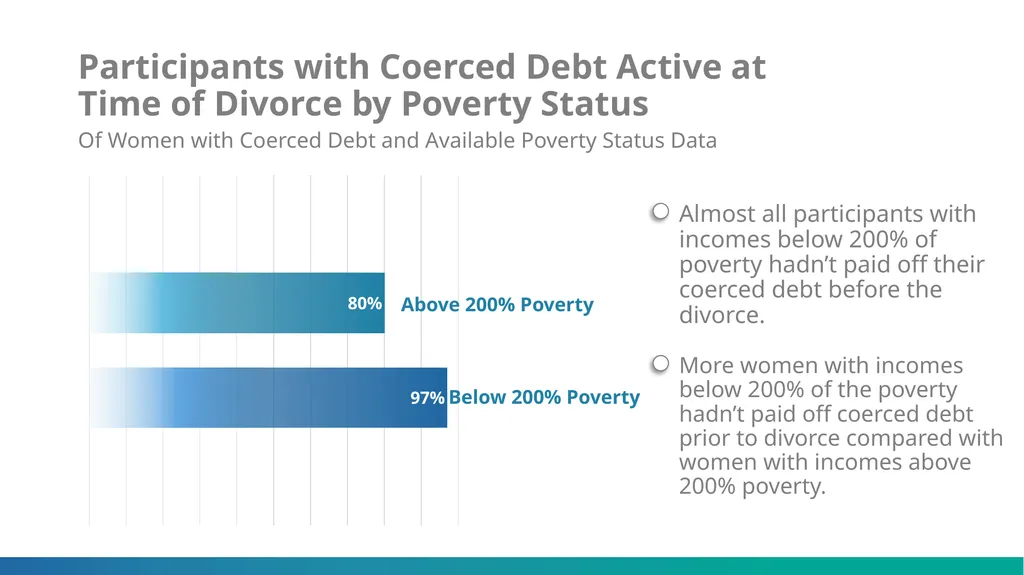
Above 200% Poverty Below 200% Poverty Of Women with Coerced Debt and Available Poverty Status Data Participants with Coerced Debt Active at Time of Divorce by Poverty Status<br>
51
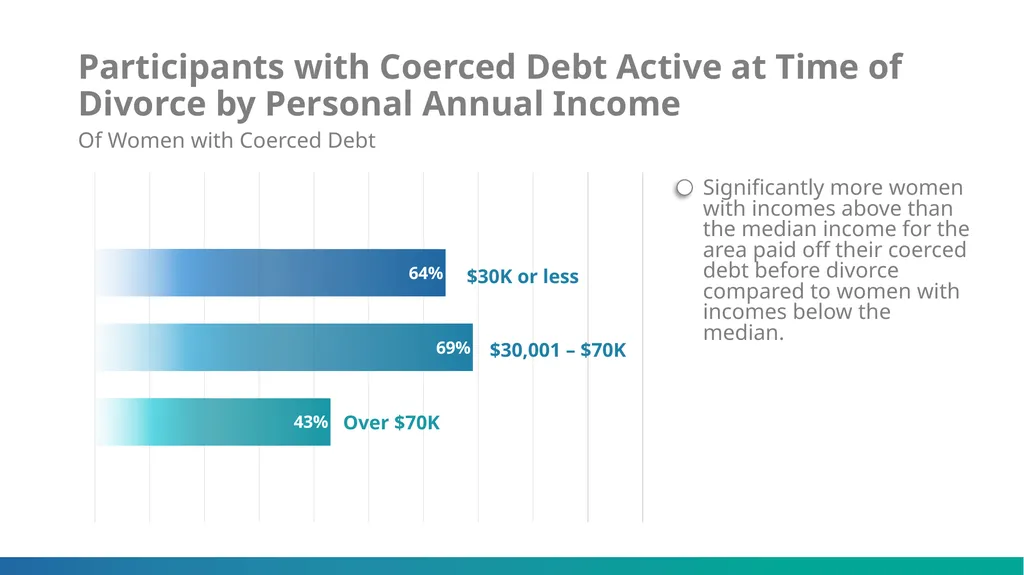
Participants with Coerced Debt Active at Time of Divorce by Personal Annual Income Over $70K $30,001 – $70K $30K or less Of Women with Coerced Debt<br>
52
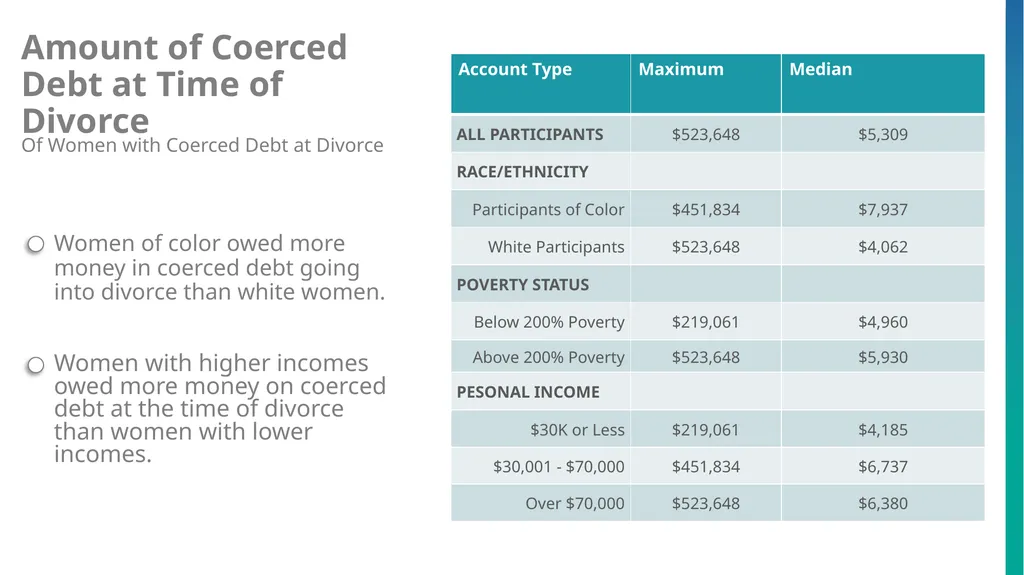
Amount of Coerced Debt at Time of Divorce Of Women with Coerced Debt at Divorce<br>
53
Effectiveness of Legal Remedies How do women seek and attain help for coerced debt through two relevant legal systems: divorce law and debtor-creditor law?<br>
54
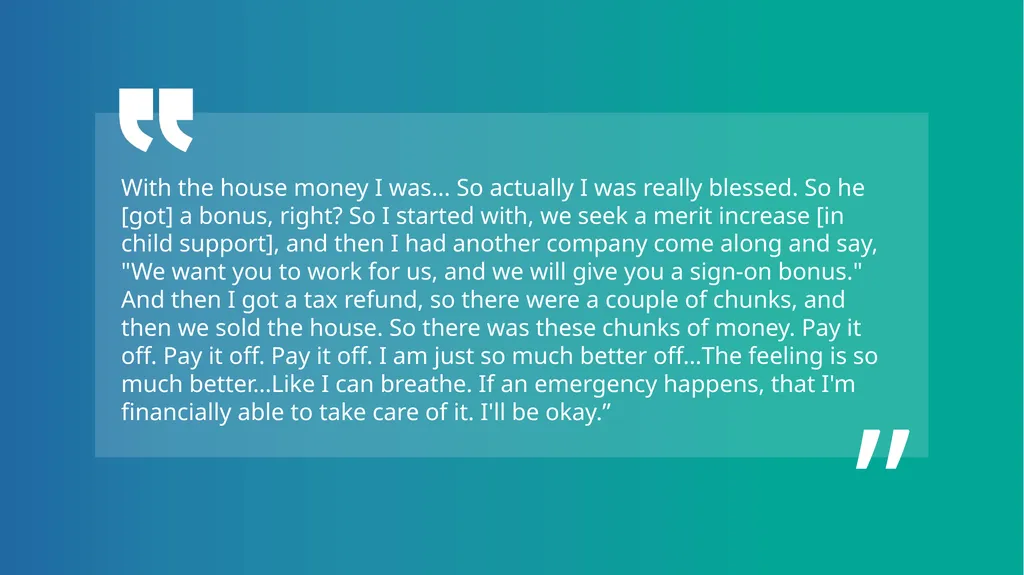
With the house money I was... So actually I was really blessed. So he [got] a bonus, right? So I started with, we seek a merit increase [in child support], and then I had another company come along and say, "We want you to work for us, and we will give you a sign-on bonus." And then I got a tax refund, so there were a couple of chunks, and then we sold the house. So there was these chunks of money. Pay it off. Pay it off. Pay it off. I am just so much better off…The feeling is so much better…Like I can breathe. If an emergency happens, that I'm financially able to take care of it. I'll be okay.” “<br>
55
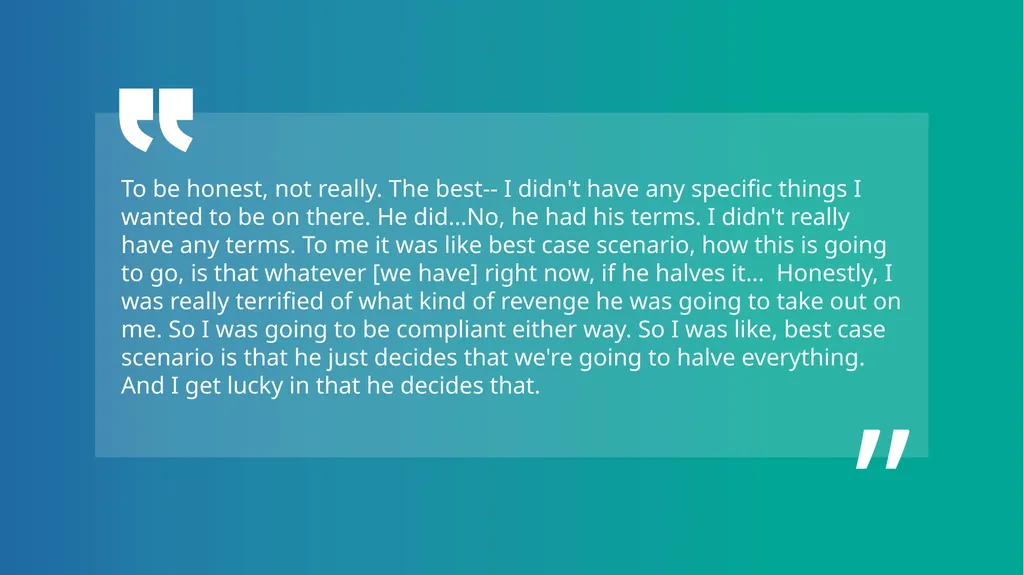
“ To be honest, not really. The best-- I didn't have any specific things I wanted to be on there. He did…No, he had his terms. I didn't really have any terms. To me it was like best case scenario, how this is going to go, is that whatever [we have] right now, if he halves it… Honestly, I was really terrified of what kind of revenge he was going to take out on me. So I was going to be compliant either way. So I was like, best case scenario is that he just decides that we're going to halve everything. And I get lucky in that he decides that.<br>
56
Help through
Divorce Law<br>
57
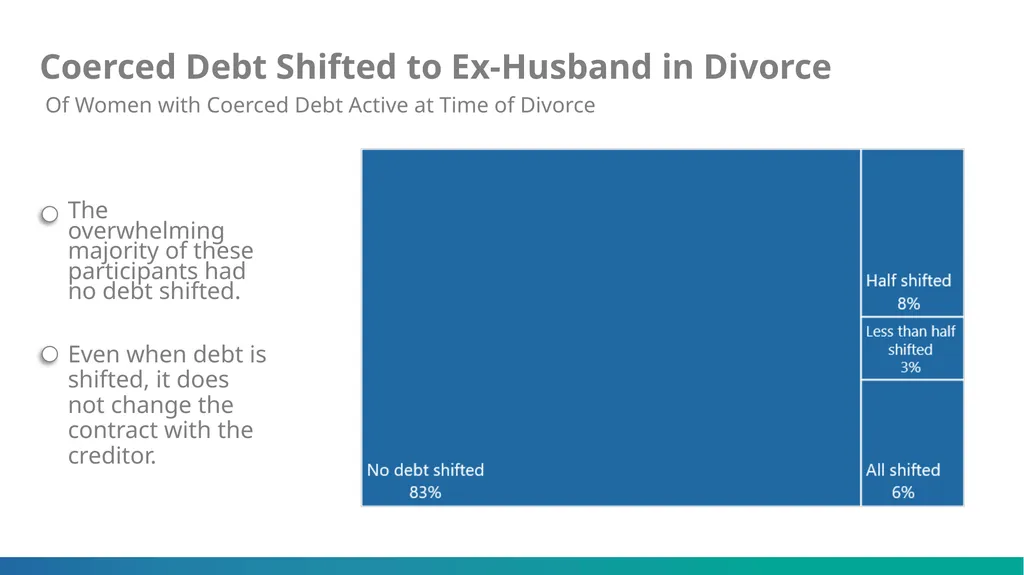
Coerced Debt Shifted to Ex-Husband in Divorce Of Women with Coerced Debt Active at Time of Divorce<br>
58
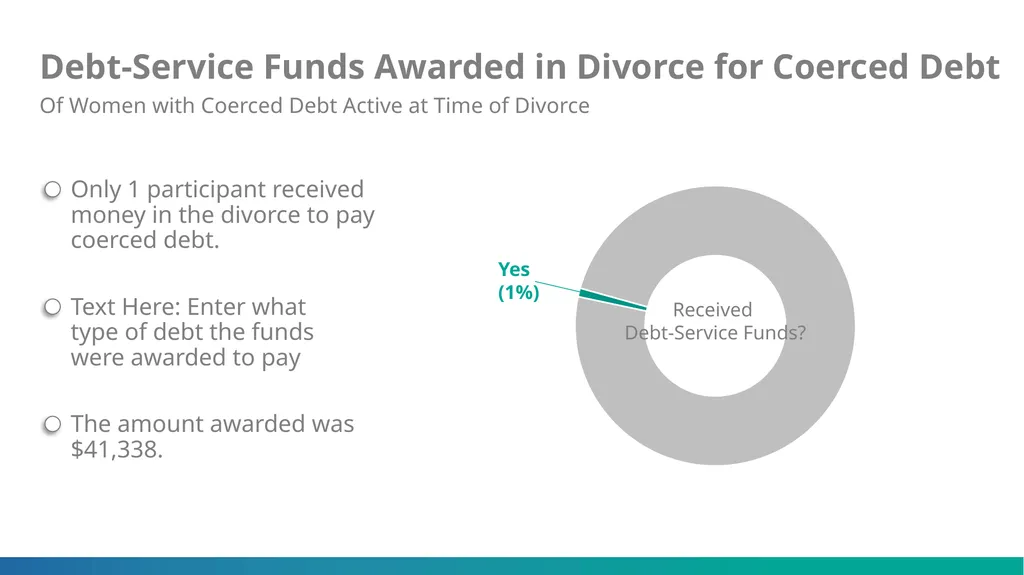
Debt-Service Funds Awarded in Divorce for Coerced Debt Of Women with Coerced Debt Active at Time of Divorce Yes
(1%) Received
Debt-Service Funds?<br>
59
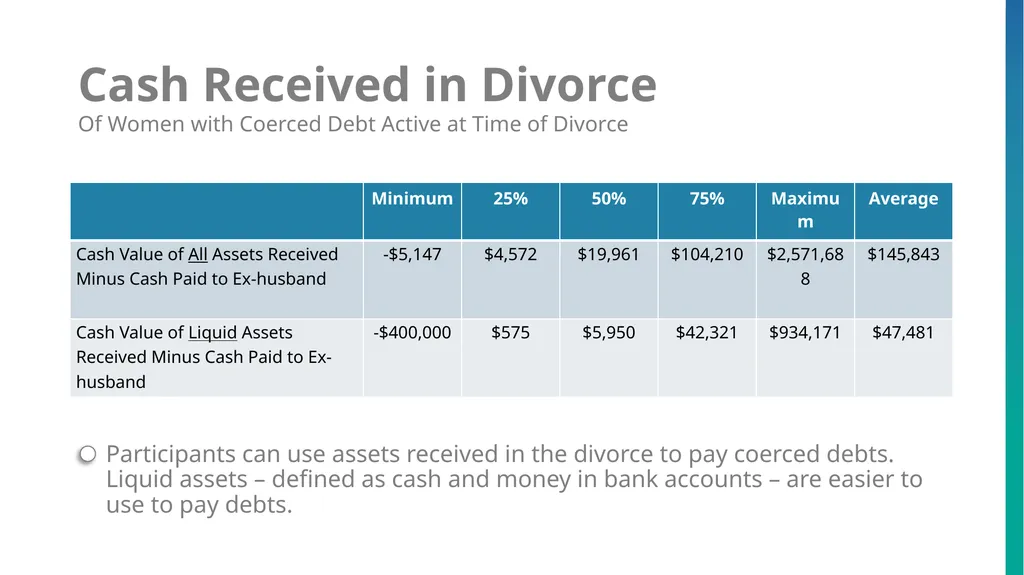
Cash Received in Divorce Of Women with Coerced Debt Active at Time of Divorce<br>
60
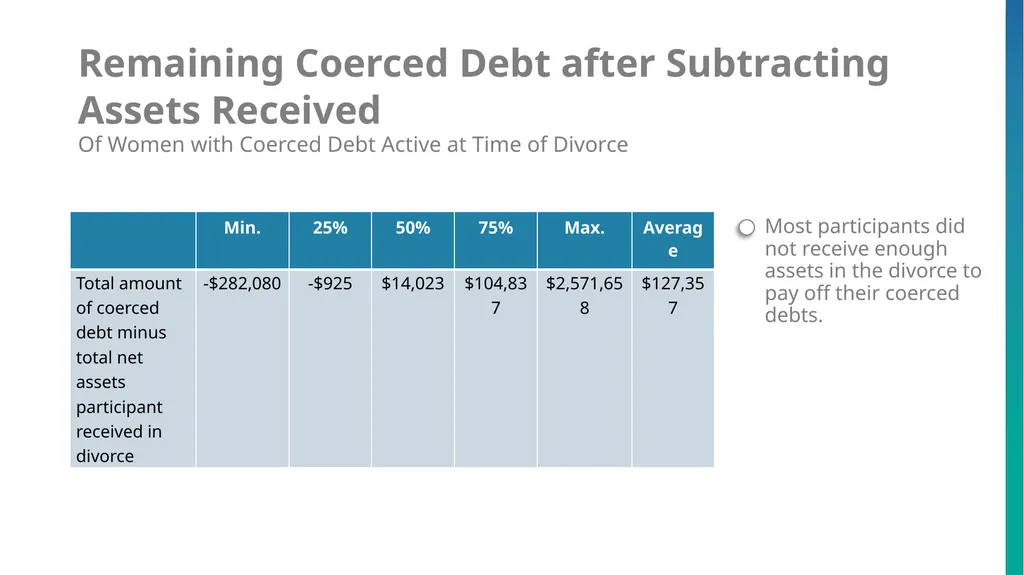
Remaining Coerced Debt after Subtracting Assets Received Of Women with Coerced Debt Active at Time of Divorce<br>
61
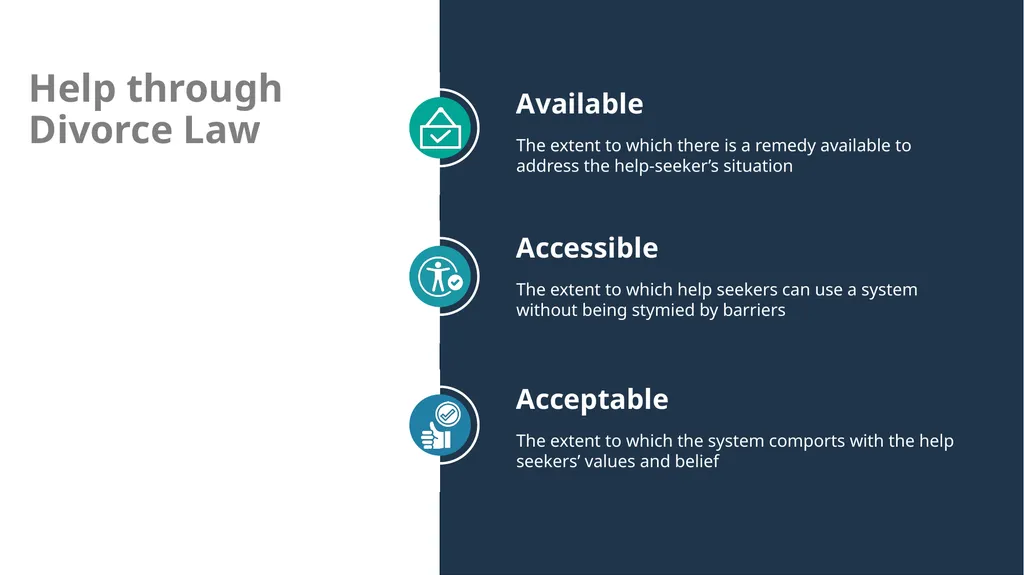
Help through
Divorce Law<br>
62
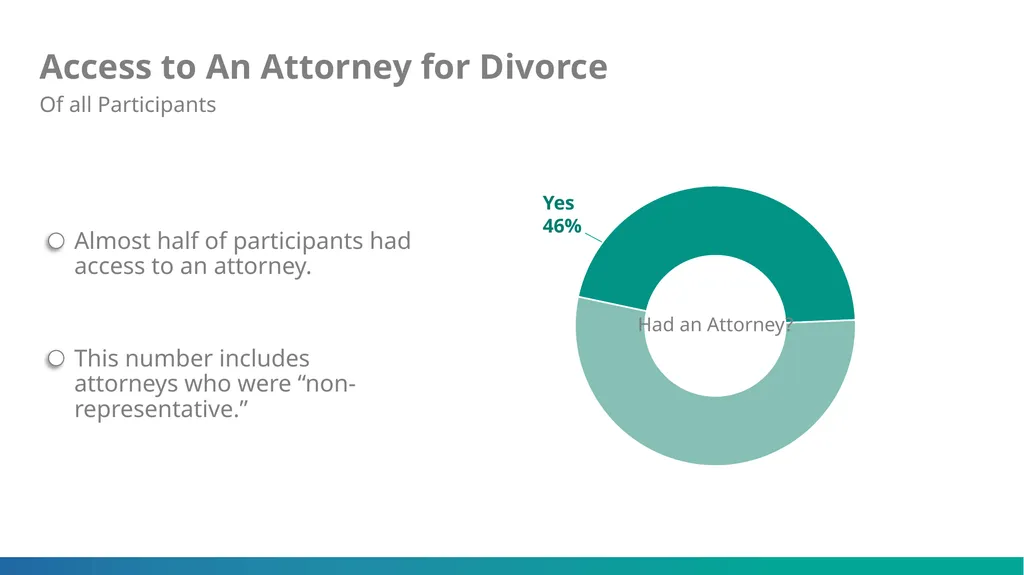
Access to An Attorney for Divorce Yes
46% Had an Attorney? Of all Participants<br>
46% Had an Attorney? Of all Participants<br>
63
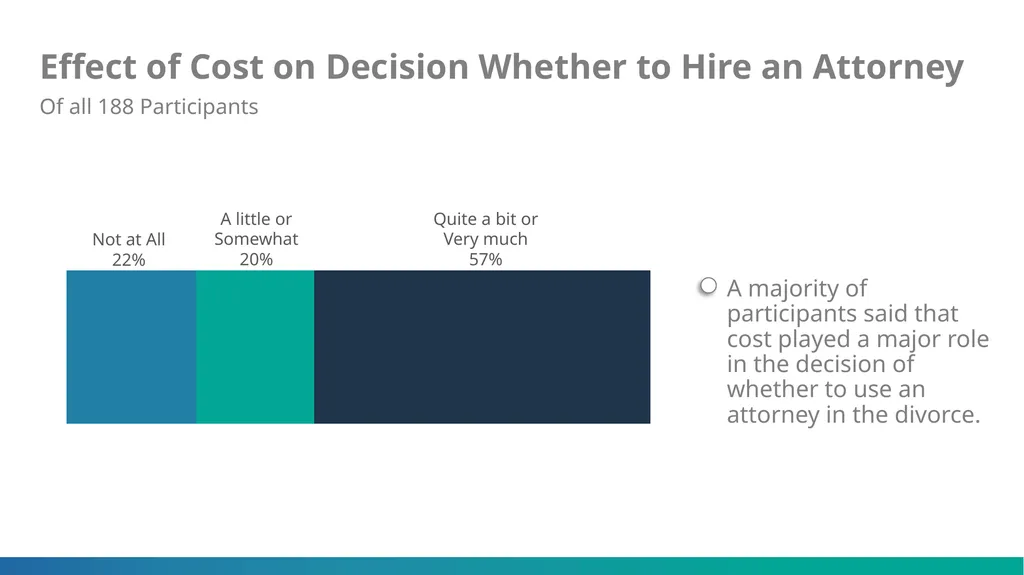
Effect of Cost on Decision Whether to Hire an Attorney Not at All
22% A little or Somewhat
20% Quite a bit or Very much
57% Of all 188 Participants<br>
20% Quite a bit or Very much
57% Of all 188 Participants<br>
64
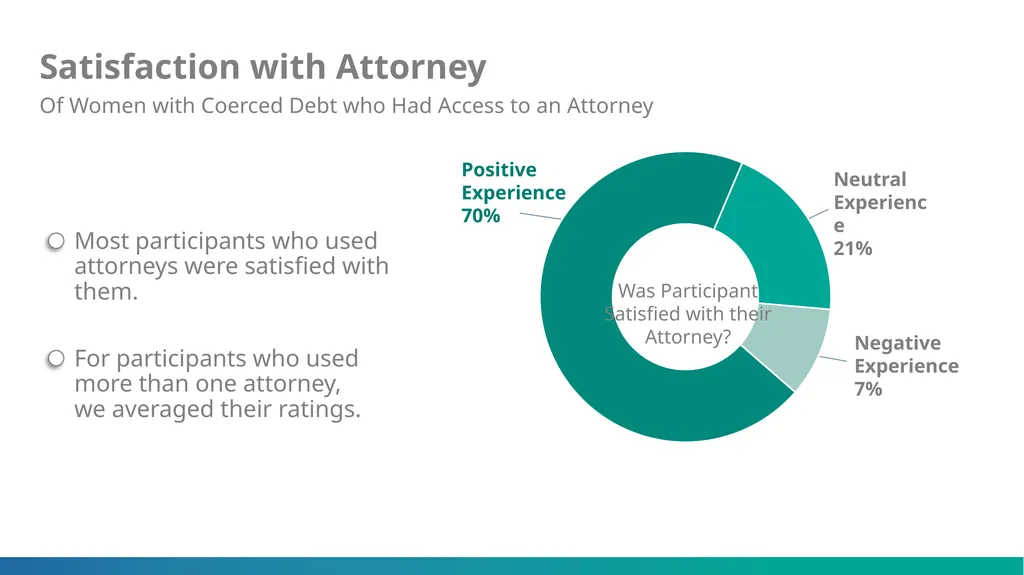
Satisfaction with Attorney Of Women with Coerced Debt who Had Access to an Attorney Negative Experience
7% Positive Experience 70% Was Participant Satisfied with their Attorney? Neutral Experience
21%<br>
7% Positive Experience 70% Was Participant Satisfied with their Attorney? Neutral Experience
21%<br>
65
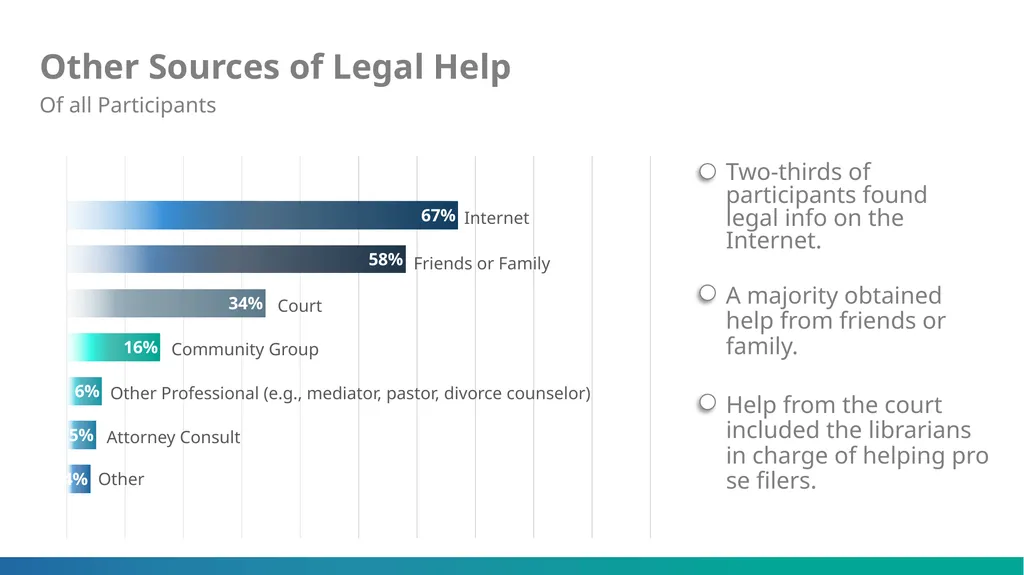
Other Sources of Legal Help Internet Friends or Family Attorney Consult Court Community Group Other Professional (e.g., mediator, pastor, divorce counselor) Other Of all Participants<br>
66
Help through
Divorce Law<br>
67
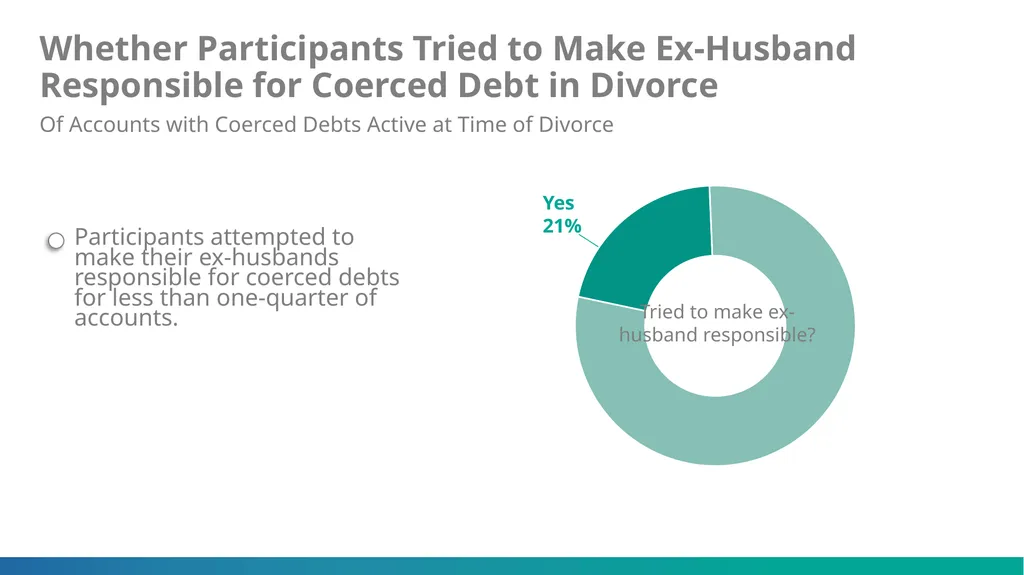
Whether Participants Tried to Make Ex-Husband Responsible for Coerced Debt in Divorce Yes
21% Tried to make ex-husband responsible? Of Accounts with Coerced Debts Active at Time of Divorce<br>
21% Tried to make ex-husband responsible? Of Accounts with Coerced Debts Active at Time of Divorce<br>
68
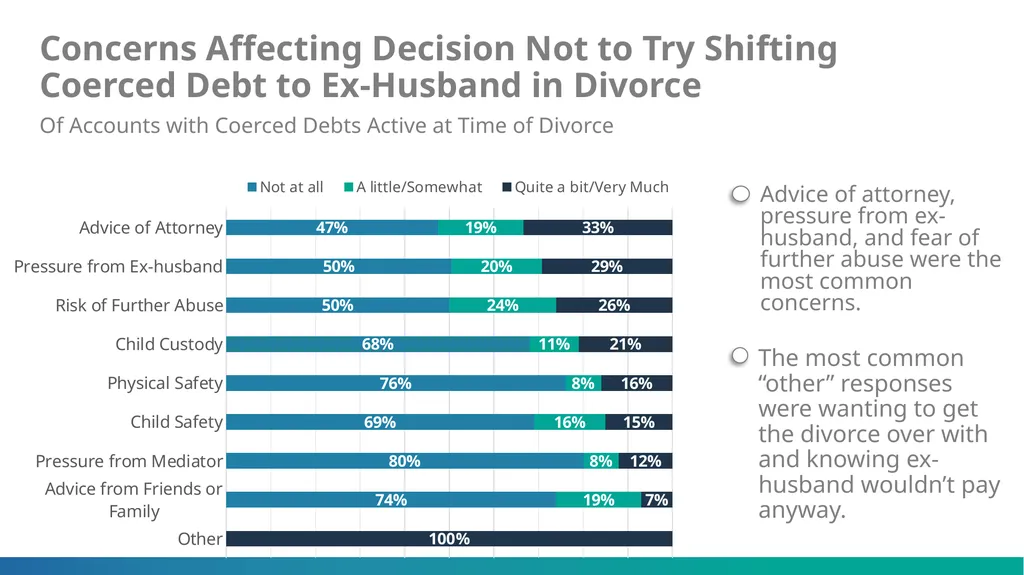
Concerns Affecting Decision Not to Try Shifting
Coerced Debt to Ex-Husband in Divorce Of Accounts with Coerced Debts Active at Time of Divorce<br>
69
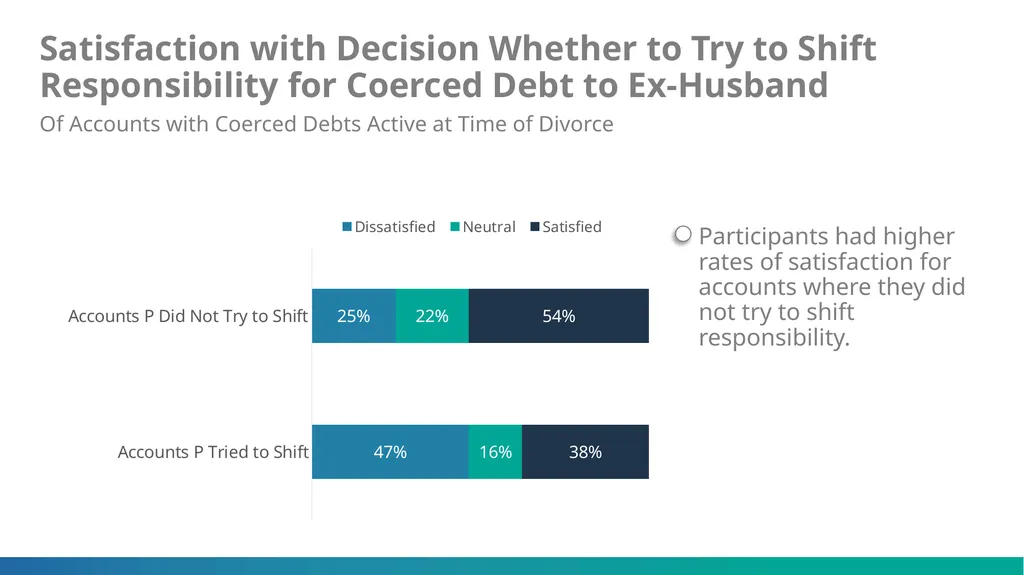
Satisfaction with Decision Whether to Try to Shift Responsibility for Coerced Debt to Ex-Husband Of Accounts with Coerced Debts Active at Time of Divorce<br>
70
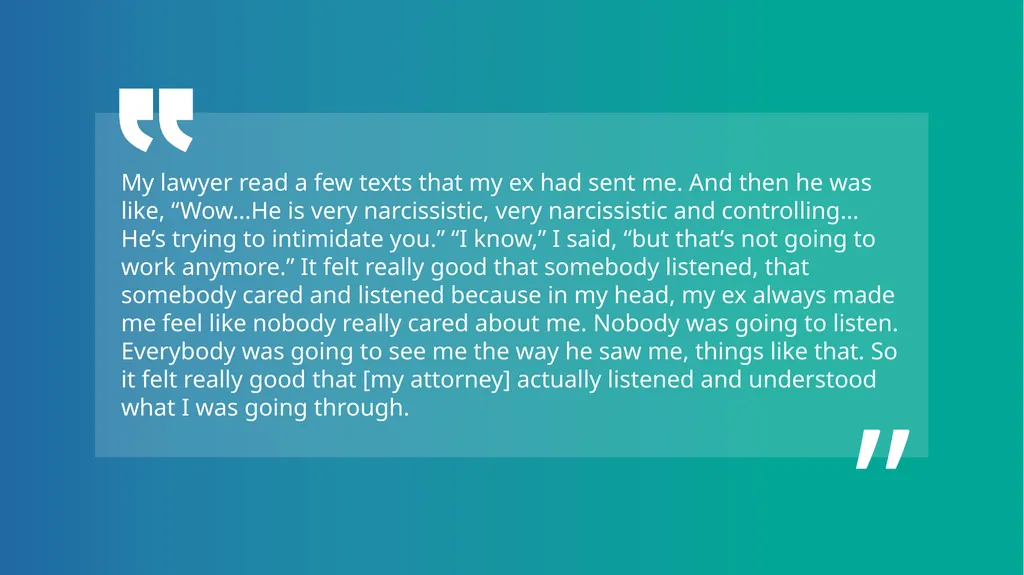
“ My lawyer read a few texts that my ex had sent me. And then he was like, “Wow…He is very narcissistic, very narcissistic and controlling…He’s trying to intimidate you.” “I know,” I said, “but that’s not going to work anymore.” It felt really good that somebody listened, that somebody cared and listened because in my head, my ex always made me feel like nobody really cared about me. Nobody was going to listen. Everybody was going to see me the way he saw me, things like that. So it felt really good that [my attorney] actually listened and understood what I was going through.<br>
71
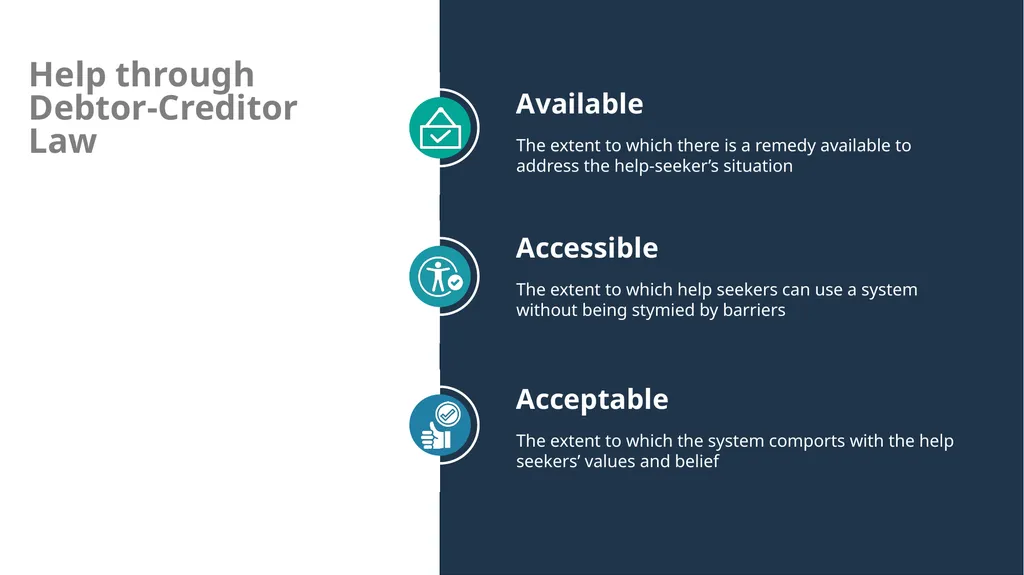
Help through Debtor-Creditor Law<br>
72
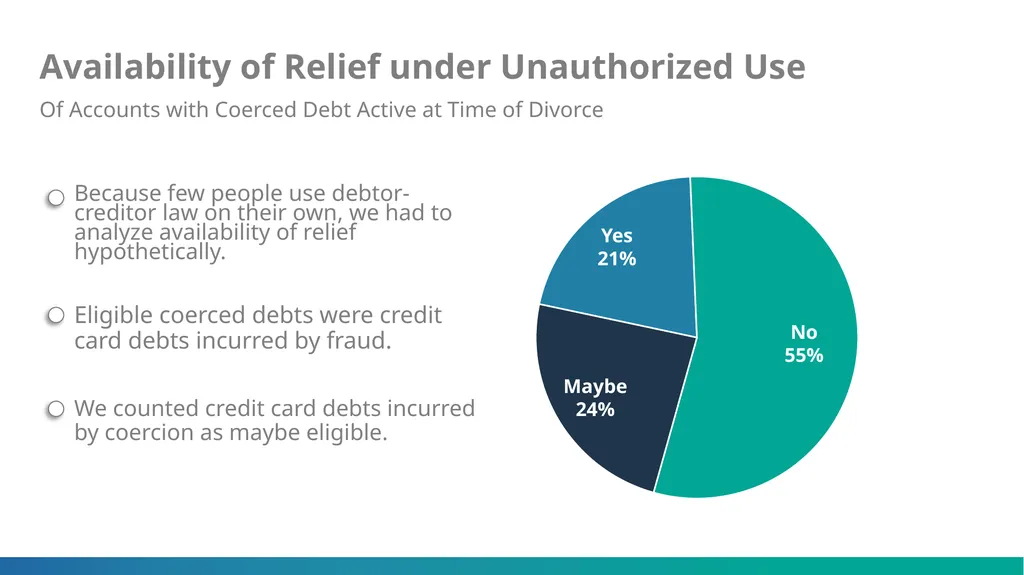
Availability of Relief under Unauthorized Use No
55% Yes
21% Of Accounts with Coerced Debt Active at Time of Divorce Maybe 24%<br>
21% Of Accounts with Coerced Debt Active at Time of Divorce Maybe 24%<br>
73
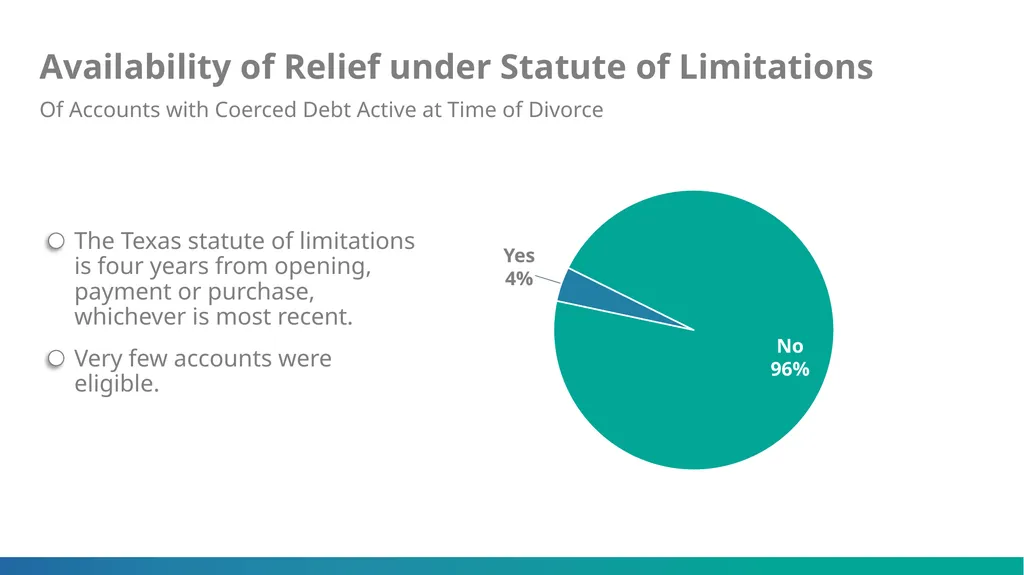
Availability of Relief under Statute of Limitations No
96% Yes
4% Of Accounts with Coerced Debt Active at Time of Divorce<br>
4% Of Accounts with Coerced Debt Active at Time of Divorce<br>
74
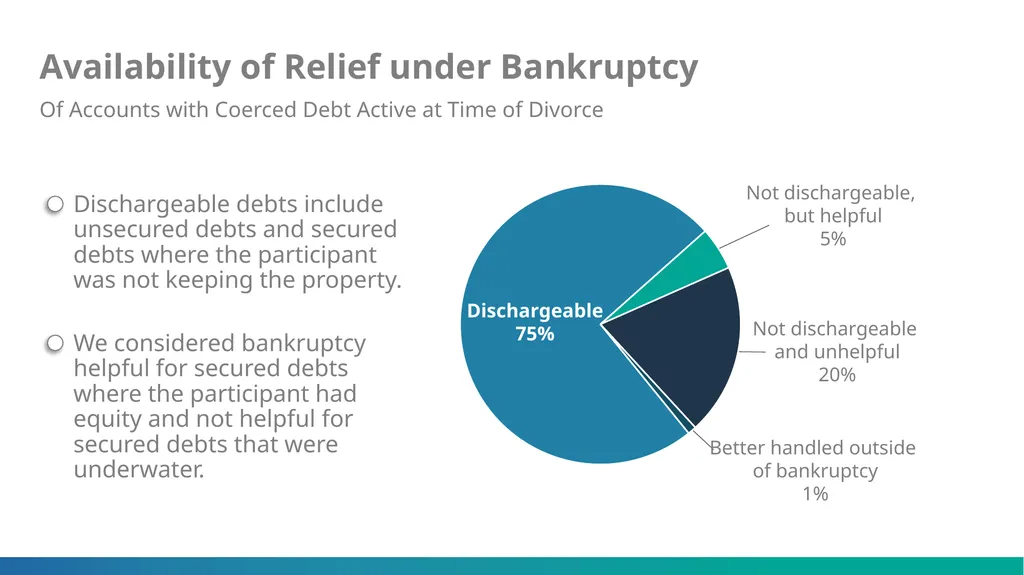
Not dischargeable,
but helpful
5% Availability of Relief under Bankruptcy Dischargeable 75% Not dischargeable and unhelpful
20% Better handled outside of bankruptcy
1% Of Accounts with Coerced Debt Active at Time of Divorce<br>
5% Availability of Relief under Bankruptcy Dischargeable 75% Not dischargeable and unhelpful
20% Better handled outside of bankruptcy
1% Of Accounts with Coerced Debt Active at Time of Divorce<br>
75
Help through Debtor-Creditor Law<br>
76
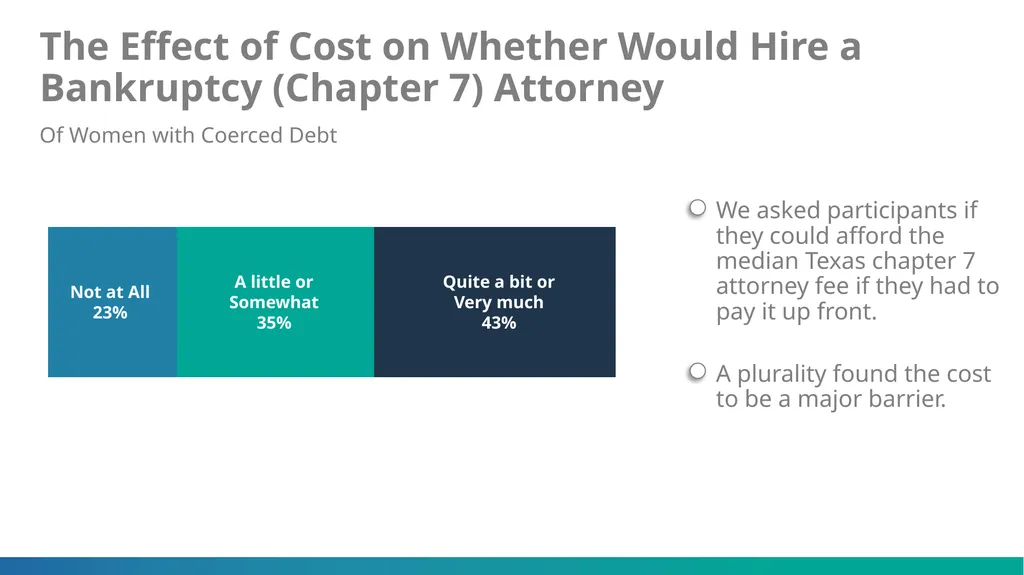
The Effect of Cost on Whether Would Hire a Bankruptcy (Chapter 7) Attorney Not at All
23% A little or Somewhat
35% Quite a bit or Very much
43% Of Women with Coerced Debt<br>
35% Quite a bit or Very much
43% Of Women with Coerced Debt<br>
77
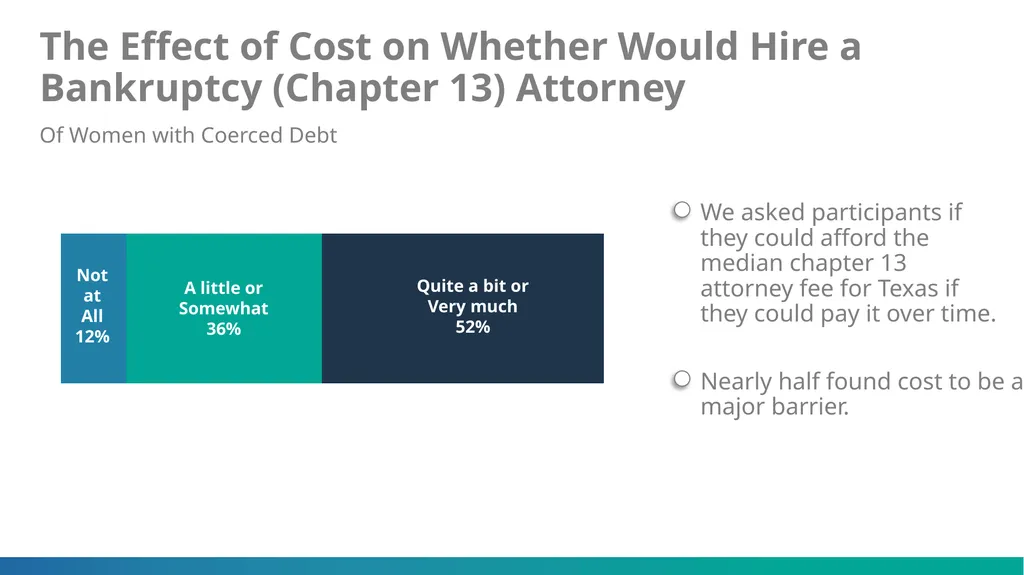
The Effect of Cost on Whether Would Hire a Bankruptcy (Chapter 13) Attorney Not at All
12% A little or Somewhat
36% Quite a bit or Very much
52% Of Women with Coerced Debt<br>
36% Quite a bit or Very much
52% Of Women with Coerced Debt<br>
78
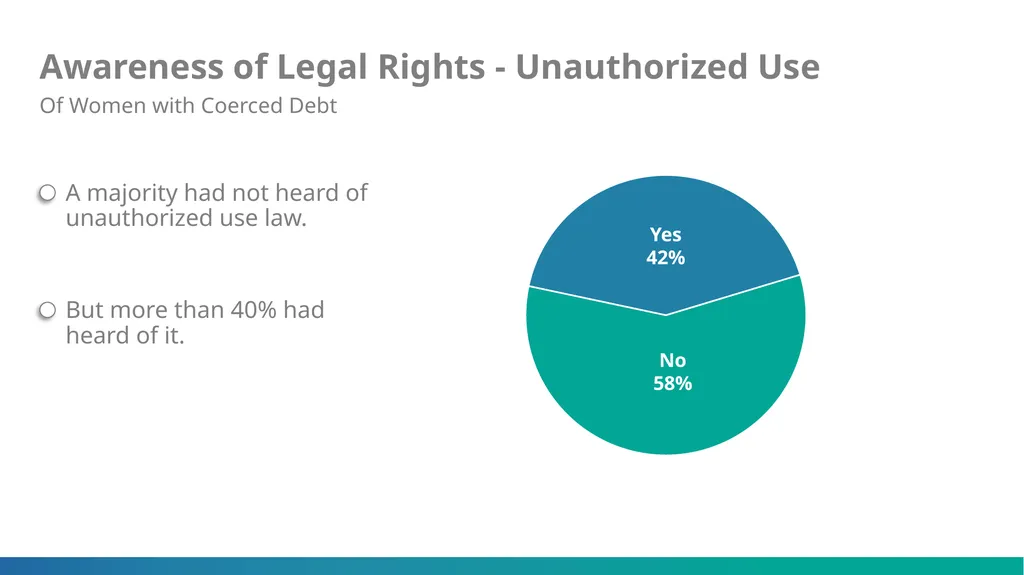
Awareness of Legal Rights - Unauthorized Use No
58% Yes
42% Of Women with Coerced Debt<br>
42% Of Women with Coerced Debt<br>
79
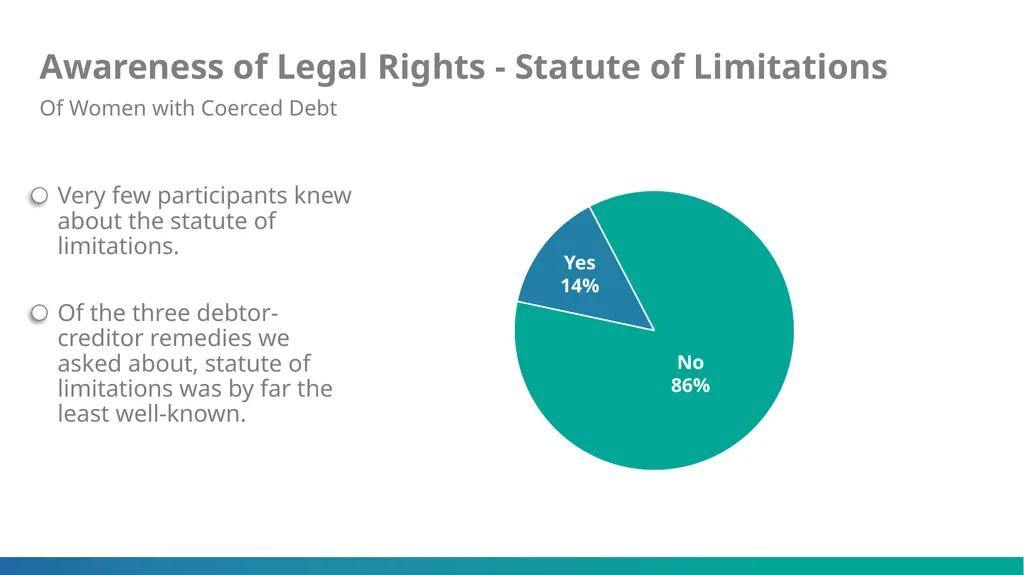
Awareness of Legal Rights - Statute of Limitations No
86% Yes
14% Of Women with Coerced Debt<br>
14% Of Women with Coerced Debt<br>
80
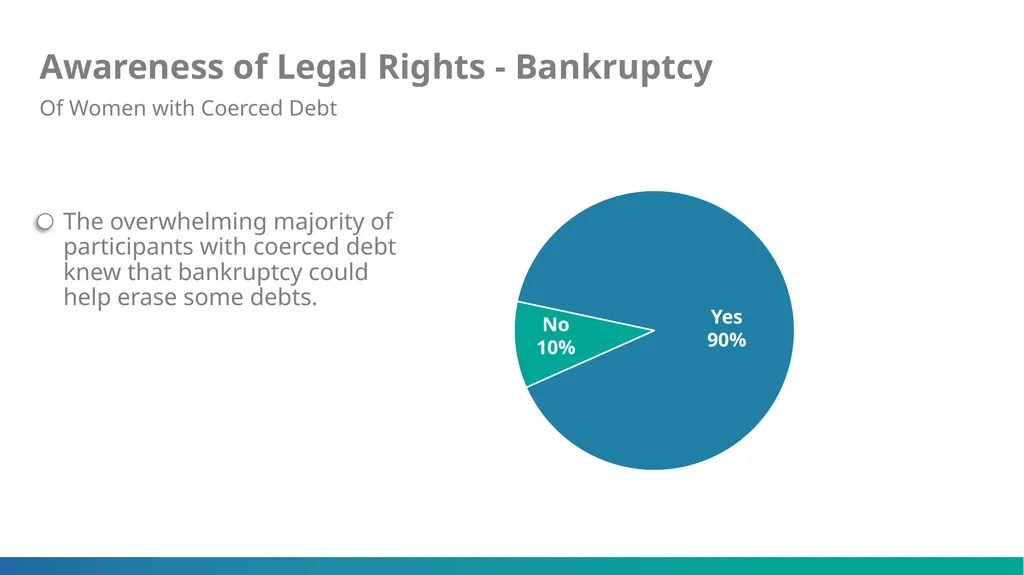
Awareness of Legal Rights - Bankruptcy Of Women with Coerced Debt No
10% Yes
90%<br>
90%<br>
81
Help through Debtor-Creditor Law<br>
82
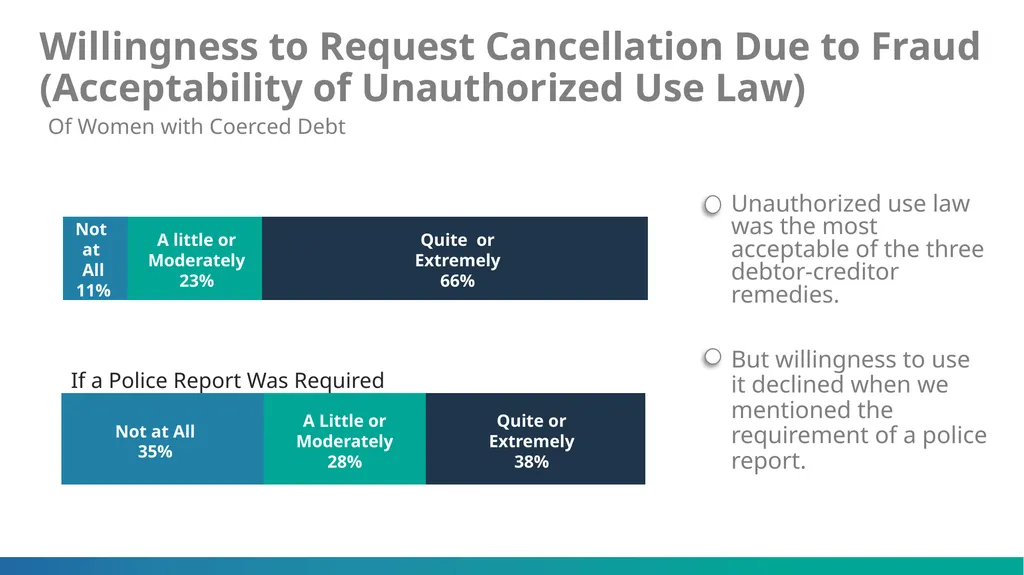
Willingness to Request Cancellation Due to Fraud (Acceptability of Unauthorized Use Law) Not
at
All
11% A little or Moderately
23% Quite or Extremely
66% Of Women with Coerced Debt Not at All 35% A Little or Moderately
28% Quite or Extremely
38% If a Police Report Was Required<br>
23% Quite or Extremely
66% Of Women with Coerced Debt Not at All 35% A Little or Moderately
28% Quite or Extremely
38% If a Police Report Was Required<br>
83
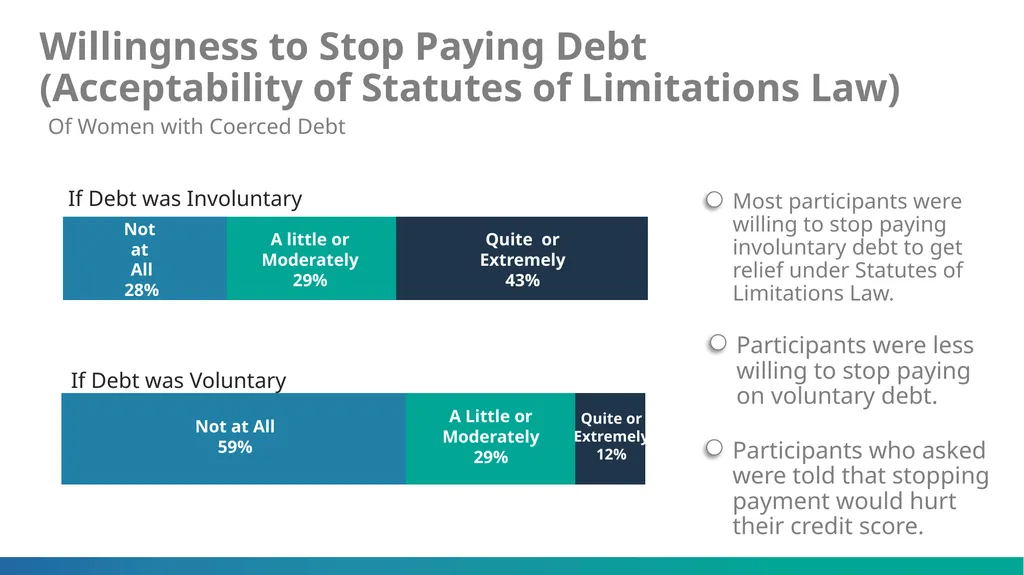
Willingness to Stop Paying Debt
(Acceptability of Statutes of Limitations Law) Not
at
All
28% A little or Moderately
29% Quite or Extremely
43% Of Women with Coerced Debt Not at All 59% A Little or Moderately
29% Quite or Extremely
12% If Debt was Voluntary If Debt was Involuntary<br>
29% Quite or Extremely
43% Of Women with Coerced Debt Not at All 59% A Little or Moderately
29% Quite or Extremely
12% If Debt was Voluntary If Debt was Involuntary<br>
84
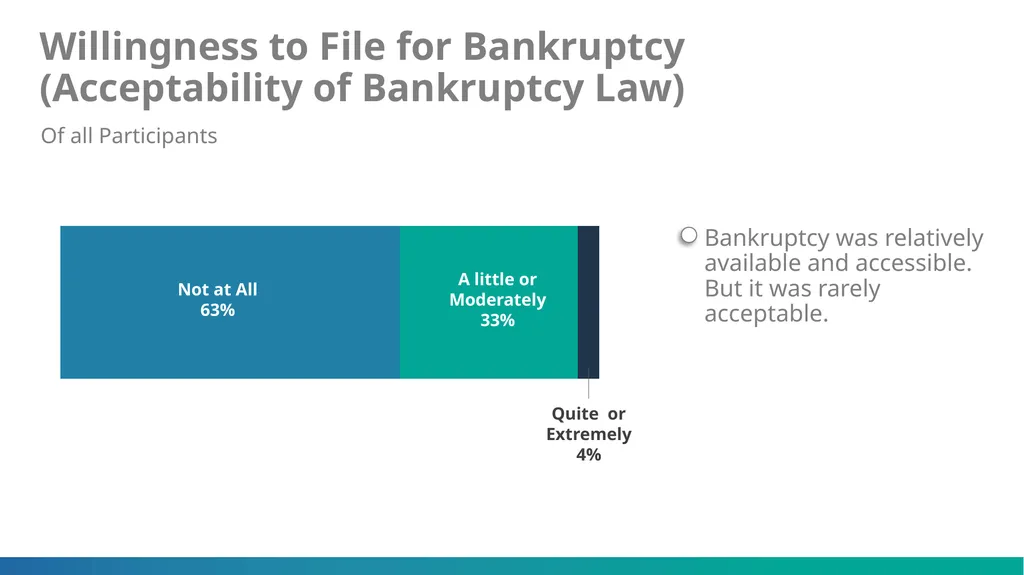
Willingness to File for Bankruptcy
(Acceptability of Bankruptcy Law) Of all Participants A little or Moderately
33% Quite or Extremely
4% Not at All 63%<br>
33% Quite or Extremely
4% Not at All 63%<br>
85
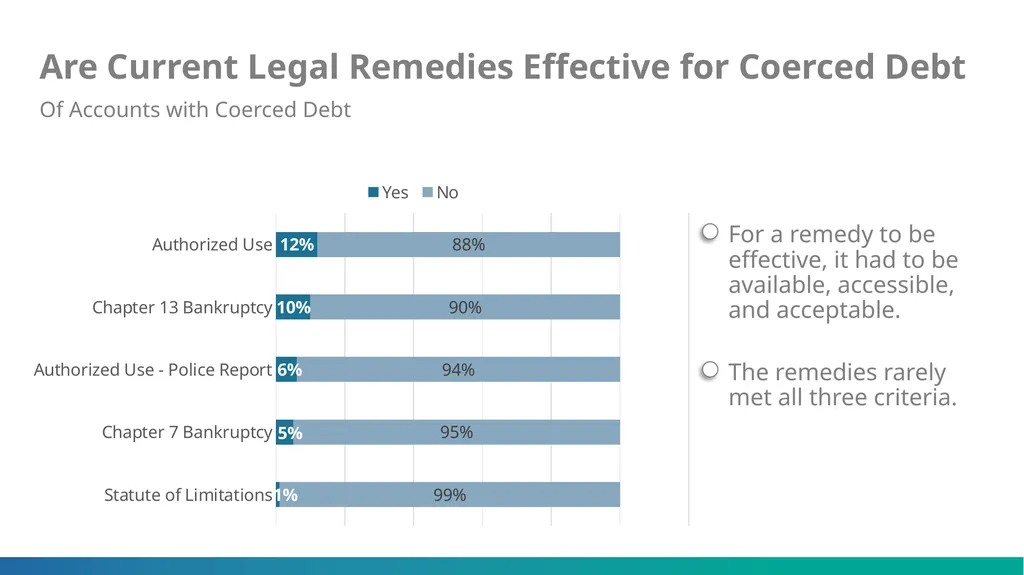
Are Current Legal Remedies Effective for Coerced Debt Of Accounts with Coerced Debt<br>
86
Discussion<br>
87
THANK YOU This project was funded by a grant from the National Science Foundation. Award #1920557.<br>