
Beyond Sport Online Learning Session Toolkit:

Description: Beyond Sport Online Learning Session Toolkit: Budgeting and Forecasting www.pwc.com What is financial management? Financial management can be defined as managing the finances of an organisation in order to achieve financial and strategic
Related Topics
Download Presentation
"Beyond Sport Online Learning Session Toolkit:" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Beyond Sport Online Learning Session
Toolkit: Budgeting and Forecasting www.pwc.com<br>
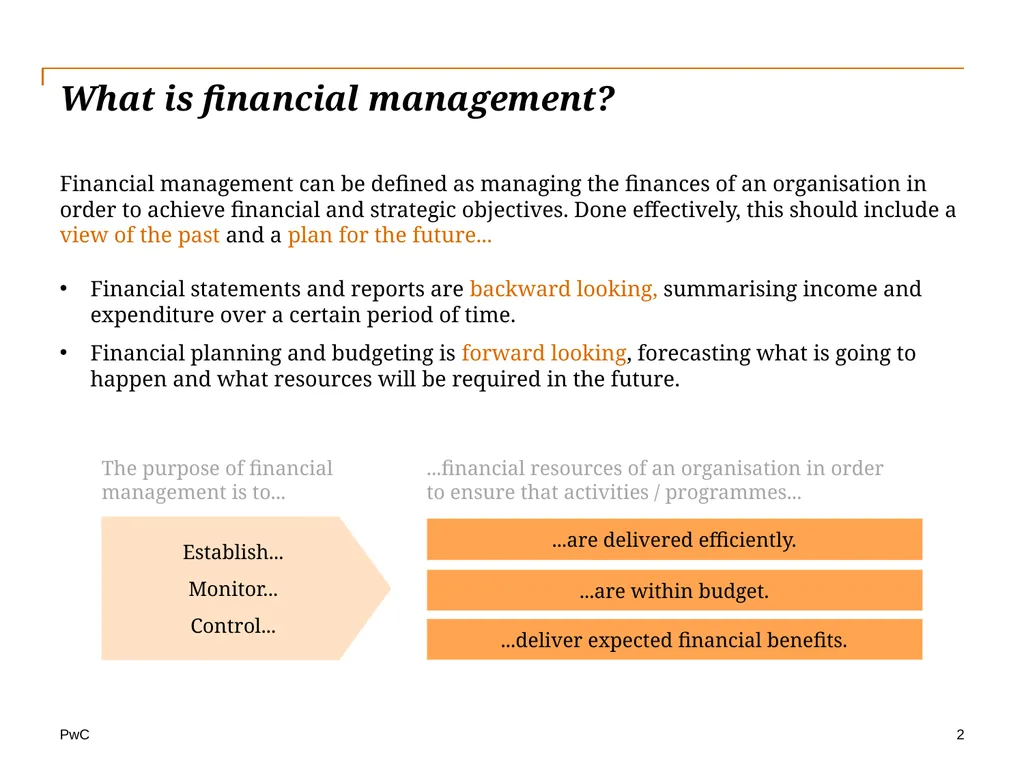
slide2. What is financial management? Financial management can be defined as managing the finances of an organisation in order to achieve financial and strategic objectives. Done effectively, this should include a view of the past and a plan for the future...
Financial statements and reports are backward looking, summarising income and expenditure over a certain period of time.
Financial planning and budgeting is forward looking, forecasting what is going to happen and what resources will be required in the future. 2<br>
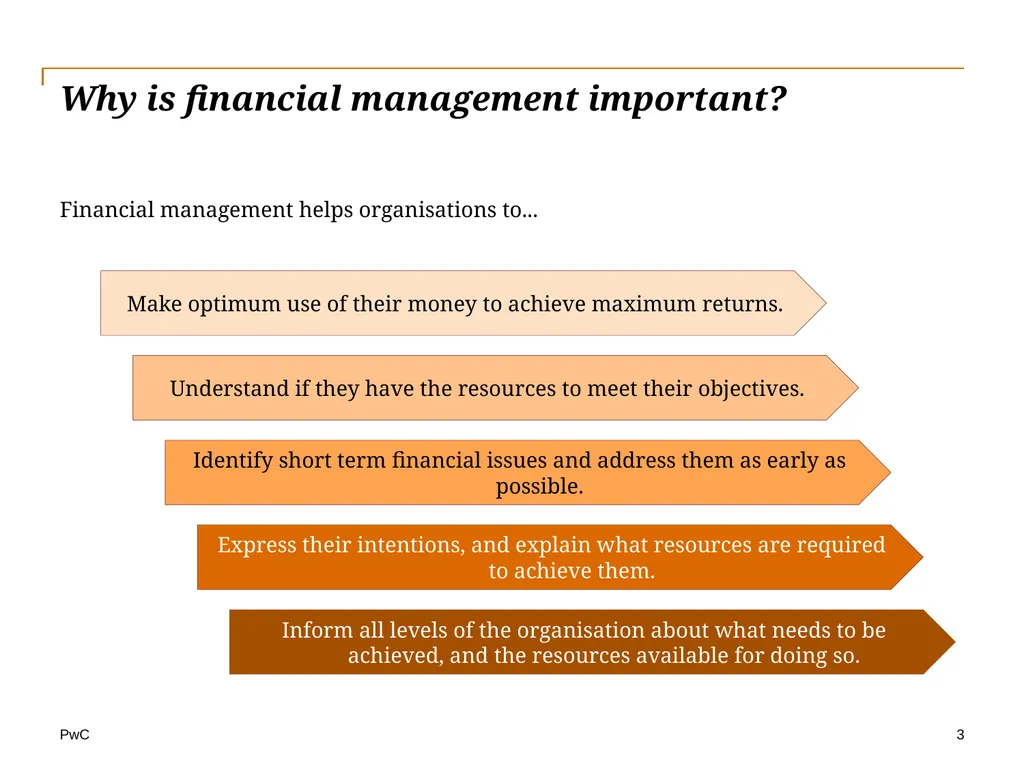
slide3. Why is financial management important? 3 Make optimum use of their money to achieve maximum returns. Understand if they have the resources to meet their objectives. Identify short term financial issues and address them as early as possible. Express their intentions, and explain what resources are required to achieve them. Inform all levels of the organisation about what needs to be achieved, and the resources available for doing so. Financial management helps organisations to...<br>
slide4. Financial statements<br>
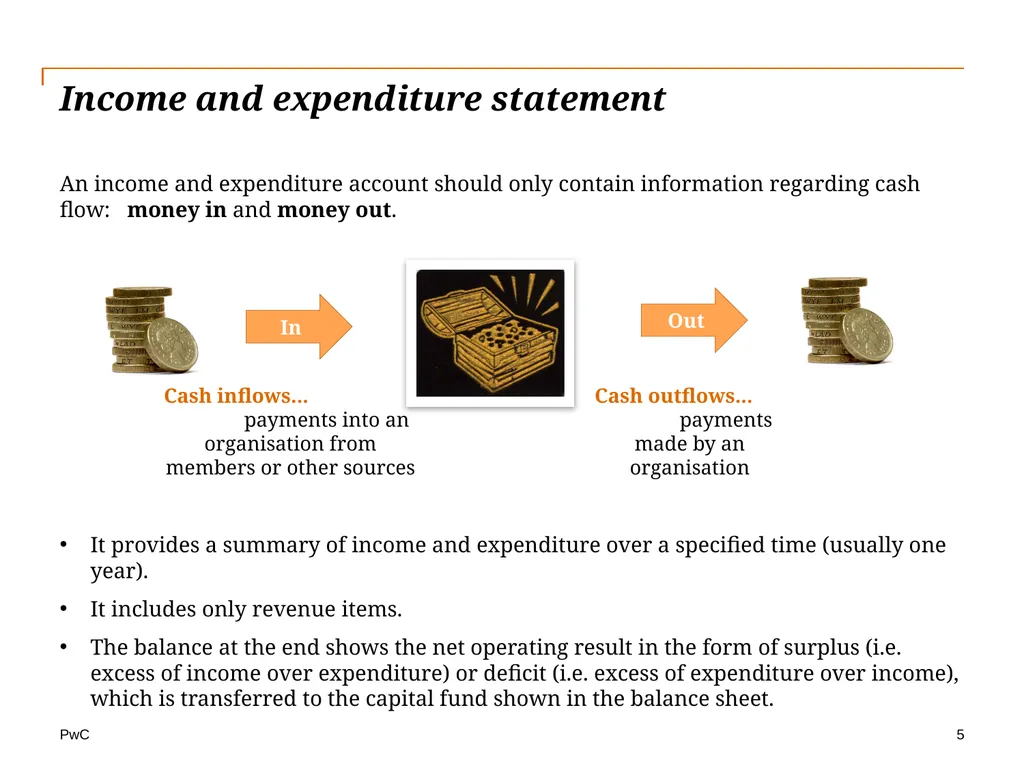
slide5. Income and expenditure statement An income and expenditure account should only contain information regarding cash flow: money in and money out.
It provides a summary of income and expenditure over a specified time (usually one year).
It includes only revenue items.
The balance at the end shows the net operating result in the form of surplus (i.e. excess of income over expenditure) or deficit (i.e. excess of expenditure over income), which is transferred to the capital fund shown in the balance sheet. 5 In Out Cash inflows...
payments into an organisation from members or other sources Cash outflows...
payments made by an organisation<br>
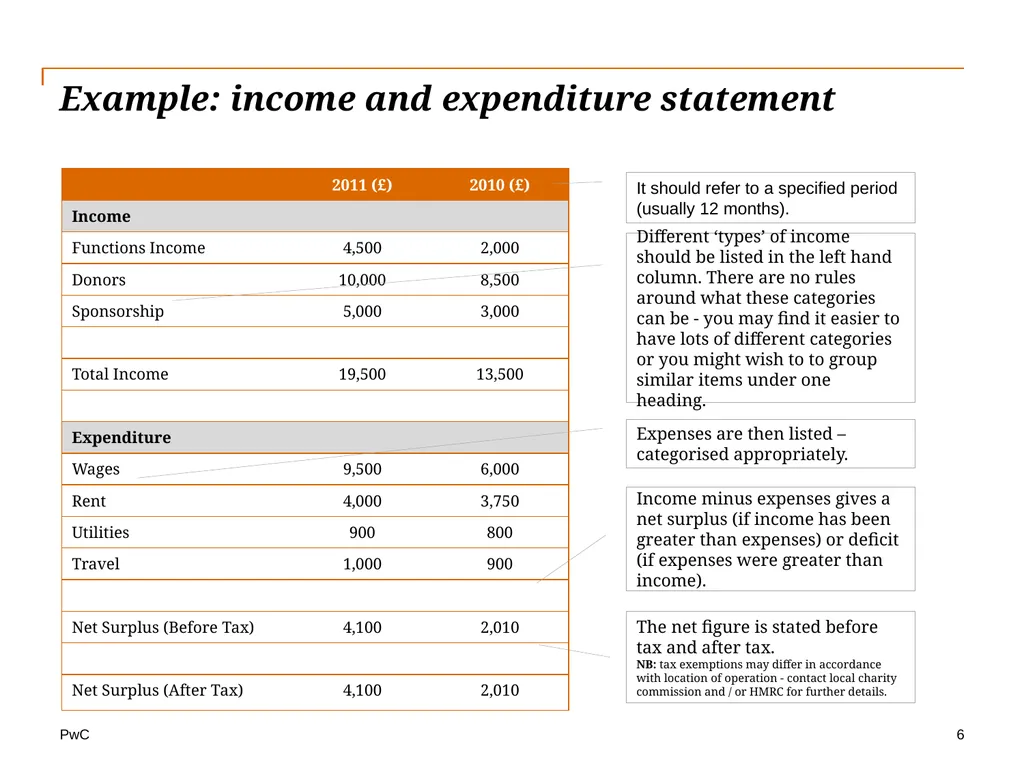
slide6. Example: income and expenditure statement 6 It should refer to a specified period (usually 12 months). Different ‘types’ of income should be listed in the left hand column. There are no rules around what these categories can be - you may find it easier to have lots of different categories or you might wish to to group similar items under one heading. Expenses are then listed – categorised appropriately. Income minus expenses gives a net surplus (if income has been greater than expenses) or deficit (if expenses were greater than income). The net figure is stated before tax and after tax.
NB: tax exemptions may differ in accordance with location of operation - contact local charity commission and / or HMRC for further details.<br>
slide7. Balance sheet An organisation’s balance sheet is a snapshot of assets and liabilities and gives a view financial health at a specific point in time.
An organisation should ideally have more assets than liabilities - similar to the income and expenditure account.
A version of the balance sheet should be presented at monthly meetings to ensure that financial performance is being monitored. 7<br>
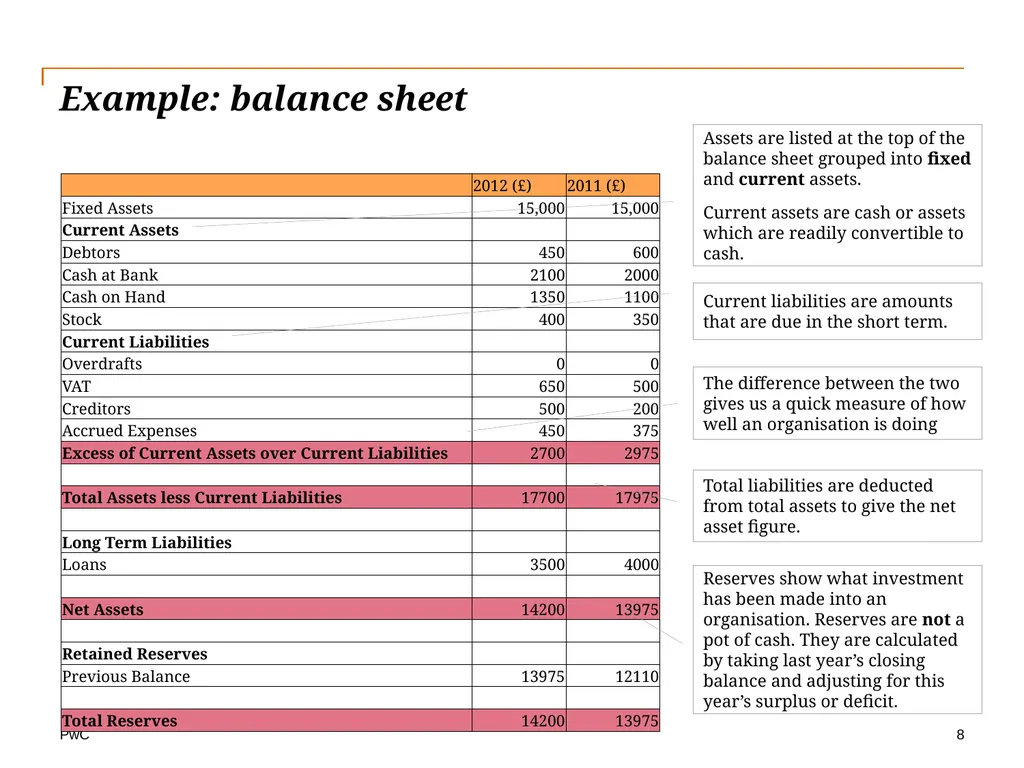
slide8. Example: balance sheet 8 Assets are listed at the top of the balance sheet grouped into fixed and current assets.
Current assets are cash or assets which are readily convertible to cash. Current liabilities are amounts that are due in the short term. The difference between the two gives us a quick measure of how well an organisation is doing Total liabilities are deducted from total assets to give the net asset figure. Reserves show what investment has been made into an organisation. Reserves are not a pot of cash. They are calculated by taking last year’s closing balance and adjusting for this year’s surplus or deficit.<br>
slide9. Financial planning<br>
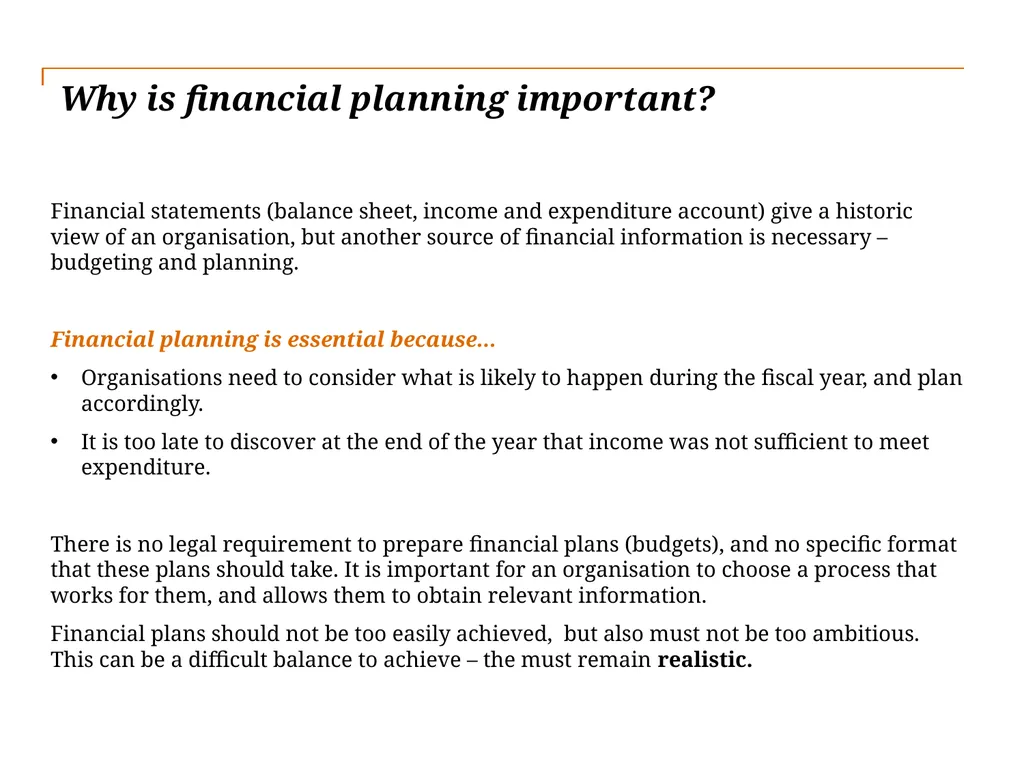
slide10. Why is financial planning important? Financial statements (balance sheet, income and expenditure account) give a historic view of an organisation, but another source of financial information is necessary – budgeting and planning.
Financial planning is essential because...
Organisations need to consider what is likely to happen during the fiscal year, and plan accordingly.
It is too late to discover at the end of the year that income was not sufficient to meet expenditure.
There is no legal requirement to prepare financial plans (budgets), and no specific format that these plans should take. It is important for an organisation to choose a process that works for them, and allows them to obtain relevant information.
Financial plans should not be too easily achieved, but also must not be too ambitious. This can be a difficult balance to achieve – the must remain realistic.<br>
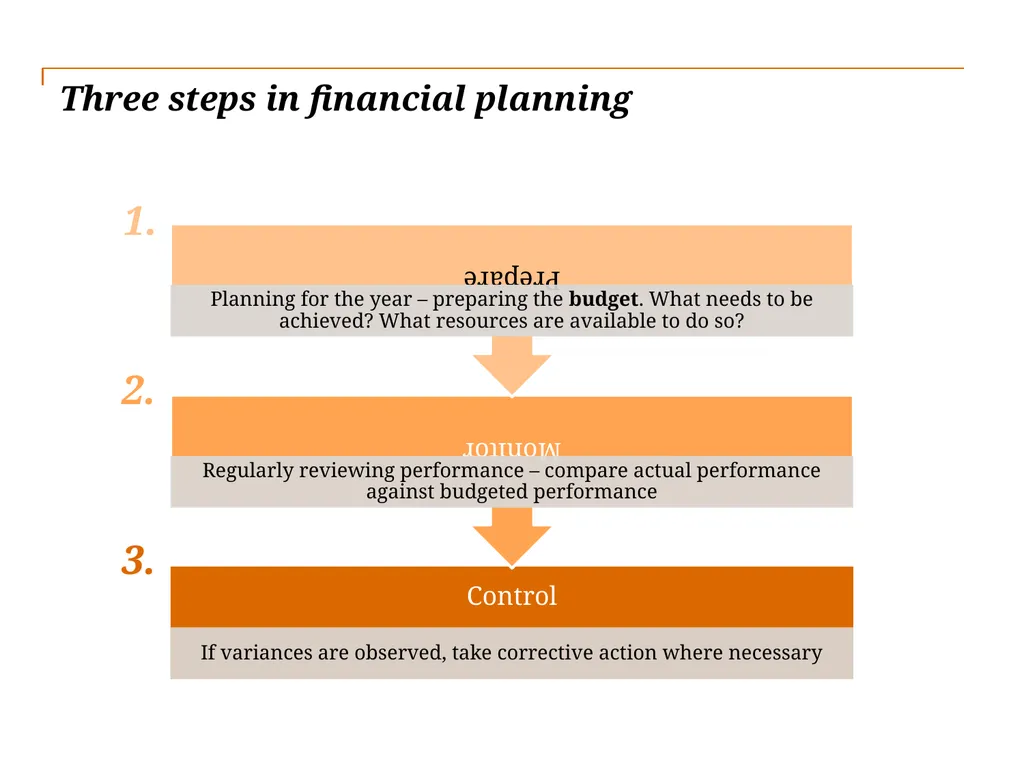
slide11. Three steps in financial planning 1. 2. 3.<br>
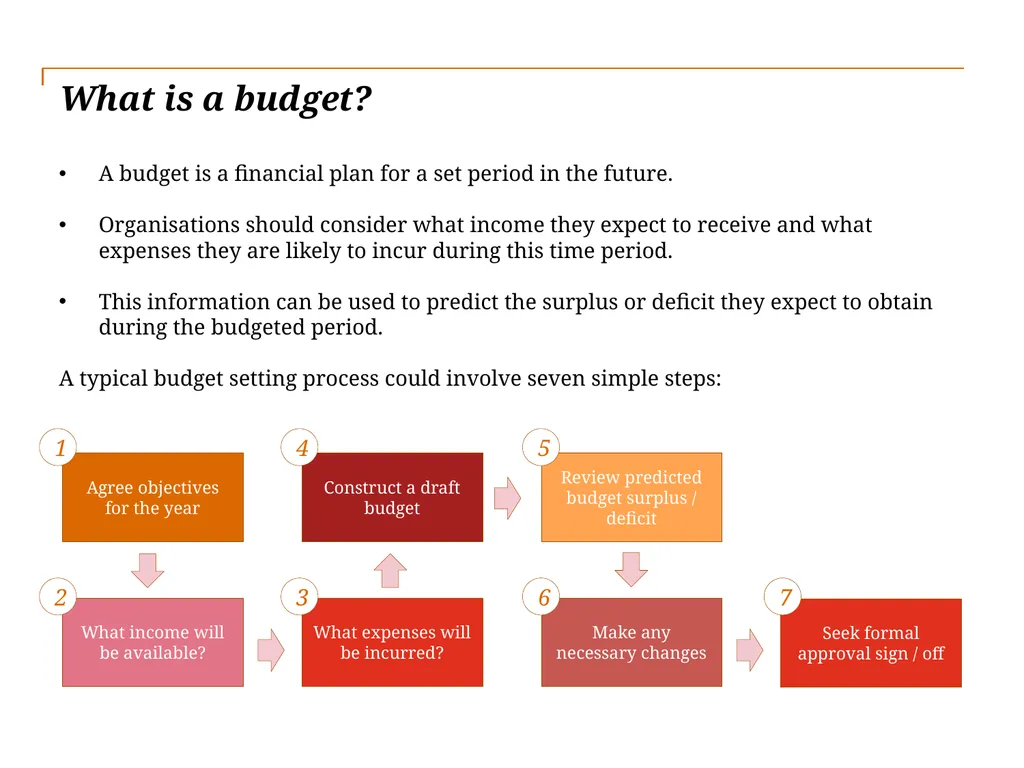
slide12. What is a budget? A budget is a financial plan for a set period in the future.
Organisations should consider what income they expect to receive and what expenses they are likely to incur during this time period.
This information can be used to predict the surplus or deficit they expect to obtain during the budgeted period.
A typical budget setting process could involve seven simple steps: Agree objectives for the year What income will be available? What expenses will be incurred? Construct a draft budget Review predicted budget surplus / deficit Make any necessary changes Seek formal approval sign / off 1 2 3 4 5 6 7<br>
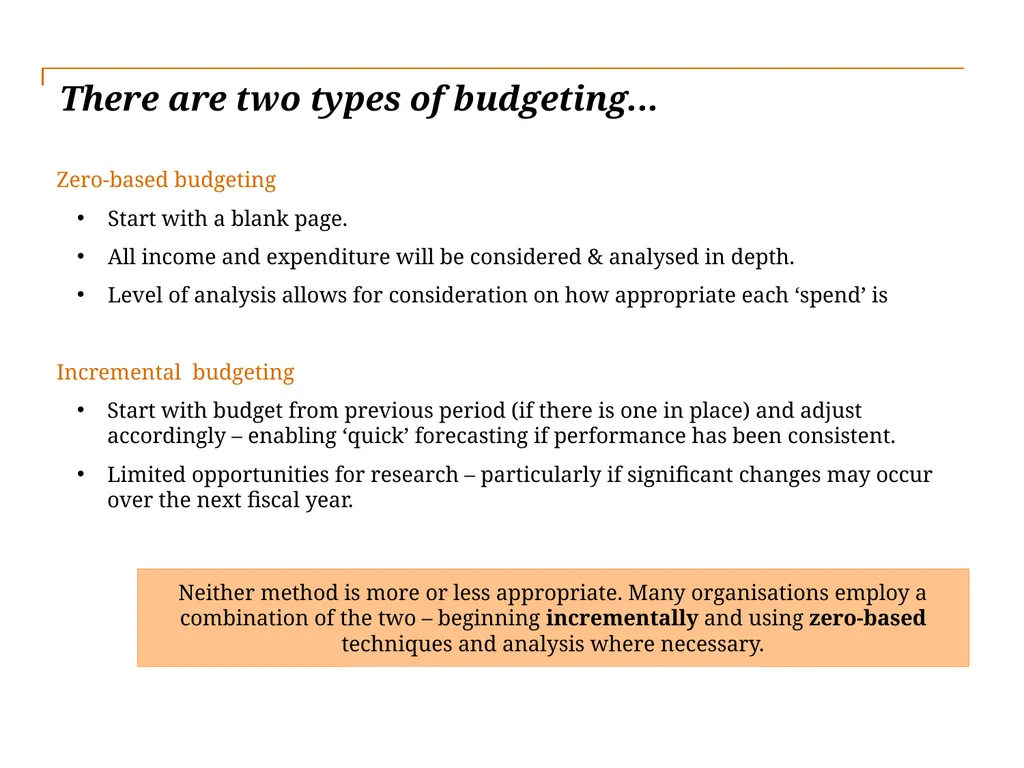
slide13. Neither method is more or less appropriate. Many organisations employ a combination of the two – beginning incrementally and using zero-based techniques and analysis where necessary. There are two types of budgeting... Zero-based budgeting
Start with a blank page.
All income and expenditure will be considered & analysed in depth.
Level of analysis allows for consideration on how appropriate each ‘spend’ is
Incremental budgeting
Start with budget from previous period (if there is one in place) and adjust accordingly – enabling ‘quick’ forecasting if performance has been consistent.
Limited opportunities for research – particularly if significant changes may occur over the next fiscal year.<br>
slide14. Before setting a budget... Look at financial statements from the previous budgeting period (usually 12 months)....
Consider income and expenditure from the previous 12 months (or length of budgeting period) – providing an idea of surplus / deficit that an organization can anticipate to generate
Split this information over the course of 12 months (or length of budgeting period) to anticipate when income is earned, and when expenses are incurred - depending on the nature of income or expenditure it might be split evenly over the year or associated with certain months
Remember that the surplus / deficit on an income & expenditure sheet will be the product of 12 months of cash flow – whilst a budget may incur either surplus or deficit from month-to-month, before reaching the end of the fiscal year.<br>
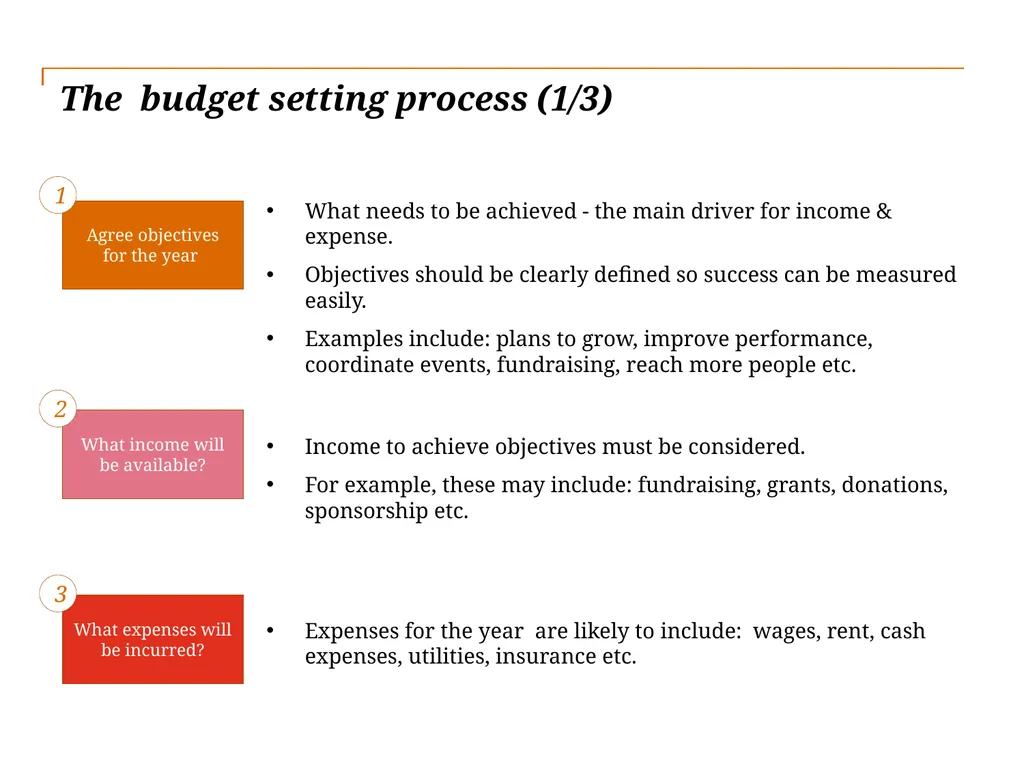
slide15. The budget setting process (1/3) What needs to be achieved - the main driver for income & expense.
Objectives should be clearly defined so success can be measured easily.
Examples include: plans to grow, improve performance, coordinate events, fundraising, reach more people etc.
Income to achieve objectives must be considered.
For example, these may include: fundraising, grants, donations, sponsorship etc.
Expenses for the year are likely to include: wages, rent, cash expenses, utilities, insurance etc. Agree objectives for the year 1 What income will be available? 2 What expenses will be incurred? 3<br>
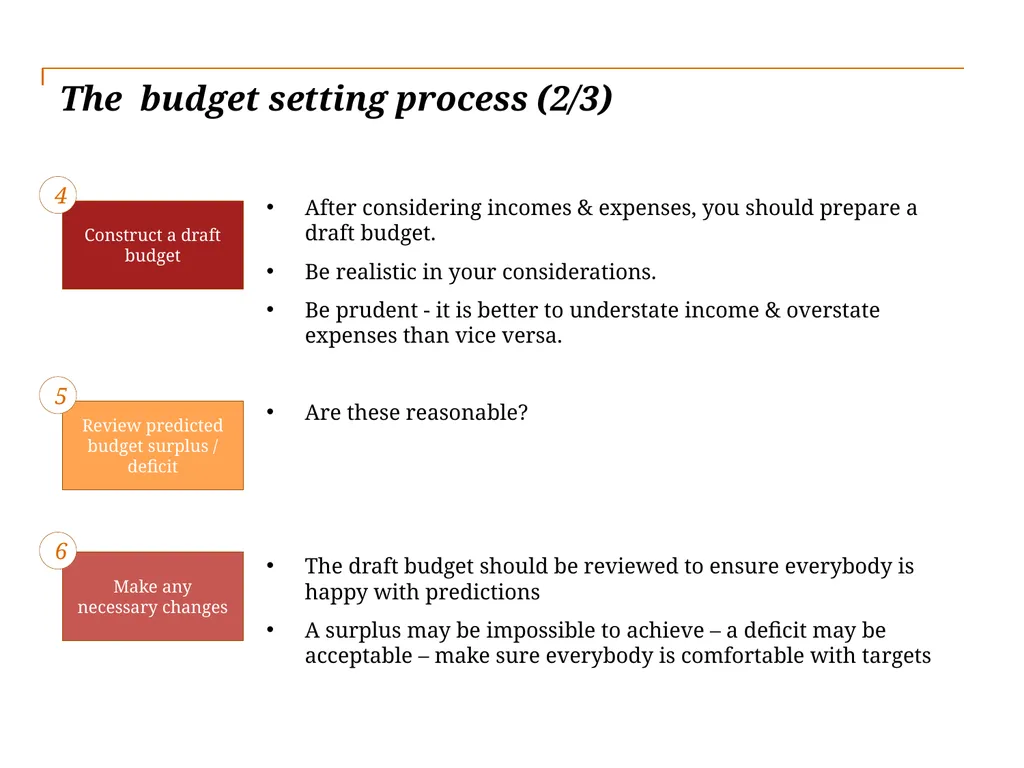
slide16. Construct a draft budget The budget setting process (2/3) After considering incomes & expenses, you should prepare a draft budget.
Be realistic in your considerations.
Be prudent - it is better to understate income & overstate expenses than vice versa.
Are these reasonable?
The draft budget should be reviewed to ensure everybody is happy with predictions
A surplus may be impossible to achieve – a deficit may be acceptable – make sure everybody is comfortable with targets 4 Review predicted budget surplus / deficit 5 Make any necessary changes 6<br>
slide17. Seek formal approval sign / off The budget setting process (3/3) Not only should the budget be approved, everyone should accept the expectations to work within in
Without this, objectives will not be effectively achieved 7<br>
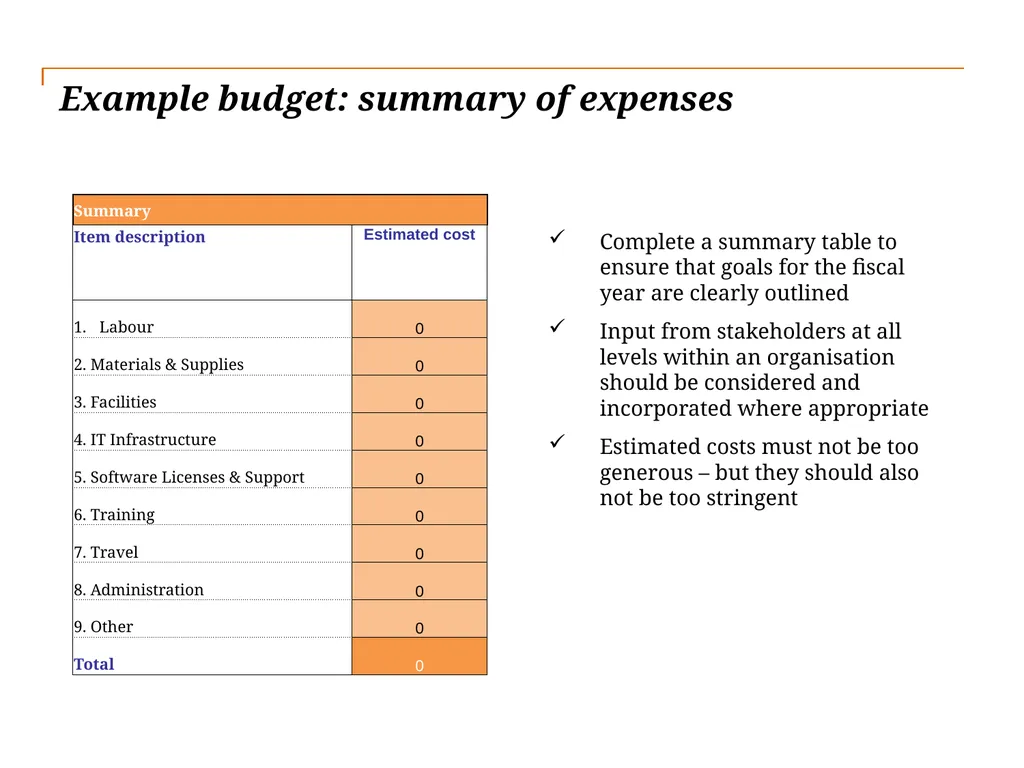
slide18. Example budget: summary of expenses Complete a summary table to ensure that goals for the fiscal year are clearly outlined
Input from stakeholders at all levels within an organisation should be considered and incorporated where appropriate
Estimated costs must not be too generous – but they should also not be too stringent<br>
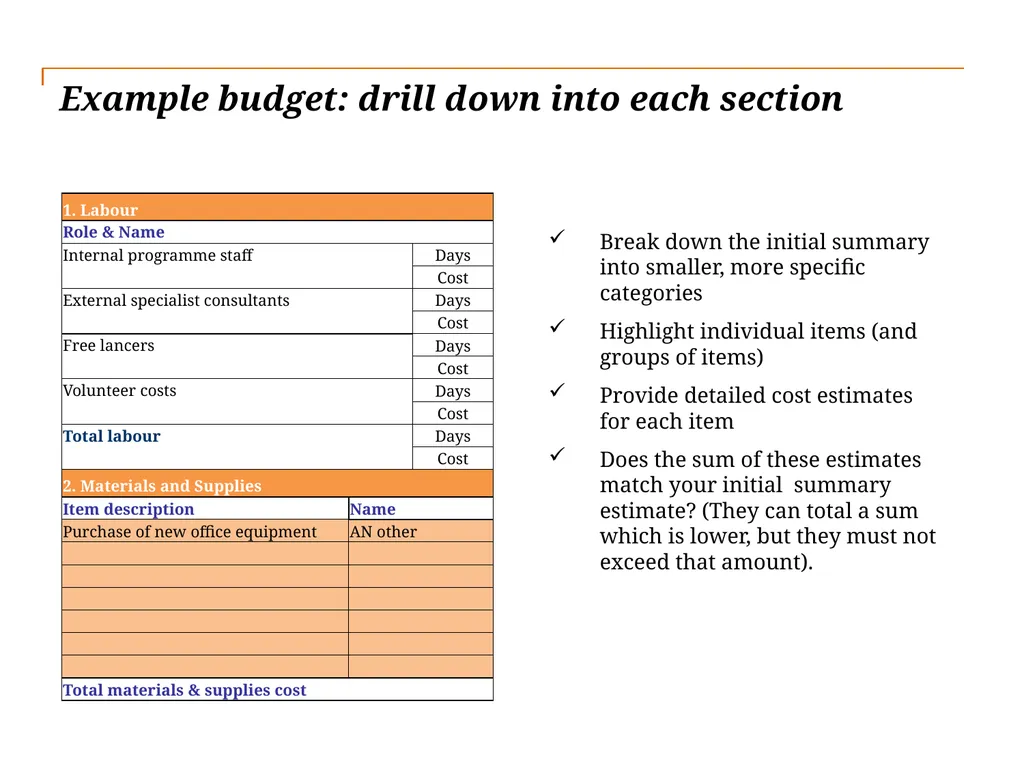
slide19. Example budget: drill down into each section Break down the initial summary into smaller, more specific categories
Highlight individual items (and groups of items)
Provide detailed cost estimates for each item
Does the sum of these estimates match your initial summary estimate? (They can total a sum which is lower, but they must not exceed that amount).<br>
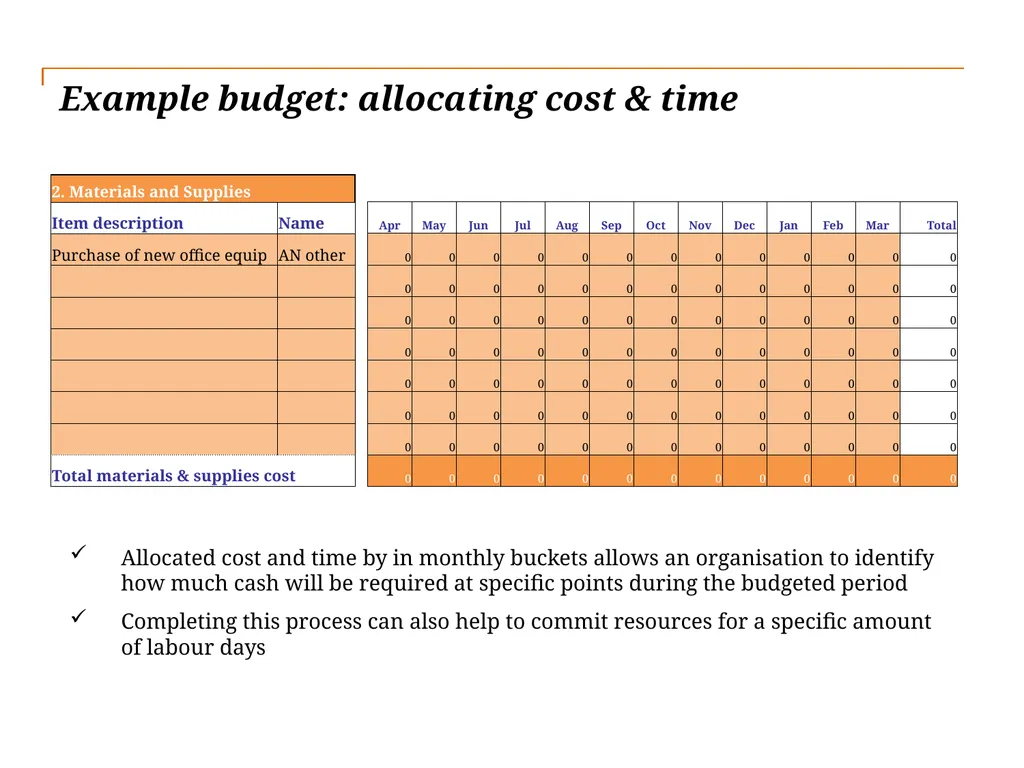
slide20. Example budget: allocating cost & time Allocated cost and time by in monthly buckets allows an organisation to identify how much cash will be required at specific points during the budgeted period
Completing this process can also help to commit resources for a specific amount of labour days<br>
slide21. Allocating time – staffing projections Staffing projections should be recorded – these can be recorded on a daily basis so all work is accountable
Projections can be based upon work which has happened previously – how many hours were required from how many members of staff to see a project through to completion?
Work around these estimates rather than on an ad-hoc basis – this will ensure an organization remains within budget<br>
slide22. Monitoring a budget Having set a budget, it is crucial to check actual performance against budgeted performance...
Ideally, an organisation should review actual performance against budget on a monthly basis
Monitoring must happen in a timely manner to ensure it is not too late to take corrective action
Comparison of actual performance against budgeted performance is known as variance analysis
In the instance of a one off event, or embarking on a capital project that has its own individual budget it will require more regular monitoring
Upon identifying instances where actual performance does not meet budgeted performance, an organisation must investigate the reasons for these variances, and take action<br>
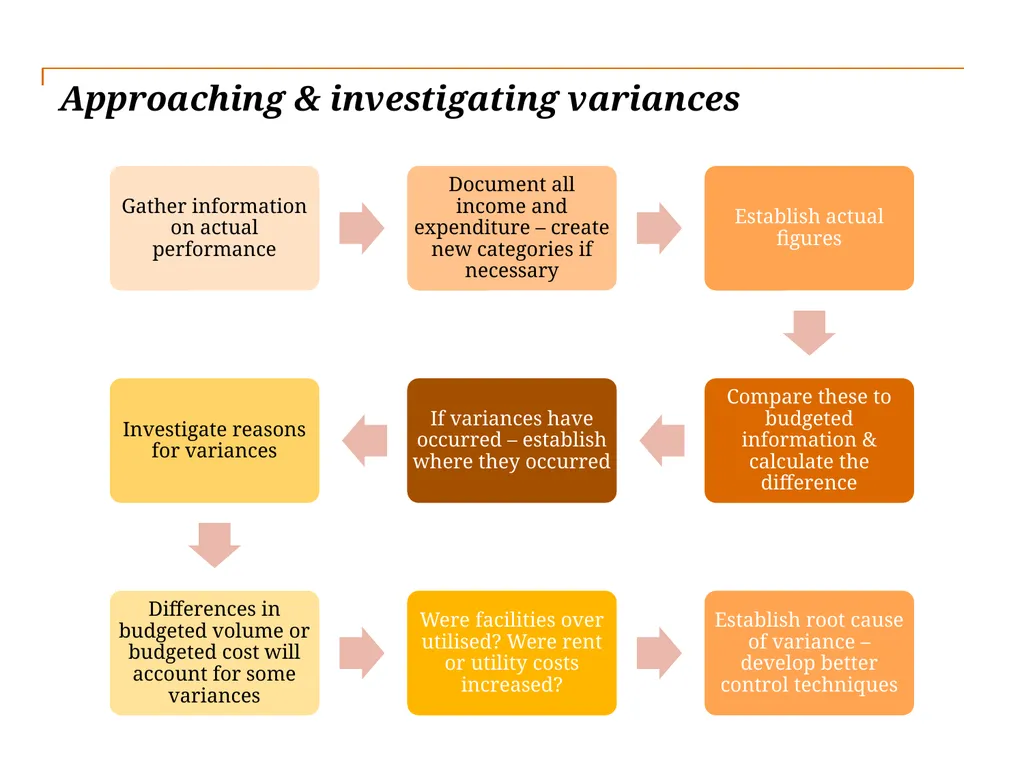
slide23. Approaching & investigating variances<br>
slide24. 10 things to remember for successful budgeting... Involve as many people as possible in the budget setting process
Allow sufficient time to complete the budget setting process
Look ahead when budgeting – don’t base it entirely on the last 12 months
Make budgeting a continuous process
Learn from previous mistakes – don’t be detracted by them
Use internal knowledge to make the budget as robust as possible
Be willing to challenge previous practise
Regularly review actual performance against budgeted performance
Partner positive & negative variances with an explanation
Ensure that key parties understand what is happening at every stage<br>
slide25. This publication has been prepared for general guidance on matters of interest only, and does not constitute professional advice. You should not act upon the information contained in this publication without obtaining specific professional advice. No representation or warranty (express or implied) is given as to the accuracy or completeness of the information contained in this publication, and, to the extent permitted by law, PricewaterhouseCoopers LLP, its members, employees and agents do not accept or assume any liability, responsibility or duty of care for any consequences of you or anyone else acting, or refraining to act, in reliance on the information contained in this publication or for any decision based on it.
© 2013 PricewaterhouseCoopers LLP. All rights reserved. In this document, “PwC” refers to PricewaterhouseCoopers LLP (a limited liability partnership in the United Kingdom) which is a member firm of PricewaterhouseCoopers International Limited, each member firm of which is a separate legal entity.<br>
slide2. What is financial management? Financial management can be defined as managing the finances of an organisation in order to achieve financial and strategic objectives. Done effectively, this should include a view of the past and a plan for the future...
Financial statements and reports are backward looking, summarising income and expenditure over a certain period of time.
Financial planning and budgeting is forward looking, forecasting what is going to happen and what resources will be required in the future. 2<br>
slide3. Why is financial management important? 3 Make optimum use of their money to achieve maximum returns. Understand if they have the resources to meet their objectives. Identify short term financial issues and address them as early as possible. Express their intentions, and explain what resources are required to achieve them. Inform all levels of the organisation about what needs to be achieved, and the resources available for doing so. Financial management helps organisations to...<br>
slide4. Financial statements<br>
slide5. Income and expenditure statement An income and expenditure account should only contain information regarding cash flow: money in and money out.
It provides a summary of income and expenditure over a specified time (usually one year).
It includes only revenue items.
The balance at the end shows the net operating result in the form of surplus (i.e. excess of income over expenditure) or deficit (i.e. excess of expenditure over income), which is transferred to the capital fund shown in the balance sheet. 5 In Out Cash inflows...
payments into an organisation from members or other sources Cash outflows...
payments made by an organisation<br>
slide6. Example: income and expenditure statement 6 It should refer to a specified period (usually 12 months). Different ‘types’ of income should be listed in the left hand column. There are no rules around what these categories can be - you may find it easier to have lots of different categories or you might wish to to group similar items under one heading. Expenses are then listed – categorised appropriately. Income minus expenses gives a net surplus (if income has been greater than expenses) or deficit (if expenses were greater than income). The net figure is stated before tax and after tax.
NB: tax exemptions may differ in accordance with location of operation - contact local charity commission and / or HMRC for further details.<br>
slide7. Balance sheet An organisation’s balance sheet is a snapshot of assets and liabilities and gives a view financial health at a specific point in time.
An organisation should ideally have more assets than liabilities - similar to the income and expenditure account.
A version of the balance sheet should be presented at monthly meetings to ensure that financial performance is being monitored. 7<br>
slide8. Example: balance sheet 8 Assets are listed at the top of the balance sheet grouped into fixed and current assets.
Current assets are cash or assets which are readily convertible to cash. Current liabilities are amounts that are due in the short term. The difference between the two gives us a quick measure of how well an organisation is doing Total liabilities are deducted from total assets to give the net asset figure. Reserves show what investment has been made into an organisation. Reserves are not a pot of cash. They are calculated by taking last year’s closing balance and adjusting for this year’s surplus or deficit.<br>
slide9. Financial planning<br>
slide10. Why is financial planning important? Financial statements (balance sheet, income and expenditure account) give a historic view of an organisation, but another source of financial information is necessary – budgeting and planning.
Financial planning is essential because...
Organisations need to consider what is likely to happen during the fiscal year, and plan accordingly.
It is too late to discover at the end of the year that income was not sufficient to meet expenditure.
There is no legal requirement to prepare financial plans (budgets), and no specific format that these plans should take. It is important for an organisation to choose a process that works for them, and allows them to obtain relevant information.
Financial plans should not be too easily achieved, but also must not be too ambitious. This can be a difficult balance to achieve – the must remain realistic.<br>
slide11. Three steps in financial planning 1. 2. 3.<br>
slide12. What is a budget? A budget is a financial plan for a set period in the future.
Organisations should consider what income they expect to receive and what expenses they are likely to incur during this time period.
This information can be used to predict the surplus or deficit they expect to obtain during the budgeted period.
A typical budget setting process could involve seven simple steps: Agree objectives for the year What income will be available? What expenses will be incurred? Construct a draft budget Review predicted budget surplus / deficit Make any necessary changes Seek formal approval sign / off 1 2 3 4 5 6 7<br>
slide13. Neither method is more or less appropriate. Many organisations employ a combination of the two – beginning incrementally and using zero-based techniques and analysis where necessary. There are two types of budgeting... Zero-based budgeting
Start with a blank page.
All income and expenditure will be considered & analysed in depth.
Level of analysis allows for consideration on how appropriate each ‘spend’ is
Incremental budgeting
Start with budget from previous period (if there is one in place) and adjust accordingly – enabling ‘quick’ forecasting if performance has been consistent.
Limited opportunities for research – particularly if significant changes may occur over the next fiscal year.<br>
slide14. Before setting a budget... Look at financial statements from the previous budgeting period (usually 12 months)....
Consider income and expenditure from the previous 12 months (or length of budgeting period) – providing an idea of surplus / deficit that an organization can anticipate to generate
Split this information over the course of 12 months (or length of budgeting period) to anticipate when income is earned, and when expenses are incurred - depending on the nature of income or expenditure it might be split evenly over the year or associated with certain months
Remember that the surplus / deficit on an income & expenditure sheet will be the product of 12 months of cash flow – whilst a budget may incur either surplus or deficit from month-to-month, before reaching the end of the fiscal year.<br>
slide15. The budget setting process (1/3) What needs to be achieved - the main driver for income & expense.
Objectives should be clearly defined so success can be measured easily.
Examples include: plans to grow, improve performance, coordinate events, fundraising, reach more people etc.
Income to achieve objectives must be considered.
For example, these may include: fundraising, grants, donations, sponsorship etc.
Expenses for the year are likely to include: wages, rent, cash expenses, utilities, insurance etc. Agree objectives for the year 1 What income will be available? 2 What expenses will be incurred? 3<br>
slide16. Construct a draft budget The budget setting process (2/3) After considering incomes & expenses, you should prepare a draft budget.
Be realistic in your considerations.
Be prudent - it is better to understate income & overstate expenses than vice versa.
Are these reasonable?
The draft budget should be reviewed to ensure everybody is happy with predictions
A surplus may be impossible to achieve – a deficit may be acceptable – make sure everybody is comfortable with targets 4 Review predicted budget surplus / deficit 5 Make any necessary changes 6<br>
slide17. Seek formal approval sign / off The budget setting process (3/3) Not only should the budget be approved, everyone should accept the expectations to work within in
Without this, objectives will not be effectively achieved 7<br>
slide18. Example budget: summary of expenses Complete a summary table to ensure that goals for the fiscal year are clearly outlined
Input from stakeholders at all levels within an organisation should be considered and incorporated where appropriate
Estimated costs must not be too generous – but they should also not be too stringent<br>
slide19. Example budget: drill down into each section Break down the initial summary into smaller, more specific categories
Highlight individual items (and groups of items)
Provide detailed cost estimates for each item
Does the sum of these estimates match your initial summary estimate? (They can total a sum which is lower, but they must not exceed that amount).<br>
slide20. Example budget: allocating cost & time Allocated cost and time by in monthly buckets allows an organisation to identify how much cash will be required at specific points during the budgeted period
Completing this process can also help to commit resources for a specific amount of labour days<br>
slide21. Allocating time – staffing projections Staffing projections should be recorded – these can be recorded on a daily basis so all work is accountable
Projections can be based upon work which has happened previously – how many hours were required from how many members of staff to see a project through to completion?
Work around these estimates rather than on an ad-hoc basis – this will ensure an organization remains within budget<br>
slide22. Monitoring a budget Having set a budget, it is crucial to check actual performance against budgeted performance...
Ideally, an organisation should review actual performance against budget on a monthly basis
Monitoring must happen in a timely manner to ensure it is not too late to take corrective action
Comparison of actual performance against budgeted performance is known as variance analysis
In the instance of a one off event, or embarking on a capital project that has its own individual budget it will require more regular monitoring
Upon identifying instances where actual performance does not meet budgeted performance, an organisation must investigate the reasons for these variances, and take action<br>
slide23. Approaching & investigating variances<br>
slide24. 10 things to remember for successful budgeting... Involve as many people as possible in the budget setting process
Allow sufficient time to complete the budget setting process
Look ahead when budgeting – don’t base it entirely on the last 12 months
Make budgeting a continuous process
Learn from previous mistakes – don’t be detracted by them
Use internal knowledge to make the budget as robust as possible
Be willing to challenge previous practise
Regularly review actual performance against budgeted performance
Partner positive & negative variances with an explanation
Ensure that key parties understand what is happening at every stage<br>
slide25. This publication has been prepared for general guidance on matters of interest only, and does not constitute professional advice. You should not act upon the information contained in this publication without obtaining specific professional advice. No representation or warranty (express or implied) is given as to the accuracy or completeness of the information contained in this publication, and, to the extent permitted by law, PricewaterhouseCoopers LLP, its members, employees and agents do not accept or assume any liability, responsibility or duty of care for any consequences of you or anyone else acting, or refraining to act, in reliance on the information contained in this publication or for any decision based on it.
© 2013 PricewaterhouseCoopers LLP. All rights reserved. In this document, “PwC” refers to PricewaterhouseCoopers LLP (a limited liability partnership in the United Kingdom) which is a member firm of PricewaterhouseCoopers International Limited, each member firm of which is a separate legal entity.<br>