
P.R.I.M.E. Finance Panel of Recognized

Description: P.R.I.M.E. Finance Panel of Recognized International Market Experts in Finance Predictive Trends in Financial Market Disputes Disputes on the Horizon: Predictive Trends in Financial Market Disputes P.R.I.M.E. Finance New York Conference
Related Topics
Download Presentation
"P.R.I.M.E. Finance Panel of Recognized" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. P.R.I.M.E. Finance
Panel of Recognized International Market Experts in Finance
Predictive Trends in Financial Market Disputes Disputes on the Horizon: Predictive Trends in Financial Market Disputes
P.R.I.M.E. Finance New York Conference 2019
17 October 2019, New York<br>
slide2. Trends in Sovereign Debt Disputes Carolyn B. Lamm<br>
slide3. International Multiparty Claims: Inevitable Effect of Globalization Along with the globalization of business streams, the IBA Legal Practice Division recognized in 2008 as “inevitable that … the group of possible claimants who have similar claims may cross borders”
“Multi-jurisdictional collective redress actions involving claimants and defendants from different countries and legal regimes are inevitable as parties press for broader, and perhaps global, resolutions of collective redress claims.” IBA Legal Practice Division, Guidelines for Recognising and Enforcing Foreign Judgments for Collective Redress ¶¶ 4, 13 (2008) © 2019 White & Case LLP<br>
slide4. Trends Favoring Collective Redress Increased availability of collective redress procedures in national courts
Class actions in the U.S.
Various other forms of representative or group actions recently introduced in national legislation of other countries
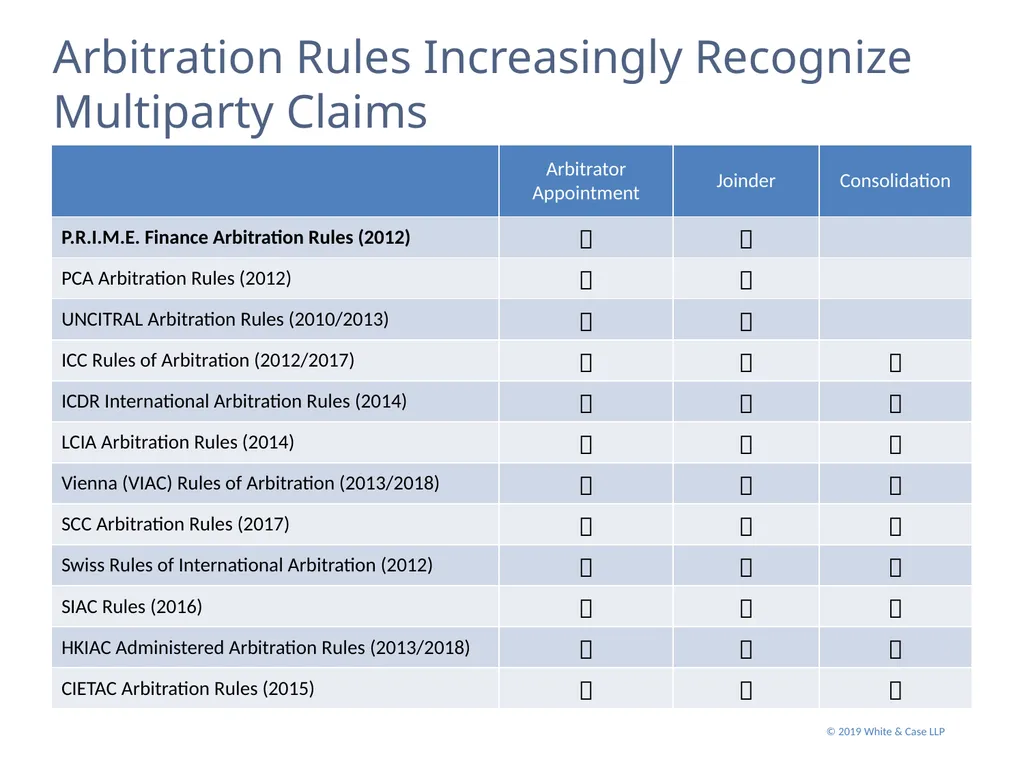
Increased recognition of multiparty claims in international arbitration rules
Including under certain investment treaties
Increased availability of third-party funding<br>
slide5. Arbitration Rules Increasingly Recognize Multiparty Claims © 2019 White & Case LLP<br>
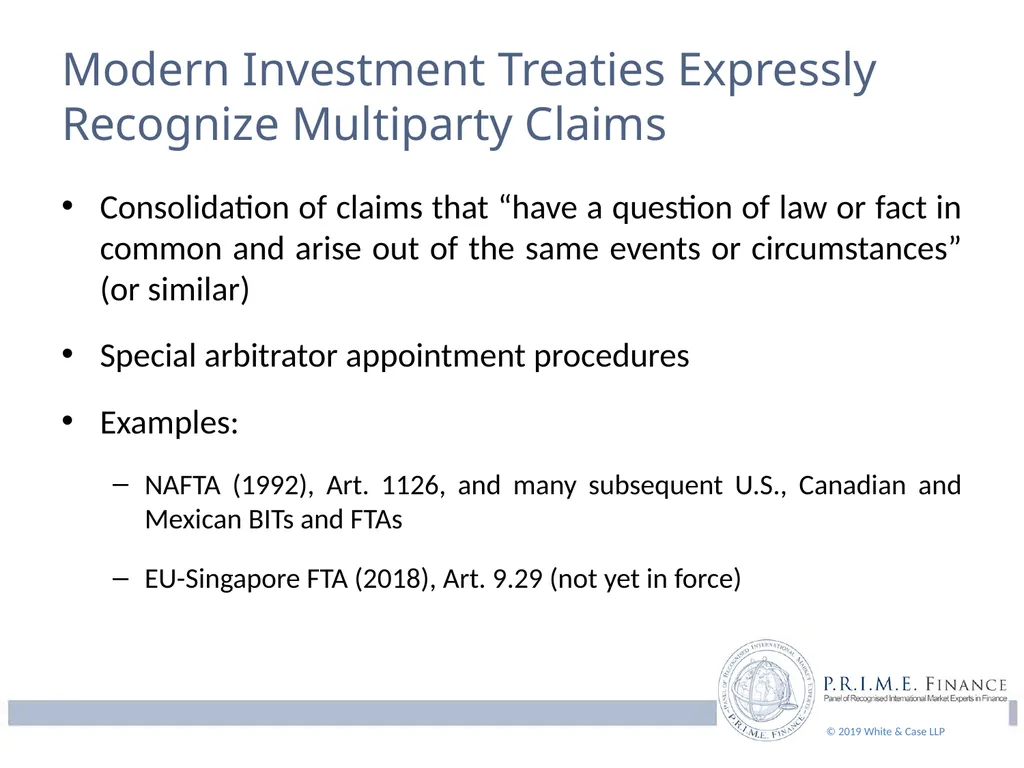
slide6. Modern Investment Treaties Expressly Recognize Multiparty Claims Consolidation of claims that “have a question of law or fact in common and arise out of the same events or circumstances” (or similar)
Special arbitrator appointment procedures
Examples:
NAFTA (1992), Art. 1126, and many subsequent U.S., Canadian and Mexican BITs and FTAs
EU-Singapore FTA (2018), Art. 9.29 (not yet in force) © 2019 White & Case LLP<br>
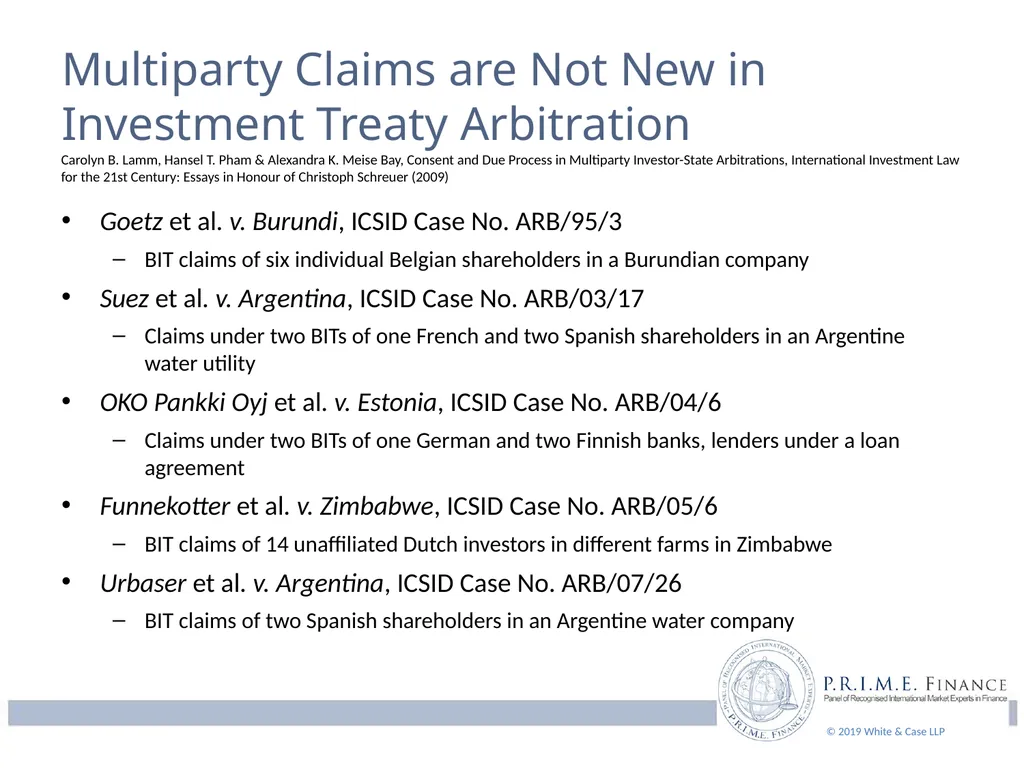
slide7. Multiparty Claims are Not New in Investment Treaty Arbitration Goetz et al. v. Burundi, ICSID Case No. ARB/95/3
BIT claims of six individual Belgian shareholders in a Burundian company
Suez et al. v. Argentina, ICSID Case No. ARB/03/17
Claims under two BITs of one French and two Spanish shareholders in an Argentine water utility
OKO Pankki Oyj et al. v. Estonia, ICSID Case No. ARB/04/6
Claims under two BITs of one German and two Finnish banks, lenders under a loan agreement
Funnekotter et al. v. Zimbabwe, ICSID Case No. ARB/05/6
BIT claims of 14 unaffiliated Dutch investors in different farms in Zimbabwe
Urbaser et al. v. Argentina, ICSID Case No. ARB/07/26
BIT claims of two Spanish shareholders in an Argentine water company Carolyn B. Lamm, Hansel T. Pham & Alexandra K. Meise Bay, Consent and Due Process in Multiparty Investor-State Arbitrations, International Investment Law for the 21st Century: Essays in Honour of Christoph Schreuer (2009) © 2019 White & Case LLP<br>
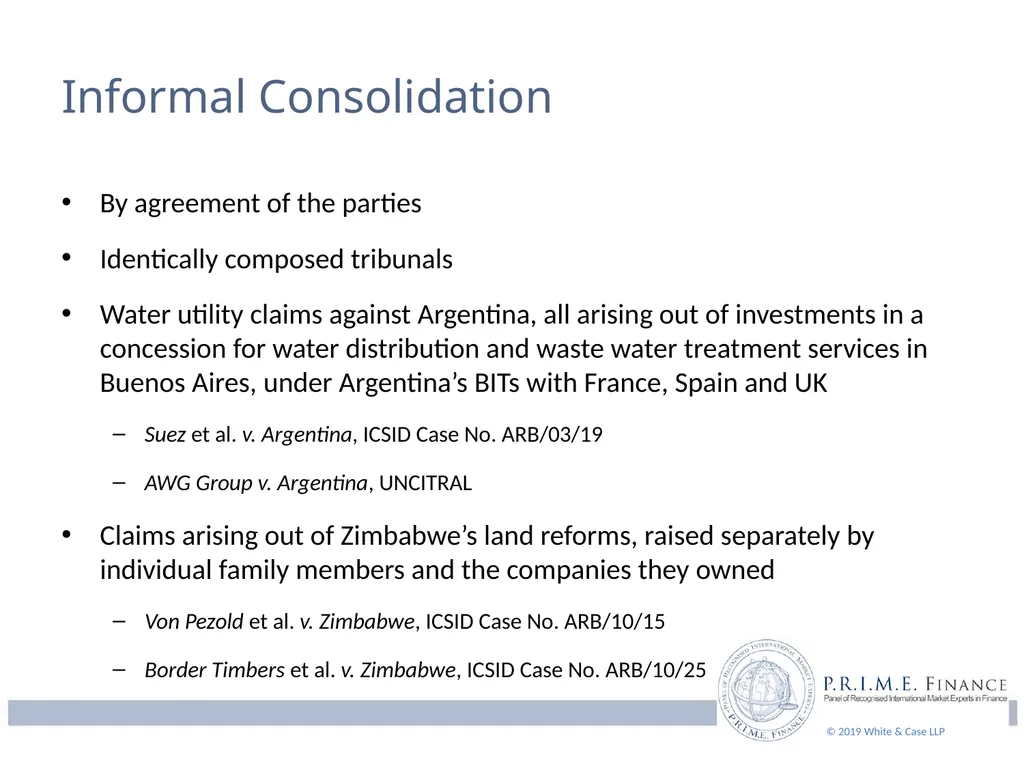
slide8. Informal Consolidation By agreement of the parties
Identically composed tribunals
Water utility claims against Argentina, all arising out of investments in a concession for water distribution and waste water treatment services in Buenos Aires, under Argentina’s BITs with France, Spain and UK
Suez et al. v. Argentina, ICSID Case No. ARB/03/19
AWG Group v. Argentina, UNCITRAL
Claims arising out of Zimbabwe’s land reforms, raised separately by individual family members and the companies they owned
Von Pezold et al. v. Zimbabwe, ICSID Case No. ARB/10/15
Border Timbers et al. v. Zimbabwe, ICSID Case No. ARB/10/25 © 2019 White & Case LLP<br>
slide9. Financial Instruments Constitute Protected “Investments” under Most Investment Treaties Definitions of “Investment” in BITs and FTA Investment Chapters generally include financial instruments:
All assets invested in compliance with the law
Securities, bonds, debt instruments, and other instruments having economic value
Tribunals have found to constitute “investments”:
Loans, negotiable instruments, sovereign bonds, oil price hedges
Some treaties specifically exclude claims arising out of sovereign debt restructuring
Example: US-Uruguay BIT (2005), Annex G © 2019 White & Case LLP<br>
slide10. Argentine Sovereign Debt Dispute 130+ lawsuits in New York, USD 3.3 billion+
470+ lawsuits in Germany, EUR 106 million+
3 ICSID arbitrations based on Italy-Argentina BIT, led by Abaclat:
2 withdrawn after prevailing on jurisdiction (Ambiente and Alemanni)
Pursue treaty rights:
Claims for expropriation, lack of fair and equitable treatment, national treatment, most-favored nation treatment, unreasonable or discriminatory treatment
Total claims of approximately USD 2.5 billion
Preserve contractual rights under bonds issued under 7 different laws:
Group actions in U.S. federal court by Abaclat claimants, stayed pending arbitration
Prescription letters Abaclat et al. v. Argentine Republic, ICSID Case No. ARB/07/5, Decision on Jurisdiction and Admissibility (4 Aug. 2011) ¶ 82 See generally Carolyn B. Lamm, Eckhard R. Hellbeck and David P. Riesenberg, Theories of Liability and Responsibility, in International Financial Disputes – Arbitration and Mediation 241 (Jeffrey Golden and Carolyn B. Lamm, eds. 2015) © 2019 White & Case LLP<br>
slide11. Argentine Bond ICSID Arbitrations Abaclat et al. v. Argentina (2011)
60,000 individually-named Claimants – “mass” or “aggregate” claim
“Homogeneity” – common claim, common cause, and common injury formulation
Settled after merits hearing, having prevailed on jurisdiction and admissibility
Ambiente Ufficio et al. v. Argentina (2013)
Alemanni et al. v. Argentina (2014)
90 / 74 Claimants respectively – not “mass” claims
Both discontinued after prevailing on jurisdiction and admissibility Abaclat et al. v. Argentine Republic, ICSID Case No. ARB/07/5, Decision on Jurisdiction and Admissibility (4 Aug. 2011) ¶ 485 Ambiente Ufficio S.p.A. et al. v. Argentine Republic, ICSID Case No. ARB/08/9, Decision on Jurisdiction and Admissibility (8 Feb. 2013) ¶¶ 114, 116, 120, 230 Giovanni Alemanni et al. v. Argentine Republic, ICSID Case No. ARB/07/8, Decision on Jurisdiction and Admissibility (17 Nov. 2014) ¶ 267 © 2019 White & Case LLP<br>
slide12. Other Debt Instrument-Related Multiparty Arbitrations Based on Treaties Anderson et al. v. Costa Rica
Claimants: 137 individually-named Canadian nationals, alleged victims of a USD 405 million Ponzi scheme orchestrated by Villalobos brothers in Costa Rica
Claims under Canada-Costa Rica BIT alleging that Costa Rica failed to provide proper vigilance and regulatory supervision over the national financial system, and thereby violated BIT protections re: full protection and security, fair and equitable treatment, due process of law, and expropriation
Tribunal dismissed the claims finding that the deposit transactions violated Costa Rican law, thus the assets could not be considered as "investments" under the BIT Alasdair Ross Anderson et al v. Republic of Costa Rica, ICSID Case No. ARB(AF)/07/3, Award (19 May 2010) ¶¶ 15-16, 57-59, 65 © 2019 White & Case LLP<br>
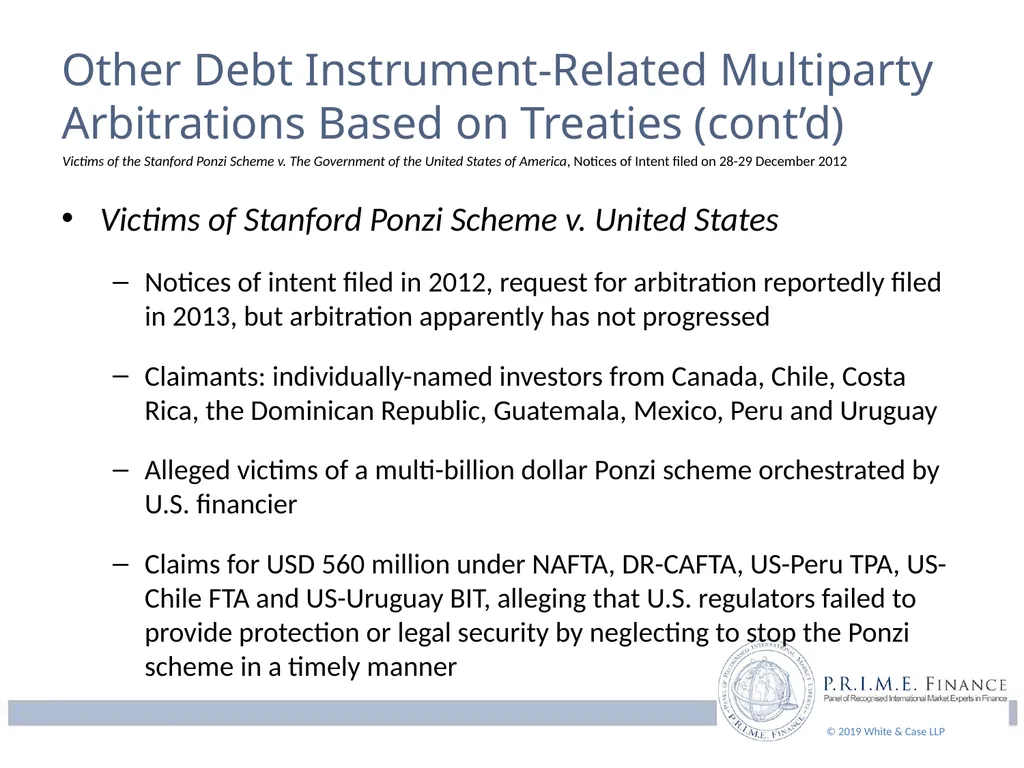
slide13. Other Debt Instrument-Related Multiparty Arbitrations Based on Treaties (cont’d) Victims of Stanford Ponzi Scheme v. United States
Notices of intent filed in 2012, request for arbitration reportedly filed in 2013, but arbitration apparently has not progressed
Claimants: individually-named investors from Canada, Chile, Costa Rica, the Dominican Republic, Guatemala, Mexico, Peru and Uruguay
Alleged victims of a multi-billion dollar Ponzi scheme orchestrated by U.S. financier
Claims for USD 560 million under NAFTA, DR-CAFTA, US-Peru TPA, US-Chile FTA and US-Uruguay BIT, alleging that U.S. regulators failed to provide protection or legal security by neglecting to stop the Ponzi scheme in a timely manner Victims of the Stanford Ponzi Scheme v. The Government of the United States of America, Notices of Intent filed on 28-29 December 2012 © 2019 White & Case LLP<br>
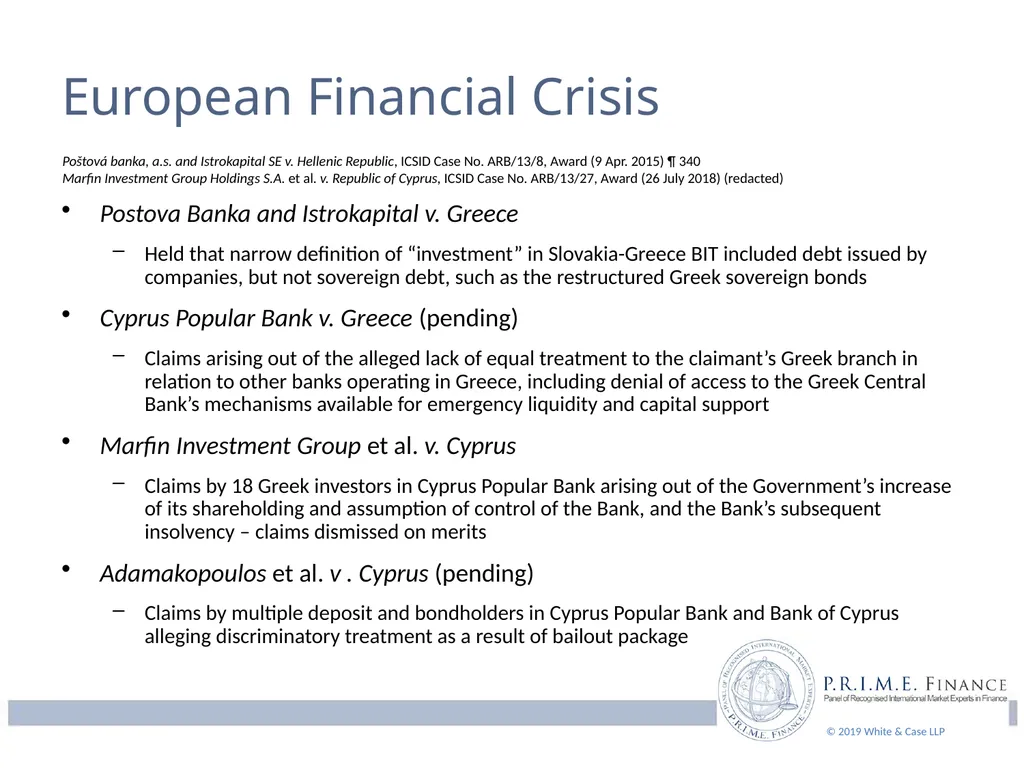
slide14. European Financial Crisis Postova Banka and Istrokapital v. Greece
Held that narrow definition of “investment” in Slovakia-Greece BIT included debt issued by companies, but not sovereign debt, such as the restructured Greek sovereign bonds
Cyprus Popular Bank v. Greece (pending)
Claims arising out of the alleged lack of equal treatment to the claimant’s Greek branch in relation to other banks operating in Greece, including denial of access to the Greek Central Bank’s mechanisms available for emergency liquidity and capital support
Marfin Investment Group et al. v. Cyprus
Claims by 18 Greek investors in Cyprus Popular Bank arising out of the Government’s increase of its shareholding and assumption of control of the Bank, and the Bank’s subsequent insolvency – claims dismissed on merits
Adamakopoulos et al. v . Cyprus (pending)
Claims by multiple deposit and bondholders in Cyprus Popular Bank and Bank of Cyprus alleging discriminatory treatment as a result of bailout package Poštová banka, a.s. and Istrokapital SE v. Hellenic Republic, ICSID Case No. ARB/13/8, Award (9 Apr. 2015) ¶ 340
Marfin Investment Group Holdings S.A. et al. v. Republic of Cyprus, ICSID Case No. ARB/13/27, Award (26 July 2018) (redacted) © 2019 White & Case LLP<br>
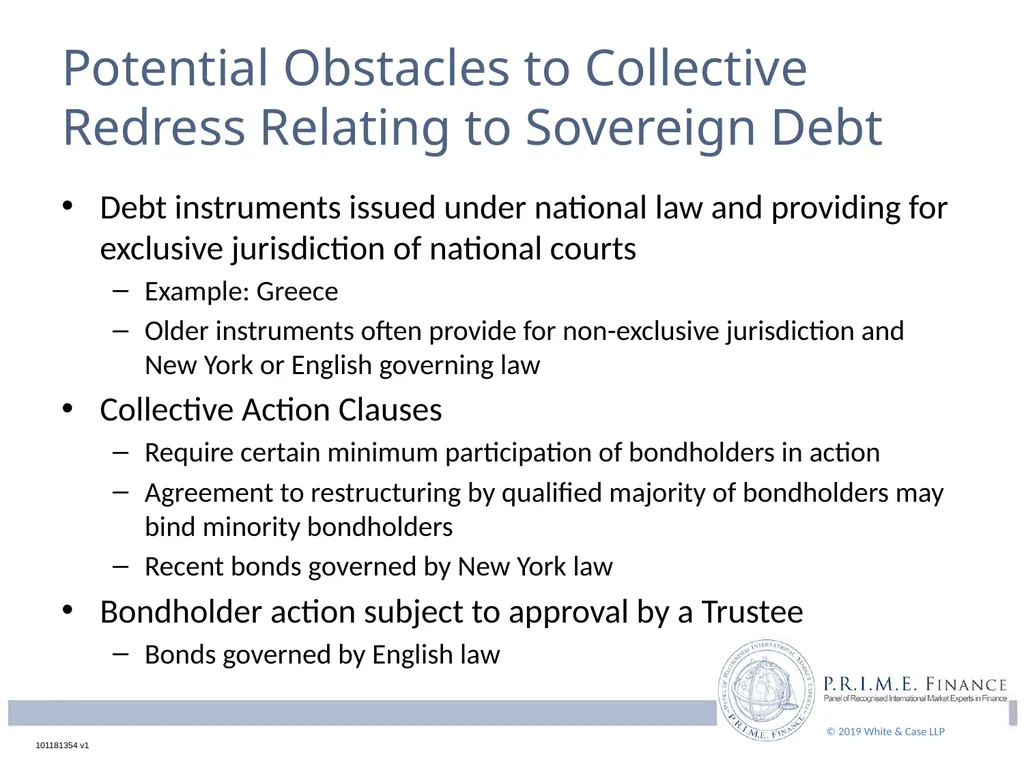
slide15. Potential Obstacles to Collective Redress Relating to Sovereign Debt Debt instruments issued under national law and providing for exclusive jurisdiction of national courts
Example: Greece
Older instruments often provide for non-exclusive jurisdiction and New York or English governing law
Collective Action Clauses
Require certain minimum participation of bondholders in action
Agreement to restructuring by qualified majority of bondholders may bind minority bondholders
Recent bonds governed by New York law
Bondholder action subject to approval by a Trustee
Bonds governed by English law © 2019 White & Case LLP 101181354 v1<br>
slide16. Predictive Trends in Europe Professor Pim Rank<br>
slide17. Predictive Trends in Europe Coloring of the civil law duty of care of banks by caretaking duties based on public law
Extension of the civil law duty of care of banks from retail clients to professional clients
Extension of the civil law duty of care of banks from clients to third parties
More frequent intervention by regulatory authorities with respect to products or conduct that are legally compliant but considered improper<br>
slide18. Coloring by the courts of the civil law duty of care of banks by caretaking duties based on public law:
In most jurisdictions in Europe, it is established case law that banks have a special civil law duty of care towards their clients due to their function in society and the fiduciary relationship between the bank and the client
Over the past few years a wide range of public legislation has been introduced in Europe aimed at the protection of clients of banks and containing detailed caretaking duties
Public law caretaking duties may be ‘read in’ in the contractual relationship between the bank and the client and ‘color’ it
Interaction between both sets of rules is heavily debated<br>
slide19. Extension by the courts of the special civil law duty of care of banks from retail clients to professional clients:
Although a bank must always act in accordance with its duty of care, irrespective of whether the client is a consumer or a professional party, this duty of care is less far-reaching where the client is a professional
What we are now seeing is that as a result of the present market conditions and the global financial crisis, courts are shifting to assuming more stringent protection for professional parties
This applies in particular to small businesses and public sector parties such as housing corporations<br>
slide20. Extension by the courts of the special civil law duty of care of banks from clients to third parties:
Under Dutch law a bank has a duty of care not only to its clients but also, under certain circumstances, to third parties.
It follows from the Safe Haven judgement of the Dutch Supreme Court that when a bank becomes aware of possible criminal activities on the part of a client, the bank may be required to carry out an investigation and take appropriate measures, at the risk of incurring liability towards third parties for failing to do so.
The Safe Haven judgment was recently confirmed and is likely to be followed by courts in other jurisdictions<br>
slide21. More frequent intervention by regulatory authorities, without a sound legal basis, with respect to certain products or conduct considered improper by such regulatory authorities:
A review by regulators of a product or service used to be limited to determining whether it complied with the legal requirements
However, more and more regulators tend to consider the economic merits of the product and service as well and to take action if they consider the product or service improper or undesirable from an economic point of view
This attitude of regulatory authorities undermines their legitimacy and makes it difficult for banks to assess whether their products and services are legally compliant<br>
slide22. Predictive Trends in US Litigation Jayant W. Tambe
Pleading Tactics: “Blinded me with science”<br>
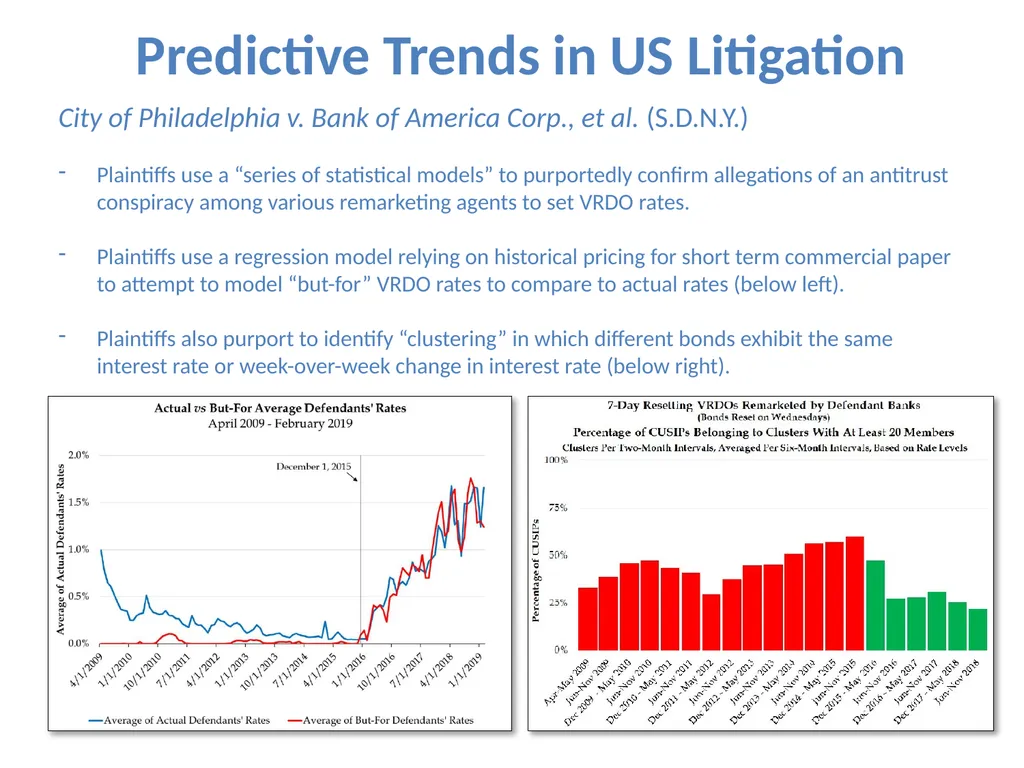
slide23. City of Philadelphia v. Bank of America Corp., et al. (S.D.N.Y.)
Plaintiffs use a “series of statistical models” to purportedly confirm allegations of an antitrust conspiracy among various remarketing agents to set VRDO rates.
Plaintiffs use a regression model relying on historical pricing for short term commercial paper to attempt to model “but-for” VRDO rates to compare to actual rates (below left).
Plaintiffs also purport to identify “clustering” in which different bonds exhibit the same interest rate or week-over-week change in interest rate (below right). Predictive Trends in US Litigation<br>
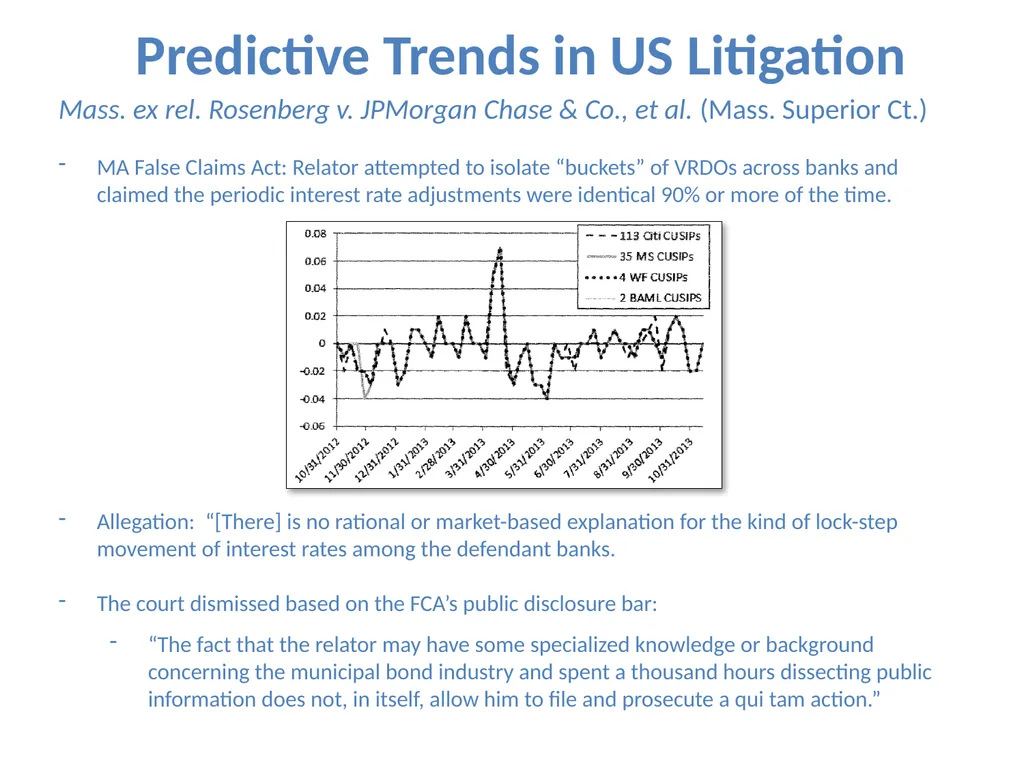
slide24. Mass. ex rel. Rosenberg v. JPMorgan Chase & Co., et al. (Mass. Superior Ct.)
MA False Claims Act: Relator attempted to isolate “buckets” of VRDOs across banks and claimed the periodic interest rate adjustments were identical 90% or more of the time.
Allegation: “[There] is no rational or market-based explanation for the kind of lock-step movement of interest rates among the defendant banks.
The court dismissed based on the FCA’s public disclosure bar:
“The fact that the relator may have some specialized knowledge or background concerning the municipal bond industry and spent a thousand hours dissecting public information does not, in itself, allow him to file and prosecute a qui tam action.” Predictive Trends in US Litigation<br>
slide25. In re GSE Bonds Antitrust Litigation (S.D.N.Y.)
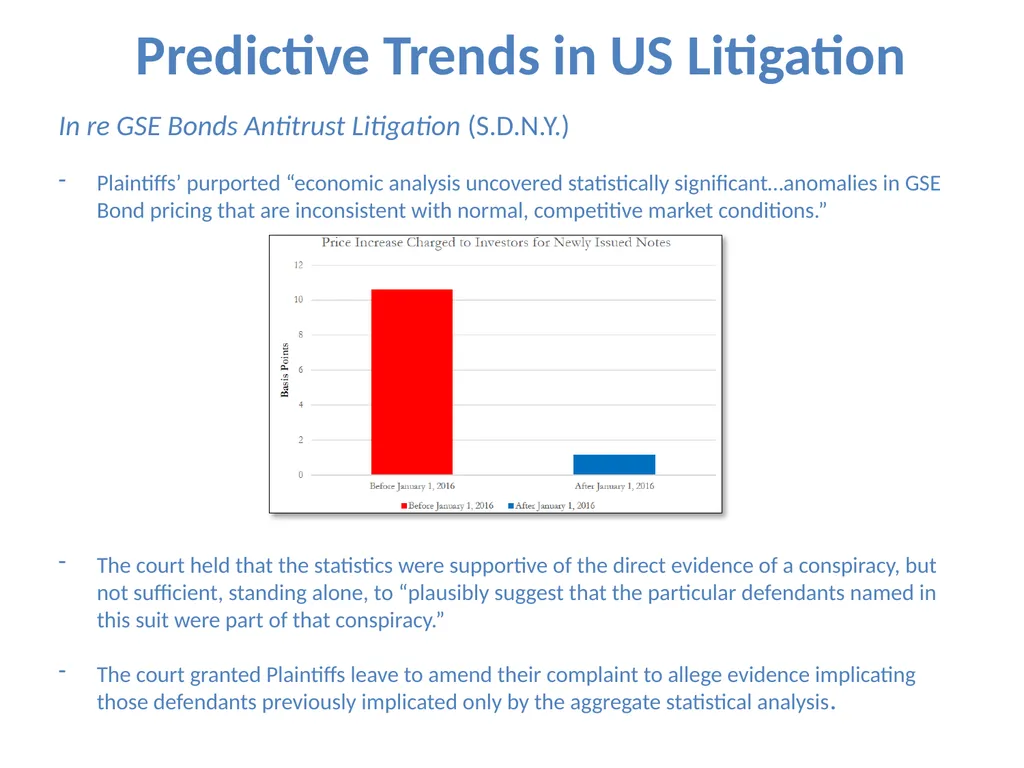
Plaintiffs’ purported “economic analysis uncovered statistically significant…anomalies in GSE Bond pricing that are inconsistent with normal, competitive market conditions.”
The court held that the statistics were supportive of the direct evidence of a conspiracy, but not sufficient, standing alone, to “plausibly suggest that the particular defendants named in this suit were part of that conspiracy.”
The court granted Plaintiffs leave to amend their complaint to allege evidence implicating those defendants previously implicated only by the aggregate statistical analysis. Predictive Trends in US Litigation<br>
slide26. John Williams
Partner
Milbank LLP Predictive Trends in US Debt Finance<br>
slide27. “Net short debt activism” in Windstream
In 2015, Windstream – a US telecom provider – completed a sale-leaseback transaction of certain fiber assets with Uniti Group Inc.
Over two years later, Aurelius purchased Windstream’s bonds and alleged that the 2015 transaction violated the bond’s covenants and Windstream was therefore in default on the bonds.
Market participants also believe that Aurelius bought a large amount of CDS protection on Windstream before making these allegations and thus stood to gain from the default even if Windstream did not pay out on the bonds. Predictive Trends in US Debt Finance<br>
slide28. “Net short debt activism” in Windstream
Windstream then (1) attempted an exchange and consent transaction in which other bondholders would waive the default and (2) took Aurelius to court, claiming that the transaction did not violate the bond’s covenants.
After over a year of litigation, Judge Jesse Furman of S.D.N.Y. held that:
the transaction violated the indenture
the exchange and consent transaction did not successfully waive the default and
entered a $310 million judgment in favor of Aurelius.
Shortly afterwards, Windstream filed for bankruptcy. Predictive Trends in US Debt Finance<br>
slide29. “Net short debt activism” in Windstream
Following Windstream, market participants raised concerns with “net short debt activism”.
“Net short debt activism” broadly describes the efforts of creditors who, despite holding a borrower’s debt, seem motivated to push the borrower into distress over covenant or other defaults.
Post-Windstream, borrowers in the US debt markets have tried to prevent this type of behavior by introducing provisions in debt documents that:
limit the rights of lenders who are “net short” or
bar claims of default after two years. Predictive Trends in US Debt Finance<br>
Panel of Recognized International Market Experts in Finance
Predictive Trends in Financial Market Disputes Disputes on the Horizon: Predictive Trends in Financial Market Disputes
P.R.I.M.E. Finance New York Conference 2019
17 October 2019, New York<br>
slide2. Trends in Sovereign Debt Disputes Carolyn B. Lamm<br>
slide3. International Multiparty Claims: Inevitable Effect of Globalization Along with the globalization of business streams, the IBA Legal Practice Division recognized in 2008 as “inevitable that … the group of possible claimants who have similar claims may cross borders”
“Multi-jurisdictional collective redress actions involving claimants and defendants from different countries and legal regimes are inevitable as parties press for broader, and perhaps global, resolutions of collective redress claims.” IBA Legal Practice Division, Guidelines for Recognising and Enforcing Foreign Judgments for Collective Redress ¶¶ 4, 13 (2008) © 2019 White & Case LLP<br>
slide4. Trends Favoring Collective Redress Increased availability of collective redress procedures in national courts
Class actions in the U.S.
Various other forms of representative or group actions recently introduced in national legislation of other countries
Increased recognition of multiparty claims in international arbitration rules
Including under certain investment treaties
Increased availability of third-party funding<br>
slide5. Arbitration Rules Increasingly Recognize Multiparty Claims © 2019 White & Case LLP<br>
slide6. Modern Investment Treaties Expressly Recognize Multiparty Claims Consolidation of claims that “have a question of law or fact in common and arise out of the same events or circumstances” (or similar)
Special arbitrator appointment procedures
Examples:
NAFTA (1992), Art. 1126, and many subsequent U.S., Canadian and Mexican BITs and FTAs
EU-Singapore FTA (2018), Art. 9.29 (not yet in force) © 2019 White & Case LLP<br>
slide7. Multiparty Claims are Not New in Investment Treaty Arbitration Goetz et al. v. Burundi, ICSID Case No. ARB/95/3
BIT claims of six individual Belgian shareholders in a Burundian company
Suez et al. v. Argentina, ICSID Case No. ARB/03/17
Claims under two BITs of one French and two Spanish shareholders in an Argentine water utility
OKO Pankki Oyj et al. v. Estonia, ICSID Case No. ARB/04/6
Claims under two BITs of one German and two Finnish banks, lenders under a loan agreement
Funnekotter et al. v. Zimbabwe, ICSID Case No. ARB/05/6
BIT claims of 14 unaffiliated Dutch investors in different farms in Zimbabwe
Urbaser et al. v. Argentina, ICSID Case No. ARB/07/26
BIT claims of two Spanish shareholders in an Argentine water company Carolyn B. Lamm, Hansel T. Pham & Alexandra K. Meise Bay, Consent and Due Process in Multiparty Investor-State Arbitrations, International Investment Law for the 21st Century: Essays in Honour of Christoph Schreuer (2009) © 2019 White & Case LLP<br>
slide8. Informal Consolidation By agreement of the parties
Identically composed tribunals
Water utility claims against Argentina, all arising out of investments in a concession for water distribution and waste water treatment services in Buenos Aires, under Argentina’s BITs with France, Spain and UK
Suez et al. v. Argentina, ICSID Case No. ARB/03/19
AWG Group v. Argentina, UNCITRAL
Claims arising out of Zimbabwe’s land reforms, raised separately by individual family members and the companies they owned
Von Pezold et al. v. Zimbabwe, ICSID Case No. ARB/10/15
Border Timbers et al. v. Zimbabwe, ICSID Case No. ARB/10/25 © 2019 White & Case LLP<br>
slide9. Financial Instruments Constitute Protected “Investments” under Most Investment Treaties Definitions of “Investment” in BITs and FTA Investment Chapters generally include financial instruments:
All assets invested in compliance with the law
Securities, bonds, debt instruments, and other instruments having economic value
Tribunals have found to constitute “investments”:
Loans, negotiable instruments, sovereign bonds, oil price hedges
Some treaties specifically exclude claims arising out of sovereign debt restructuring
Example: US-Uruguay BIT (2005), Annex G © 2019 White & Case LLP<br>
slide10. Argentine Sovereign Debt Dispute 130+ lawsuits in New York, USD 3.3 billion+
470+ lawsuits in Germany, EUR 106 million+
3 ICSID arbitrations based on Italy-Argentina BIT, led by Abaclat:
2 withdrawn after prevailing on jurisdiction (Ambiente and Alemanni)
Pursue treaty rights:
Claims for expropriation, lack of fair and equitable treatment, national treatment, most-favored nation treatment, unreasonable or discriminatory treatment
Total claims of approximately USD 2.5 billion
Preserve contractual rights under bonds issued under 7 different laws:
Group actions in U.S. federal court by Abaclat claimants, stayed pending arbitration
Prescription letters Abaclat et al. v. Argentine Republic, ICSID Case No. ARB/07/5, Decision on Jurisdiction and Admissibility (4 Aug. 2011) ¶ 82 See generally Carolyn B. Lamm, Eckhard R. Hellbeck and David P. Riesenberg, Theories of Liability and Responsibility, in International Financial Disputes – Arbitration and Mediation 241 (Jeffrey Golden and Carolyn B. Lamm, eds. 2015) © 2019 White & Case LLP<br>
slide11. Argentine Bond ICSID Arbitrations Abaclat et al. v. Argentina (2011)
60,000 individually-named Claimants – “mass” or “aggregate” claim
“Homogeneity” – common claim, common cause, and common injury formulation
Settled after merits hearing, having prevailed on jurisdiction and admissibility
Ambiente Ufficio et al. v. Argentina (2013)
Alemanni et al. v. Argentina (2014)
90 / 74 Claimants respectively – not “mass” claims
Both discontinued after prevailing on jurisdiction and admissibility Abaclat et al. v. Argentine Republic, ICSID Case No. ARB/07/5, Decision on Jurisdiction and Admissibility (4 Aug. 2011) ¶ 485 Ambiente Ufficio S.p.A. et al. v. Argentine Republic, ICSID Case No. ARB/08/9, Decision on Jurisdiction and Admissibility (8 Feb. 2013) ¶¶ 114, 116, 120, 230 Giovanni Alemanni et al. v. Argentine Republic, ICSID Case No. ARB/07/8, Decision on Jurisdiction and Admissibility (17 Nov. 2014) ¶ 267 © 2019 White & Case LLP<br>
slide12. Other Debt Instrument-Related Multiparty Arbitrations Based on Treaties Anderson et al. v. Costa Rica
Claimants: 137 individually-named Canadian nationals, alleged victims of a USD 405 million Ponzi scheme orchestrated by Villalobos brothers in Costa Rica
Claims under Canada-Costa Rica BIT alleging that Costa Rica failed to provide proper vigilance and regulatory supervision over the national financial system, and thereby violated BIT protections re: full protection and security, fair and equitable treatment, due process of law, and expropriation
Tribunal dismissed the claims finding that the deposit transactions violated Costa Rican law, thus the assets could not be considered as "investments" under the BIT Alasdair Ross Anderson et al v. Republic of Costa Rica, ICSID Case No. ARB(AF)/07/3, Award (19 May 2010) ¶¶ 15-16, 57-59, 65 © 2019 White & Case LLP<br>
slide13. Other Debt Instrument-Related Multiparty Arbitrations Based on Treaties (cont’d) Victims of Stanford Ponzi Scheme v. United States
Notices of intent filed in 2012, request for arbitration reportedly filed in 2013, but arbitration apparently has not progressed
Claimants: individually-named investors from Canada, Chile, Costa Rica, the Dominican Republic, Guatemala, Mexico, Peru and Uruguay
Alleged victims of a multi-billion dollar Ponzi scheme orchestrated by U.S. financier
Claims for USD 560 million under NAFTA, DR-CAFTA, US-Peru TPA, US-Chile FTA and US-Uruguay BIT, alleging that U.S. regulators failed to provide protection or legal security by neglecting to stop the Ponzi scheme in a timely manner Victims of the Stanford Ponzi Scheme v. The Government of the United States of America, Notices of Intent filed on 28-29 December 2012 © 2019 White & Case LLP<br>
slide14. European Financial Crisis Postova Banka and Istrokapital v. Greece
Held that narrow definition of “investment” in Slovakia-Greece BIT included debt issued by companies, but not sovereign debt, such as the restructured Greek sovereign bonds
Cyprus Popular Bank v. Greece (pending)
Claims arising out of the alleged lack of equal treatment to the claimant’s Greek branch in relation to other banks operating in Greece, including denial of access to the Greek Central Bank’s mechanisms available for emergency liquidity and capital support
Marfin Investment Group et al. v. Cyprus
Claims by 18 Greek investors in Cyprus Popular Bank arising out of the Government’s increase of its shareholding and assumption of control of the Bank, and the Bank’s subsequent insolvency – claims dismissed on merits
Adamakopoulos et al. v . Cyprus (pending)
Claims by multiple deposit and bondholders in Cyprus Popular Bank and Bank of Cyprus alleging discriminatory treatment as a result of bailout package Poštová banka, a.s. and Istrokapital SE v. Hellenic Republic, ICSID Case No. ARB/13/8, Award (9 Apr. 2015) ¶ 340
Marfin Investment Group Holdings S.A. et al. v. Republic of Cyprus, ICSID Case No. ARB/13/27, Award (26 July 2018) (redacted) © 2019 White & Case LLP<br>
slide15. Potential Obstacles to Collective Redress Relating to Sovereign Debt Debt instruments issued under national law and providing for exclusive jurisdiction of national courts
Example: Greece
Older instruments often provide for non-exclusive jurisdiction and New York or English governing law
Collective Action Clauses
Require certain minimum participation of bondholders in action
Agreement to restructuring by qualified majority of bondholders may bind minority bondholders
Recent bonds governed by New York law
Bondholder action subject to approval by a Trustee
Bonds governed by English law © 2019 White & Case LLP 101181354 v1<br>
slide16. Predictive Trends in Europe Professor Pim Rank<br>
slide17. Predictive Trends in Europe Coloring of the civil law duty of care of banks by caretaking duties based on public law
Extension of the civil law duty of care of banks from retail clients to professional clients
Extension of the civil law duty of care of banks from clients to third parties
More frequent intervention by regulatory authorities with respect to products or conduct that are legally compliant but considered improper<br>
slide18. Coloring by the courts of the civil law duty of care of banks by caretaking duties based on public law:
In most jurisdictions in Europe, it is established case law that banks have a special civil law duty of care towards their clients due to their function in society and the fiduciary relationship between the bank and the client
Over the past few years a wide range of public legislation has been introduced in Europe aimed at the protection of clients of banks and containing detailed caretaking duties
Public law caretaking duties may be ‘read in’ in the contractual relationship between the bank and the client and ‘color’ it
Interaction between both sets of rules is heavily debated<br>
slide19. Extension by the courts of the special civil law duty of care of banks from retail clients to professional clients:
Although a bank must always act in accordance with its duty of care, irrespective of whether the client is a consumer or a professional party, this duty of care is less far-reaching where the client is a professional
What we are now seeing is that as a result of the present market conditions and the global financial crisis, courts are shifting to assuming more stringent protection for professional parties
This applies in particular to small businesses and public sector parties such as housing corporations<br>
slide20. Extension by the courts of the special civil law duty of care of banks from clients to third parties:
Under Dutch law a bank has a duty of care not only to its clients but also, under certain circumstances, to third parties.
It follows from the Safe Haven judgement of the Dutch Supreme Court that when a bank becomes aware of possible criminal activities on the part of a client, the bank may be required to carry out an investigation and take appropriate measures, at the risk of incurring liability towards third parties for failing to do so.
The Safe Haven judgment was recently confirmed and is likely to be followed by courts in other jurisdictions<br>
slide21. More frequent intervention by regulatory authorities, without a sound legal basis, with respect to certain products or conduct considered improper by such regulatory authorities:
A review by regulators of a product or service used to be limited to determining whether it complied with the legal requirements
However, more and more regulators tend to consider the economic merits of the product and service as well and to take action if they consider the product or service improper or undesirable from an economic point of view
This attitude of regulatory authorities undermines their legitimacy and makes it difficult for banks to assess whether their products and services are legally compliant<br>
slide22. Predictive Trends in US Litigation Jayant W. Tambe
Pleading Tactics: “Blinded me with science”<br>
slide23. City of Philadelphia v. Bank of America Corp., et al. (S.D.N.Y.)
Plaintiffs use a “series of statistical models” to purportedly confirm allegations of an antitrust conspiracy among various remarketing agents to set VRDO rates.
Plaintiffs use a regression model relying on historical pricing for short term commercial paper to attempt to model “but-for” VRDO rates to compare to actual rates (below left).
Plaintiffs also purport to identify “clustering” in which different bonds exhibit the same interest rate or week-over-week change in interest rate (below right). Predictive Trends in US Litigation<br>
slide24. Mass. ex rel. Rosenberg v. JPMorgan Chase & Co., et al. (Mass. Superior Ct.)
MA False Claims Act: Relator attempted to isolate “buckets” of VRDOs across banks and claimed the periodic interest rate adjustments were identical 90% or more of the time.
Allegation: “[There] is no rational or market-based explanation for the kind of lock-step movement of interest rates among the defendant banks.
The court dismissed based on the FCA’s public disclosure bar:
“The fact that the relator may have some specialized knowledge or background concerning the municipal bond industry and spent a thousand hours dissecting public information does not, in itself, allow him to file and prosecute a qui tam action.” Predictive Trends in US Litigation<br>
slide25. In re GSE Bonds Antitrust Litigation (S.D.N.Y.)
Plaintiffs’ purported “economic analysis uncovered statistically significant…anomalies in GSE Bond pricing that are inconsistent with normal, competitive market conditions.”
The court held that the statistics were supportive of the direct evidence of a conspiracy, but not sufficient, standing alone, to “plausibly suggest that the particular defendants named in this suit were part of that conspiracy.”
The court granted Plaintiffs leave to amend their complaint to allege evidence implicating those defendants previously implicated only by the aggregate statistical analysis. Predictive Trends in US Litigation<br>
slide26. John Williams
Partner
Milbank LLP Predictive Trends in US Debt Finance<br>
slide27. “Net short debt activism” in Windstream
In 2015, Windstream – a US telecom provider – completed a sale-leaseback transaction of certain fiber assets with Uniti Group Inc.
Over two years later, Aurelius purchased Windstream’s bonds and alleged that the 2015 transaction violated the bond’s covenants and Windstream was therefore in default on the bonds.
Market participants also believe that Aurelius bought a large amount of CDS protection on Windstream before making these allegations and thus stood to gain from the default even if Windstream did not pay out on the bonds. Predictive Trends in US Debt Finance<br>
slide28. “Net short debt activism” in Windstream
Windstream then (1) attempted an exchange and consent transaction in which other bondholders would waive the default and (2) took Aurelius to court, claiming that the transaction did not violate the bond’s covenants.
After over a year of litigation, Judge Jesse Furman of S.D.N.Y. held that:
the transaction violated the indenture
the exchange and consent transaction did not successfully waive the default and
entered a $310 million judgment in favor of Aurelius.
Shortly afterwards, Windstream filed for bankruptcy. Predictive Trends in US Debt Finance<br>
slide29. “Net short debt activism” in Windstream
Following Windstream, market participants raised concerns with “net short debt activism”.
“Net short debt activism” broadly describes the efforts of creditors who, despite holding a borrower’s debt, seem motivated to push the borrower into distress over covenant or other defaults.
Post-Windstream, borrowers in the US debt markets have tried to prevent this type of behavior by introducing provisions in debt documents that:
limit the rights of lenders who are “net short” or
bar claims of default after two years. Predictive Trends in US Debt Finance<br>