
Valuation & Leverage Capital budgeting considering
GB
Published · 40 slides · 0 views
1 / 1
Description
Valuation Leverage Capital budgeting considering risk and leverage Introduction Today we will discuss three approaches to valuing a risky asset for which both debt and equity financing are used. Initial Simplifying Assumptions: The
Related Topics
Share
Embed code
Download this presentation From Below
"Valuation & Leverage Capital budgeting considering" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Valuation & Leverage Capital budgeting considering risk and leverage<br>
02
Introduction Today we will discuss three approaches to valuing a risky asset for which both debt and equity financing are used.
Initial Simplifying Assumptions:
The project has average (for the firm) risk.
For simplicity the betas or costs of capital used will be for the existing firm rather than being project specific. Often iffy but correctable.
The firm’s debt-equity ratio is held constant.
This simplifies the application in that we don’t need to worry about changing costs of capital over time and identifies the proper the adjustment of our risk measure for leverage. It is a realistic and common policy (at least in expectation).
Corporate taxes are the only relevant imperfection.
No agency, bankruptcy or issuance costs to quantify. Clearly not!<br>
03
The Weighted Average Cost
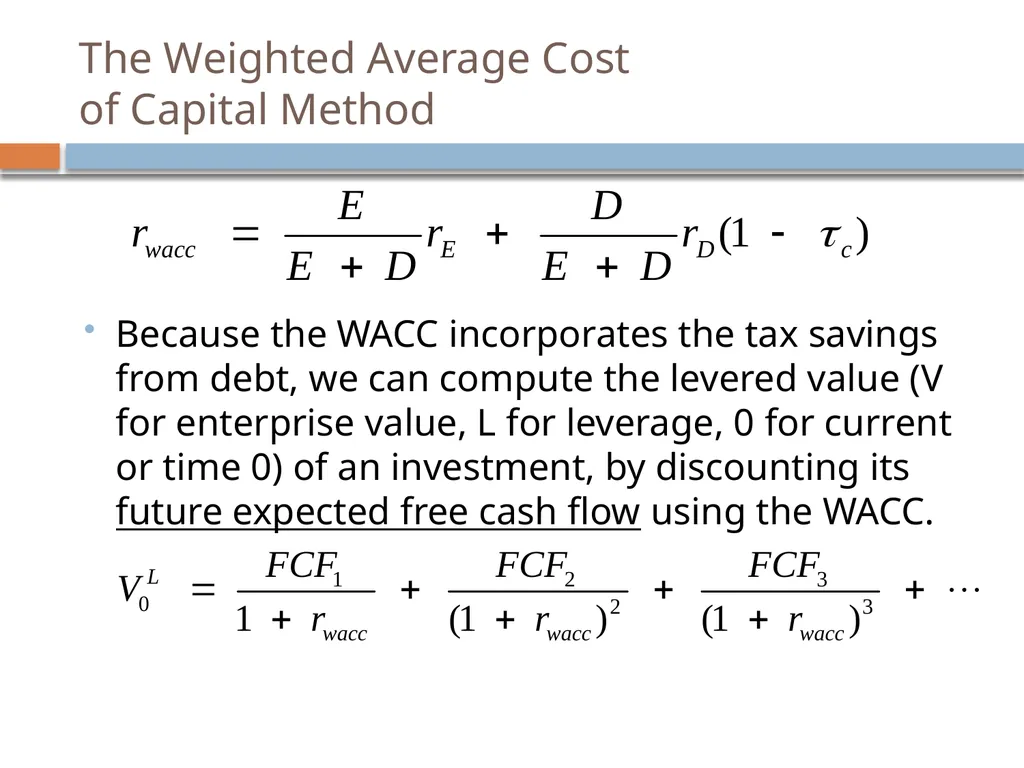
of Capital Method Because the WACC incorporates the tax savings from debt, we can compute the levered value (V for enterprise value, L for leverage, 0 for current or time 0) of an investment, by discounting its future expected free cash flow using the WACC.<br>
04
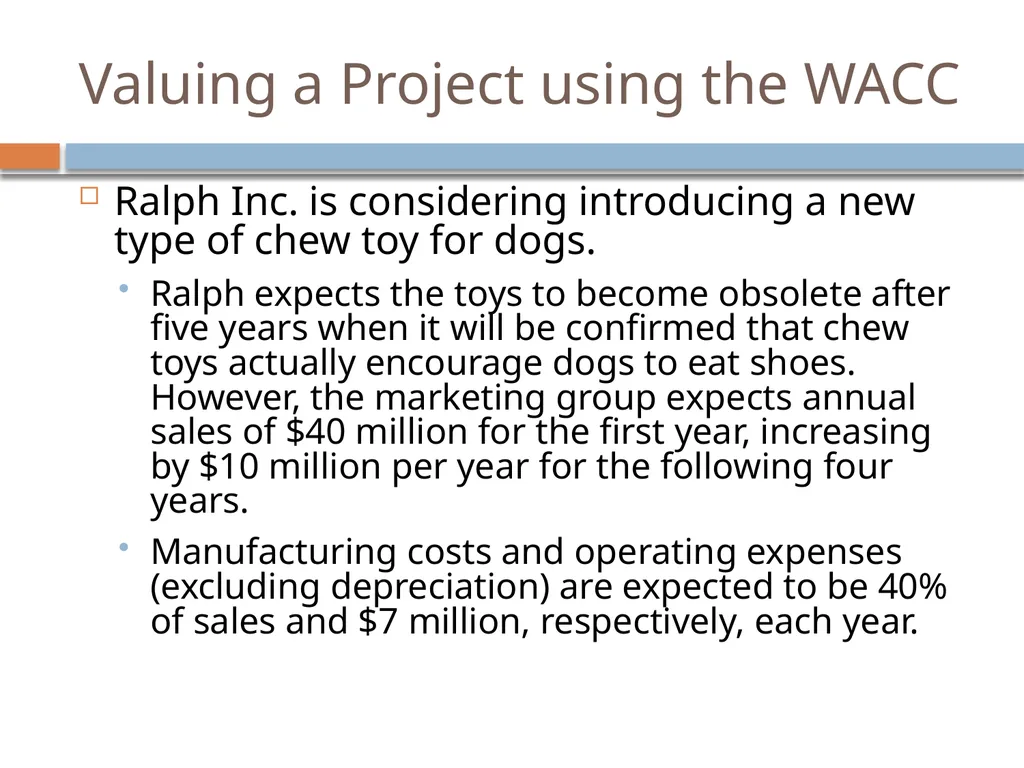
Valuing a Project using the WACC Ralph Inc. is considering introducing a new type of chew toy for dogs.
Ralph expects the toys to become obsolete after five years when it will be confirmed that chew toys actually encourage dogs to eat shoes. However, the marketing group expects annual sales of $40 million for the first year, increasing by $10 million per year for the following four years.
Manufacturing costs and operating expenses (excluding depreciation) are expected to be 40% of sales and $7 million, respectively, each year.<br>
05
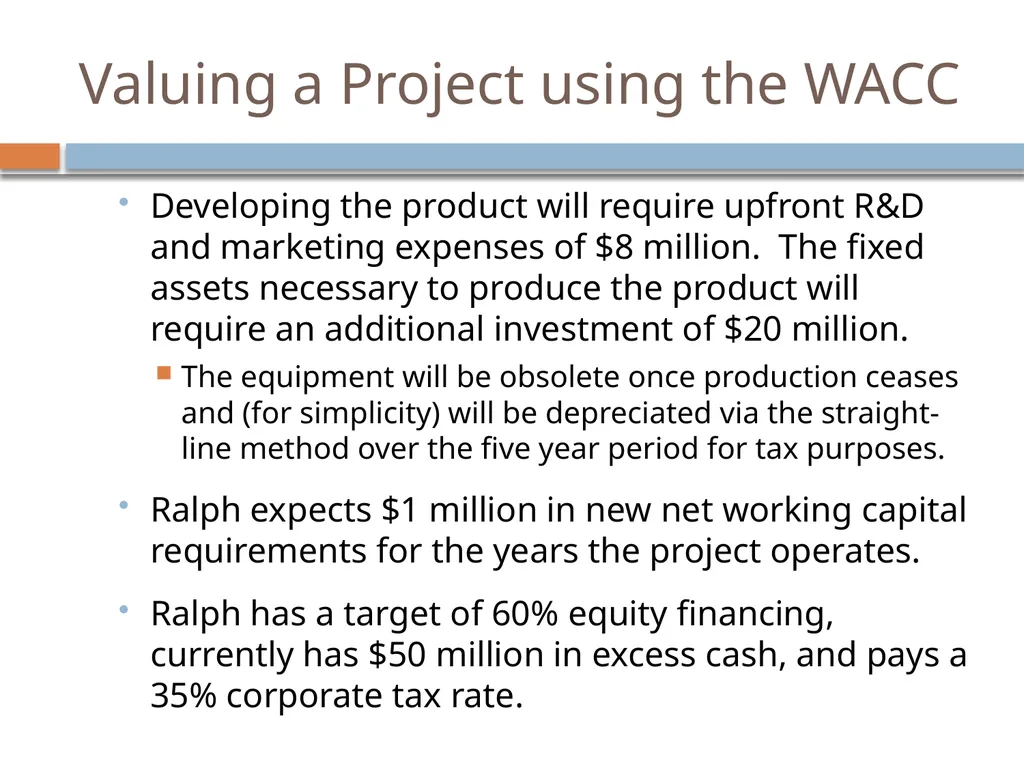
Valuing a Project using the WACC Developing the product will require upfront R&D and marketing expenses of $8 million. The fixed assets necessary to produce the product will require an additional investment of $20 million.
The equipment will be obsolete once production ceases and (for simplicity) will be depreciated via the straight-line method over the five year period for tax purposes.
Ralph expects $1 million in new net working capital requirements for the years the project operates.
Ralph has a target of 60% equity financing, currently has $50 million in excess cash, and pays a 35% corporate tax rate.<br>
06
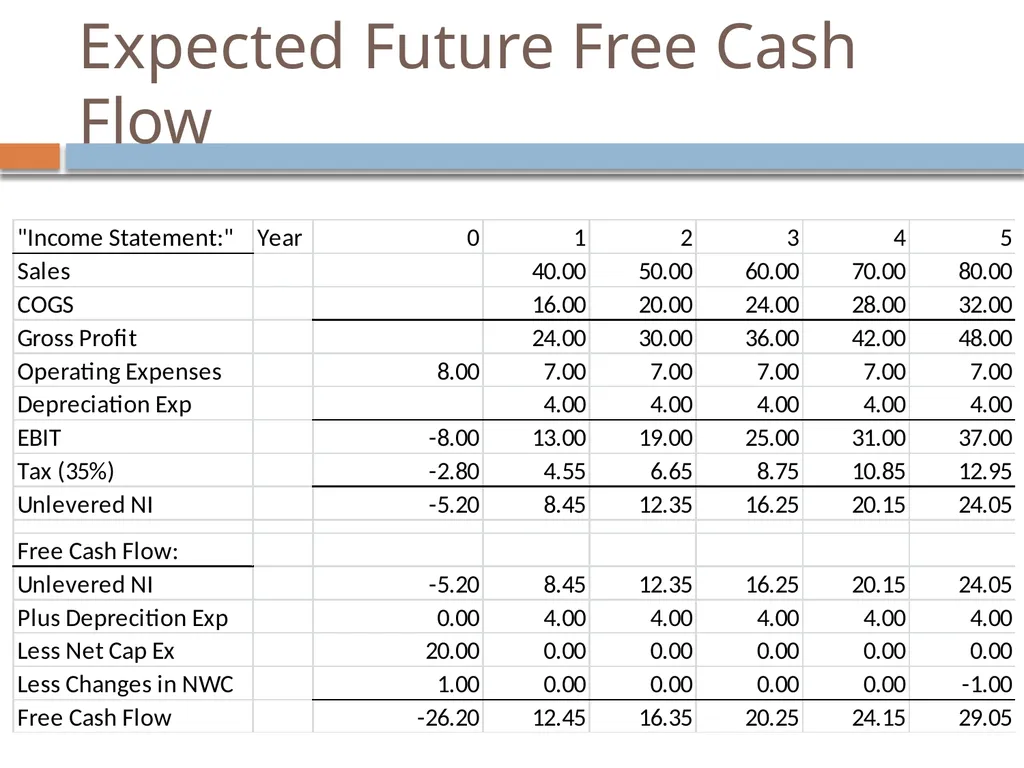
Expected Future Free Cash Flow<br>
07
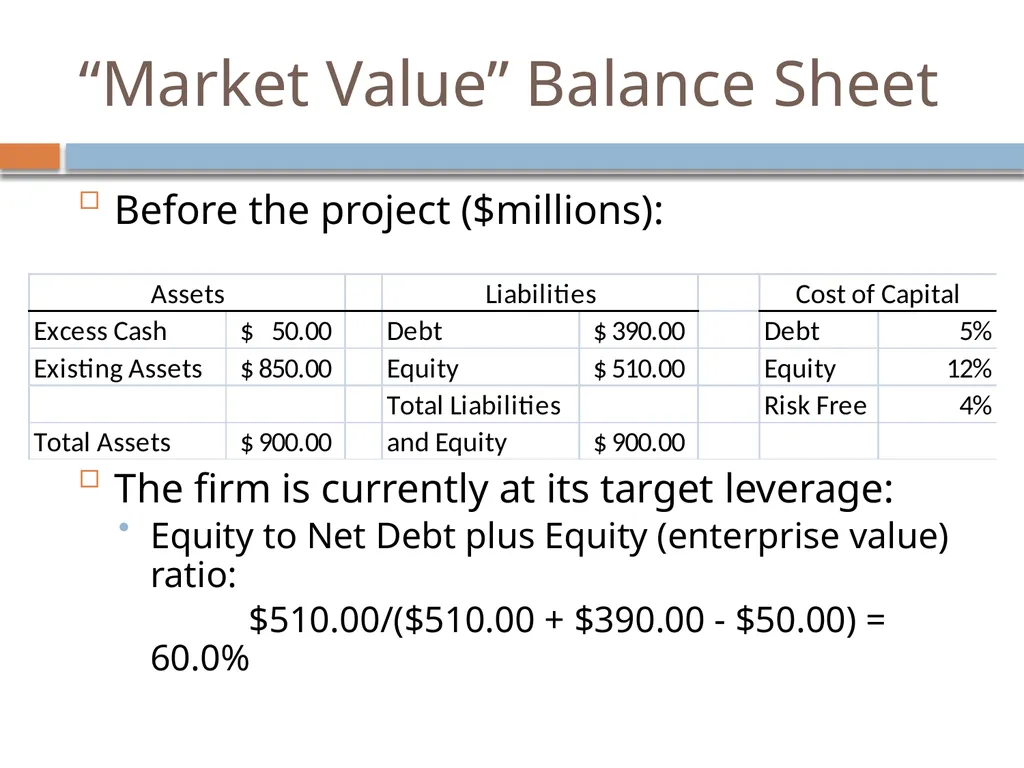
“Market Value” Balance Sheet Before the project ($millions):
The firm is currently at its target leverage:
Equity to Net Debt plus Equity (enterprise value) ratio:
$510.00/($510.00 + $390.00 - $50.00) = 60.0%<br>
The firm is currently at its target leverage:
Equity to Net Debt plus Equity (enterprise value) ratio:
$510.00/($510.00 + $390.00 - $50.00) = 60.0%<br>
08
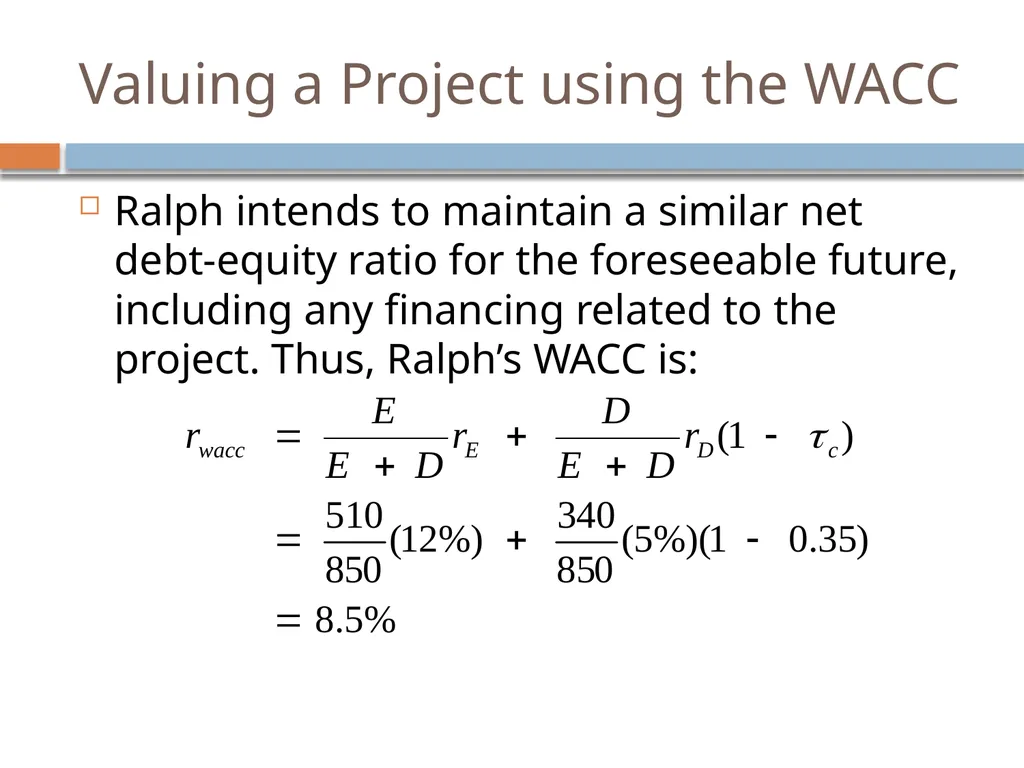
Valuing a Project using the WACC Ralph intends to maintain a similar net debt-equity ratio for the foreseeable future, including any financing related to the project. Thus, Ralph’s WACC is:<br>
09
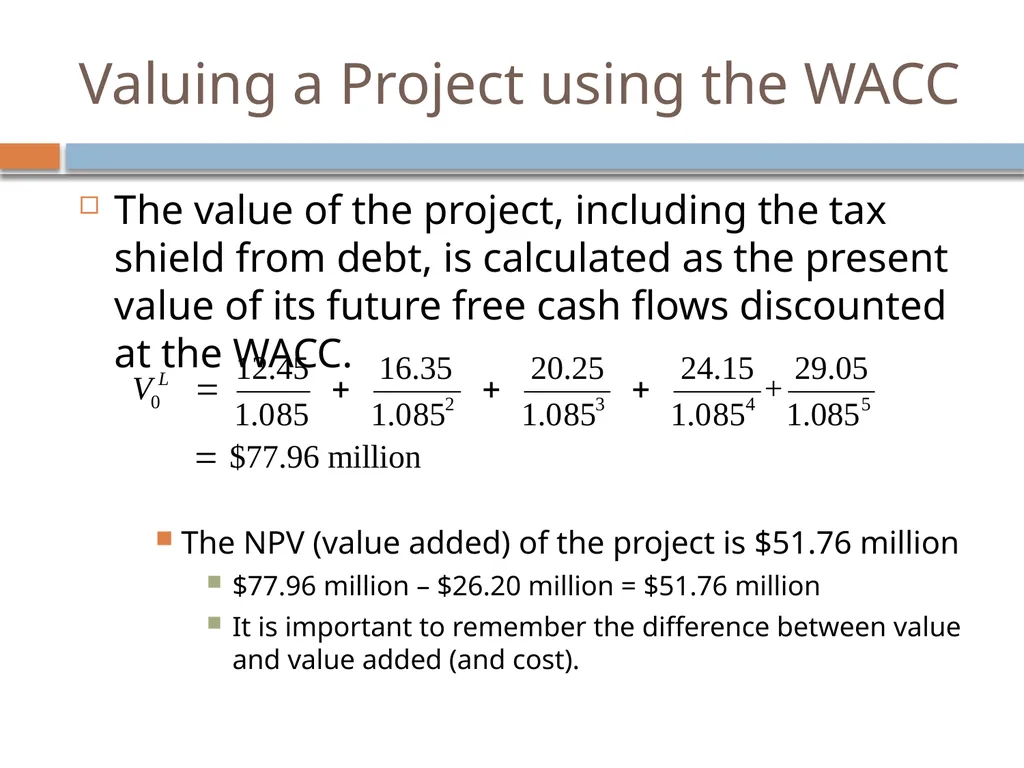
Valuing a Project using the WACC The value of the project, including the tax shield from debt, is calculated as the present value of its future free cash flows discounted at the WACC.
The NPV (value added) of the project is $51.76 million
$77.96 million – $26.20 million = $51.76 million
It is important to remember the difference between value and value added (and cost).<br>
The NPV (value added) of the project is $51.76 million
$77.96 million – $26.20 million = $51.76 million
It is important to remember the difference between value and value added (and cost).<br>
10
Summary of the WACC Method Determine the incremental free cash flow of the investment project.
Compute the weighted average cost of capital.
Compute the value of the investment, including the tax benefit of leverage, by discounting the free cash flow of the investment using the WACC.
Note that only the tax benefit of debt is explicitly valued via this method.
The WACC can be used throughout the firm as the companywide cost of capital for new investments that are of comparable risk to the firm itself and that will adopt the firm’s debt-equity ratio.<br>
11
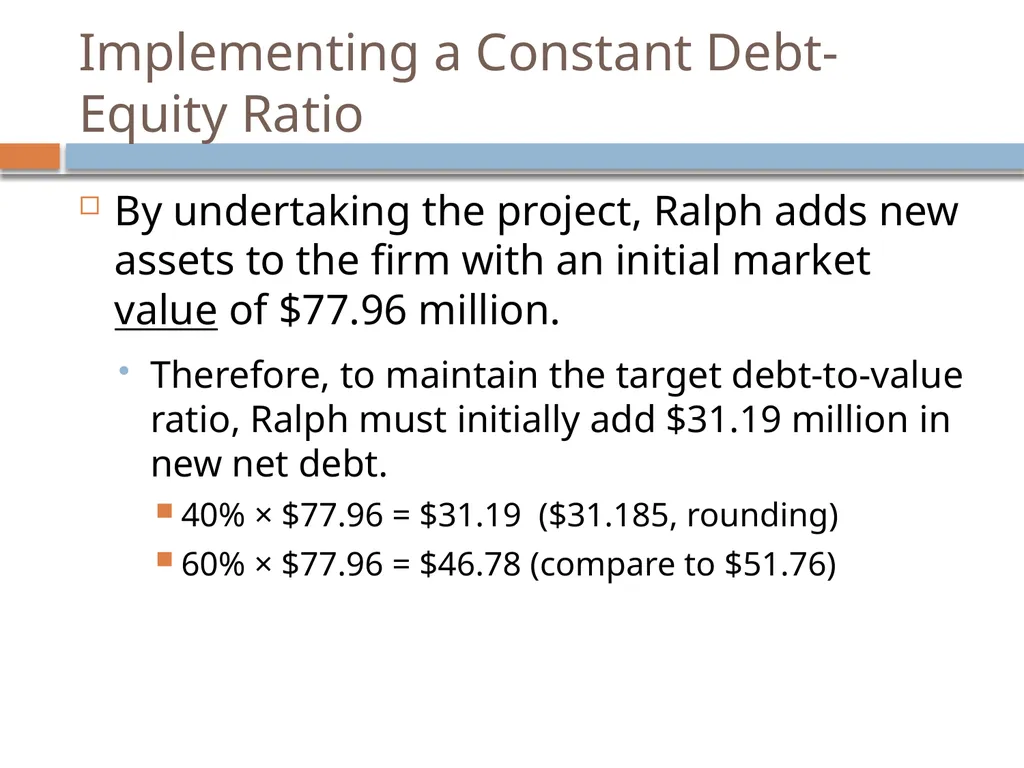
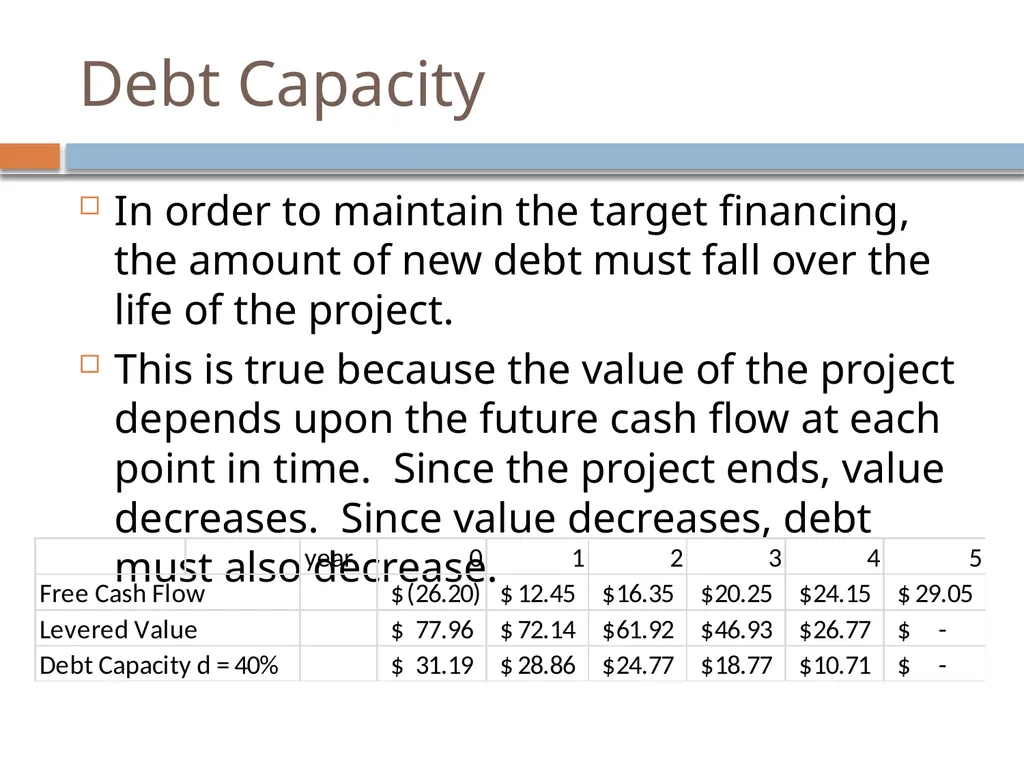
Implementing a Constant Debt-Equity Ratio By undertaking the project, Ralph adds new assets to the firm with an initial market value of $77.96 million.
Therefore, to maintain the target debt-to-value ratio, Ralph must initially add $31.19 million in new net debt.
40% × $77.96 = $31.19 ($31.185, rounding)
60% × $77.96 = $46.78 (compare to $51.76)<br>
Therefore, to maintain the target debt-to-value ratio, Ralph must initially add $31.19 million in new net debt.
40% × $77.96 = $31.19 ($31.185, rounding)
60% × $77.96 = $46.78 (compare to $51.76)<br>
12
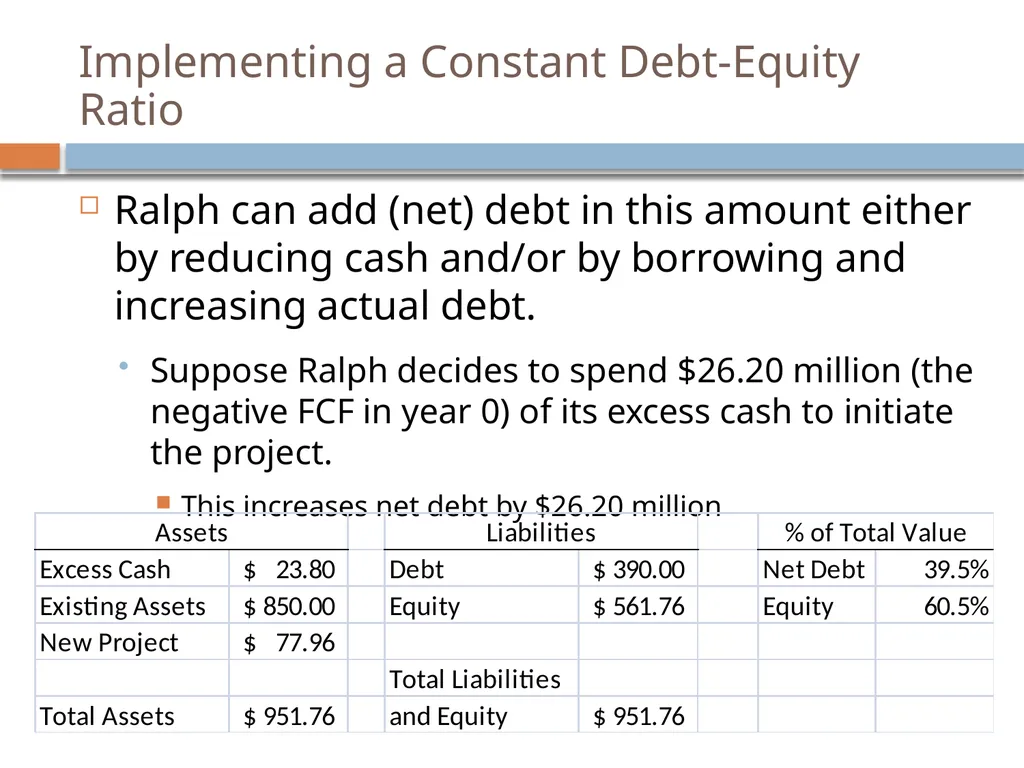
Implementing a Constant Debt-Equity Ratio Ralph can add (net) debt in this amount either by reducing cash and/or by borrowing and increasing actual debt.
Suppose Ralph decides to spend $26.20 million (the negative FCF in year 0) of its excess cash to initiate the project.
This increases net debt by $26.20 million<br>
Suppose Ralph decides to spend $26.20 million (the negative FCF in year 0) of its excess cash to initiate the project.
This increases net debt by $26.20 million<br>
13
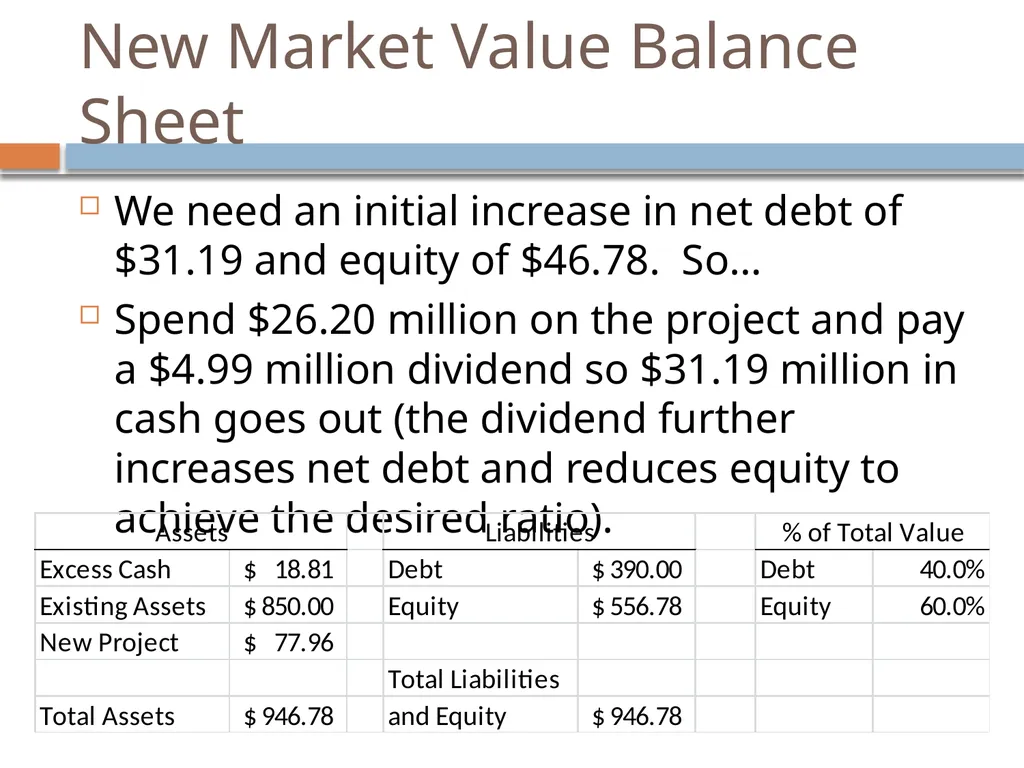
New Market Value Balance Sheet We need an initial increase in net debt of $31.19 and equity of $46.78. So…
Spend $26.20 million on the project and pay a $4.99 million dividend so $31.19 million in cash goes out (the dividend further increases net debt and reduces equity to achieve the desired ratio).<br>
Spend $26.20 million on the project and pay a $4.99 million dividend so $31.19 million in cash goes out (the dividend further increases net debt and reduces equity to achieve the desired ratio).<br>
14
Implementing a Constant Debt-Equity Ratio The market value of Ralph’s equity increases by $46.78 million.
$556.78 − $510.00 = $46.78 (60% of $77.96)
Adding the dividend of $4.99 million into the mix, the shareholders’ total gain is $51.76 million.
$46.78 + 4.99 = $51.76 (rounding)
Which is exactly the NPV calculated for the project
The first try: without the dividend the equity value increased by the project’s NPV of $51.76 = $561.76 - $510.00. This was too large an increase in equity (with an increase in net debt of $26.20) since Ralph seeks to maintain 60% equity financing.<br>
15
Implementing a Constant Debt-Equity Ratio Debt Capacity
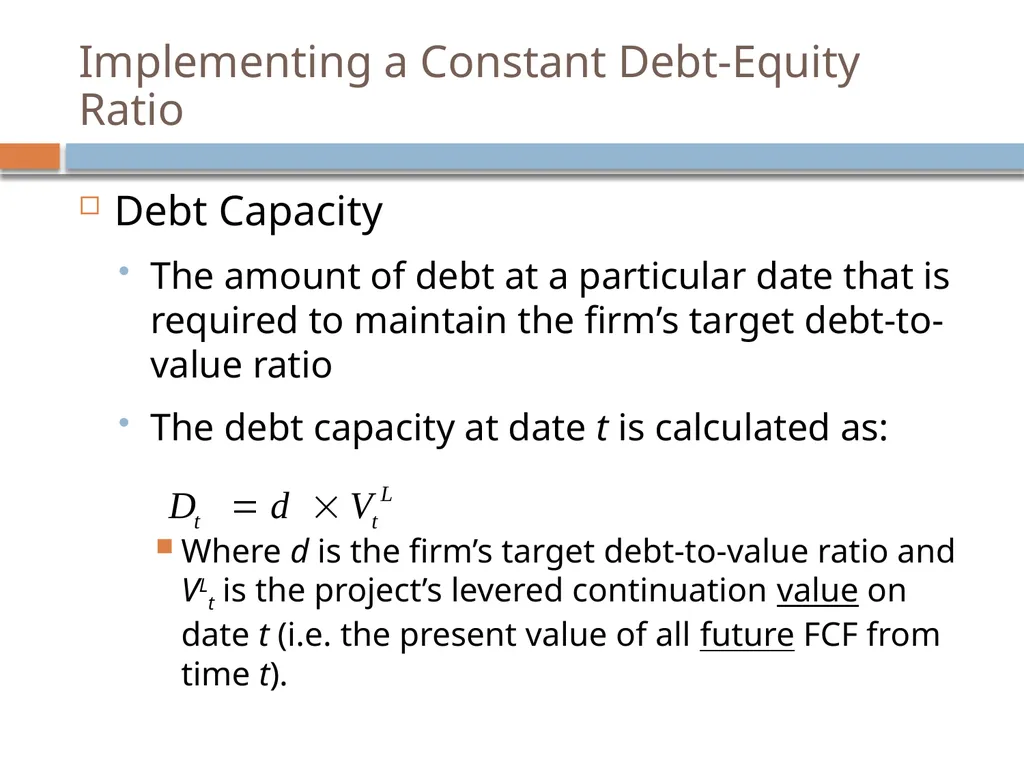
The amount of debt at a particular date that is required to maintain the firm’s target debt-to-value ratio
The debt capacity at date t is calculated as:
Where d is the firm’s target debt-to-value ratio and VLt is the project’s levered continuation value on date t (i.e. the present value of all future FCF from time t).<br>
16
Debt Capacity In order to maintain the target financing, the amount of new debt must fall over the life of the project.
This is true because the value of the project depends upon the future cash flow at each point in time. Since the project ends, value decreases. Since value decreases, debt must also decrease.<br>
This is true because the value of the project depends upon the future cash flow at each point in time. Since the project ends, value decreases. Since value decreases, debt must also decrease.<br>
17
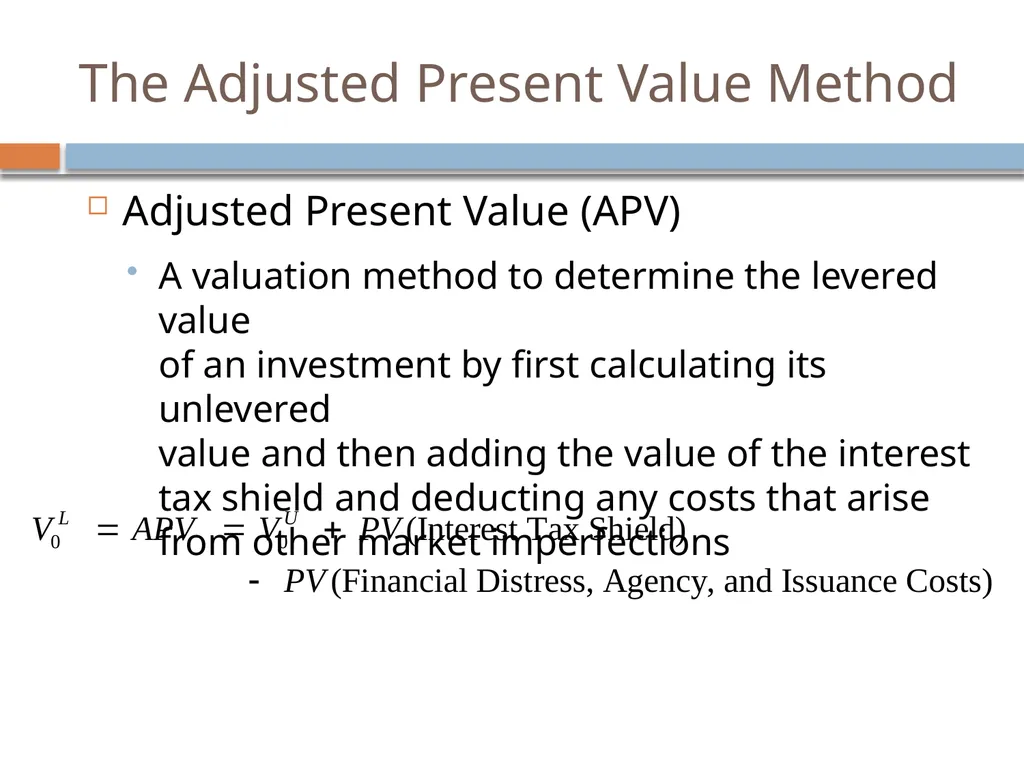
The Adjusted Present Value Method Adjusted Present Value (APV)
A valuation method to determine the levered value of an investment by first calculating its unlevered value and then adding the value of the interest tax shield and deducting any costs that arise from other market imperfections<br>
A valuation method to determine the levered value of an investment by first calculating its unlevered value and then adding the value of the interest tax shield and deducting any costs that arise from other market imperfections<br>
18
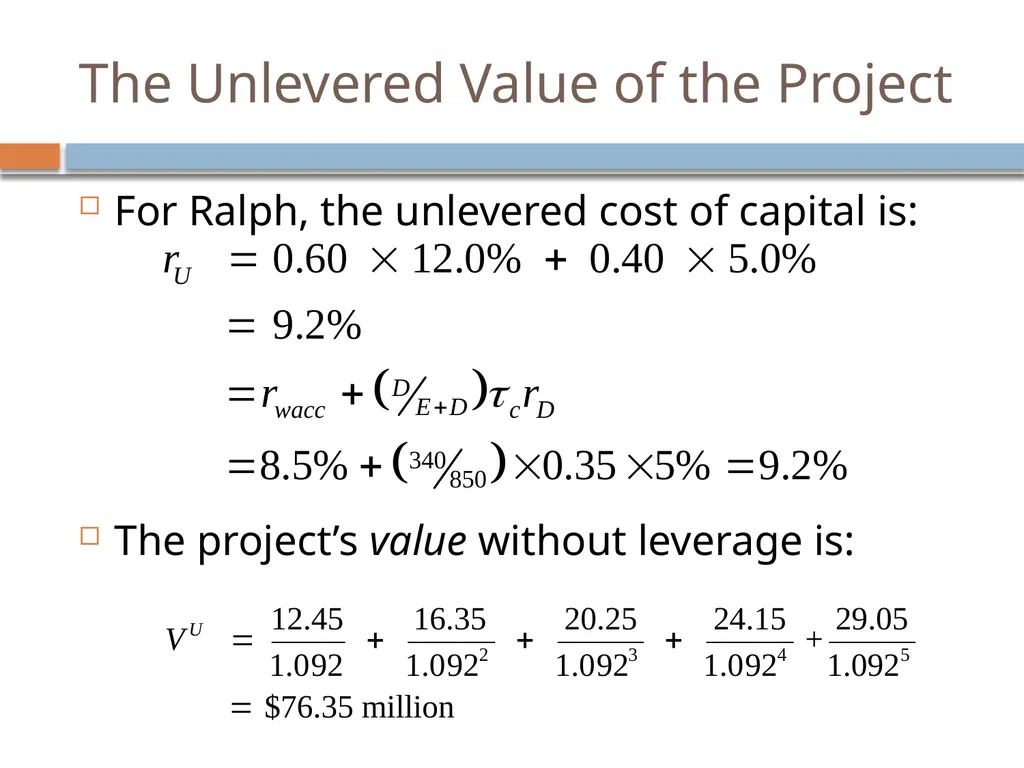
The Unlevered Value of the Project The first step in the APV method is to calculate the value of the free cash flows using the project’s cost of capital if it were financed without leverage.<br>
19
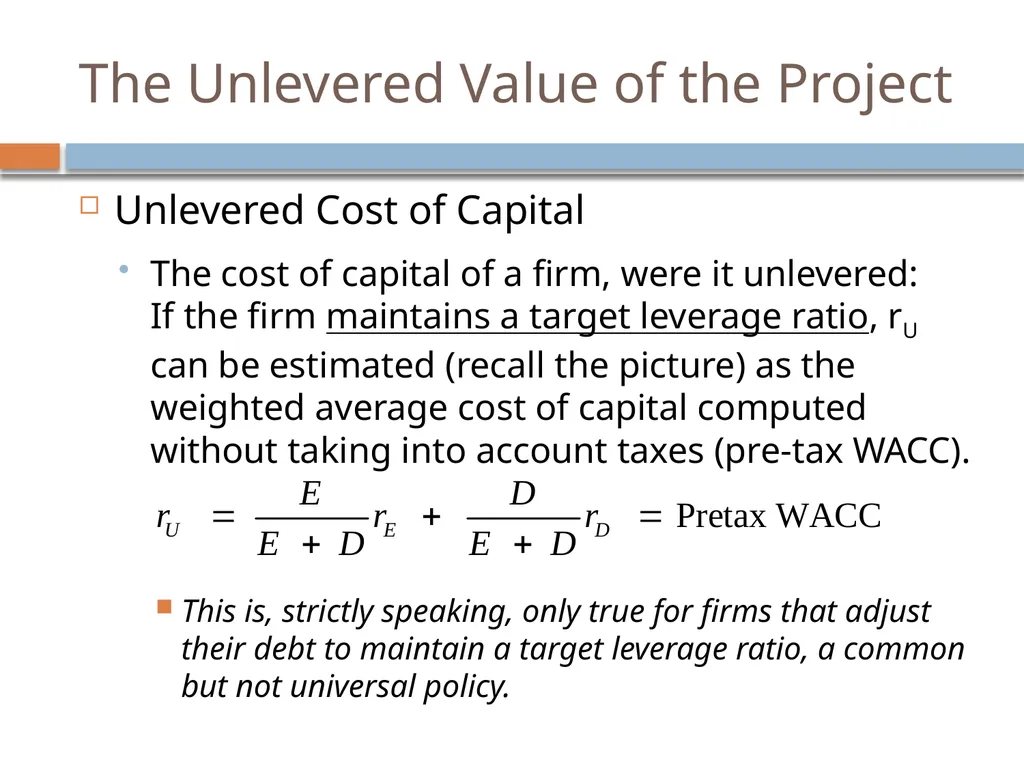
The Unlevered Value of the Project Unlevered Cost of Capital
The cost of capital of a firm, were it unlevered: If the firm maintains a target leverage ratio, rU can be estimated (recall the picture) as the weighted average cost of capital computed without taking into account taxes (pre-tax WACC).
This is, strictly speaking, only true for firms that adjust their debt to maintain a target leverage ratio, a common but not universal policy.<br>
20
The Unlevered Value of the Project For Ralph, the unlevered cost of capital is:
The project’s value without leverage is:<br>
The project’s value without leverage is:<br>
21
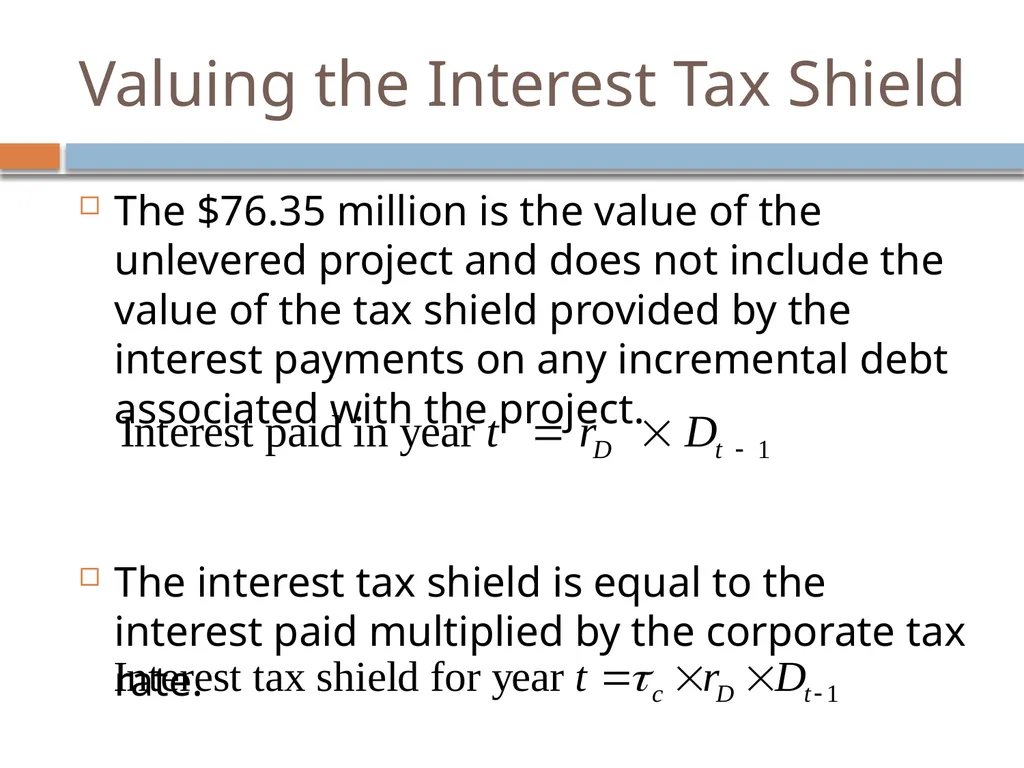
Valuing the Interest Tax Shield The $76.35 million is the value of the unlevered project and does not include the value of the tax shield provided by the interest payments on any incremental debt associated with the project.
The interest tax shield is equal to the interest paid multiplied by the corporate tax rate.<br>
The interest tax shield is equal to the interest paid multiplied by the corporate tax rate.<br>
22
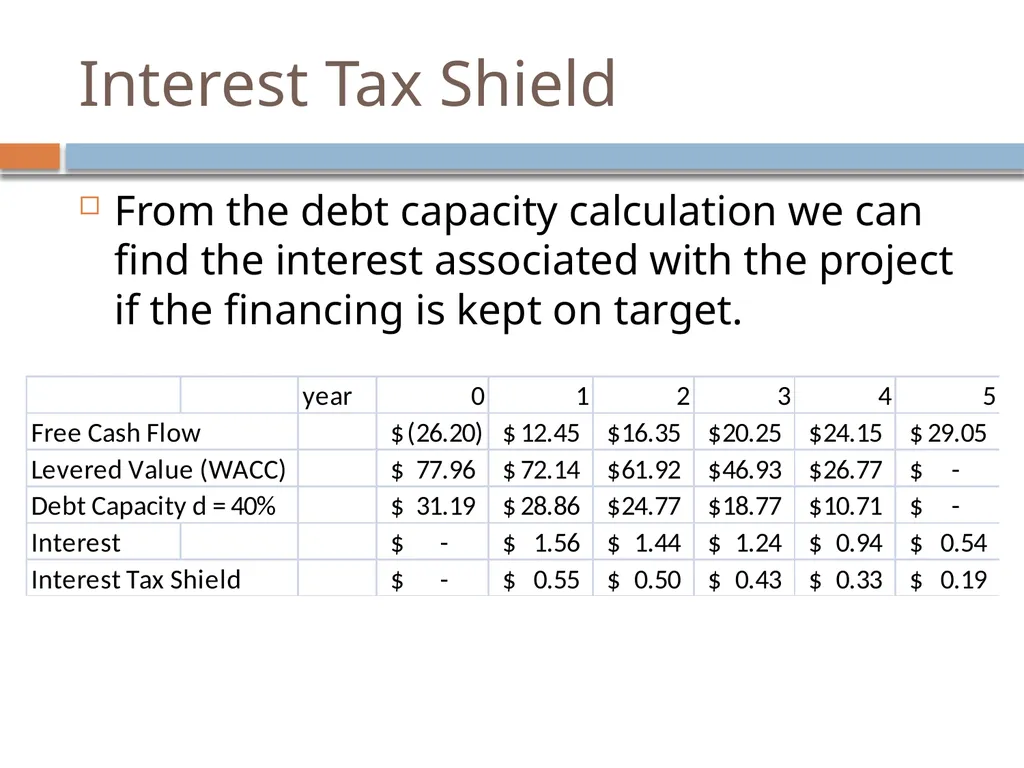
Interest Tax Shield From the debt capacity calculation we can find the interest associated with the project if the financing is kept on target.<br>
23
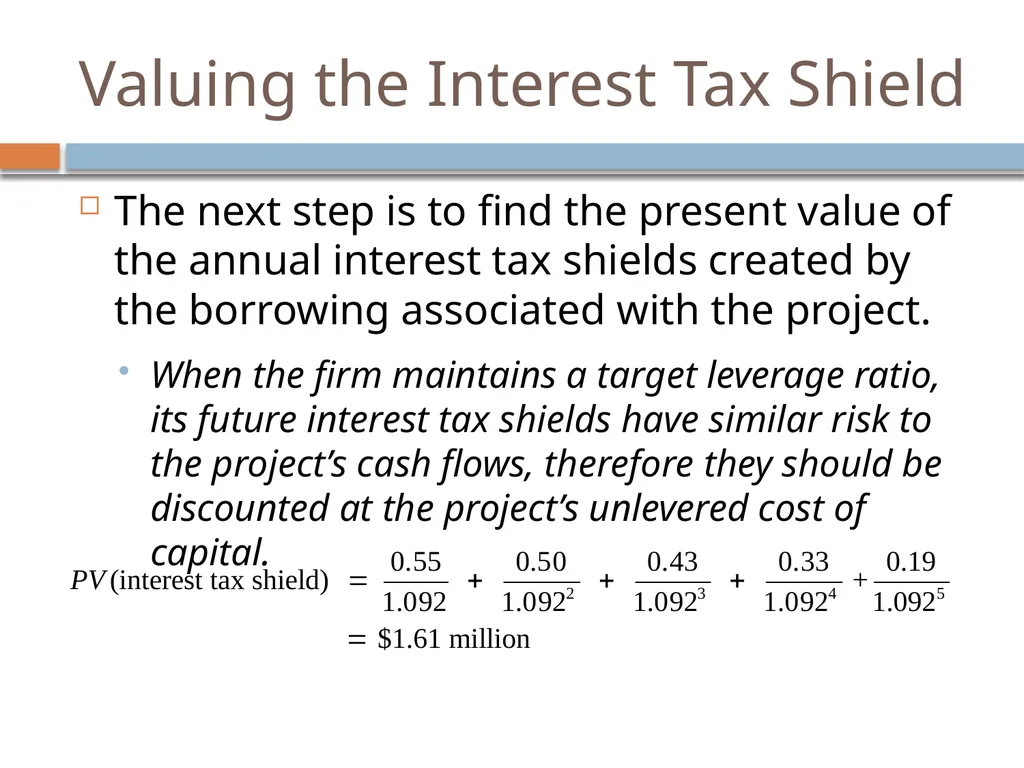
Valuing the Interest Tax Shield The next step is to find the present value of the annual interest tax shields created by the borrowing associated with the project.
When the firm maintains a target leverage ratio, its future interest tax shields have similar risk to the project’s cash flows, therefore they should be discounted at the project’s unlevered cost of capital.<br>
When the firm maintains a target leverage ratio, its future interest tax shields have similar risk to the project’s cash flows, therefore they should be discounted at the project’s unlevered cost of capital.<br>
24
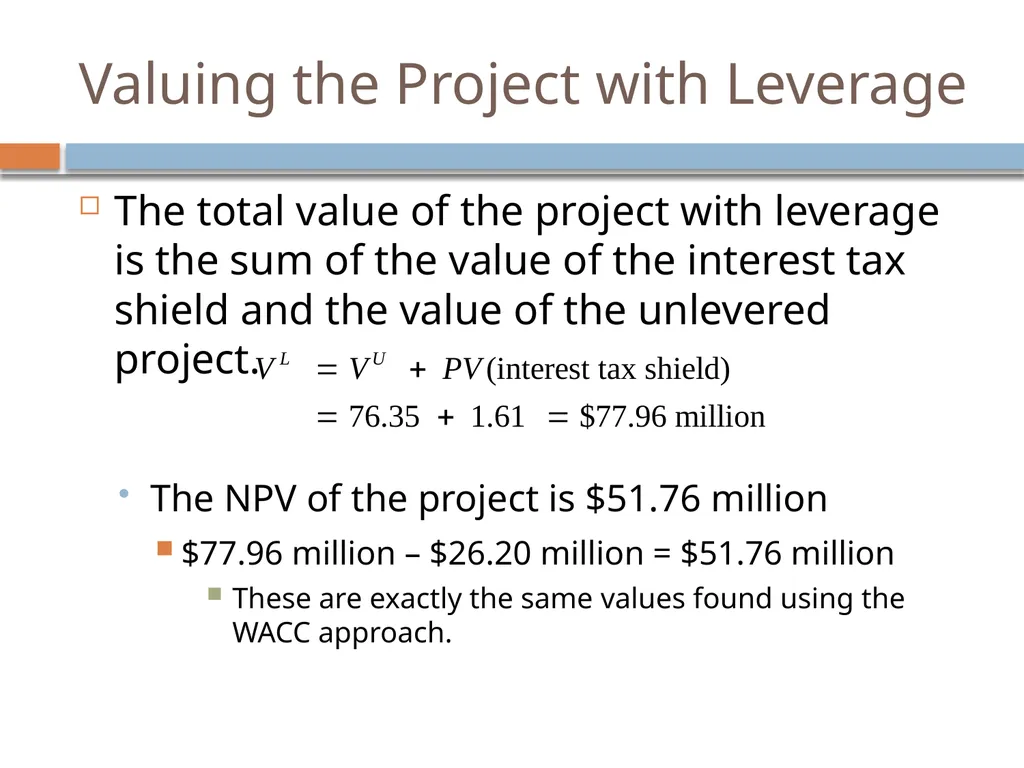
Valuing the Project with Leverage The total value of the project with leverage is the sum of the value of the interest tax shield and the value of the unlevered project.
The NPV of the project is $51.76 million
$77.96 million – $26.20 million = $51.76 million
These are exactly the same values found using the WACC approach.<br>
The NPV of the project is $51.76 million
$77.96 million – $26.20 million = $51.76 million
These are exactly the same values found using the WACC approach.<br>
25
Summary of the APV Method Determine the investment’s value
without leverage.
Determine the present value of the interest tax shield.
Determine the expected interest tax shield.
Discount the interest tax shield.
Add the unlevered value to the present value of the interest tax shield to determine the value of the investment with leverage.
Could subtract the costs associated with debt as well if there is a reasonable way to quantify them.<br>
26
Summary of the APV Method The APV method has some advantages.
It can be easier to apply than the WACC method when the firm does not maintain a constant debt-equity ratio.
The APV approach also explicitly values market imperfections and therefore allows managers to measure their contribution to value.
Note that but for the tax shield the WACC method may also do this.<br>
27
The Flow-to-Equity Method Flow-to-Equity
A valuation method that calculates the free cash flow available to equity holders taking into account all payments to and from debt holders.
Free Cash Flow to Equity (FCFE), the free cash flow that remains after providing for interest payments, debt issuance and debt repayments
The cash flows to equity holders are then discounted using the cost of (levered) equity capital.<br>
28
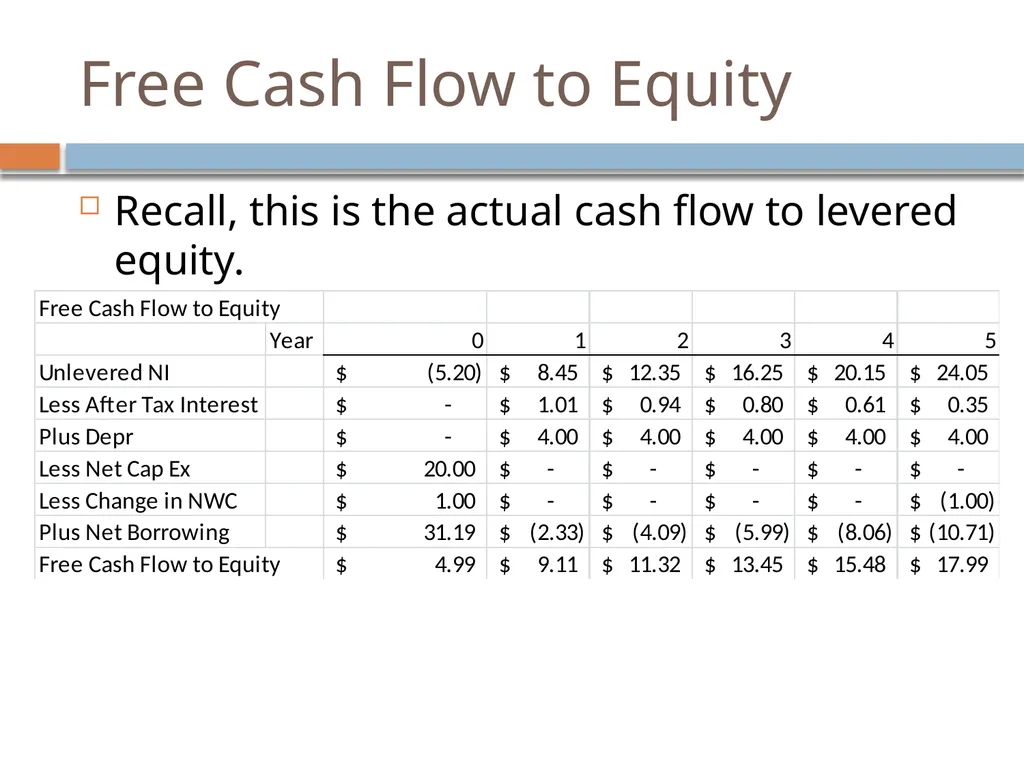
Free Cash Flow to Equity Recall, this is the actual cash flow to levered equity.<br>
29
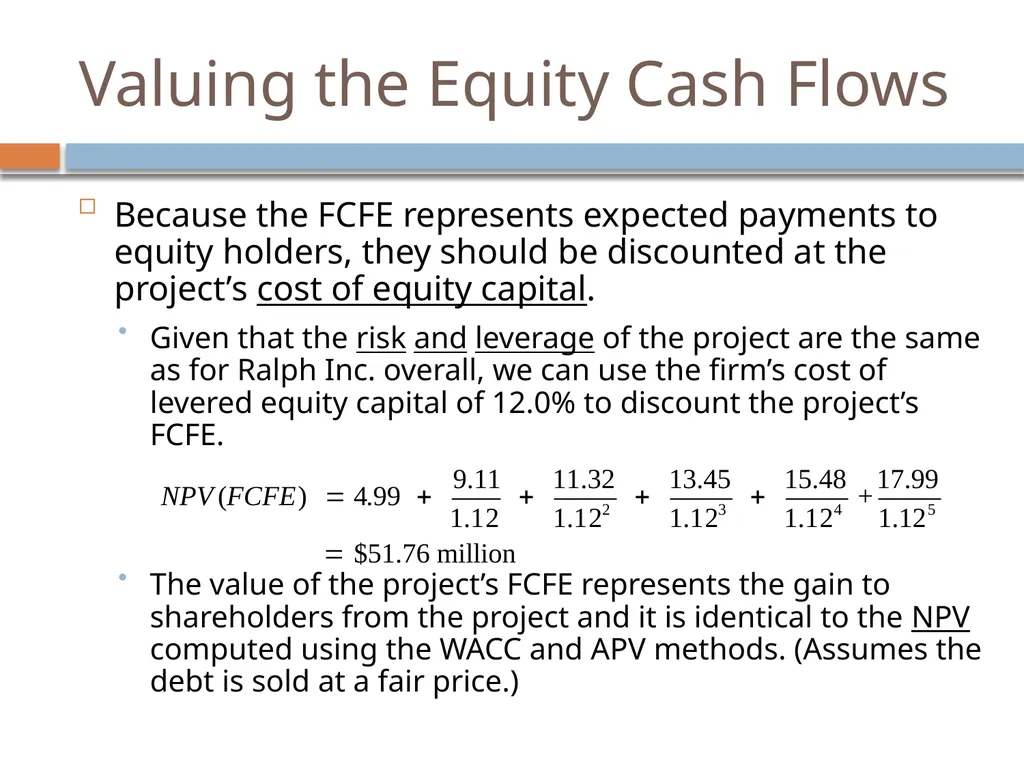
Valuing the Equity Cash Flows Because the FCFE represents expected payments to equity holders, they should be discounted at the project’s cost of equity capital.
Given that the risk and leverage of the project are the same as for Ralph Inc. overall, we can use the firm’s cost of levered equity capital of 12.0% to discount the project’s FCFE.
The value of the project’s FCFE represents the gain to shareholders from the project and it is identical to the NPV computed using the WACC and APV methods. (Assumes the debt is sold at a fair price.)<br>
30
Project-Based Costs of Capital Any specific project may have different systematic risk than the average project for the firm.
In addition, different projects will may also vary in the amount of leverage they will support.
In other words, let’s relax those initial simplifying assumptions.<br>
In addition, different projects will may also vary in the amount of leverage they will support.
In other words, let’s relax those initial simplifying assumptions.<br>
31
Estimating the Unlevered Cost of Capital Suppose the project Ralph launches faces different market risks than its main business.
The unlevered cost of capital for the new project can be estimated by looking at publicly traded, pure play firms that have similar business risk.<br>
The unlevered cost of capital for the new project can be estimated by looking at publicly traded, pure play firms that have similar business risk.<br>
32
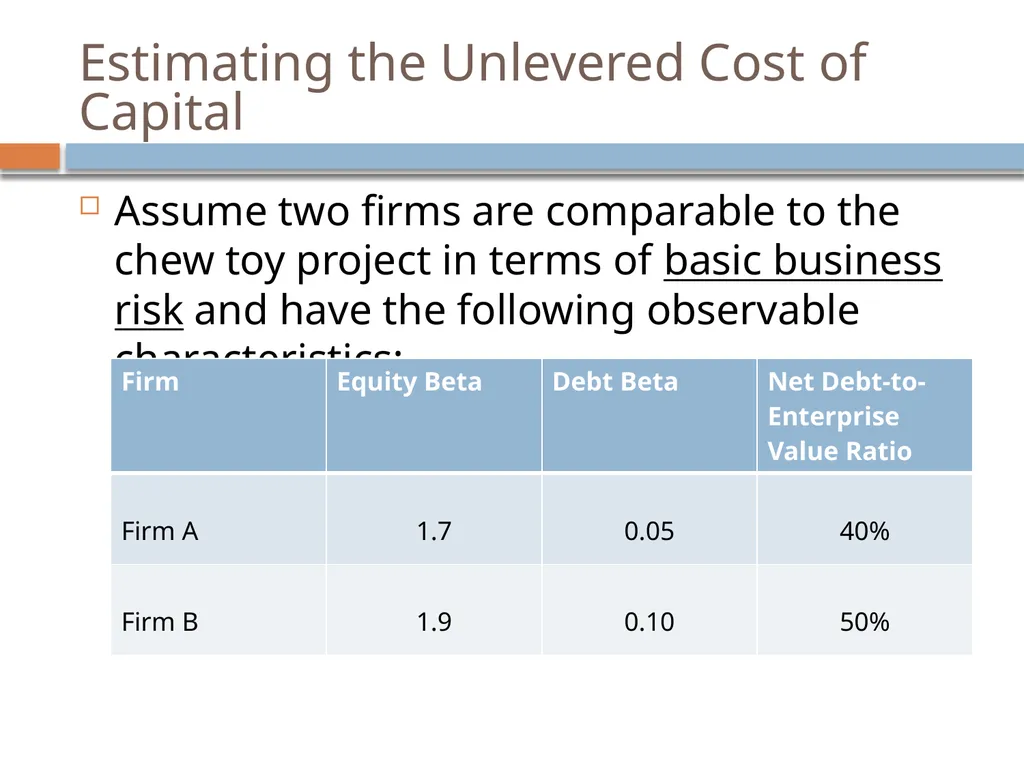
Estimating the Unlevered Cost of Capital Assume two firms are comparable to the chew toy project in terms of basic business risk and have the following observable characteristics:<br>
33
Estimating the Unlevered Cost
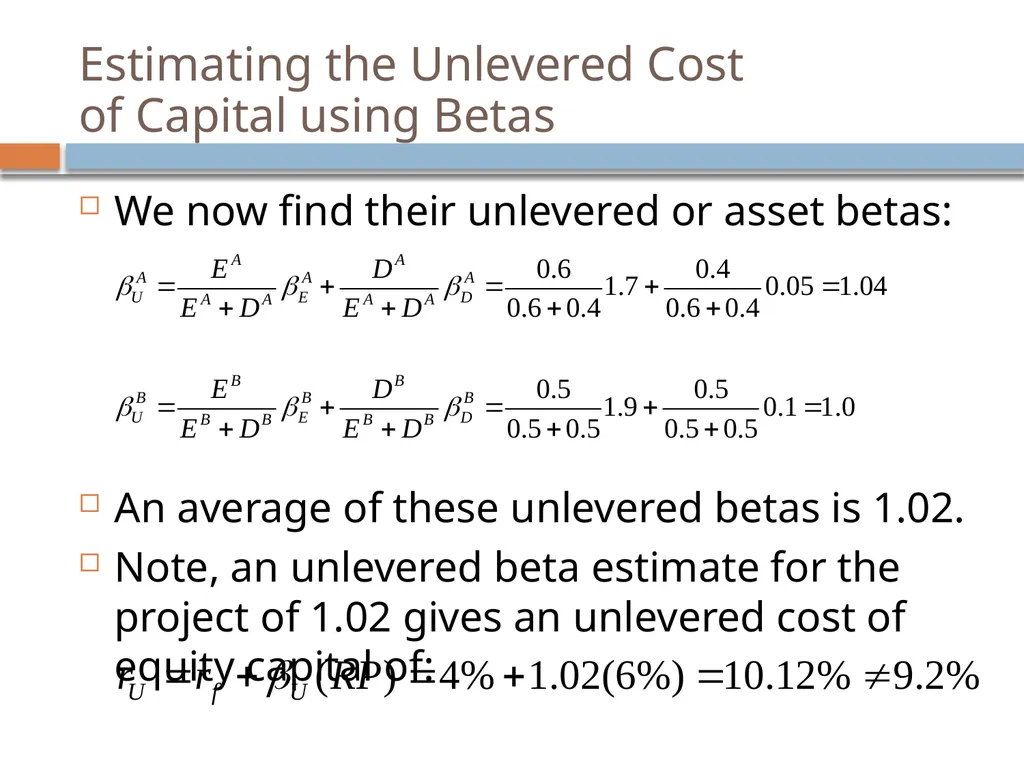
of Capital using Betas We now find their unlevered or asset betas:
An average of these unlevered betas is 1.02.
Note, an unlevered beta estimate for the project of 1.02 gives an unlevered cost of equity capital of:<br>
An average of these unlevered betas is 1.02.
Note, an unlevered beta estimate for the project of 1.02 gives an unlevered cost of equity capital of:<br>
34
Project Leverage
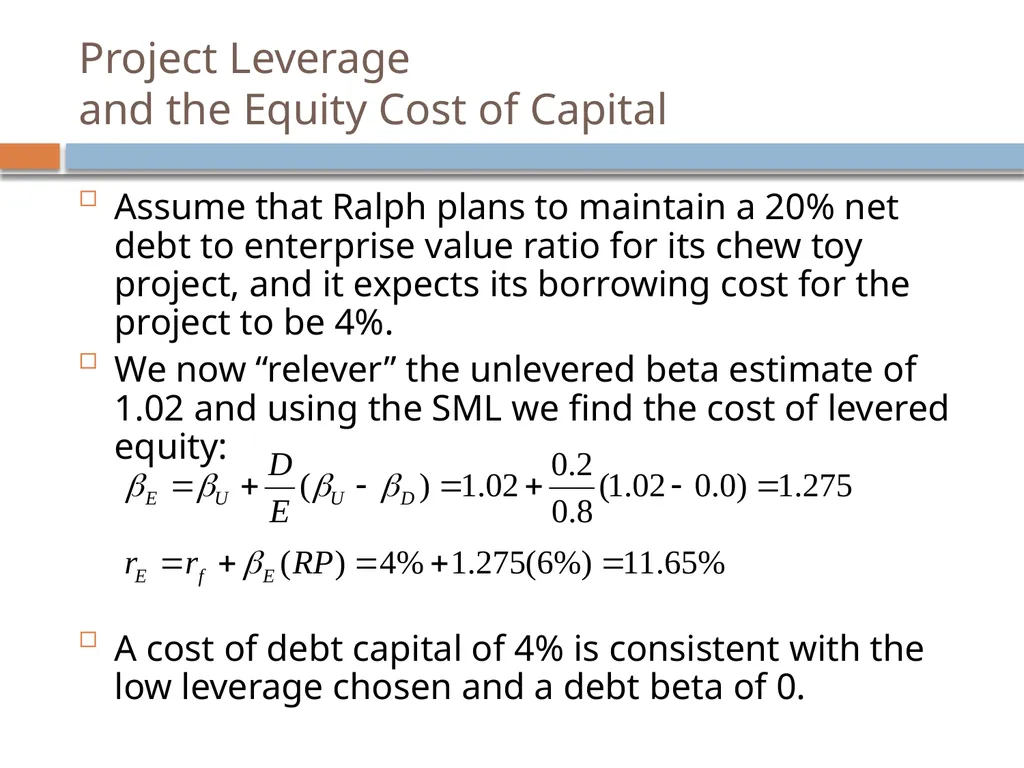
and the Equity Cost of Capital Assume that Ralph plans to maintain a 20% net debt to enterprise value ratio for its chew toy project, and it expects its borrowing cost for the project to be 4%.
We now “relever” the unlevered beta estimate of 1.02 and using the SML we find the cost of levered equity:
A cost of debt capital of 4% is consistent with the low leverage chosen and a debt beta of 0.<br>
We now “relever” the unlevered beta estimate of 1.02 and using the SML we find the cost of levered equity:
A cost of debt capital of 4% is consistent with the low leverage chosen and a debt beta of 0.<br>
35
Project Leverage and the
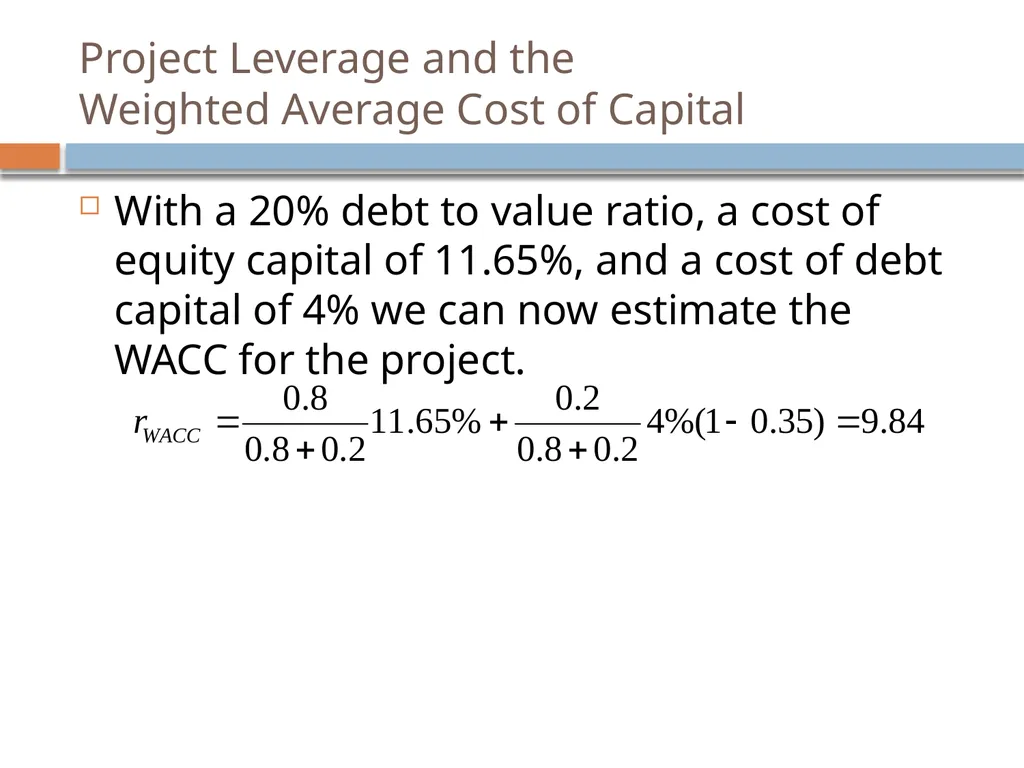
Weighted Average Cost of Capital With a 20% debt to value ratio, a cost of equity capital of 11.65%, and a cost of debt capital of 4% we can now estimate the WACC for the project.<br>
36
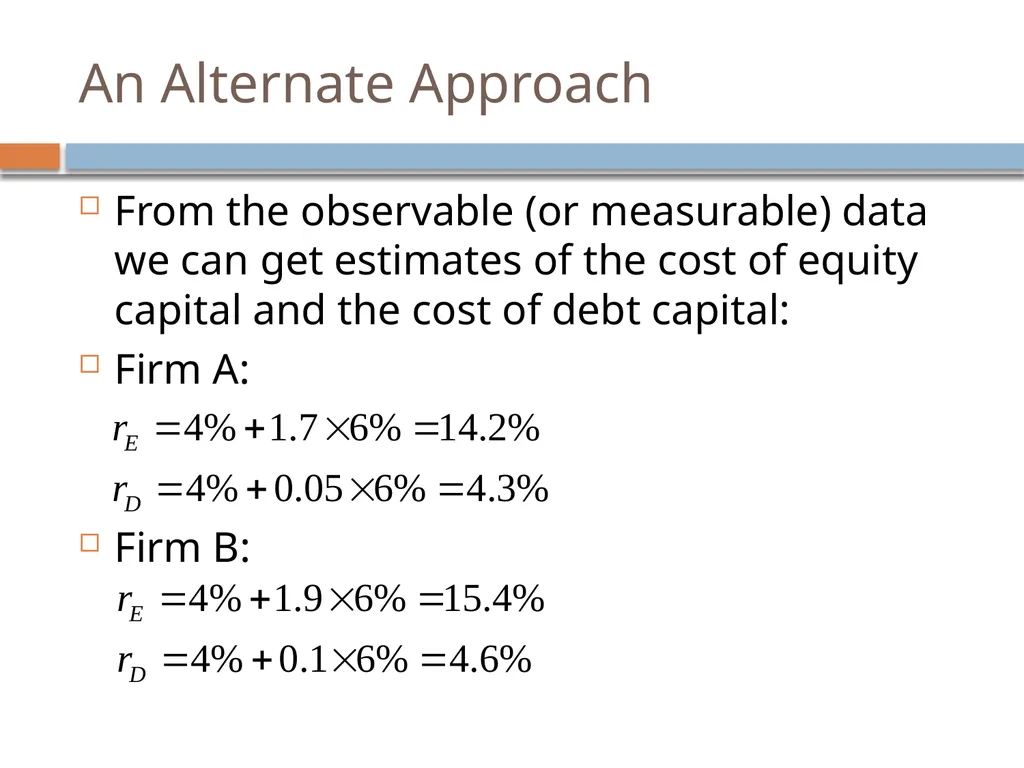
An Alternate Approach From the observable (or measurable) data we can get estimates of the cost of equity capital and the cost of debt capital:
Firm A:
Firm B:<br>
Firm A:
Firm B:<br>
37
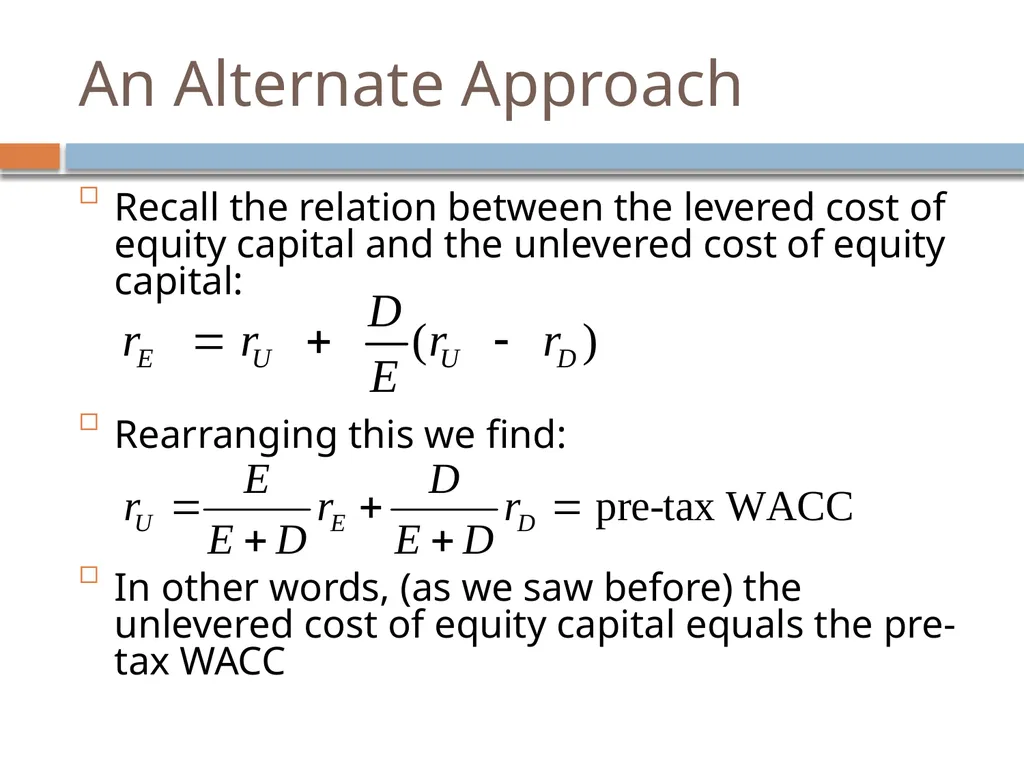
An Alternate Approach Recall the relation between the levered cost of equity capital and the unlevered cost of equity capital:
Rearranging this we find:
In other words, (as we saw before) the unlevered cost of equity capital equals the pre-tax WACC<br>
Rearranging this we find:
In other words, (as we saw before) the unlevered cost of equity capital equals the pre-tax WACC<br>
38
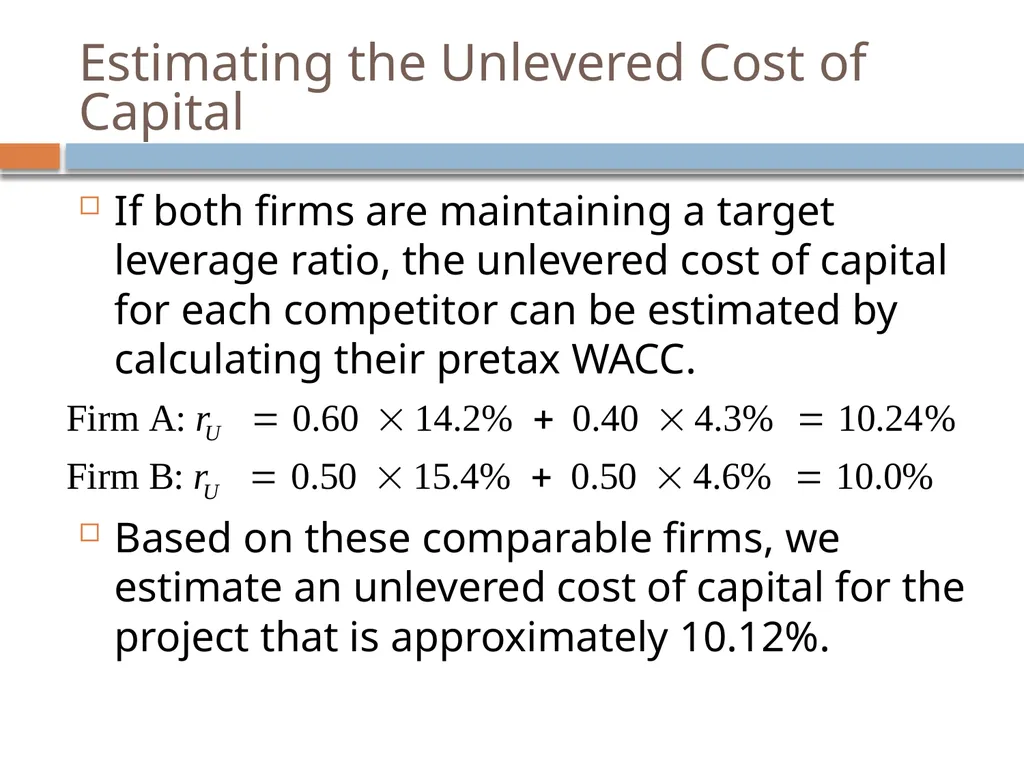
Estimating the Unlevered Cost of Capital If both firms are maintaining a target leverage ratio, the unlevered cost of capital for each competitor can be estimated by calculating their pretax WACC.
Based on these comparable firms, we estimate an unlevered cost of capital for the project that is approximately 10.12%.<br>
Based on these comparable firms, we estimate an unlevered cost of capital for the project that is approximately 10.12%.<br>
39
Project Leverage
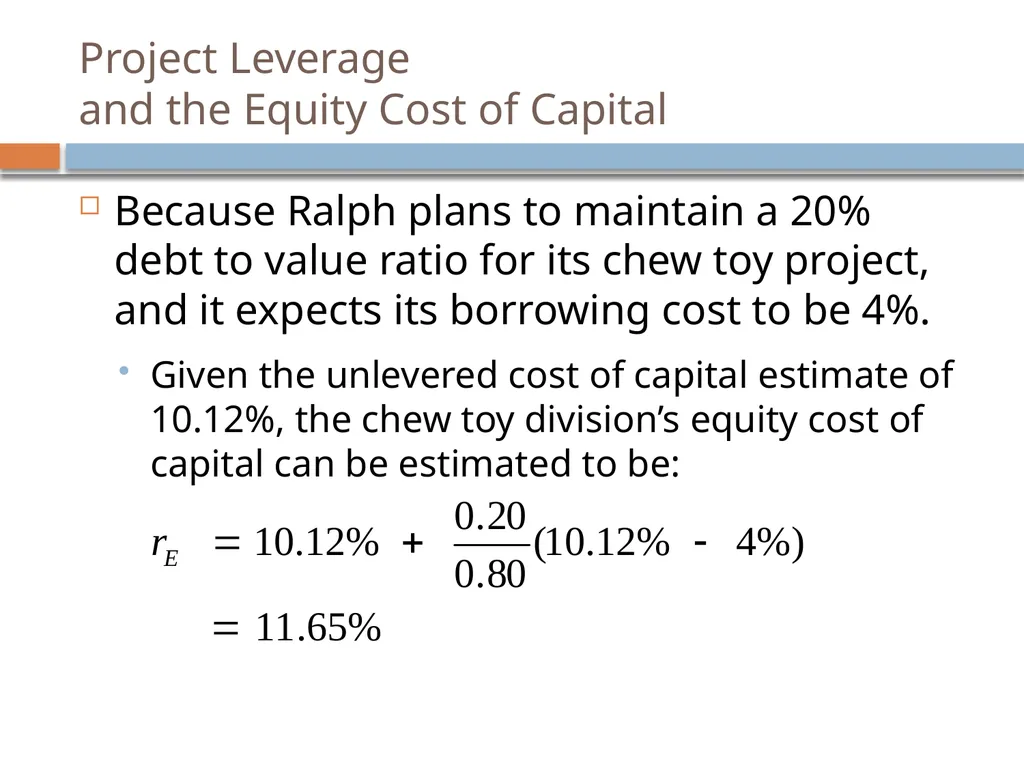
and the Equity Cost of Capital Because Ralph plans to maintain a 20% debt to value ratio for its chew toy project, and it expects its borrowing cost to be 4%.
Given the unlevered cost of capital estimate of 10.12%, the chew toy division’s equity cost of capital can be estimated to be:<br>
Given the unlevered cost of capital estimate of 10.12%, the chew toy division’s equity cost of capital can be estimated to be:<br>
40
Project Leverage and the
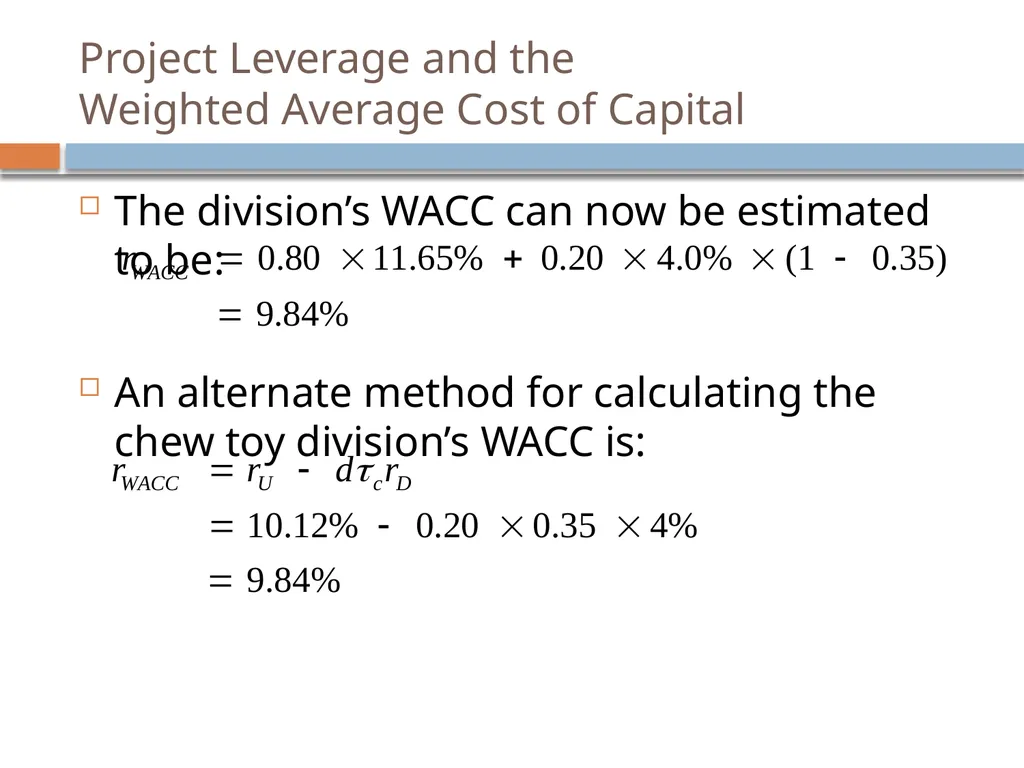
Weighted Average Cost of Capital The division’s WACC can now be estimated to be:
An alternate method for calculating the chew toy division’s WACC is:<br>
An alternate method for calculating the chew toy division’s WACC is:<br>