
What Have We Learned from Experimental FInance?
MT
Published · 46 slides · 0 views
1 / 1
Description
What Have We Learned from Experimental FInance? Shyam Sunder Yale School of Management Kozminski Academy Warsaw, Poland June 23, 2012 (c) Copyright 2003, Shyam Sunder 2 Questions to Address Why do we need even more data on financial
Related Topics
Share
Embed code
Download this presentation From Below
"What Have We Learned from Experimental FInance?" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
What Have We Learned from Experimental FInance? Shyam Sunder
Yale School of Management
Kozminski Academy
Warsaw, Poland
June 23, 2012<br>
Yale School of Management
Kozminski Academy
Warsaw, Poland
June 23, 2012<br>
02
(c) Copyright 2003, Shyam Sunder 2 Questions to Address Why do we need even more data on financial markets?
How could the data from such simple “Mickey Mouse” markets help us in a far more complex investment environment?
Is experimental finance a branch or variation of behavioral economics/behavioral finance?
What have we learned so far from asset market experiments?
What is next?<br>
How could the data from such simple “Mickey Mouse” markets help us in a far more complex investment environment?
Is experimental finance a branch or variation of behavioral economics/behavioral finance?
What have we learned so far from asset market experiments?
What is next?<br>
03
(c) Copyright 2003, Shyam Sunder 3 1. Why Do We Need More Data from Experimental Markets? Of all branches of economics, financial economics probably has the most detailed and up-to-date observational data available
Consequently, this branch of economics is characterized by one of the strongest empirical traditions
Why, then, spend time and money to conduct experiments with financial markets and gather more data?<br>
Consequently, this branch of economics is characterized by one of the strongest empirical traditions
Why, then, spend time and money to conduct experiments with financial markets and gather more data?<br>
04
(c) Copyright 2003, Shyam Sunder 4 Transactions v. Expectations Data from the stock exchanges include bids, asks, transaction prices, volume, etc.
Data from information services on actions and events that may influence markets
Neither does or can report on expectations
Theory of financial markets (and economics of uncertainty) is built on expectations
Need data on expectations to empirically distinguish among competing theories<br>
Data from information services on actions and events that may influence markets
Neither does or can report on expectations
Theory of financial markets (and economics of uncertainty) is built on expectations
Need data on expectations to empirically distinguish among competing theories<br>
05
(c) Copyright 2003, Shyam Sunder 5 Relating Market Actions to Expectations and Parameters In experimental markets, the researcher knows the expectations, and the underlying parameters
With this knowledge, we know the price and other predictions of alternative theories
We can therefore conduct powerful tests of theories which were not possible from the field data (because we know little about the parameters and expectations that generate the field data from the stock exchanges).
Examples to follow<br>
06
(c) Copyright 2003, Shyam Sunder 6 2. What Can Simple Experiments Tell Us about Complex Markets? Experimental markets are typically conducted in simple settings
Student subjects of typical laboratory experiments have little experience
Security markets are complex, and populated by experienced professionals
What could we possibly learn from experiments about the “real” markets?<br>
Student subjects of typical laboratory experiments have little experience
Security markets are complex, and populated by experienced professionals
What could we possibly learn from experiments about the “real” markets?<br>
07
(c) Copyright 2003, Shyam Sunder 7 Simplicity is Science All sciences aim at finding simple principles that explain or predict a large part (rarely all) of the phenomenon of interest
Simple models: in math or in laboratory make core as well as convenience assumptions
The power of a theory depends on the robustness of its predictions as the data environments deviate from the assumptions of convenience<br>
Simple models: in math or in laboratory make core as well as convenience assumptions
The power of a theory depends on the robustness of its predictions as the data environments deviate from the assumptions of convenience<br>
08
(c) Copyright 2003, Shyam Sunder 8 Simple Experiments Help Discover/Verify Basic Principles How do we learn to count?
How do we learn to swim?
How do we learn the laws of electricity?
Noise generated by countless factors in complex environments makes it difficult to detect the fundamental principles
Simple math and laboratory models help us learn better, before we immerse ourselves in the complexity of the real phenomena
If the principle is general, it better be applicable to the simple environments<br>
09
(c) Copyright 2003, Shyam Sunder 9 3. Is This Behavioral Economics/Finance? Experimental economics: emphasis is on design of market and other economic institutions to gather empirical data
Institutions and rules matter (e.g., microstructure)
People do what they think is best for them, given what they know (they learn, are not dumb)
Design experiments to sort out the claims of competing theories
Engineer test beds for alternative institutions
Focus on equilibrium, efficiency, prices, and allocations
Complements modeling and field empirical research<br>
10
(c) Copyright 2003, Shyam Sunder 10 4. What Have We Learned from Experiments? Within the past two decades, asset market experiments have revealed some important findings by exploiting their advantages
These findings were not, and could not have been, reached from the field data alone
We shall summarize a few key findings in the time available<br>
These findings were not, and could not have been, reached from the field data alone
We shall summarize a few key findings in the time available<br>
11
(c) Copyright 2003, Shyam Sunder 11 Key Findings Security markets can aggregate and disseminate information (efficient markets)
But they do not always do so (inefficiency)
Information dissemination, when it occurs, is rarely instantaneous or perfect (learning takes time)
Markets permit costly research to persist in equilibrium (why pay for research?)
Price, as well as bids, offers, timing, etc., transmit information (many channels for information flow)<br>
12
(c) Copyright 2003, Shyam Sunder 12 More Findings Well-functioning derivative markets help improve the efficiency of primary markets
Most important: statistical efficiency or inability to make money from past data does not mean informational efficiency (can’t make money the price is right)<br>
Most important: statistical efficiency or inability to make money from past data does not mean informational efficiency (can’t make money the price is right)<br>
13
(c) Copyright 2003, Shyam Sunder 13 Efficient Markets: Information Dissemination Can markets disseminate information from those who know to those who don’t?
Could not be established from analysis of field data because we don’t know the distribution of information among investors
Plott and Sunder (Journal of Political Economy, 1982) established the basic proposition through a simple experiment<br>
Could not be established from analysis of field data because we don’t know the distribution of information among investors
Plott and Sunder (Journal of Political Economy, 1982) established the basic proposition through a simple experiment<br>
14
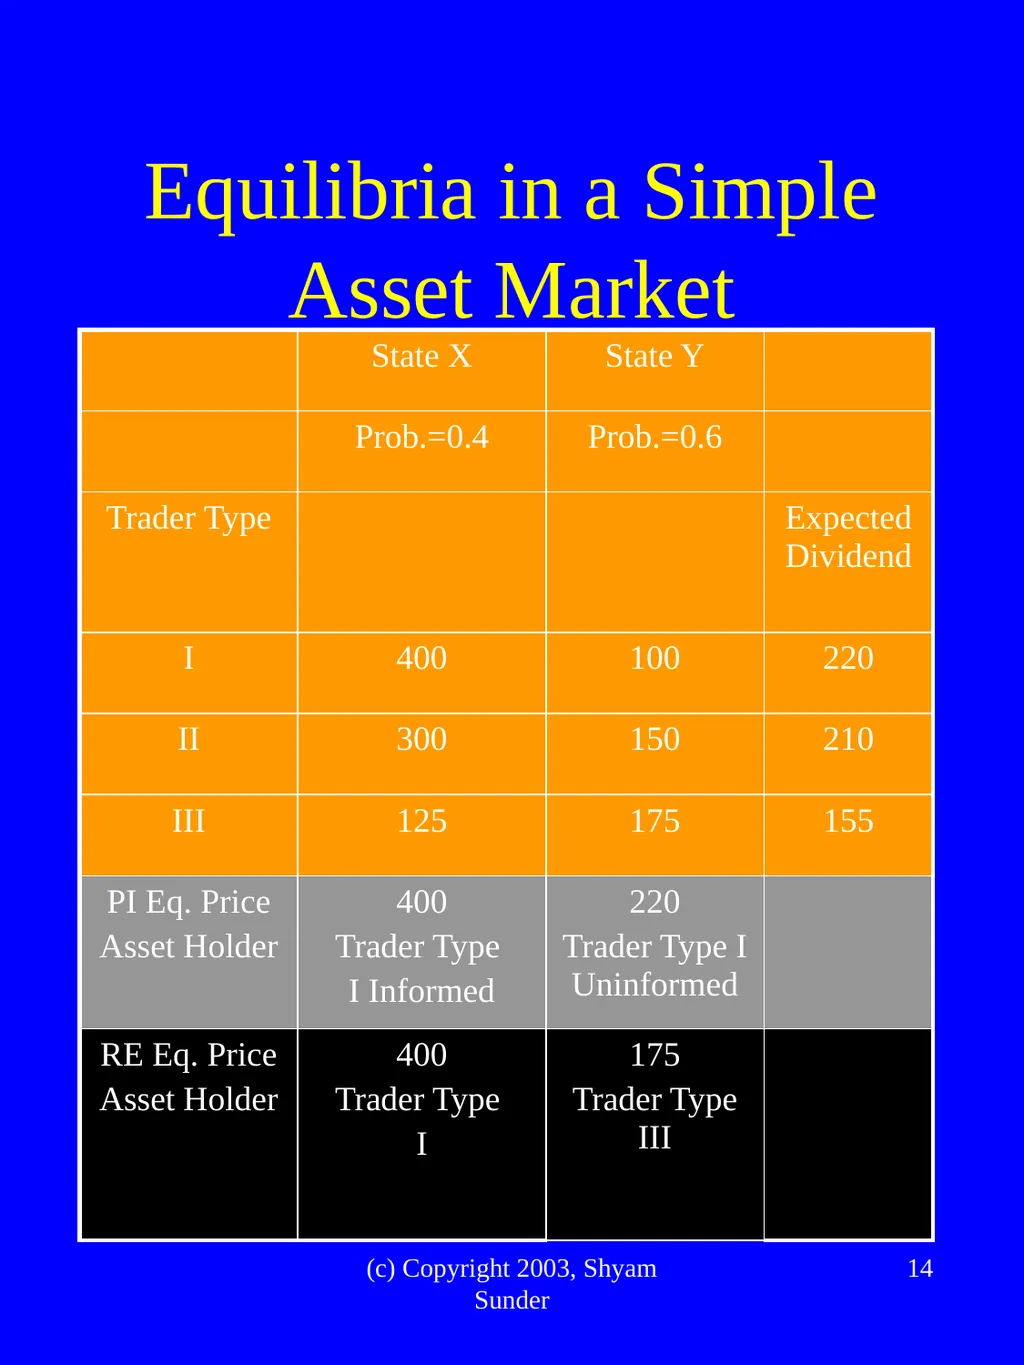
(c) Copyright 2003, Shyam Sunder 14 Equilibria in a Simple Asset Market<br>
15
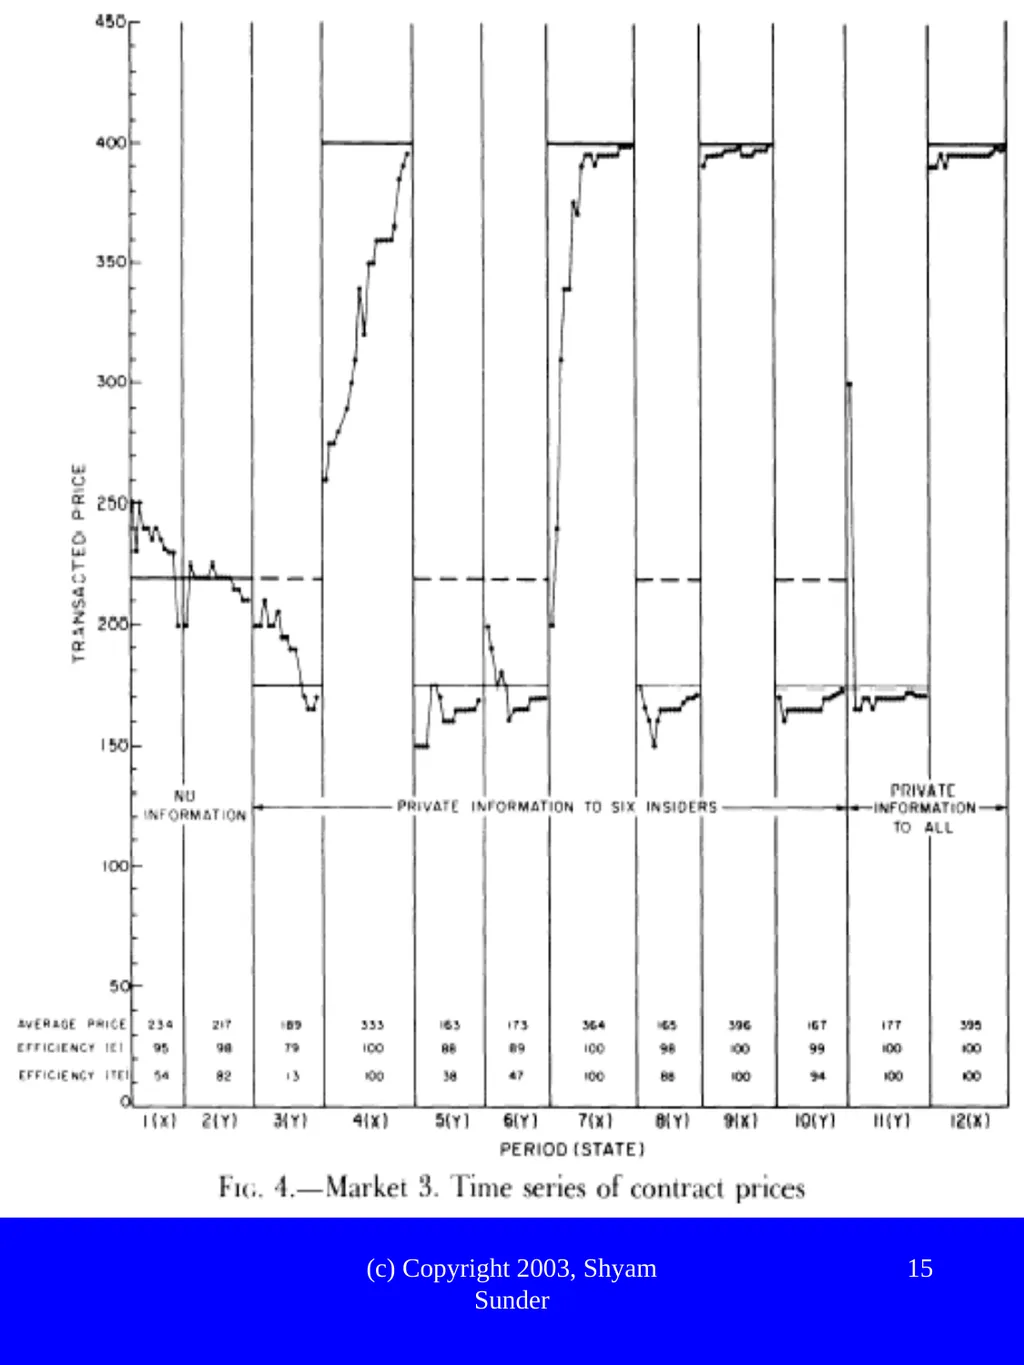
(c) Copyright 2003, Shyam Sunder 15<br>
16
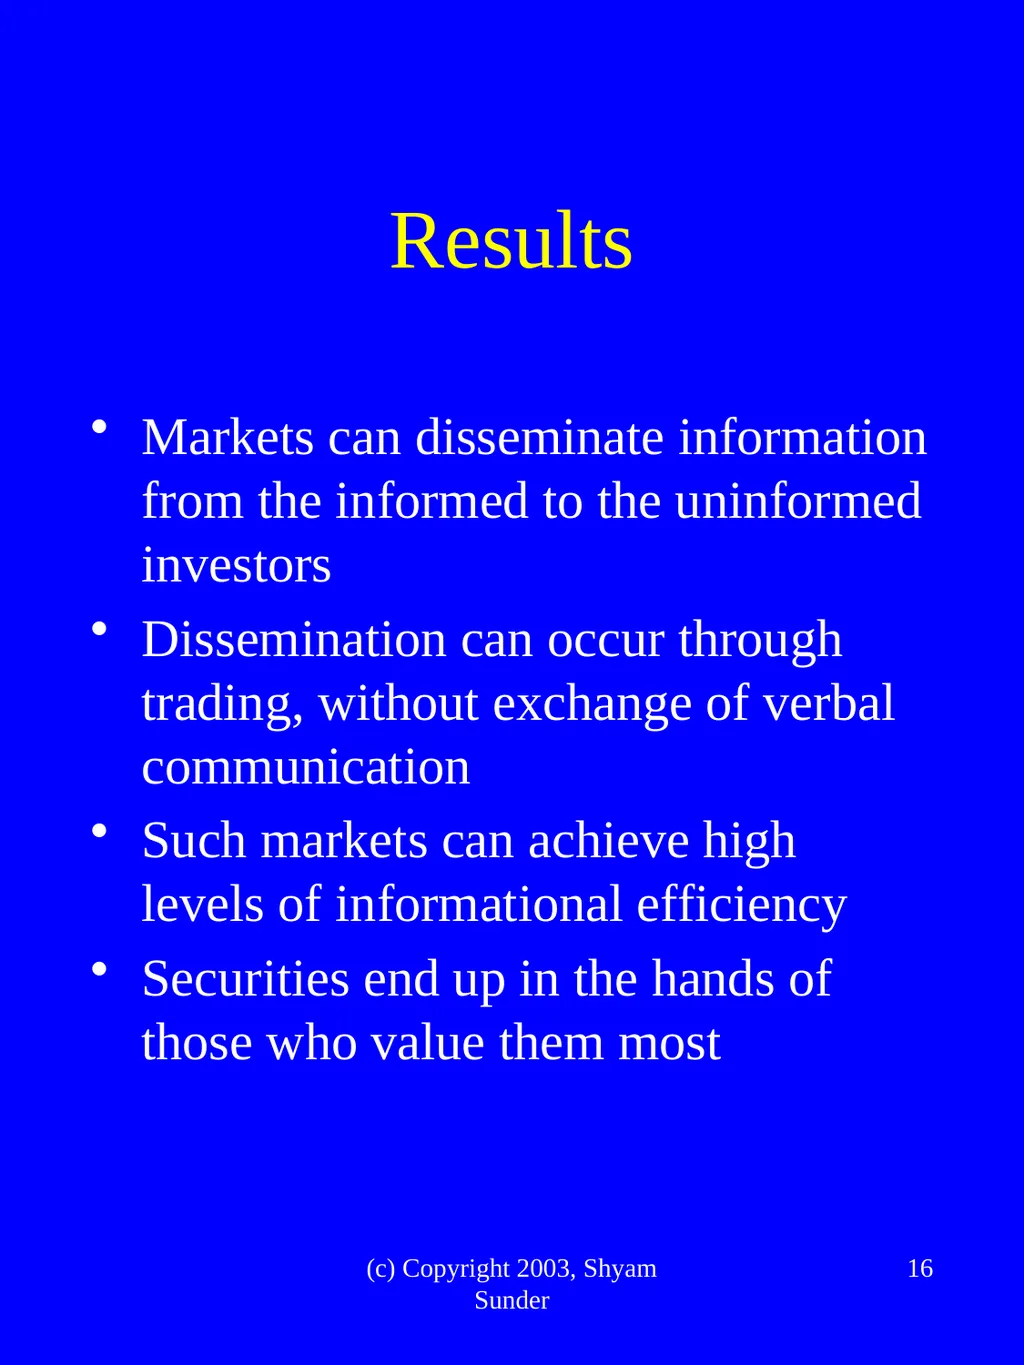
(c) Copyright 2003, Shyam Sunder 16 Results Markets can disseminate information from the informed to the uninformed investors
Dissemination can occur through trading, without exchange of verbal communication
Such markets can achieve high levels of informational efficiency
Securities end up in the hands of those who value them most<br>
Dissemination can occur through trading, without exchange of verbal communication
Such markets can achieve high levels of informational efficiency
Securities end up in the hands of those who value them most<br>
17
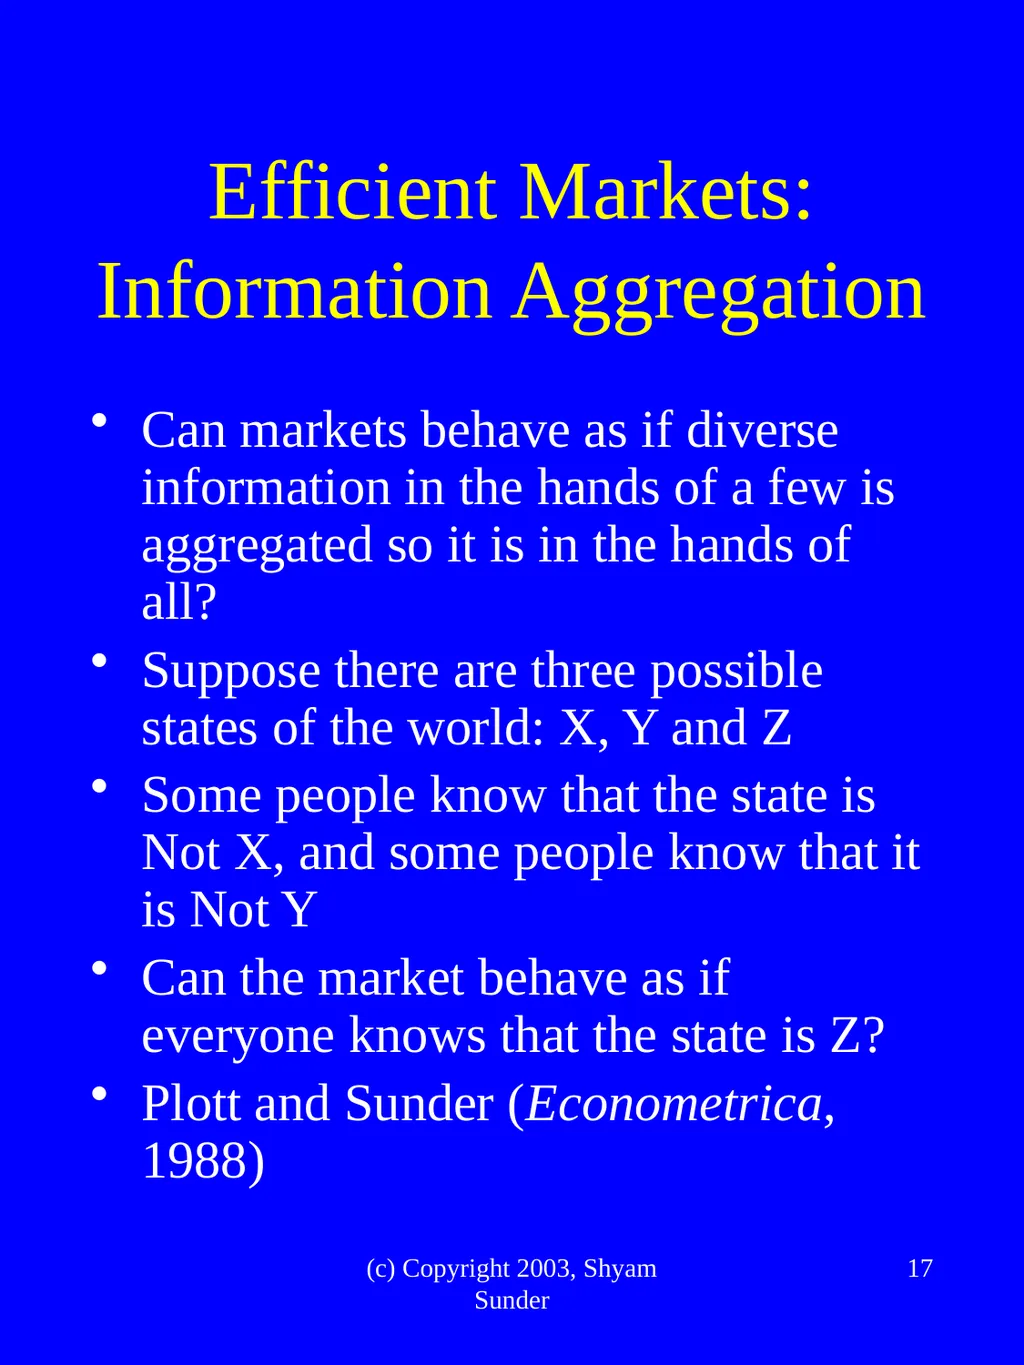
(c) Copyright 2003, Shyam Sunder 17 Efficient Markets: Information Aggregation Can markets behave as if diverse information in the hands of a few is aggregated so it is in the hands of all?
Suppose there are three possible states of the world: X, Y and Z
Some people know that the state is Not X, and some people know that it is Not Y
Can the market behave as if everyone knows that the state is Z?
Plott and Sunder (Econometrica, 1988)<br>
Suppose there are three possible states of the world: X, Y and Z
Some people know that the state is Not X, and some people know that it is Not Y
Can the market behave as if everyone knows that the state is Z?
Plott and Sunder (Econometrica, 1988)<br>
18
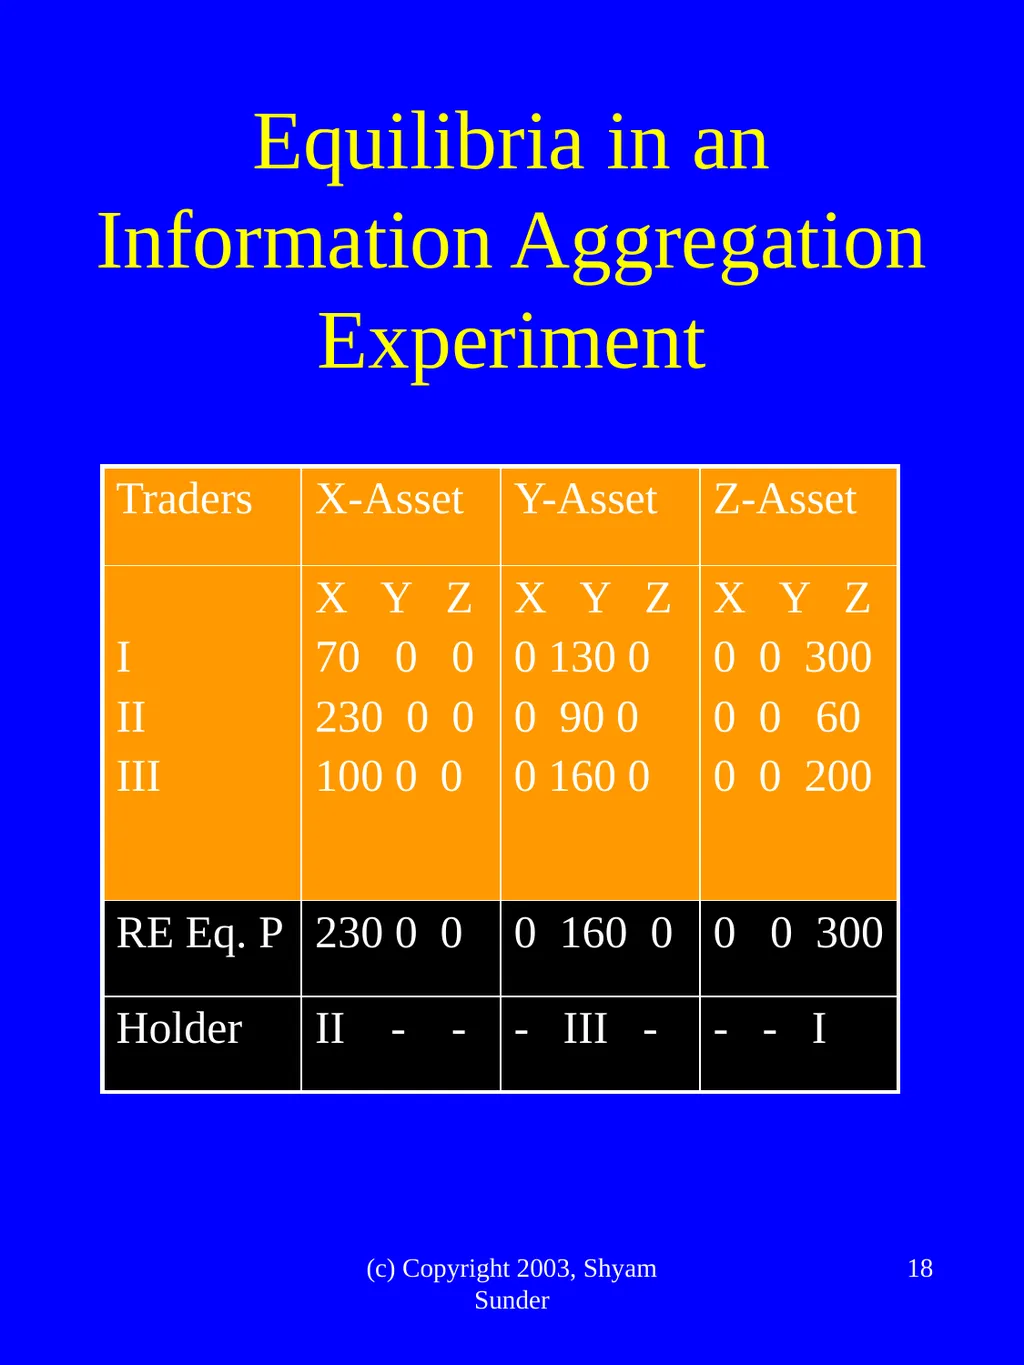
(c) Copyright 2003, Shyam Sunder 18 Equilibria in an Information Aggregation Experiment<br>
19
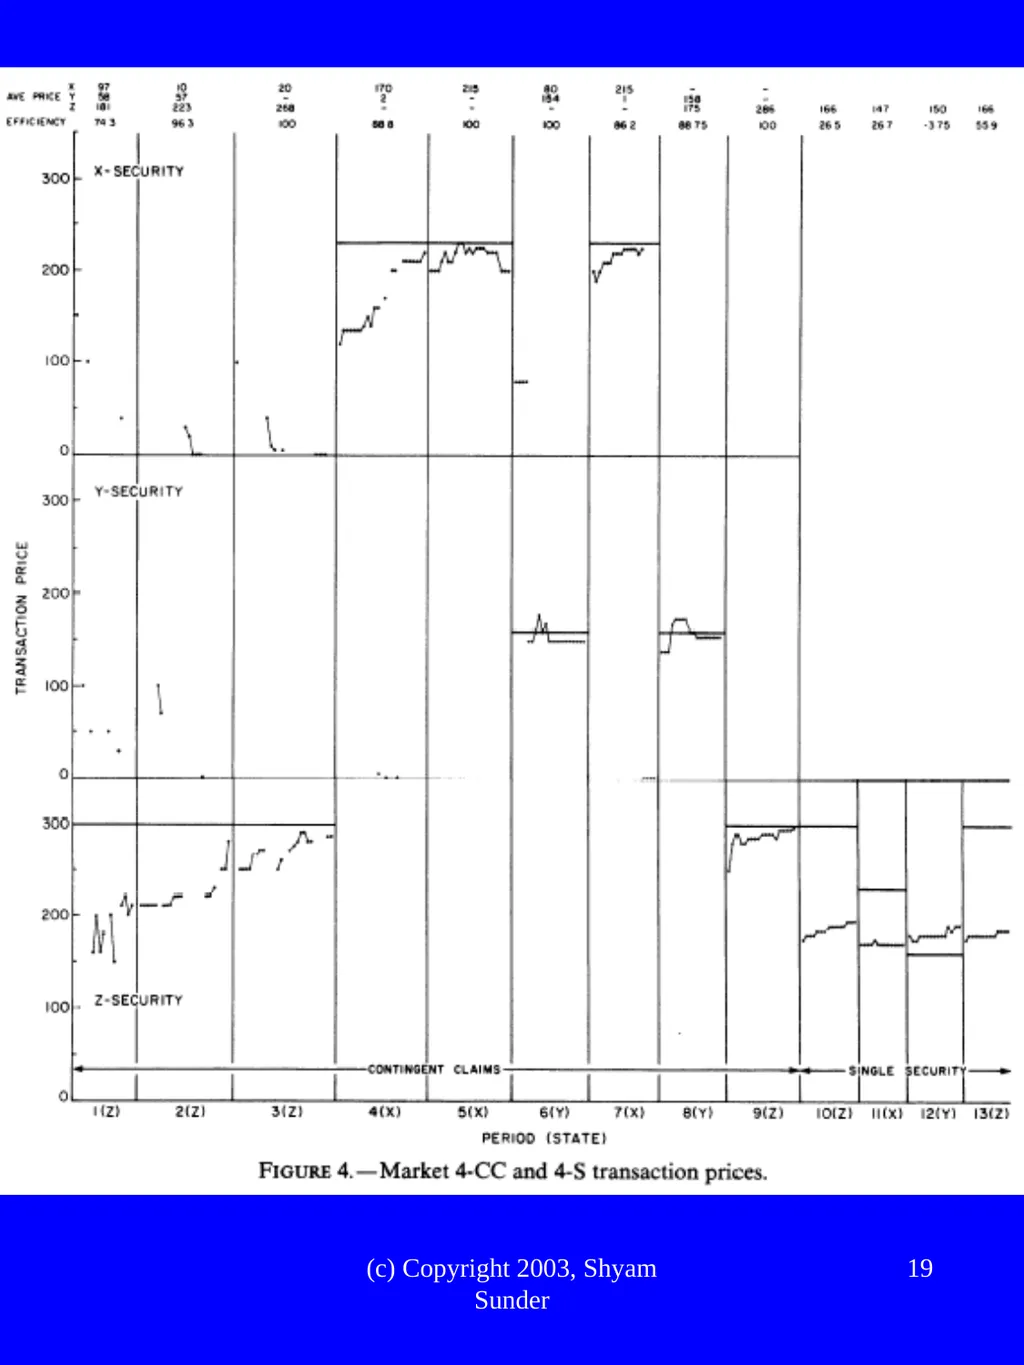
(c) Copyright 2003, Shyam Sunder 19<br>
20
(c) Copyright 2003, Shyam Sunder 20 Aggregation Results Complete markets can aggregate and disseminate diverse information
Such markets can achieve high information and allocative efficiency
Same happens when investors have homogenous preferences (which makes it easier for traders to infer information from actions of others)<br>
Such markets can achieve high information and allocative efficiency
Same happens when investors have homogenous preferences (which makes it easier for traders to infer information from actions of others)<br>
21
(c) Copyright 2003, Shyam Sunder 21 Inefficiency Just because markets can aggregate and disseminate information does not mean that all markets do so under all conditions
Experiments show that market conditions must allow investors the opportunity to learn the information from what they can observe
Even in these simple experimental markets, these conditions are not always satisfied (too many states, too few observations and repetitions to facilitate learning)
For example, a complete market for three Arrow-Debreu securities is efficient, but an incomplete market for a single security is not<br>
22
(c) Copyright 2003, Shyam Sunder 22 Learning Takes Time Even in the best of circumstances, equilibrium outcomes are not achieved instantaneously
Markets tend toward efficiency, but cannot achieve it instantaneously
It takes time for investors to observe, form conjectures, test them, modify their strategies, etc.
With repetition, investors get better at learning, but the environment changes continually, including the behavior of other investors; so the learning process never ends<br>
23
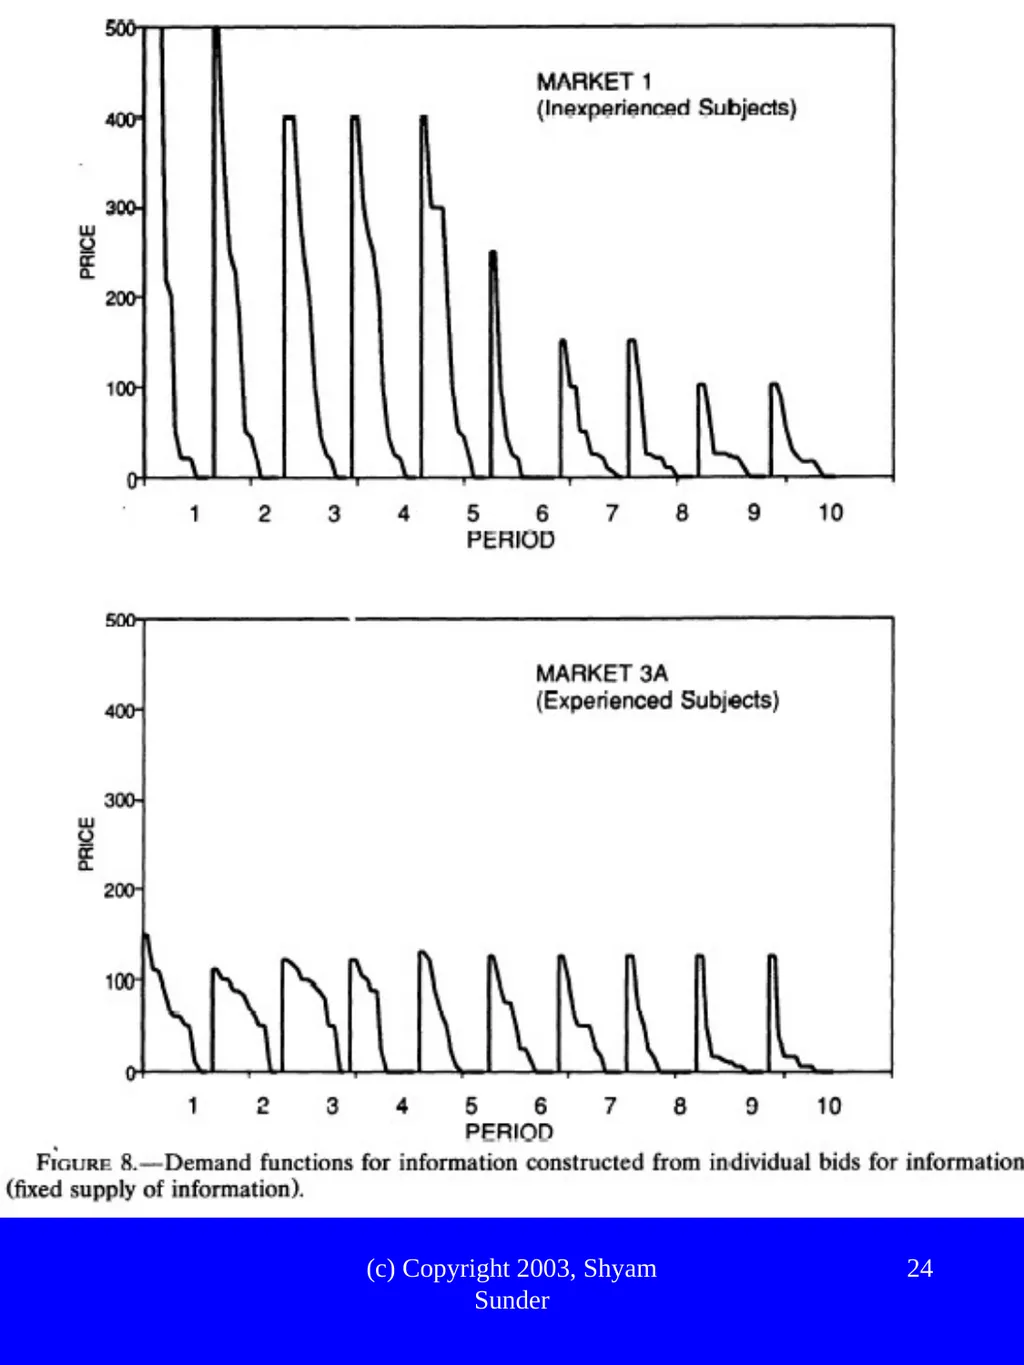
(c) Copyright 2003, Shyam Sunder 23 Why Pay for Research? This has been the conundrum of the efficient market theory: If the markets are efficient, why pay for research.
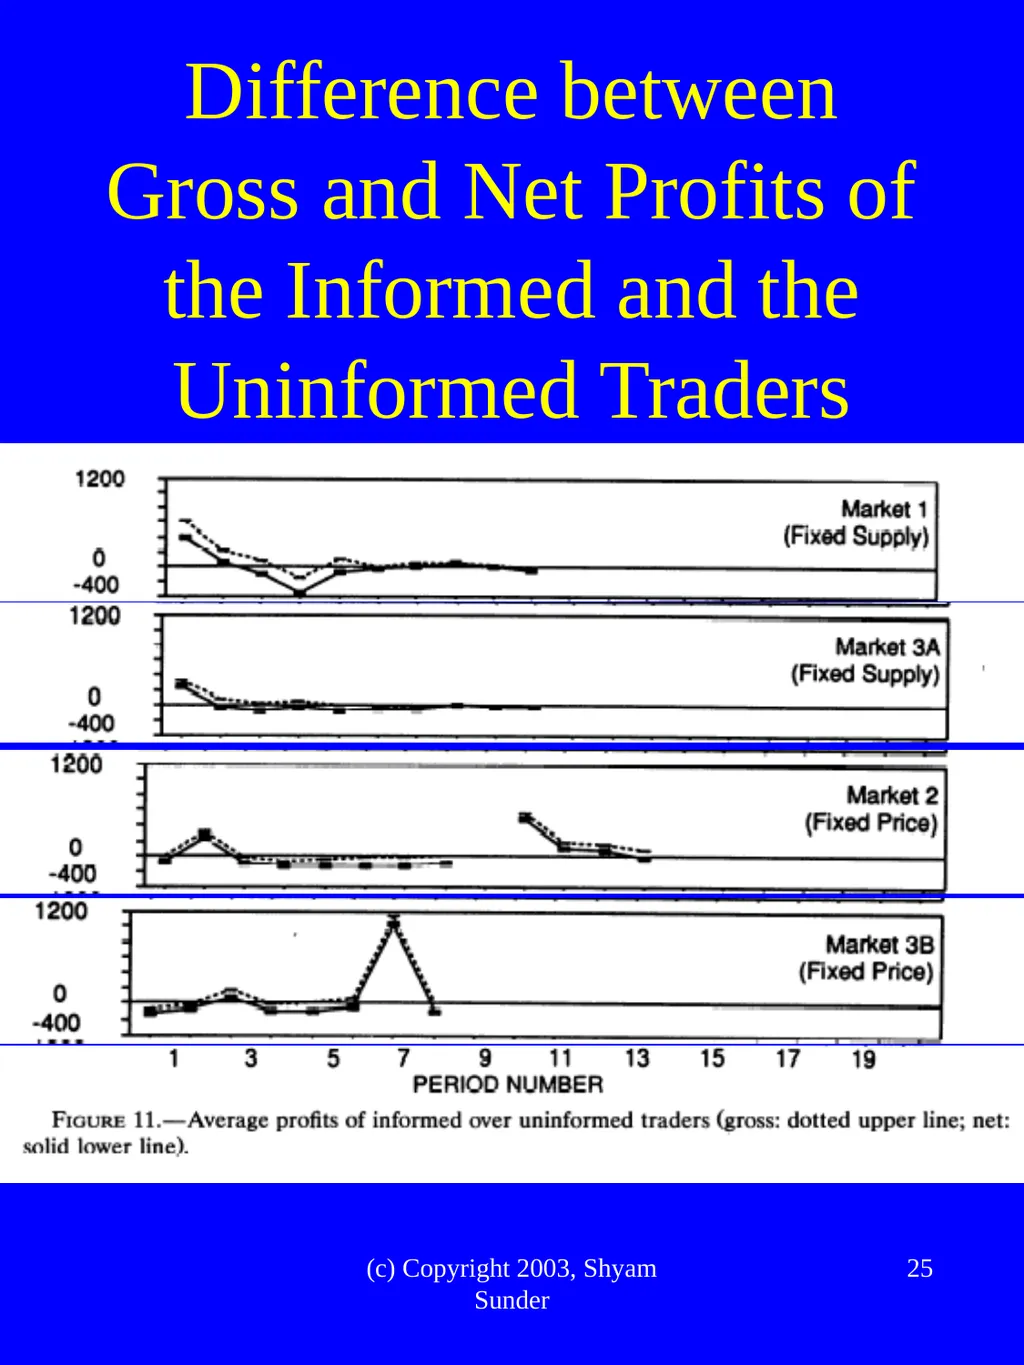
This finite rate of learning makes it possible to support costly research, even in markets which tend toward efficient outcomes
Enough people would conduct research so the average returns to research equal the average cost. Research users have higher gross profits, but their net profits are the same as the profits of the others
Sunder (Econometrica, 1993)<br>
24
(c) Copyright 2003, Shyam Sunder 24<br>
25
(c) Copyright 2003, Shyam Sunder 25 Difference between Gross and Net Profits of the Informed and the Uninformed Traders<br>
26
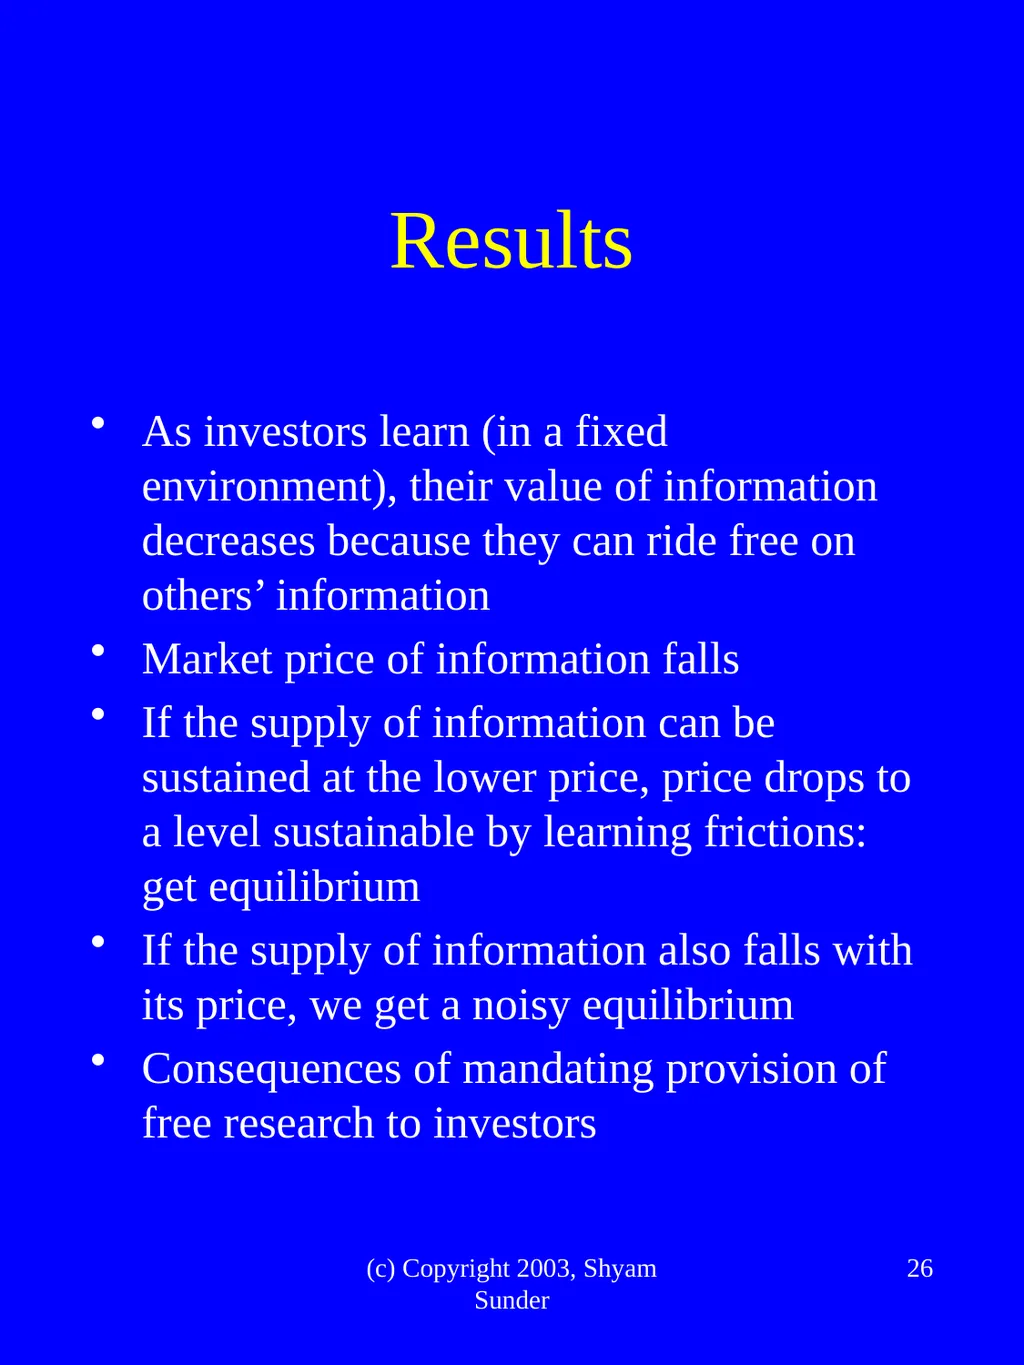
(c) Copyright 2003, Shyam Sunder 26 Results As investors learn (in a fixed environment), their value of information decreases because they can ride free on others’ information
Market price of information falls
If the supply of information can be sustained at the lower price, price drops to a level sustainable by learning frictions: get equilibrium
If the supply of information also falls with its price, we get a noisy equilibrium
Consequences of mandating provision of free research to investors<br>
27
(c) Copyright 2003, Shyam Sunder 27 Many Channels for Information Flow In economic theory, transaction prices are considered the primary vehicle for the transmission of information in markets
Experimental markets show that other observables (bids, asks, volume, timing, etc.) also transmit information in markets
In deep markets, price can be the result of the information transmission through these other variables
Example: see trading in period 8 on slide number 15<br>
Experimental markets show that other observables (bids, asks, volume, timing, etc.) also transmit information in markets
In deep markets, price can be the result of the information transmission through these other variables
Example: see trading in period 8 on slide number 15<br>
28
(c) Copyright 2003, Shyam Sunder 28 Effect of Derivatives on Primary Markets Derivative markets help increase the efficiency of primary markets
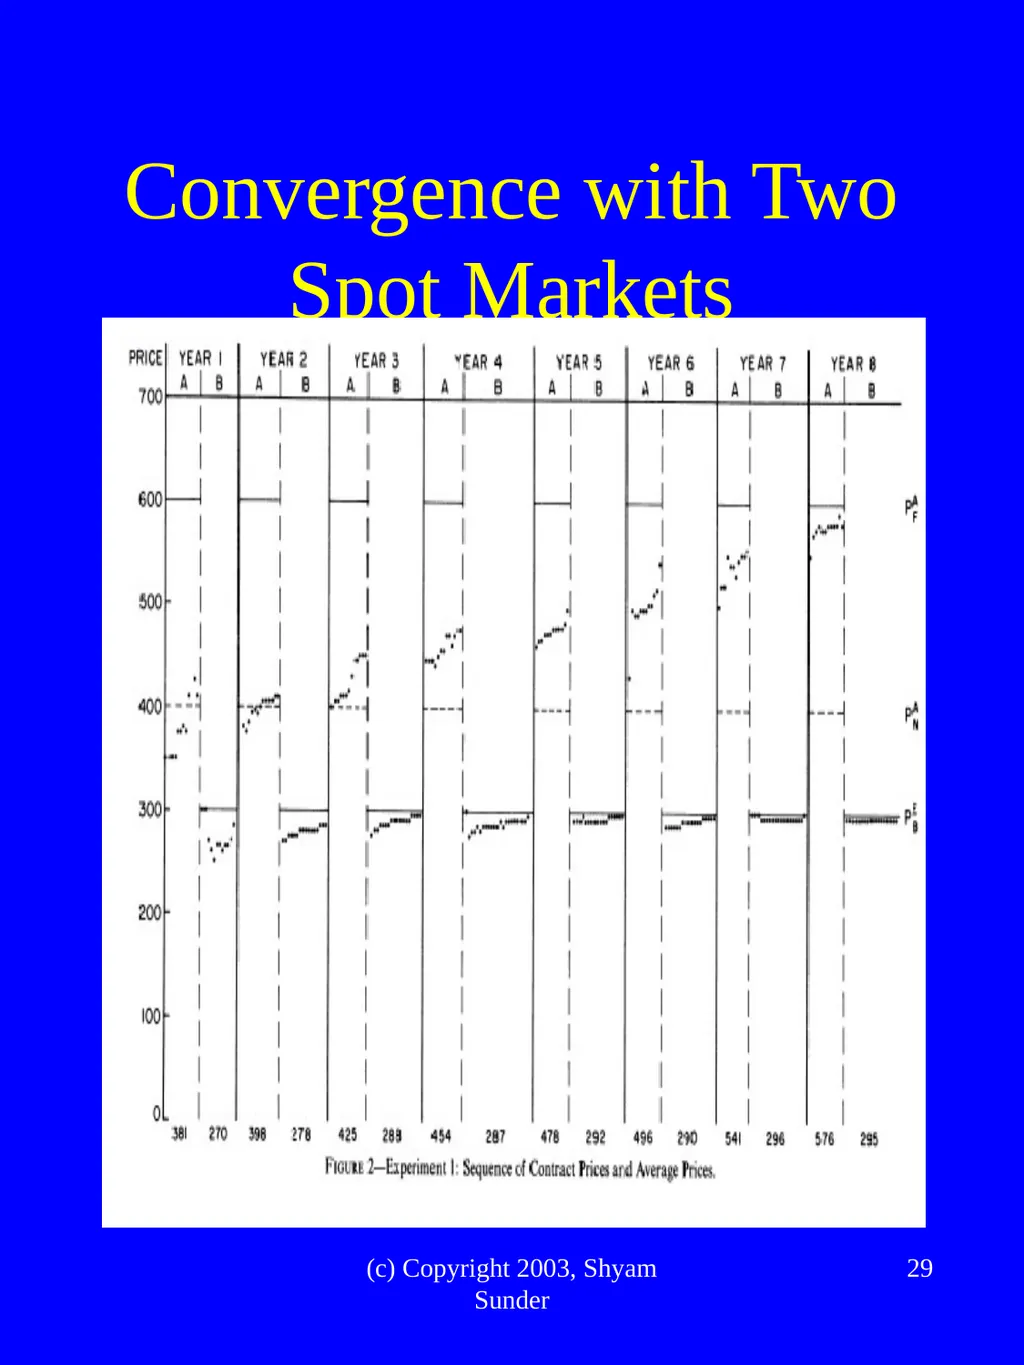
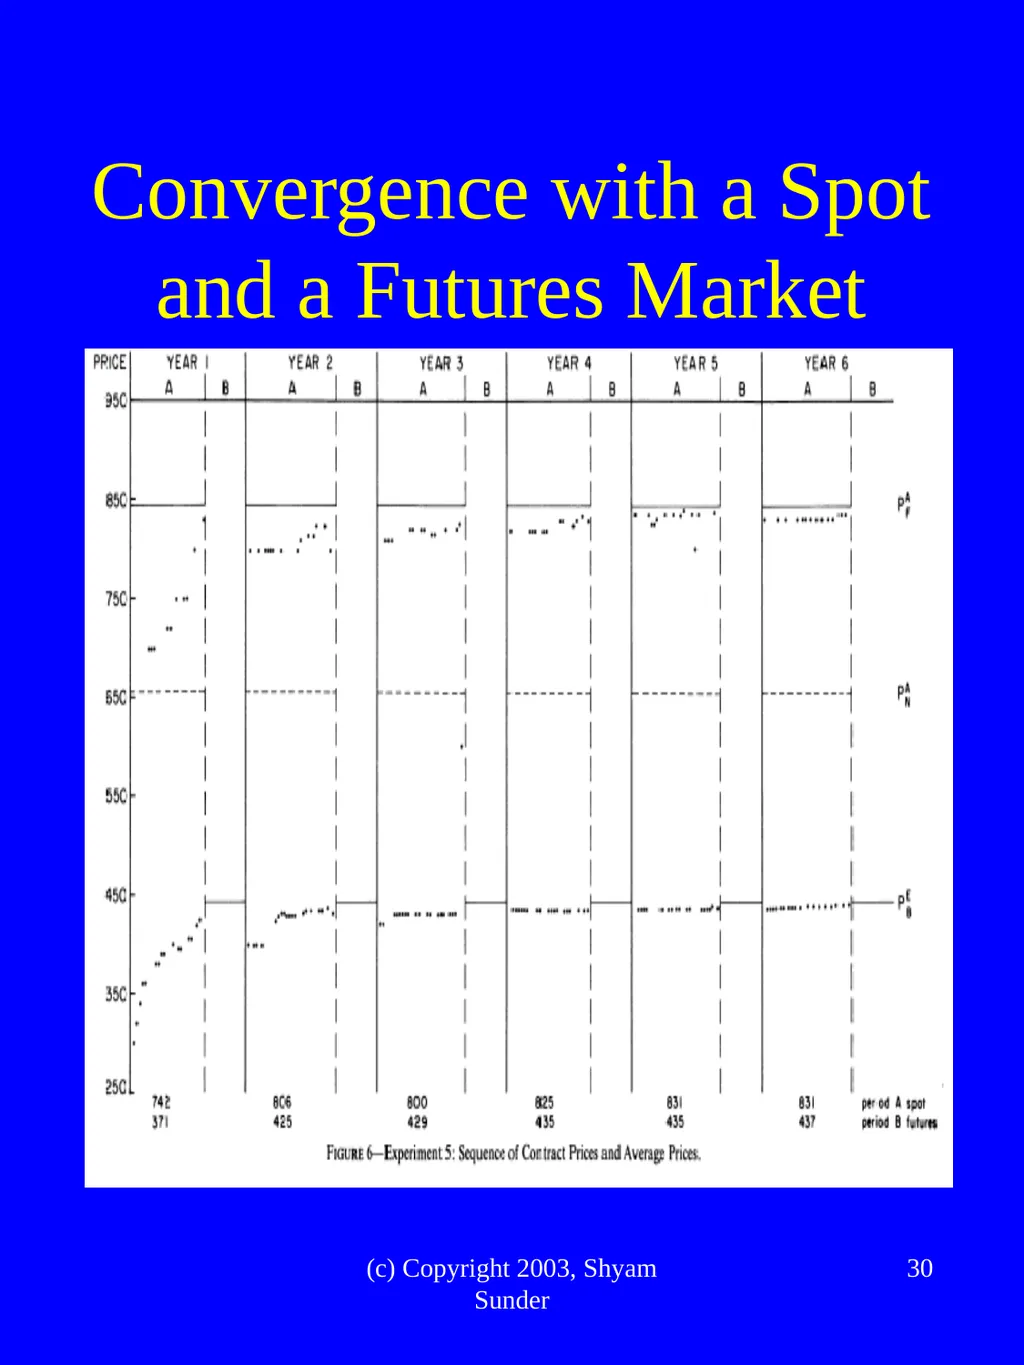
Forsythe, Palfrey and Plott (Econometrica 1982), the first asset market experiment, showed that futures markets speed up convergence to equilibrium in the primary market
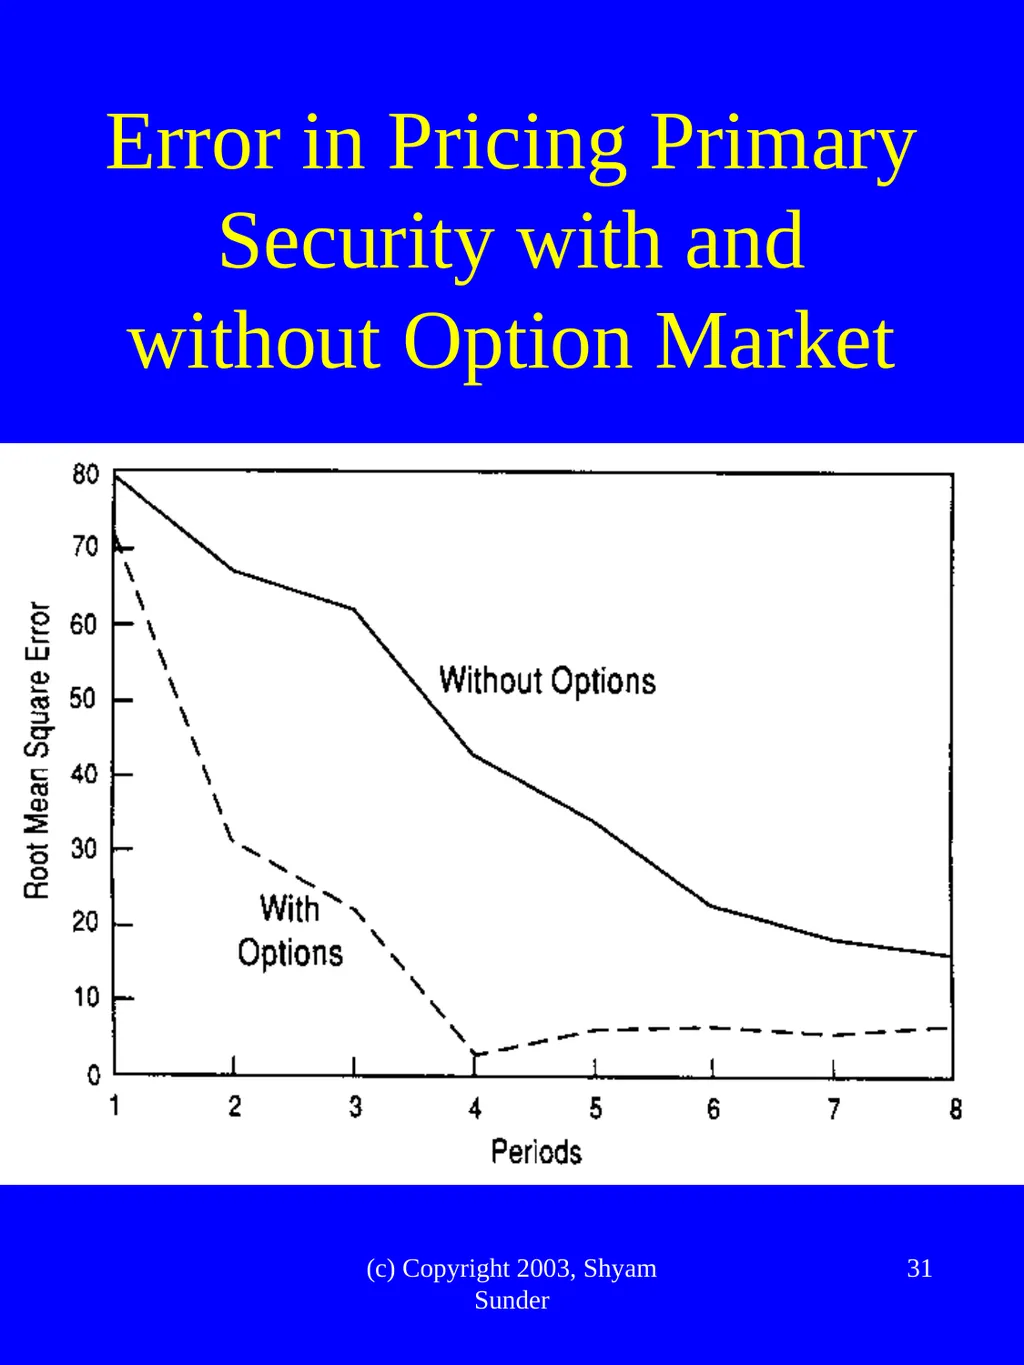
Kluger and Wyatt found that the option markets increase the informational efficiency of the equity market<br>
Forsythe, Palfrey and Plott (Econometrica 1982), the first asset market experiment, showed that futures markets speed up convergence to equilibrium in the primary market
Kluger and Wyatt found that the option markets increase the informational efficiency of the equity market<br>
29
(c) Copyright 2003, Shyam Sunder 29 Convergence with Two Spot Markets<br>
30
(c) Copyright 2003, Shyam Sunder 30 Convergence with a Spot and a Futures Market<br>
31
(c) Copyright 2003, Shyam Sunder 31 Error in Pricing Primary Security with and without Option Market<br>
32
(c) Copyright 2003, Shyam Sunder 32 How Can We Tell If a Market is Efficient? Traditional statistical approach: if you can’t make money from information (past data, public, or all information), the market is efficient
Experiments: statistical efficiency is a necessary but not a sufficient condition for the informational efficiency of markets
Example: Slide 19, second half is efficient by statistical criteria but is not informationally efficient
Even when investors know that the price is not right, they may have no means of profiting from that knowledge<br>
33
(c) Copyright 2003, Shyam Sunder 33 5. What Is Next? The above is a highly selective summary of what we have learned from experimental asset markets
What is coming up next?
The existence and causes of market bubbles is a perennial subject in financial economics
What might we learn about bubbles from experiments?<br>
What is coming up next?
The existence and causes of market bubbles is a perennial subject in financial economics
What might we learn about bubbles from experiments?<br>
34
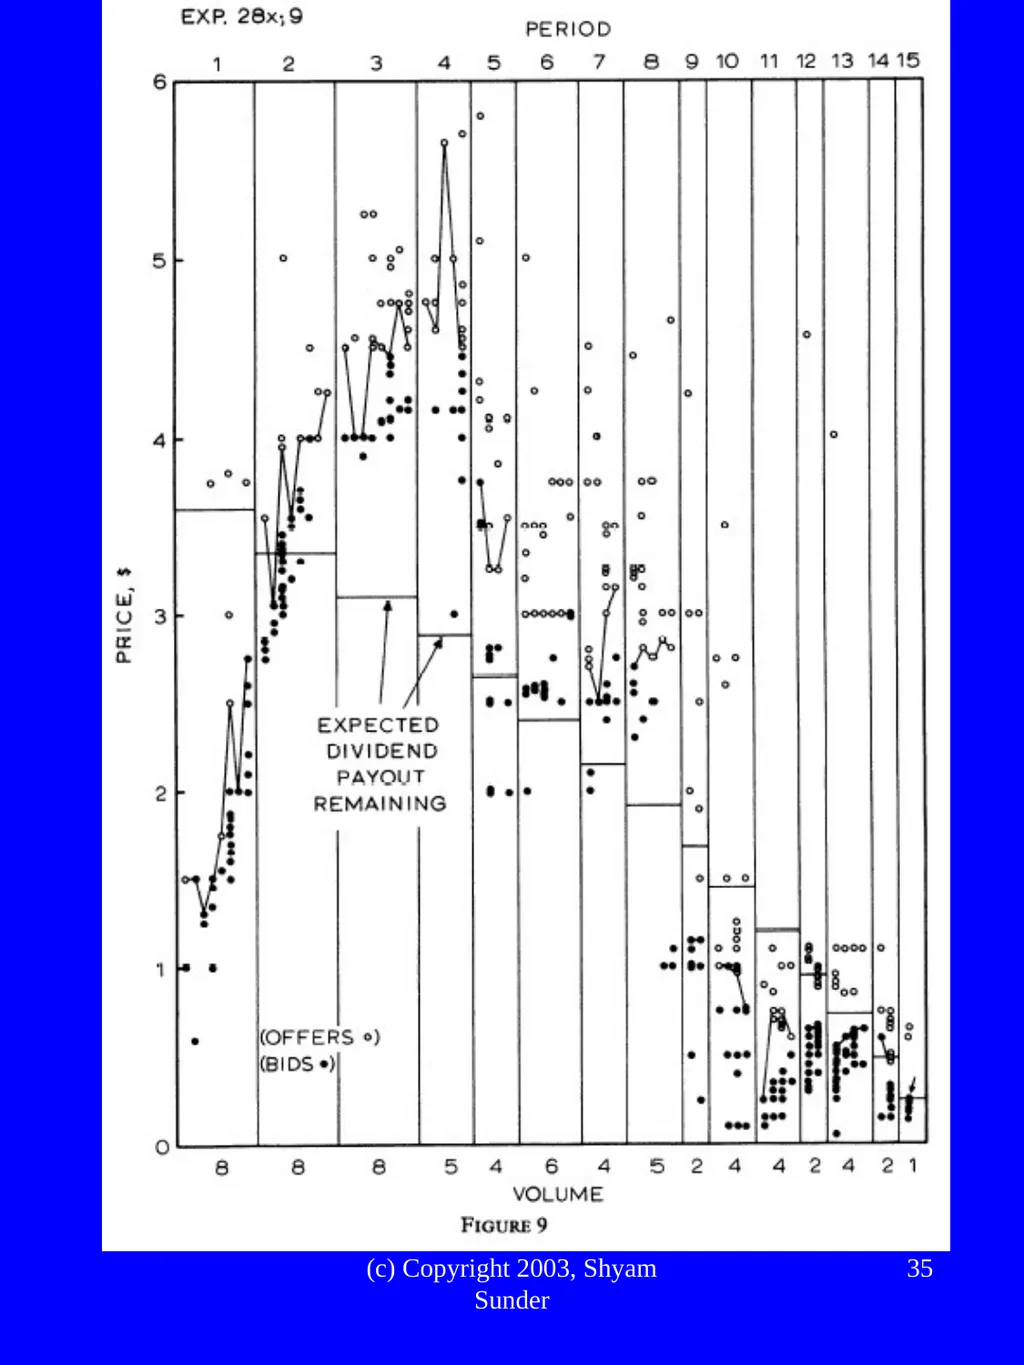
(c) Copyright 2003, Shyam Sunder 34 Bubbles in Simple Asset Markets Smith, Suchanek and Williams (Econometrica 1988) showed that bubbles can arise in simple asset markets with inexperienced subjects, and tend to diminish with experience
Lei, Noussair and Plott (Econometrica 2001) showed that bubbles can arise even when investors cannot engage in speculative trades. They suggest that bubbles can arise from errors in decision making even in absence of a lack of common knowledge of rationality (“bigger fool” beliefs)<br>
Lei, Noussair and Plott (Econometrica 2001) showed that bubbles can arise even when investors cannot engage in speculative trades. They suggest that bubbles can arise from errors in decision making even in absence of a lack of common knowledge of rationality (“bigger fool” beliefs)<br>
35
(c) Copyright 2003, Shyam Sunder 35<br>
36
(c) Copyright 2003, Shyam Sunder 36 Valuing Equity without Dividend Anchors Fundamental economic model of valuation is DCF
When security matures beyond investment horizon, personal DCF includes the sale price at horizon
Sale price depends on other investors’ expectations of DCF beyond my own horizon
Applying DCF involves backward inducting from the maturity of the security through the expectations and valuations of the future “generations” of investors<br>
37
(c) Copyright 2003, Shyam Sunder 37 Valuation be Equal to Fundamental Value if All investors form rational expectations
All investors form higher order expectations
Common knowledge of rational expectations
Common knowledge of higher order expectations
Common knowledge of maturity
These are very difficult conditions to meet in a market
Bubbles arise, even with rational investors who make no errors, if they cannot backward induct the DCF<br>
38
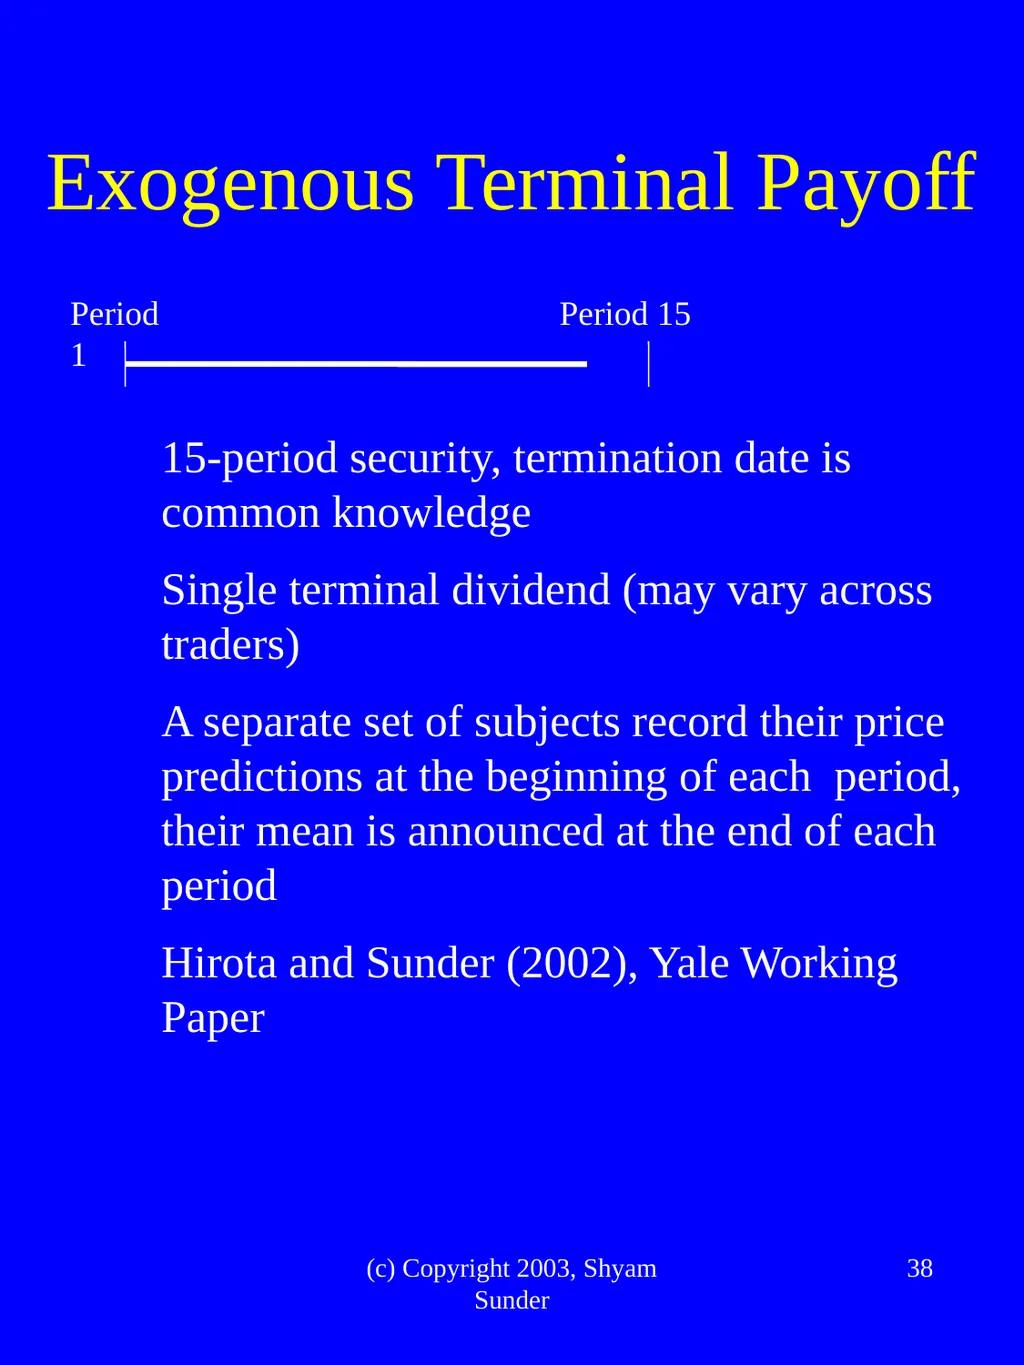
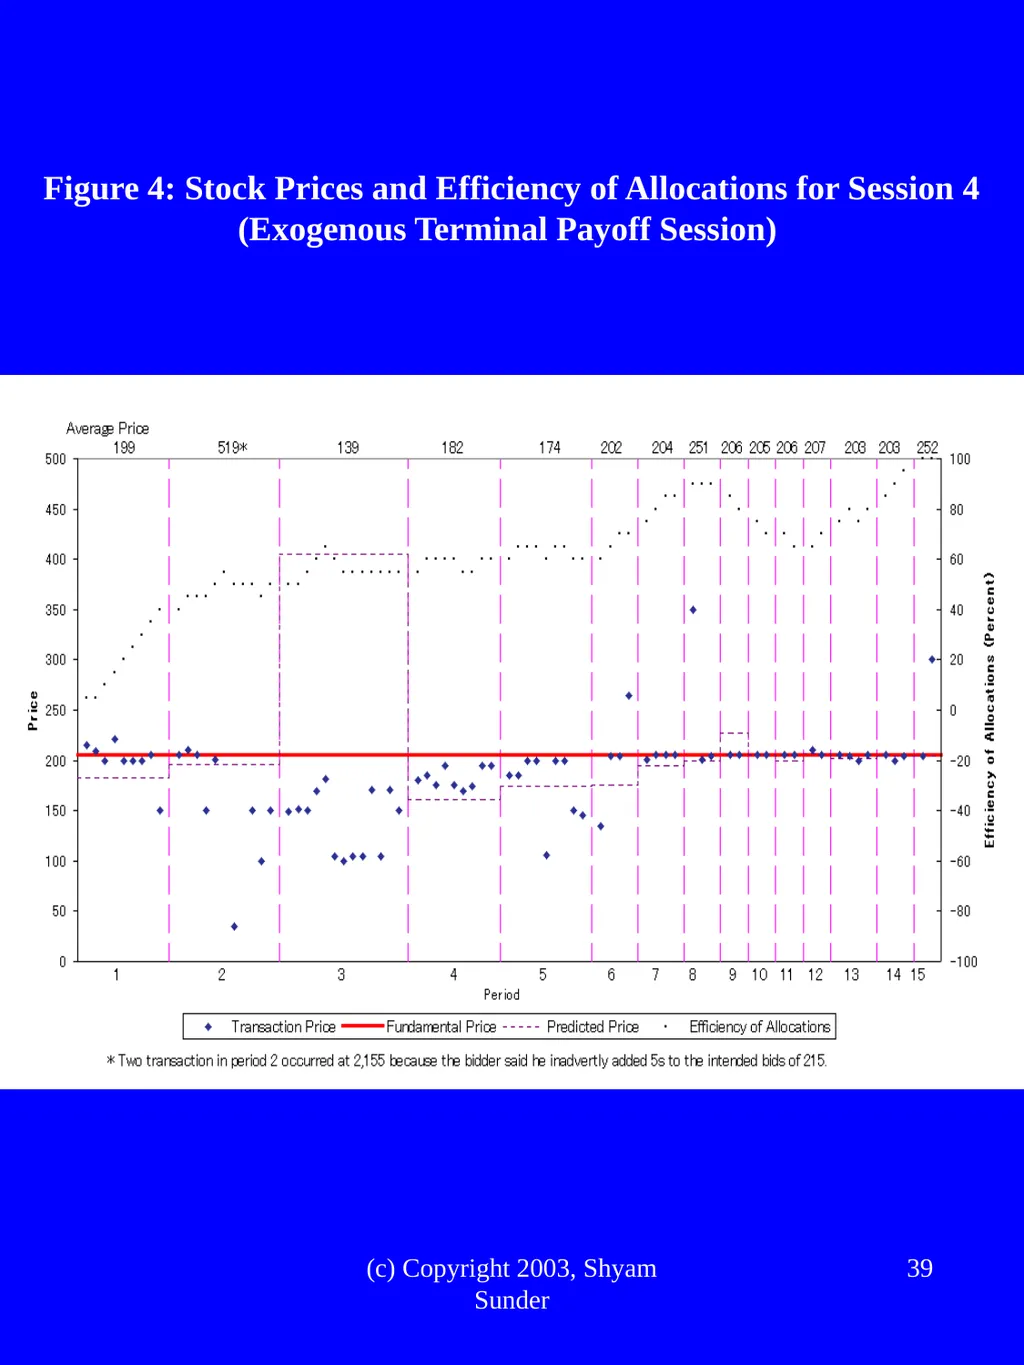
(c) Copyright 2003, Shyam Sunder 38 Exogenous Terminal Payoff 15-period security, termination date is common knowledge
Single terminal dividend (may vary across traders)
A separate set of subjects record their price predictions at the beginning of each period, their mean is announced at the end of each period
Hirota and Sunder (2002), Yale Working Paper Period 1 Period 15<br>
Single terminal dividend (may vary across traders)
A separate set of subjects record their price predictions at the beginning of each period, their mean is announced at the end of each period
Hirota and Sunder (2002), Yale Working Paper Period 1 Period 15<br>
39
(c) Copyright 2003, Shyam Sunder 39 Figure 4: Stock Prices and Efficiency of Allocations for Session 4
(Exogenous Terminal Payoff Session)<br>
(Exogenous Terminal Payoff Session)<br>
40
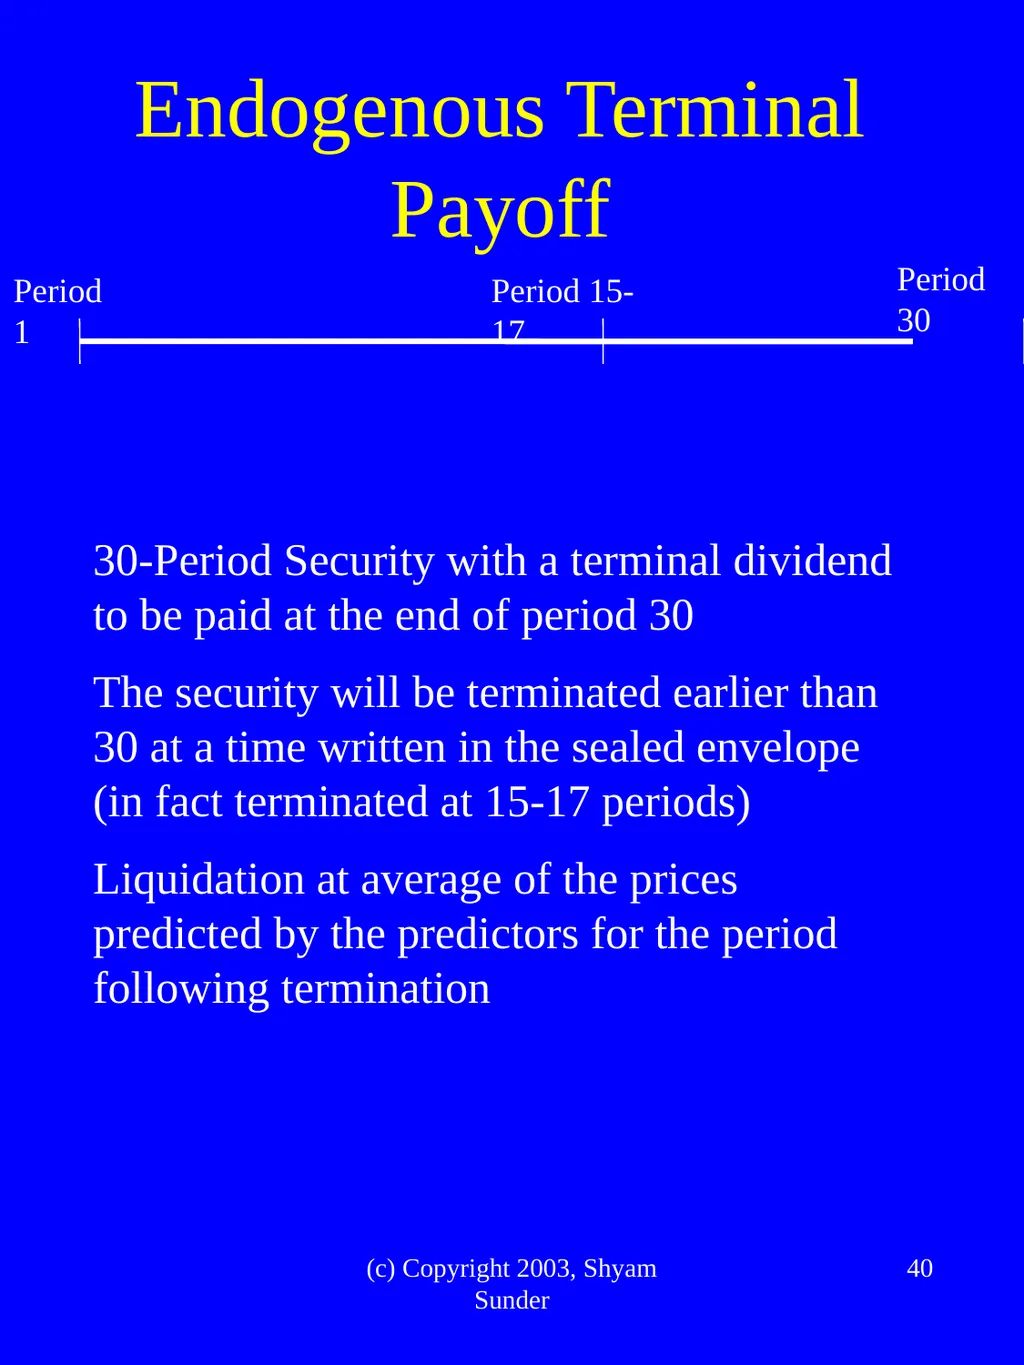
(c) Copyright 2003, Shyam Sunder 40 Endogenous Terminal Payoff 30-Period Security with a terminal dividend to be paid at the end of period 30
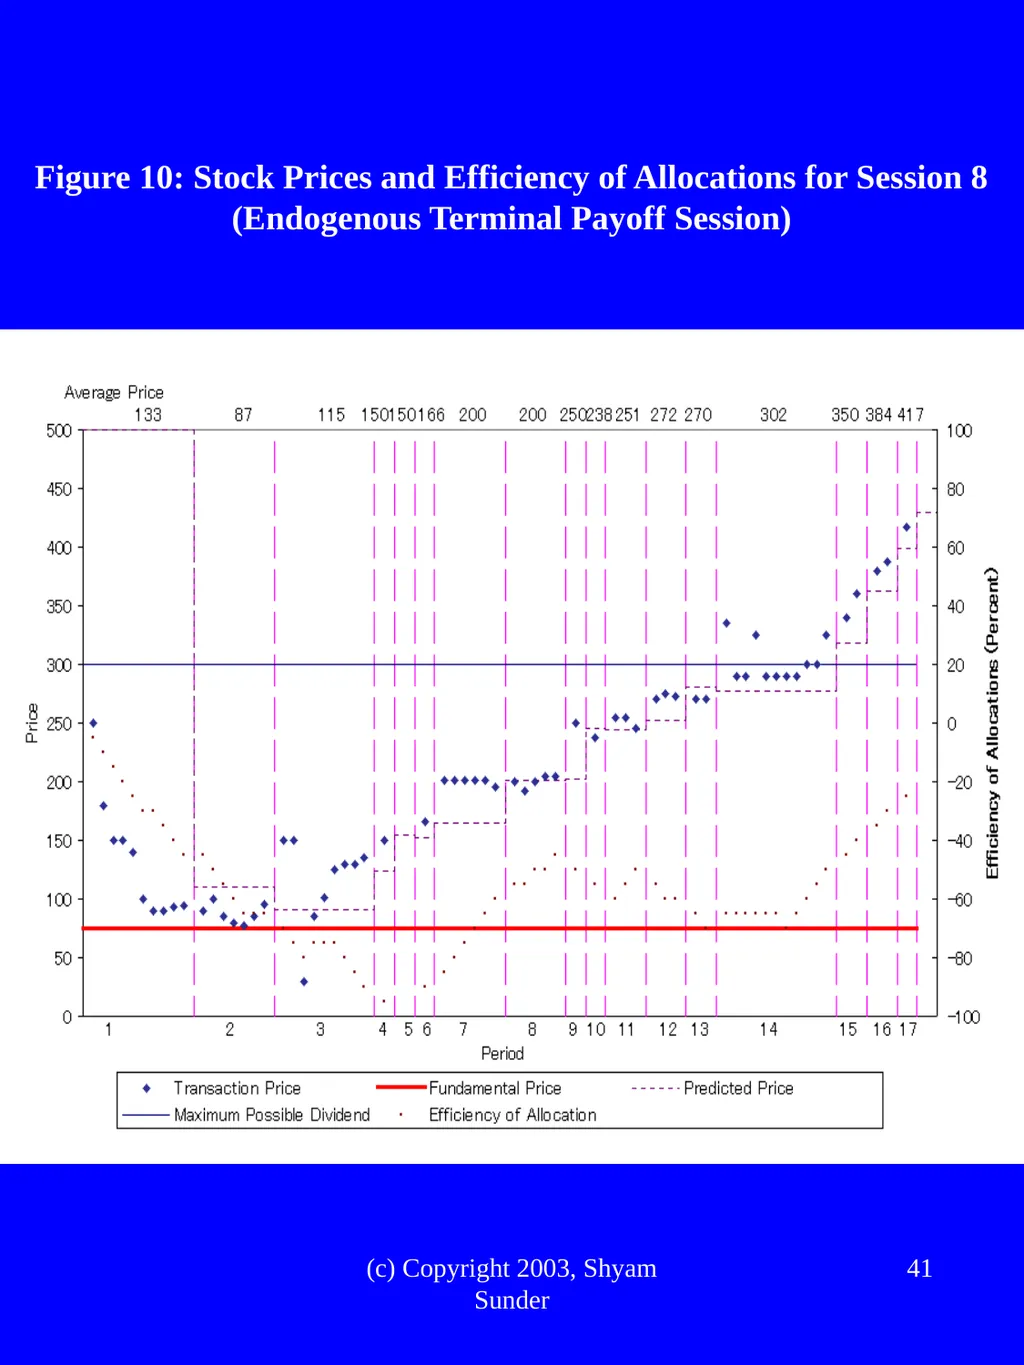
The security will be terminated earlier than 30 at a time written in the sealed envelope (in fact terminated at 15-17 periods)
Liquidation at average of the prices predicted by the predictors for the period following termination Period 1 Period 15-17 Period 30<br>
The security will be terminated earlier than 30 at a time written in the sealed envelope (in fact terminated at 15-17 periods)
Liquidation at average of the prices predicted by the predictors for the period following termination Period 1 Period 15-17 Period 30<br>
41
(c) Copyright 2003, Shyam Sunder 41 Figure 10: Stock Prices and Efficiency of Allocations for Session 8
(Endogenous Terminal Payoff Session)<br>
(Endogenous Terminal Payoff Session)<br>
42
(c) Copyright 2003, Shyam Sunder 42 Understanding Bubbles DCF valuation makes heroic assumptions about the knowledge necessary to do backward induction
Even if investors are rational and make no mistakes, it is unlikely that they can have the common knowledge necessary for price to be equal to fundamental valuation in a market populated by limited horizon investors
Not surprisingly, pricing of new technology, high growth, and high risk equities are more susceptible to bubbles
In such circumstances, if we do not have common knowledge of higher order beliefs, how can we test valuation theories?<br>
43
(c) Copyright 2003, Shyam Sunder 43 Wrap Up Only a thumbnail sketch of some experimental results on asset markets
Could not discuss many other important and interesting studies
See Sunder’s survey paper in Kagel and Roth’s Handbook of Experimental Economics<br>
Could not discuss many other important and interesting studies
See Sunder’s survey paper in Kagel and Roth’s Handbook of Experimental Economics<br>
44
(c) Copyright 2003, Shyam Sunder 44 Better Understanding As the experimental camera focused on information processing in asset markets, the theoretical line drawing has been filled by details, shadows, color, and warts
This finer grain portrait of asset markets confirms the rough outline of the extant theory
But it is considerably more complex, and is providing guidance and challenges for further theoretical investigations of interplay of information in asset markets<br>
This finer grain portrait of asset markets confirms the rough outline of the extant theory
But it is considerably more complex, and is providing guidance and challenges for further theoretical investigations of interplay of information in asset markets<br>
45
(c) Copyright 2003, Shyam Sunder 45 You Have to Try This It is a unique experience to watch trading in an experimental asset market
You know all the information, parameters, and alternative theoretical predictions
Yet, what you see often surprises you, forcing you to rethink, and discover new insights into how these markets work
Experimental asset markets are our LEGO sets. Playing with them produces new ideas, and helps us sort out good ideas from the bad ones
I would have preferred to have you sit in my lab and experience all this yourself, instead of talking to you because students who participate in these markets gain a sophisticated understanding of the markets<br>
46
(c) Copyright 2003, Shyam Sunder 46 Thank You Please send any comments you may have to me at
shyam.sunder@yale.edu
This presentation will be available at
www.som.yale.edu/faculty/sunder/research<br>
shyam.sunder@yale.edu
This presentation will be available at
www.som.yale.edu/faculty/sunder/research<br>