
Property Product Program (PPP) For SAC use
EM
Published · 56 slides · 0 views
1 / 1




Description
Property Product Program (PPP) For SAC use Version: Feb 2023 2 OCBC Home Loan Financing Key Features Benefits 5. Specific Credit criteria: LTVMOA Income Policy Requirement NPA Proxy Income Valuation High Net worth 6. Regulatory
Related Topics
Share
Embed code
Download this presentation From Below
"Property Product Program (PPP) For SAC use" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
01
Property Product Program (PPP) For SAC use
Version: Feb 2023<br>
Version: Feb 2023<br>
02
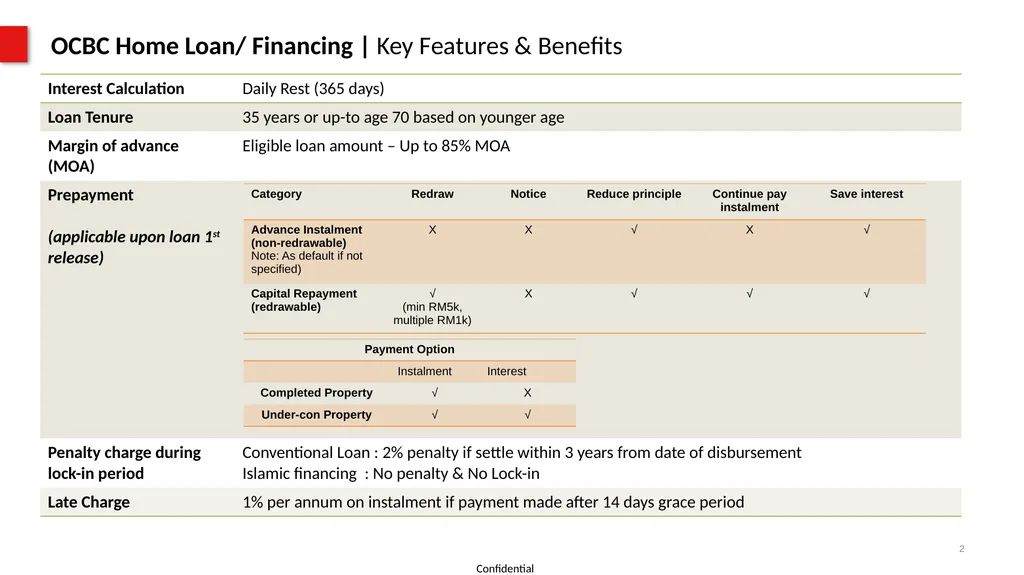
2 OCBC Home Loan/ Financing | Key Features & Benefits<br>
03
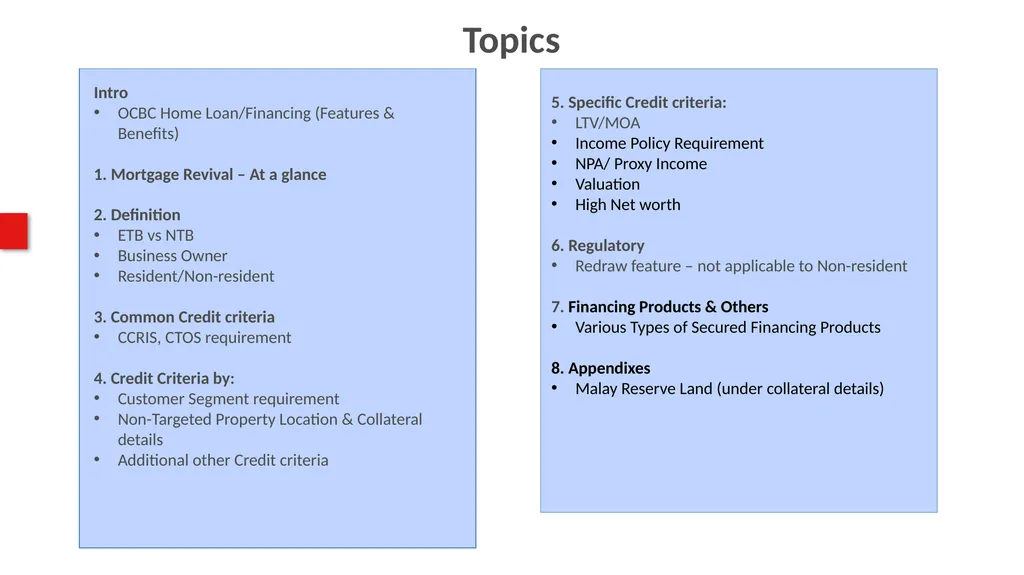
5. Specific Credit criteria:
LTV/MOA
Income Policy Requirement
NPA/ Proxy Income
Valuation
High Net worth
6. Regulatory
Redraw feature – not applicable to Non-resident
7. Financing Products & Others
Various Types of Secured Financing Products
8. Appendixes
Malay Reserve Land (under collateral details) Topics Intro
OCBC Home Loan/Financing (Features & Benefits)
1. Mortgage Revival – At a glance
2. Definition
ETB vs NTB
Business Owner
Resident/Non-resident
3. Common Credit criteria
CCRIS, CTOS requirement
4. Credit Criteria by:
Customer Segment requirement
Non-Targeted Property Location & Collateral details
Additional other Credit criteria<br>
04
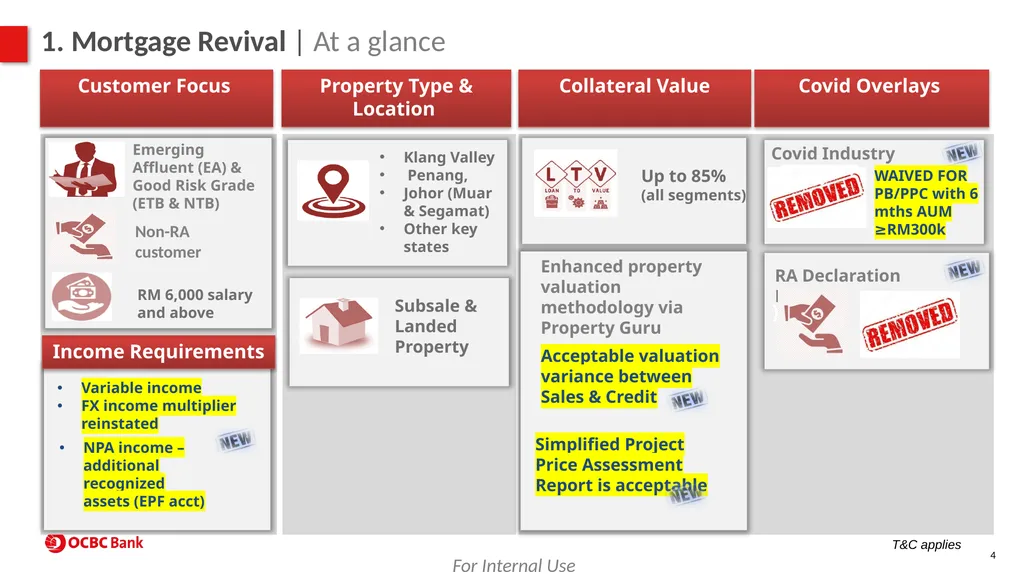
1. Mortgage Revival | At a glance 4 For Internal Use T&C applies Enhanced property valuation methodology via Property Guru Income Requirements Variable income
FX income multiplier reinstated NPA income –additional recognized assets (EPF acct) Acceptable valuation variance between Sales & Credit Simplified Project Price Assessment Report is acceptable WAIVED FOR PB/PPC with 6 mths AUM ≥RM300k Non-RA customer<br>
FX income multiplier reinstated NPA income –additional recognized assets (EPF acct) Acceptable valuation variance between Sales & Credit Simplified Project Price Assessment Report is acceptable WAIVED FOR PB/PPC with 6 mths AUM ≥RM300k Non-RA customer<br>
05
5 2. Definition
ETB vs NTB
Business Owner
Resident & Non-Resident<br>
ETB vs NTB
Business Owner
Resident & Non-Resident<br>
06
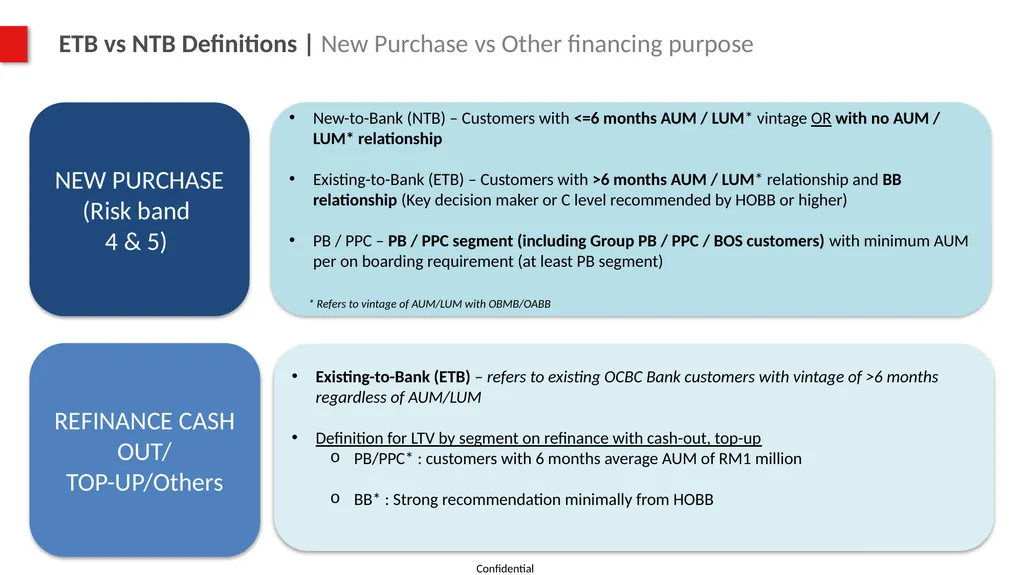
ETB vs NTB Definitions | New Purchase vs Other financing purpose New-to-Bank (NTB) – Customers with <=6 months AUM / LUM* vintage OR with no AUM / LUM* relationship
Existing-to-Bank (ETB) – Customers with >6 months AUM / LUM* relationship and BB relationship (Key decision maker or C level recommended by HOBB or higher)
PB / PPC – PB / PPC segment (including Group PB / PPC / BOS customers) with minimum AUM per on boarding requirement (at least PB segment)
* Refers to vintage of AUM/LUM with OBMB/OABB NEW PURCHASE (Risk band
4 & 5) Existing-to-Bank (ETB) – refers to existing OCBC Bank customers with vintage of >6 months regardless of AUM/LUM
Definition for LTV by segment on refinance with cash-out, top-up
PB/PPC* : customers with 6 months average AUM of RM1 million
BB* : Strong recommendation minimally from HOBB REFINANCE CASH OUT/ TOP-UP/Others<br>
07
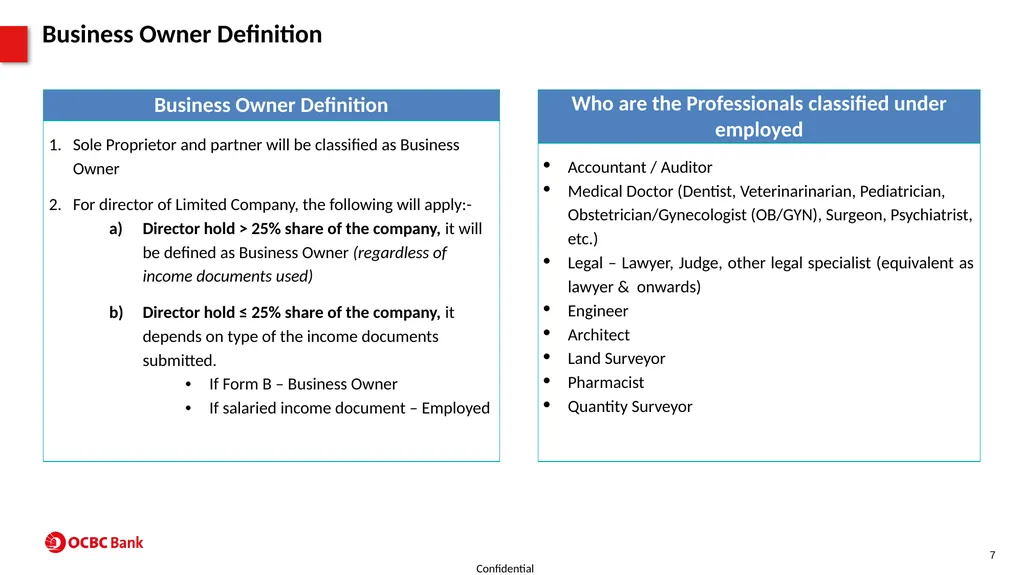
Business Owner Definition 7<br>
08
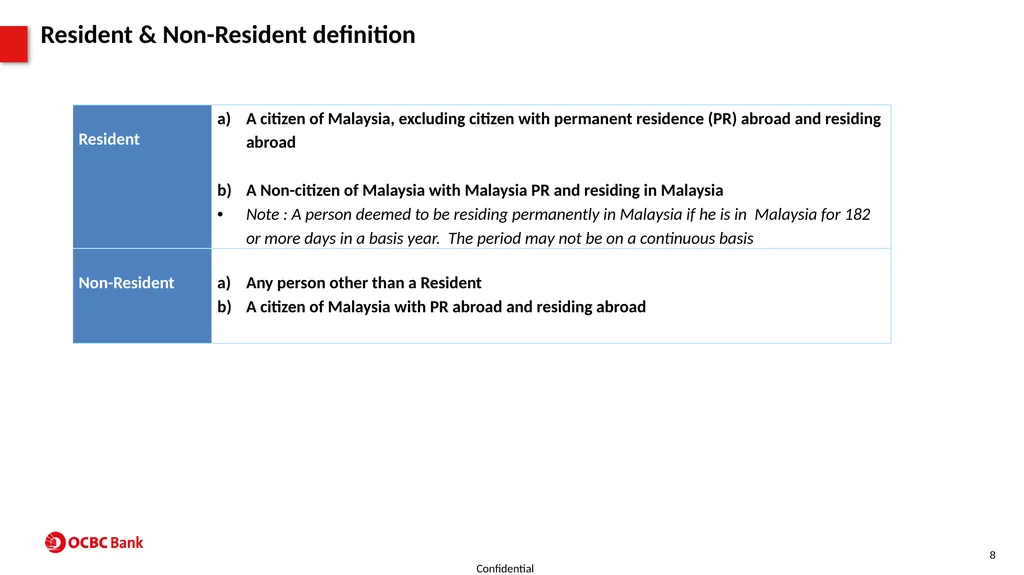
8 Resident & Non-Resident definition<br>
09
9 3. Common Credit Criteria
CTOS and CCRIS requirement<br>
CTOS and CCRIS requirement<br>
10
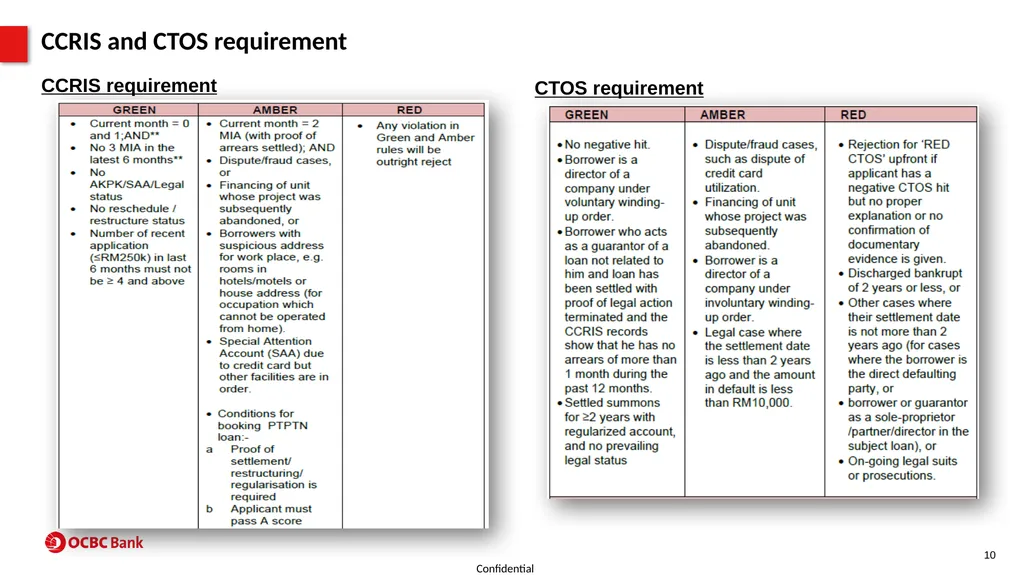
CCRIS and CTOS requirement 10 CTOS requirement CCRIS requirement<br>
11
11 4. Credit Criteria by:
Customer Segment requirement
Non-Targeted Property Location & Collateral details<br>
Customer Segment requirement
Non-Targeted Property Location & Collateral details<br>
12
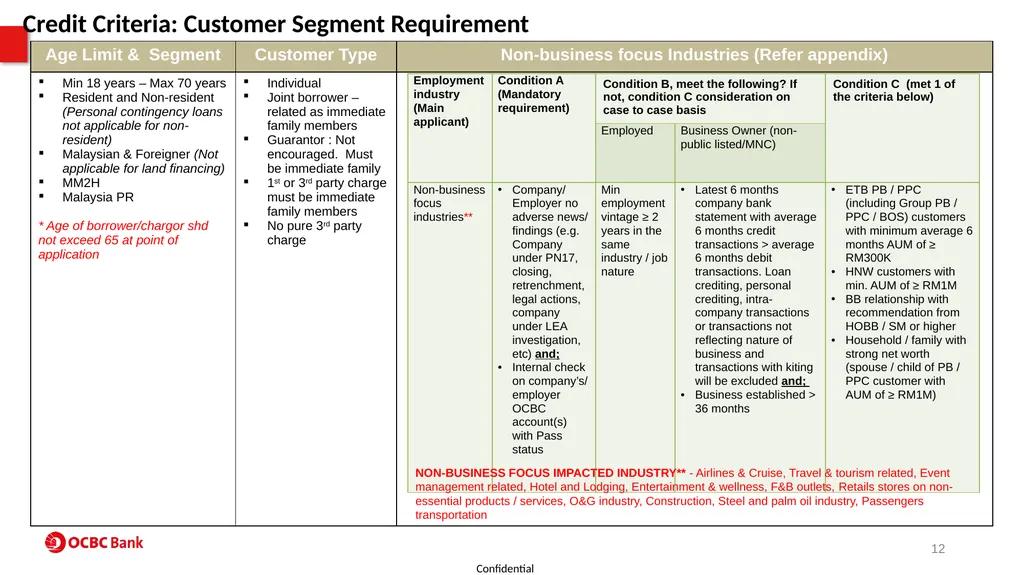
12 Credit Criteria: Customer Segment Requirement NON-BUSINESS FOCUS IMPACTED INDUSTRY** - Airlines & Cruise, Travel & tourism related, Event management related, Hotel and Lodging, Entertainment & wellness, F&B outlets, Retails stores on non-essential products / services, O&G industry, Construction, Steel and palm oil industry, Passengers transportation<br>
13
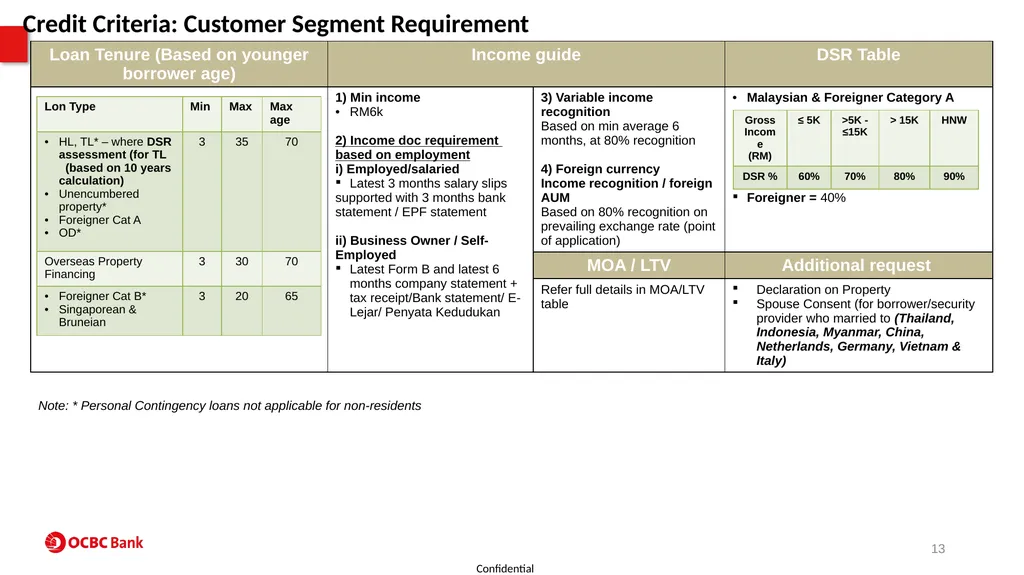
13 Credit Criteria: Customer Segment Requirement Note: * Personal Contingency loans not applicable for non-residents<br>
14
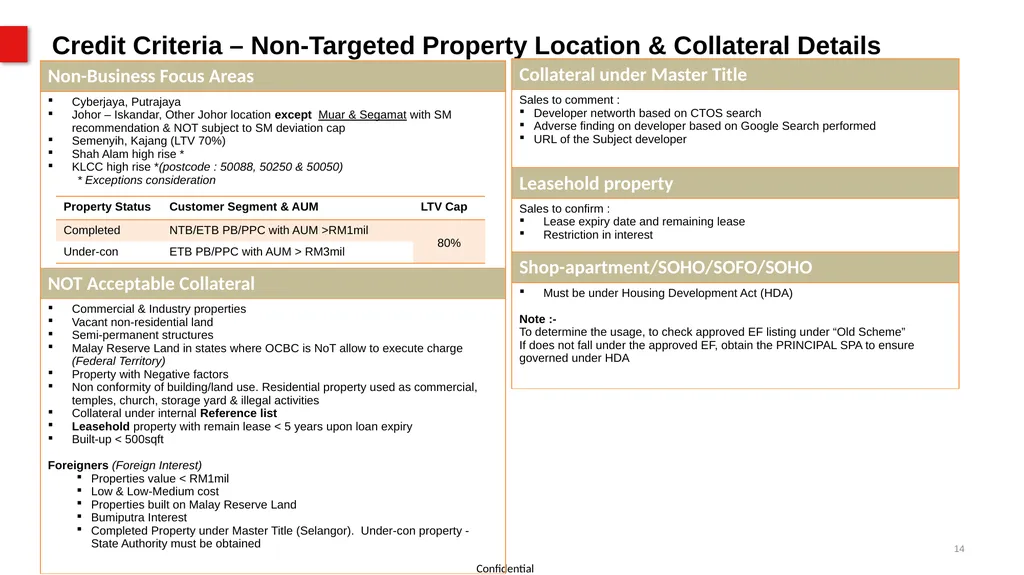
14 Credit Criteria – Non-Targeted Property Location & Collateral Details<br>
15
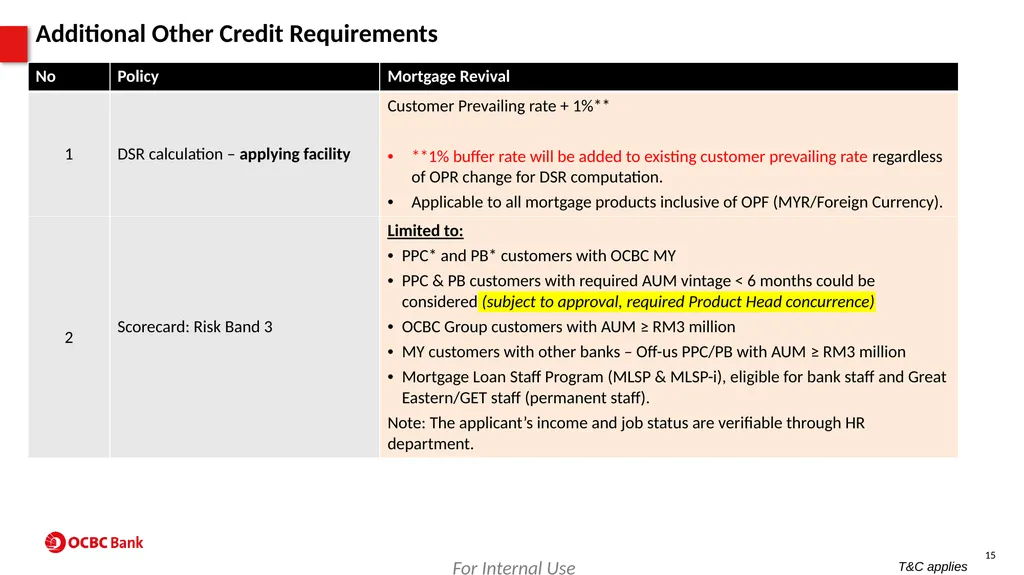
15 Additional Other Credit Requirements For Internal Use T&C applies<br>
16
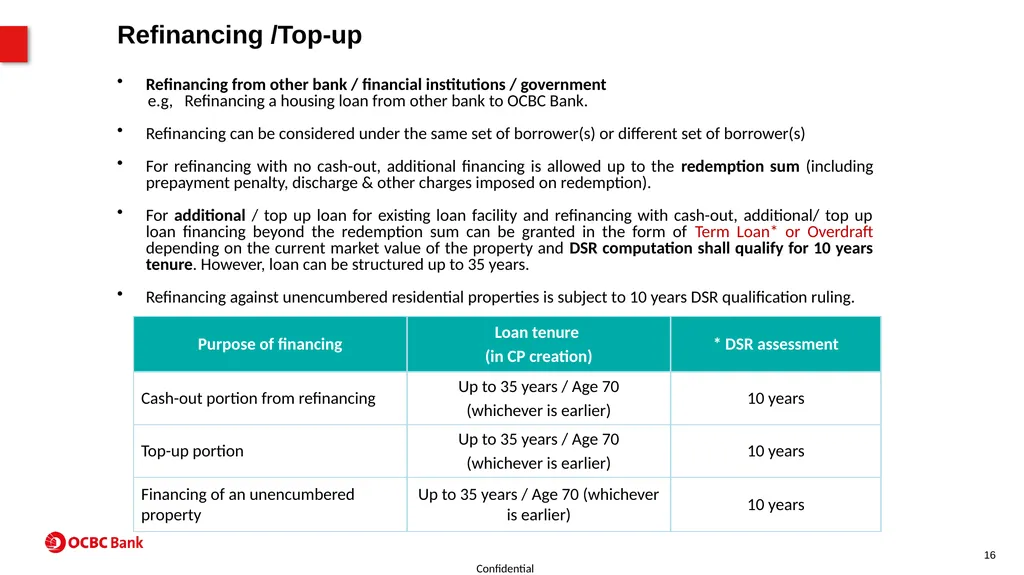
Refinancing /Top-up 16 Refinancing from other bank / financial institutions / government
e.g, Refinancing a housing loan from other bank to OCBC Bank.
Refinancing can be considered under the same set of borrower(s) or different set of borrower(s)
For refinancing with no cash-out, additional financing is allowed up to the redemption sum (including prepayment penalty, discharge & other charges imposed on redemption).
For additional / top up loan for existing loan facility and refinancing with cash-out, additional/ top up loan financing beyond the redemption sum can be granted in the form of Term Loan* or Overdraft depending on the current market value of the property and DSR computation shall qualify for 10 years tenure. However, loan can be structured up to 35 years.
Refinancing against unencumbered residential properties is subject to 10 years DSR qualification ruling.<br>
17
17 5. Specific Credit Criteria:
LTV/MOA
Income Policy Requirement
NPA/ Proxy Income
Valuation
High Net worth<br>
LTV/MOA
Income Policy Requirement
NPA/ Proxy Income
Valuation
High Net worth<br>
18
Loan-to-Value (LTV)/ Margin of Advance (MOA) 18<br>
19
Margin of Advance (MOA)/ Loan-To-Value (LTV) Table & conditions Note:
PB1/PPC1 - PB/PPC who has min 6 months average AUM RM1mil
PB2/PPC2 - PB / PPC segment (including Group PB / PPC / BOS customers) with minimum AUM per on boarding requirement (at least PB segment)
Risk Band 1 & 2 : manual review for HNW customers segment ie. PB or above with ≥ RM1mil AUM.
Risk Band 3 : Biz owner allowed for PB/PPC customers with ≥ RM1mil AUM and OCBC Group customers or off-us PPC/PB customers with AUM ≥ RM3mil. This is the existing Covid Tightening business focus criteria.
Risk Band 4 & 5 Biz Owner 1st/2nd HL : Any suspicious profile mismatch application with immature CCRIS vintage to be escalated to BFM for further investigation.
3rd HL remains up to max direct LTV 70%.
MLSP follows current policy on LTV eg. max at 85% direct MOA.
Max LTV 80% for big ticket loans (>RM4mil for KV & Penang Island, >RM2mil for other areas)
Max LTV for OD is 70% * Additional conditions apply Important Criteria to be Read in Conjunction with MOA Matrix
Direct MOA = Loan to Property Value + LVS (including Legal Fees, Valuation Fees and Stamp Duties)
Total MOA = Direct MOA + MRTA financing up to 5%. For low direct MOA segment at 70% and below, MRTA financing can be up to 10%.
For segment entitled to 85% direct MOA, total MOA including MRTA is capped at 89%.<br>
20
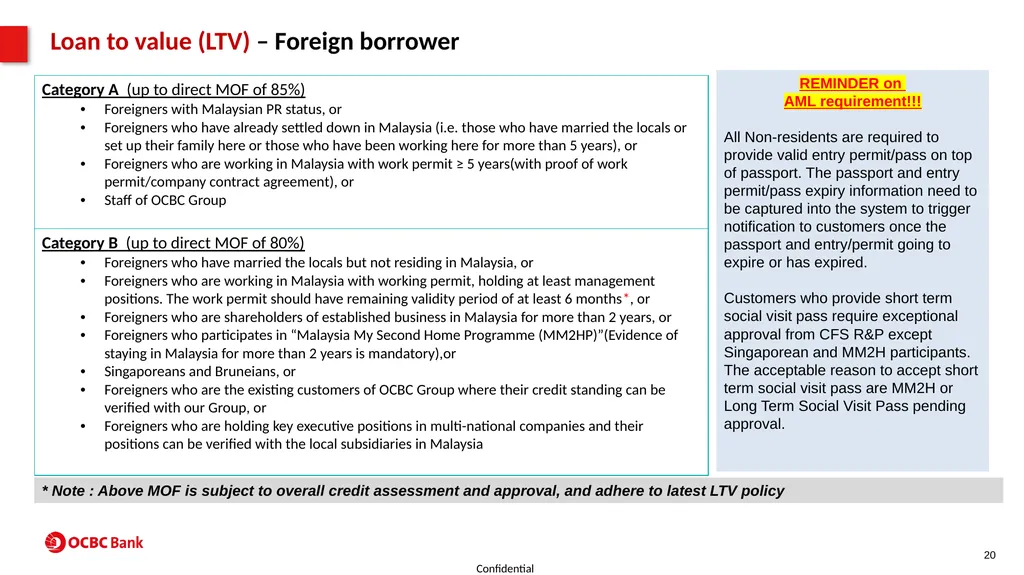
Loan to value (LTV) – Foreign borrower 20 * Note : Above MOF is subject to overall credit assessment and approval, and adhere to latest LTV policy REMINDER on
AML requirement!!!
All Non-residents are required to provide valid entry permit/pass on top of passport. The passport and entry permit/pass expiry information need to be captured into the system to trigger notification to customers once the passport and entry/permit going to expire or has expired.
Customers who provide short term social visit pass require exceptional approval from CFS R&P except Singaporean and MM2H participants. The acceptable reason to accept short term social visit pass are MM2H or Long Term Social Visit Pass pending approval.<br>
21
Loan to value (LTV) - 70% for 3rd HL application Definition of 3rd Housing Loan (HL) for max LTV / (Direct MOF) of 70%
Individuals who hold 2 outstanding HL accounts shall be subject to a max LTV ratio of 70%
The number of existing housing loan accounts is verified through CCRIS.
How to prove disposal/settlement of 3rd HL to qualify for higher MOF?
If the borrower has disposed of/ fully settled/ top-up loan charged to the same collateral, documentary proof to be furnished are as follow:
Loan agreement; and/or
Sales and Purchase Agreement (stamped and valid); and/or
Loan Settlement Letter; and/or
Loan Settlement payment receipt; and/or
Bank statement (proof of payment); and/or
BNM CCRIS (with loan account number) or CBS report for Singaporeans and PR of Singapore<br>
22
Income Policy requirement Acceptable forms of Income Substantiation
Income document sources & recognition
Income verification 22<br>
Income document sources & recognition
Income verification 22<br>
23
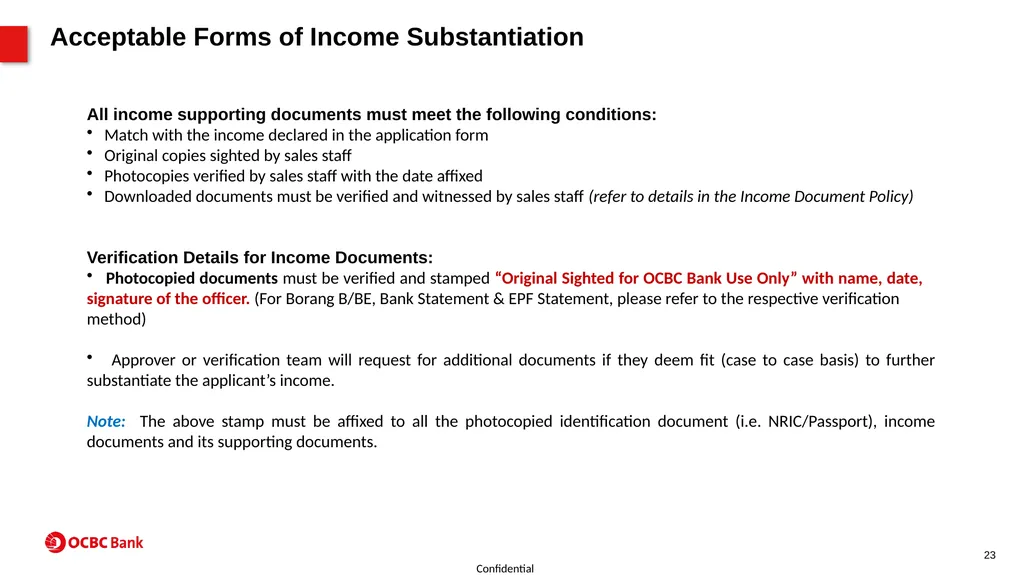
Acceptable Forms of Income Substantiation 23 All income supporting documents must meet the following conditions:
Match with the income declared in the application form
Original copies sighted by sales staff
Photocopies verified by sales staff with the date affixed
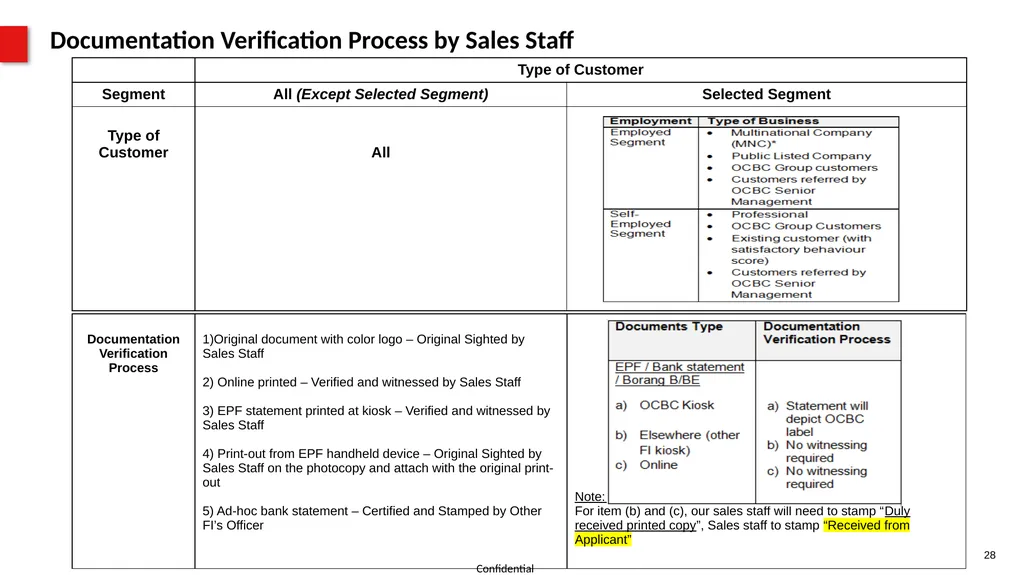
Downloaded documents must be verified and witnessed by sales staff (refer to details in the Income Document Policy)
Verification Details for Income Documents:
Photocopied documents must be verified and stamped “Original Sighted for OCBC Bank Use Only” with name, date, signature of the officer. (For Borang B/BE, Bank Statement & EPF Statement, please refer to the respective verification
method)
Approver or verification team will request for additional documents if they deem fit (case to case basis) to further substantiate the applicant’s income.
Note: The above stamp must be affixed to all the photocopied identification document (i.e. NRIC/Passport), income documents and its supporting documents.<br>
24
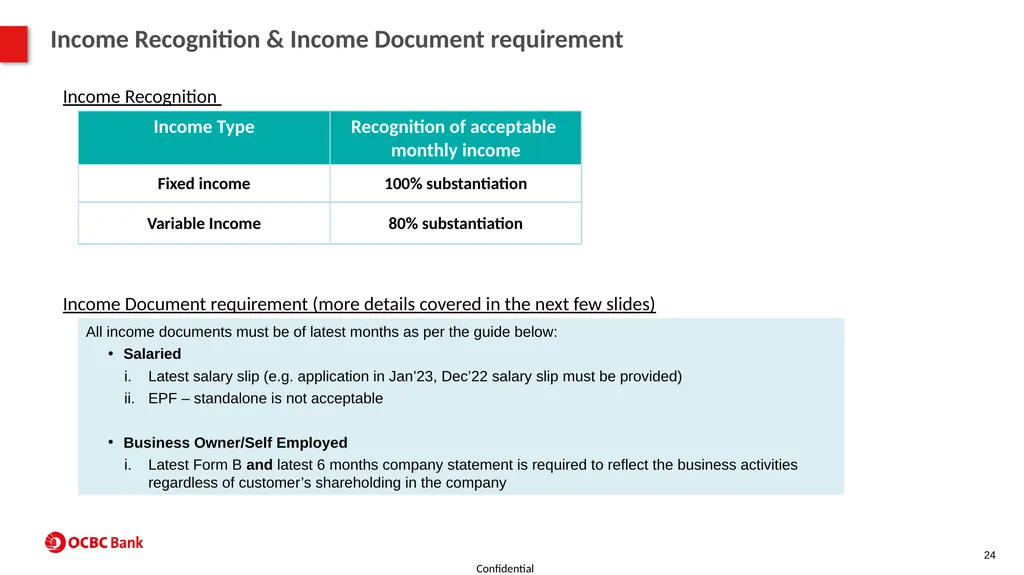
24 Income Recognition & Income Document requirement All income documents must be of latest months as per the guide below:
Salaried
Latest salary slip (e.g. application in Jan’23, Dec’22 salary slip must be provided)
EPF – standalone is not acceptable
Business Owner/Self Employed
Latest Form B and latest 6 months company statement is required to reflect the business activities regardless of customer’s shareholding in the company Income Recognition Income Document requirement (more details covered in the next few slides)<br>
25
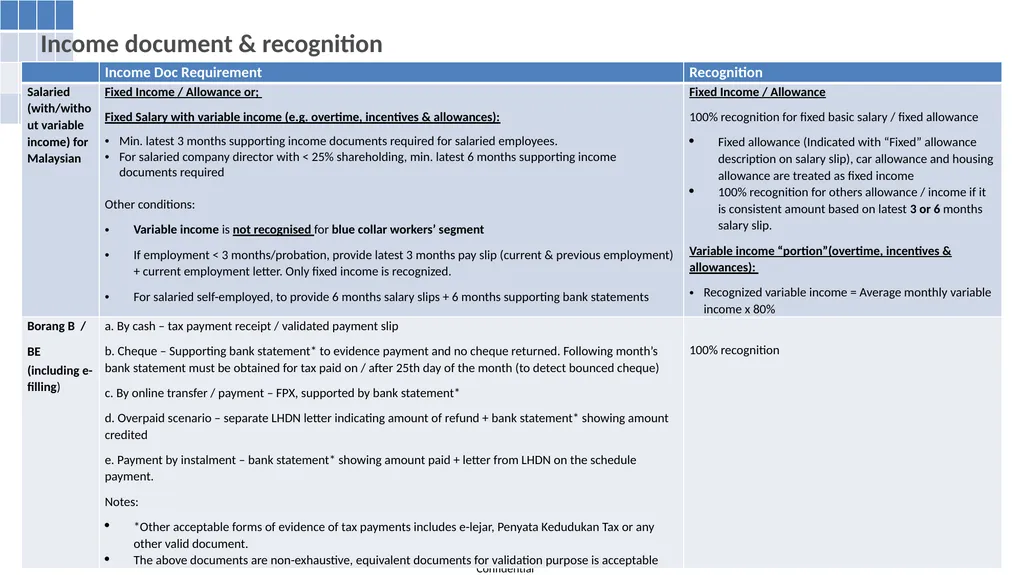
Income document & recognition<br>
26
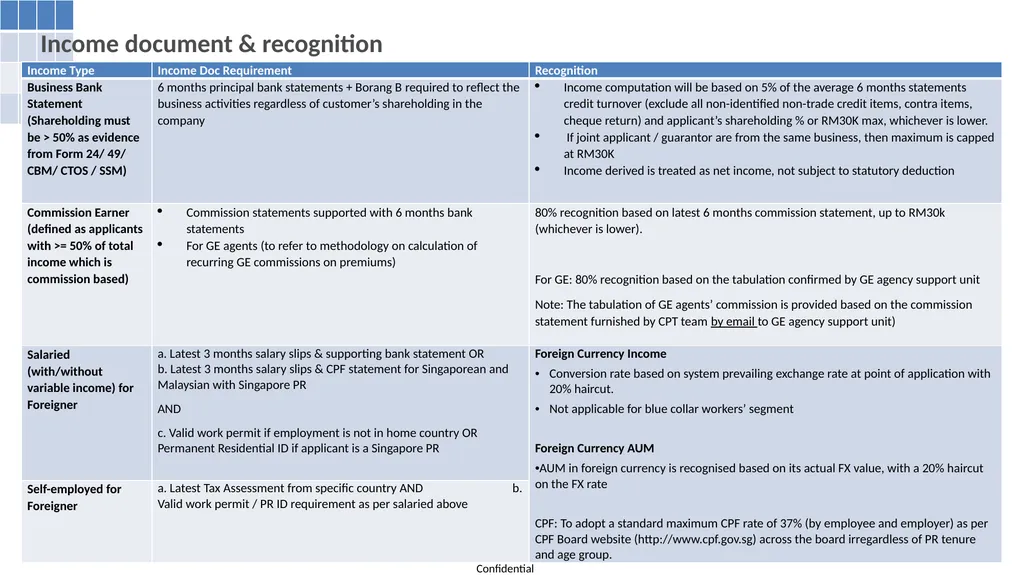
For Internal Use Income document & recognition<br>
27
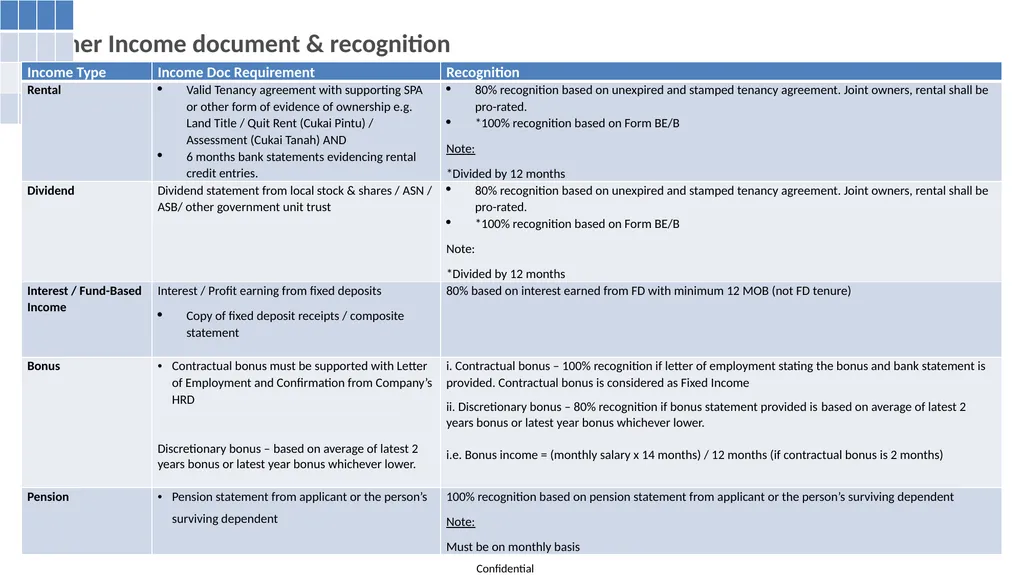
Other Income document & recognition<br>
28
28 Documentation Verification Process by Sales Staff<br>
29
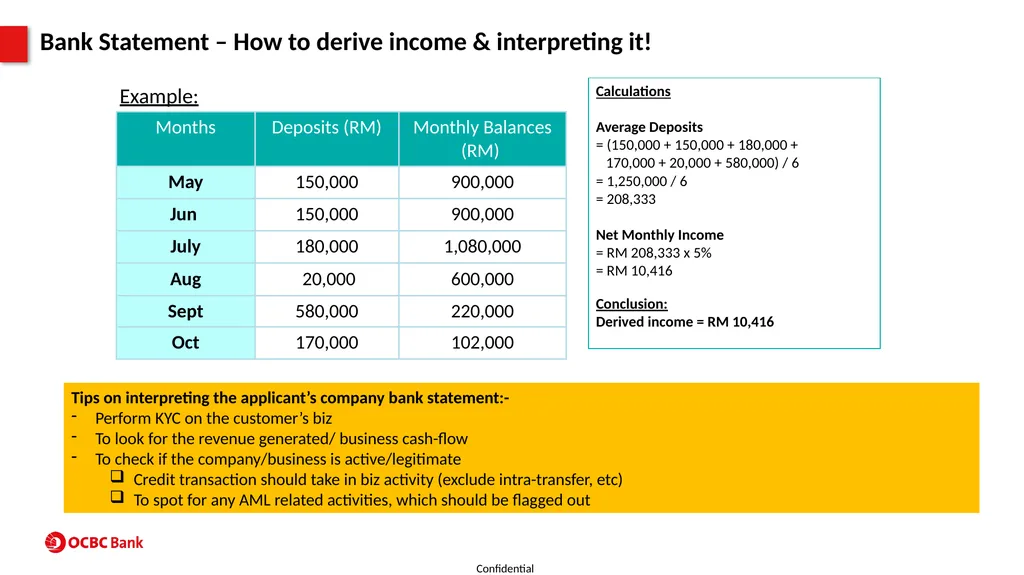
Bank Statement – How to derive income & interpreting it! Calculations
Average Deposits
= (150,000 + 150,000 + 180,000 +
170,000 + 20,000 + 580,000) / 6
= 1,250,000 / 6
= 208,333
Net Monthly Income
= RM 208,333 x 5%
= RM 10,416
Conclusion:
Derived income = RM 10,416 Example: Tips on interpreting the applicant’s company bank statement:-
Perform KYC on the customer’s biz
To look for the revenue generated/ business cash-flow
To check if the company/business is active/legitimate
Credit transaction should take in biz activity (exclude intra-transfer, etc)
To spot for any AML related activities, which should be flagged out<br>
30
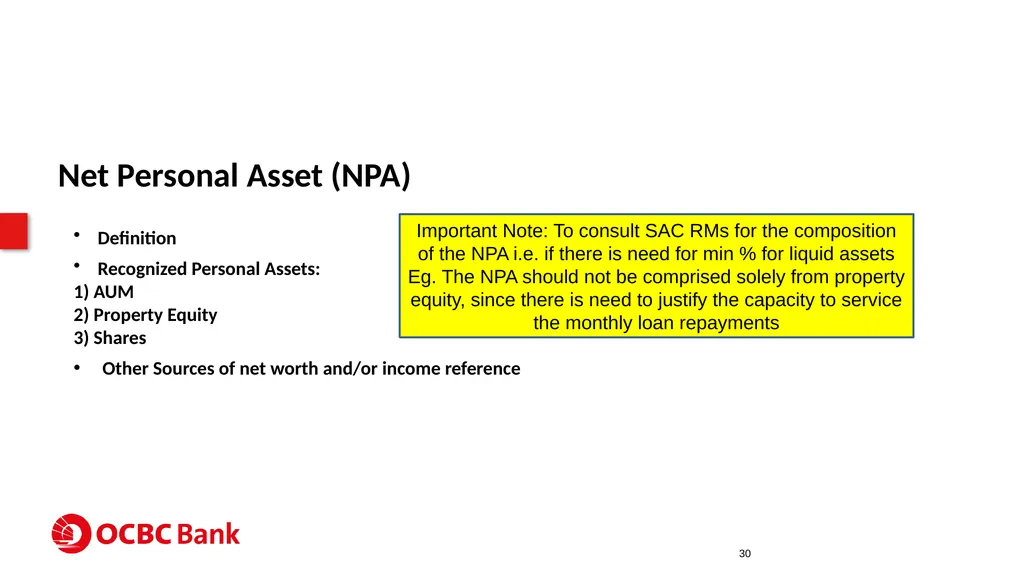
Net Personal Asset (NPA) Definition
Recognized Personal Assets:
1) AUM
2) Property Equity
3) Shares
Other Sources of net worth and/or income reference 30 Important Note: To consult SAC RMs for the composition of the NPA i.e. if there is need for min % for liquid assets
Eg. The NPA should not be comprised solely from property equity, since there is need to justify the capacity to service the monthly loan repayments<br>
31
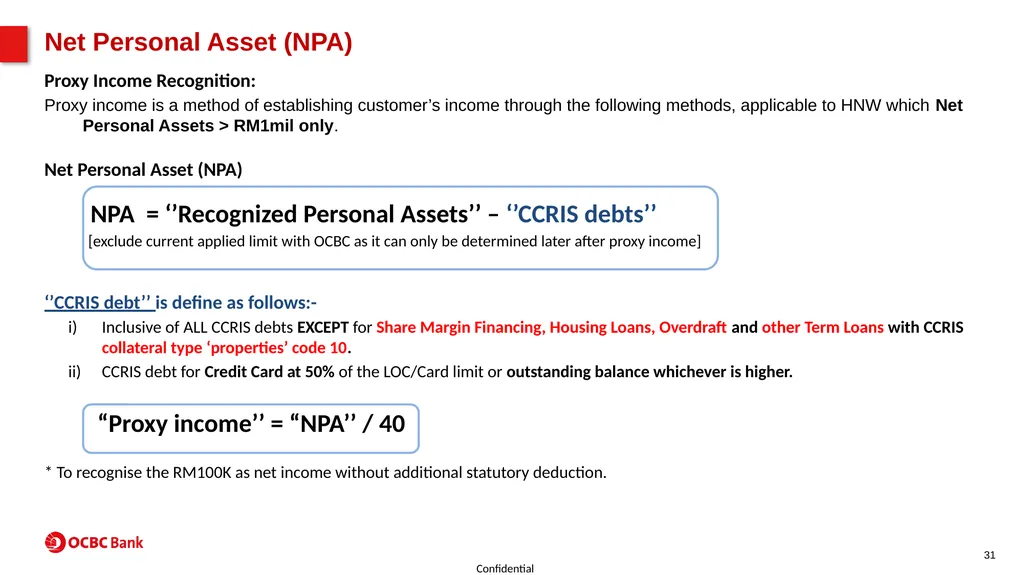
Net Personal Asset (NPA) 31 Proxy Income Recognition:
Proxy income is a method of establishing customer’s income through the following methods, applicable to HNW which Net Personal Assets > RM1mil only.
Net Personal Asset (NPA)
NPA = ‘’Recognized Personal Assets’’ – ‘’CCRIS debts’’
[exclude current applied limit with OCBC as it can only be determined later after proxy income]
‘’CCRIS debt’’ is define as follows:-
Inclusive of ALL CCRIS debts EXCEPT for Share Margin Financing, Housing Loans, Overdraft and other Term Loans with CCRIS collateral type ‘properties’ code 10.
CCRIS debt for Credit Card at 50% of the LOC/Card limit or outstanding balance whichever is higher.
“Proxy income’’ = “NPA’’ / 40
* To recognise the RM100K as net income without additional statutory deduction.<br>
32
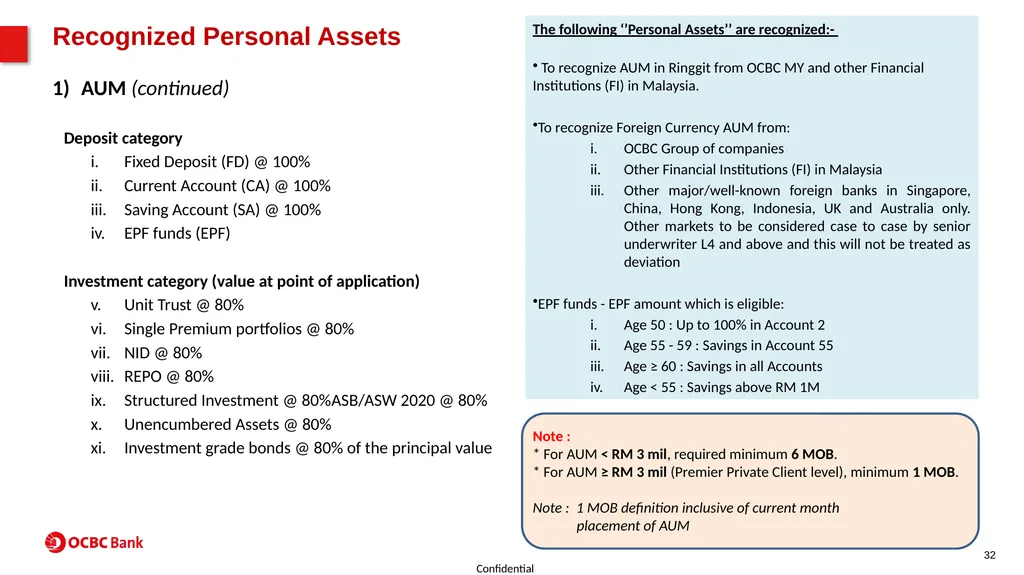
Note :
* For AUM < RM 3 mil, required minimum 6 MOB.
* For AUM ≥ RM 3 mil (Premier Private Client level), minimum 1 MOB.
Note : 1 MOB definition inclusive of current month
placement of AUM Recognized Personal Assets 32 AUM (continued)
Deposit category
Fixed Deposit (FD) @ 100%
Current Account (CA) @ 100%
Saving Account (SA) @ 100%
EPF funds (EPF)
Investment category (value at point of application)
Unit Trust @ 80%
Single Premium portfolios @ 80%
NID @ 80%
REPO @ 80%
Structured Investment @ 80%ASB/ASW 2020 @ 80%
Unencumbered Assets @ 80%
Investment grade bonds @ 80% of the principal value The following ‘’Personal Assets’’ are recognized:-
To recognize AUM in Ringgit from OCBC MY and other Financial Institutions (FI) in Malaysia.
To recognize Foreign Currency AUM from:
OCBC Group of companies
Other Financial Institutions (FI) in Malaysia
Other major/well-known foreign banks in Singapore, China, Hong Kong, Indonesia, UK and Australia only. Other markets to be considered case to case by senior underwriter L4 and above and this will not be treated as deviation
EPF funds - EPF amount which is eligible:
Age 50 : Up to 100% in Account 2
Age 55 - 59 : Savings in Account 55
Age ≥ 60 : Savings in all Accounts
Age < 55 : Savings above RM 1M<br>
33
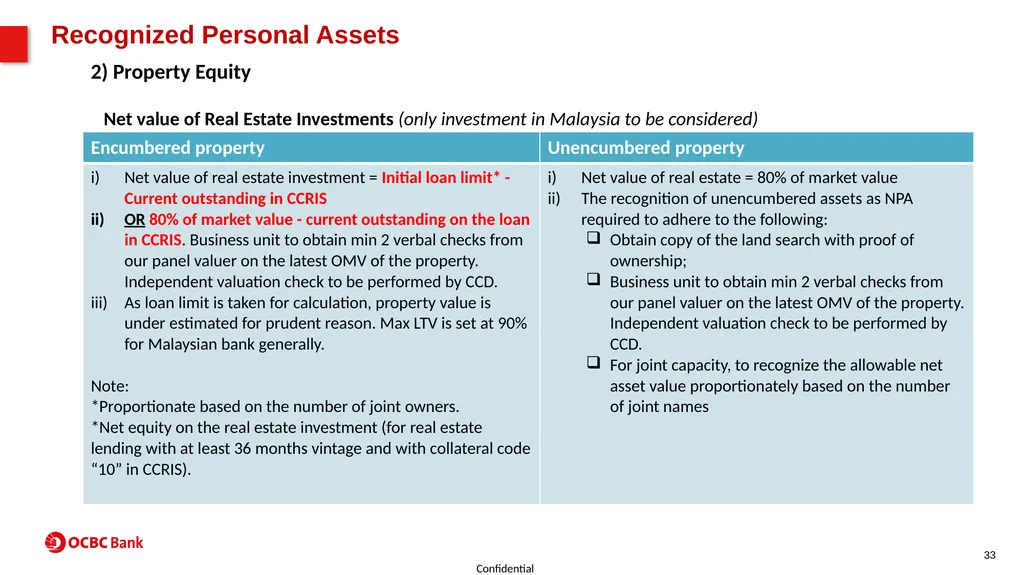
Recognized Personal Assets 33 2) Property Equity
Net value of Real Estate Investments (only investment in Malaysia to be considered)<br>
Net value of Real Estate Investments (only investment in Malaysia to be considered)<br>
34
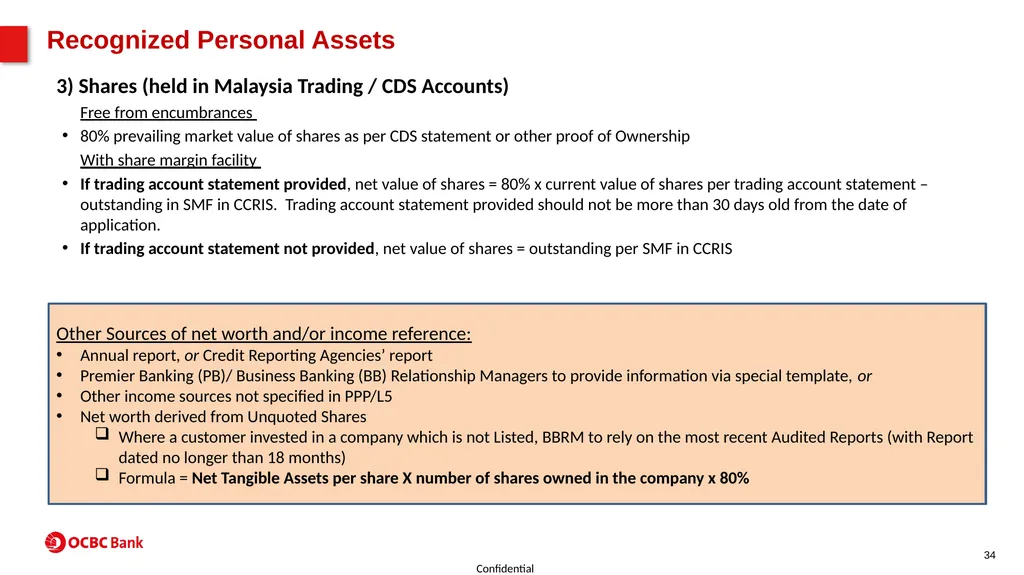
Recognized Personal Assets 34 3) Shares (held in Malaysia Trading / CDS Accounts)
Free from encumbrances
80% prevailing market value of shares as per CDS statement or other proof of Ownership
With share margin facility
If trading account statement provided, net value of shares = 80% x current value of shares per trading account statement – outstanding in SMF in CCRIS. Trading account statement provided should not be more than 30 days old from the date of application.
If trading account statement not provided, net value of shares = outstanding per SMF in CCRIS Other Sources of net worth and/or income reference:
Annual report, or Credit Reporting Agencies’ report
Premier Banking (PB)/ Business Banking (BB) Relationship Managers to provide information via special template, or
Other income sources not specified in PPP/L5
Net worth derived from Unquoted Shares
Where a customer invested in a company which is not Listed, BBRM to rely on the most recent Audited Reports (with Report dated no longer than 18 months)
Formula = Net Tangible Assets per share X number of shares owned in the company x 80%<br>
35
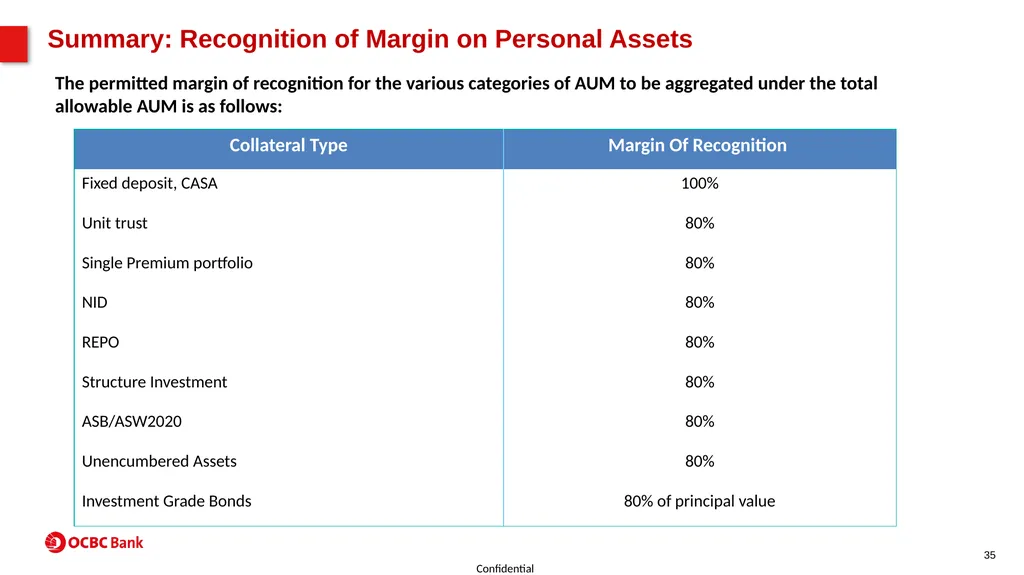
Summary: Recognition of Margin on Personal Assets 35 The permitted margin of recognition for the various categories of AUM to be aggregated under the total allowable AUM is as follows:<br>
36
Valuation 36<br>
37
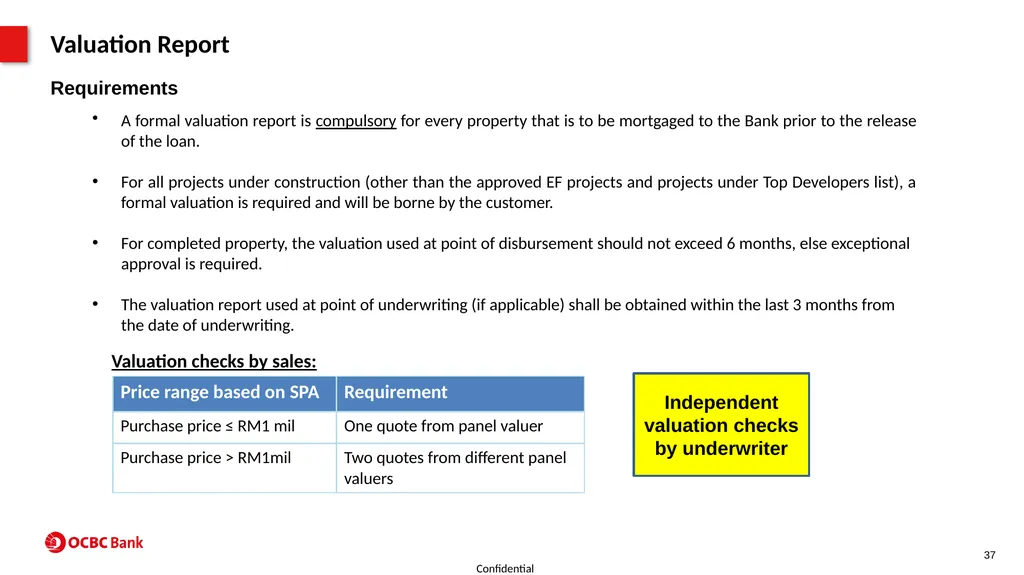
Valuation Report
Requirements A formal valuation report is compulsory for every property that is to be mortgaged to the Bank prior to the release of the loan.
For all projects under construction (other than the approved EF projects and projects under Top Developers list), a formal valuation is required and will be borne by the customer.
For completed property, the valuation used at point of disbursement should not exceed 6 months, else exceptional approval is required.
The valuation report used at point of underwriting (if applicable) shall be obtained within the last 3 months from the date of underwriting.
Valuation checks by sales: 37 Independent valuation checks by underwriter<br>
38
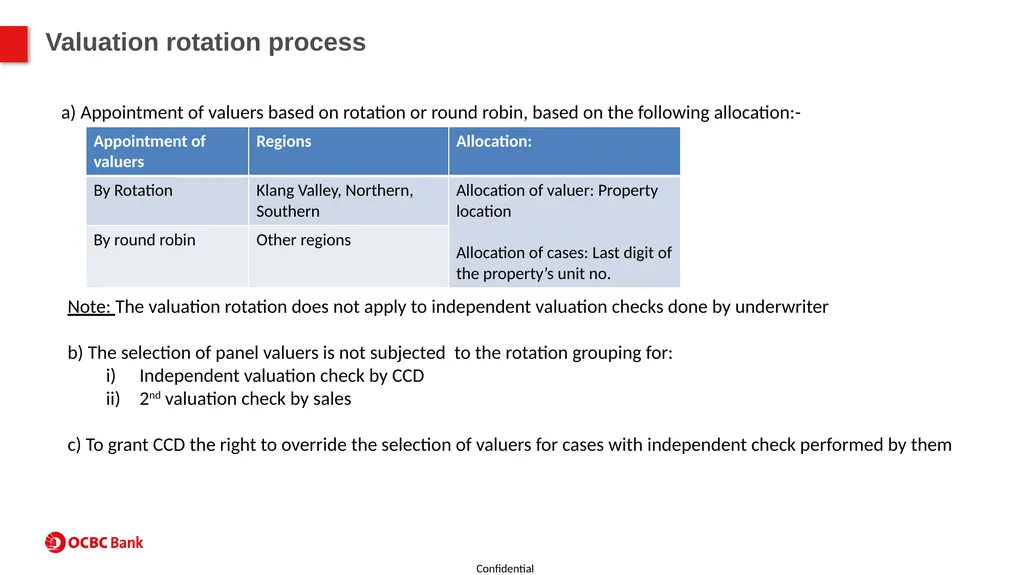
Note: The valuation rotation does not apply to independent valuation checks done by underwriter
b) The selection of panel valuers is not subjected to the rotation grouping for:
Independent valuation check by CCD
2nd valuation check by sales
c) To grant CCD the right to override the selection of valuers for cases with independent check performed by them a) Appointment of valuers based on rotation or round robin, based on the following allocation:- Valuation rotation process<br>
39
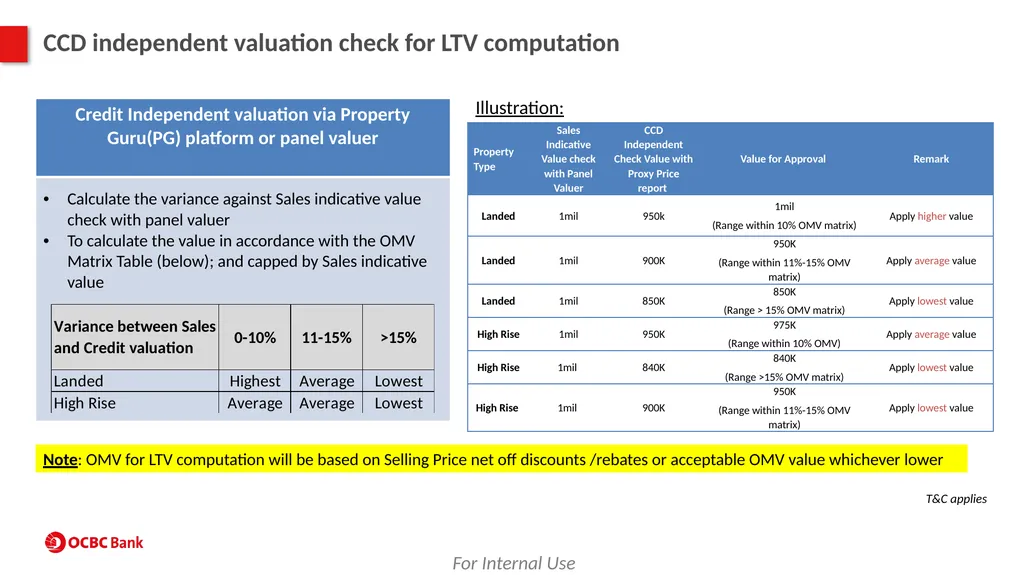
CCD independent valuation check for LTV computation Note: OMV for LTV computation will be based on Selling Price net off discounts /rebates or acceptable OMV value whichever lower T&C applies For Internal Use Illustration:<br>
40
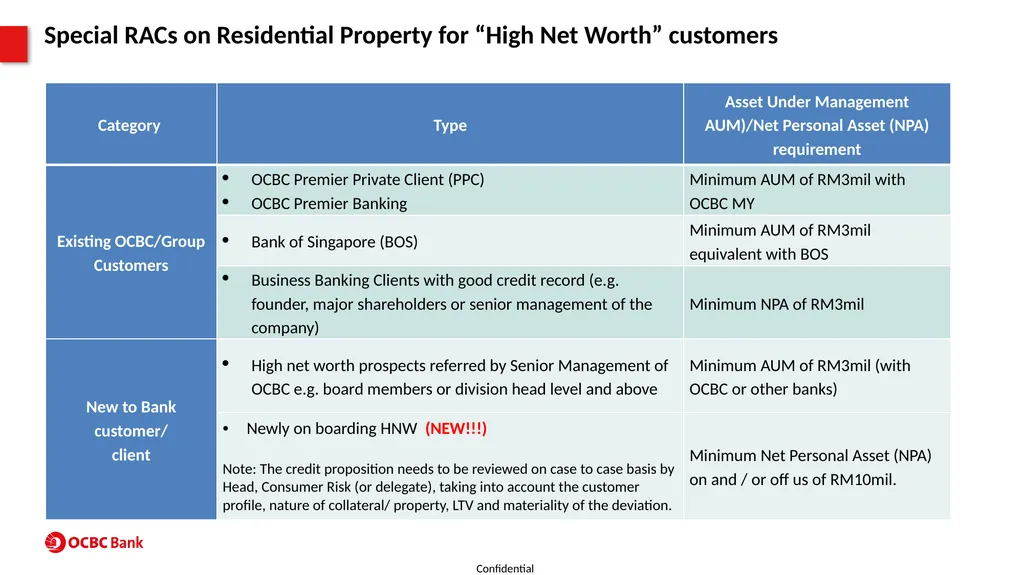
High Net Worth 40 High Net worth (HNW) guiding principles
Special RACs for HNW<br>
Special RACs for HNW<br>
41
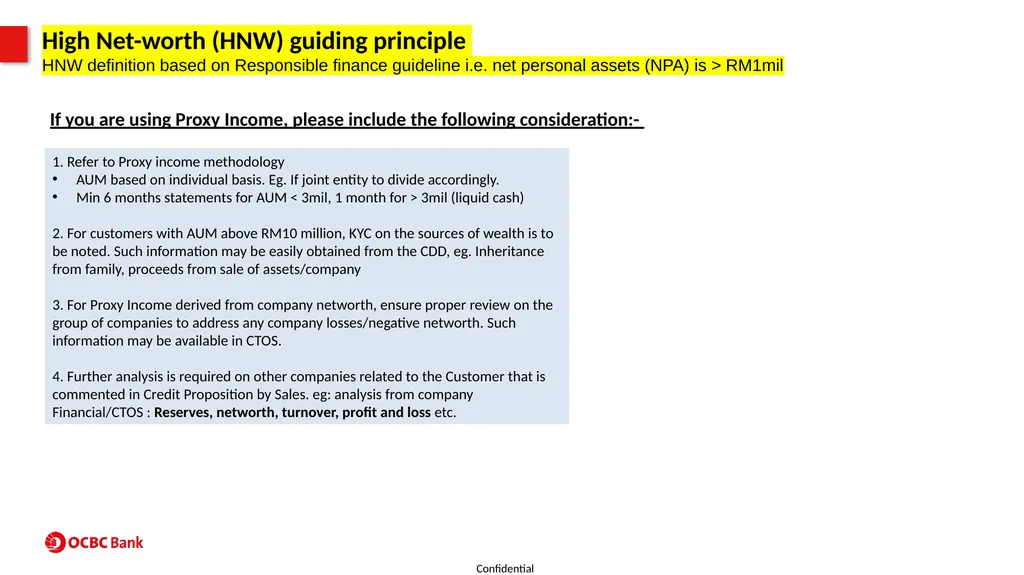
1. Refer to Proxy income methodology
AUM based on individual basis. Eg. If joint entity to divide accordingly.
Min 6 months statements for AUM < 3mil, 1 month for > 3mil (liquid cash)
2. For customers with AUM above RM10 million, KYC on the sources of wealth is to be noted. Such information may be easily obtained from the CDD, eg. Inheritance from family, proceeds from sale of assets/company
3. For Proxy Income derived from company networth, ensure proper review on the group of companies to address any company losses/negative networth. Such information may be available in CTOS.
4. Further analysis is required on other companies related to the Customer that is commented in Credit Proposition by Sales. eg: analysis from company Financial/CTOS : Reserves, networth, turnover, profit and loss etc. If you are using Proxy Income, please include the following consideration:- High Net-worth (HNW) guiding principle
HNW definition based on Responsible finance guideline i.e. net personal assets (NPA) is > RM1mil<br>
42
Special RACs for High Net Worth “(HNW)” customers 42 Back<br>
43
Definition of “High Net Worth” Customer
(i.e. targeted to qualify for the Special RACs) Special RACs on Residential Property for “High Net Worth” customers<br>
(i.e. targeted to qualify for the Special RACs) Special RACs on Residential Property for “High Net Worth” customers<br>
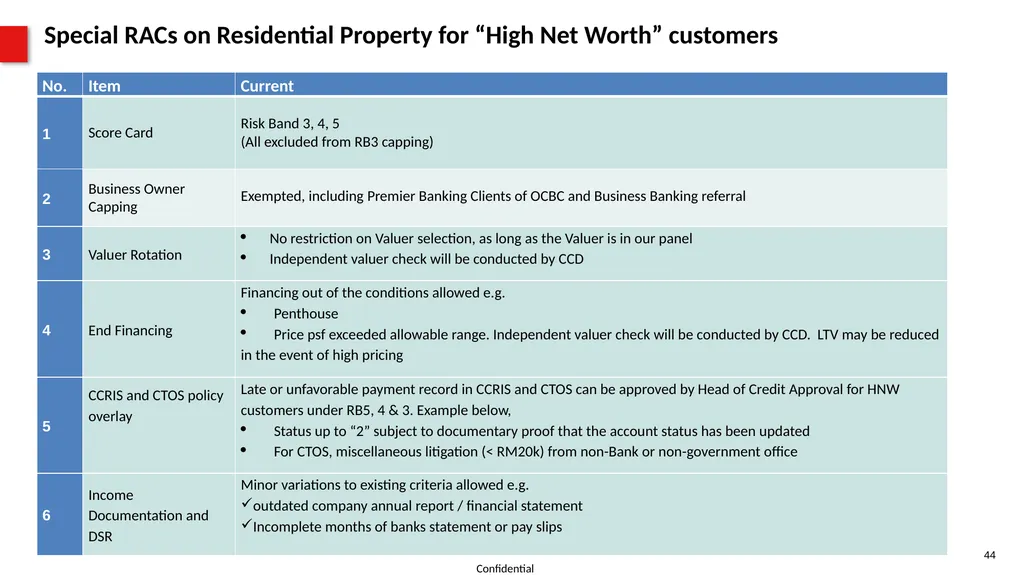
44
44 Special RACs on Residential Property for “High Net Worth” customers<br>
45
45 6. Regulatory
Redraw (Not applicable to Non-Resident)<br>
Redraw (Not applicable to Non-Resident)<br>
46
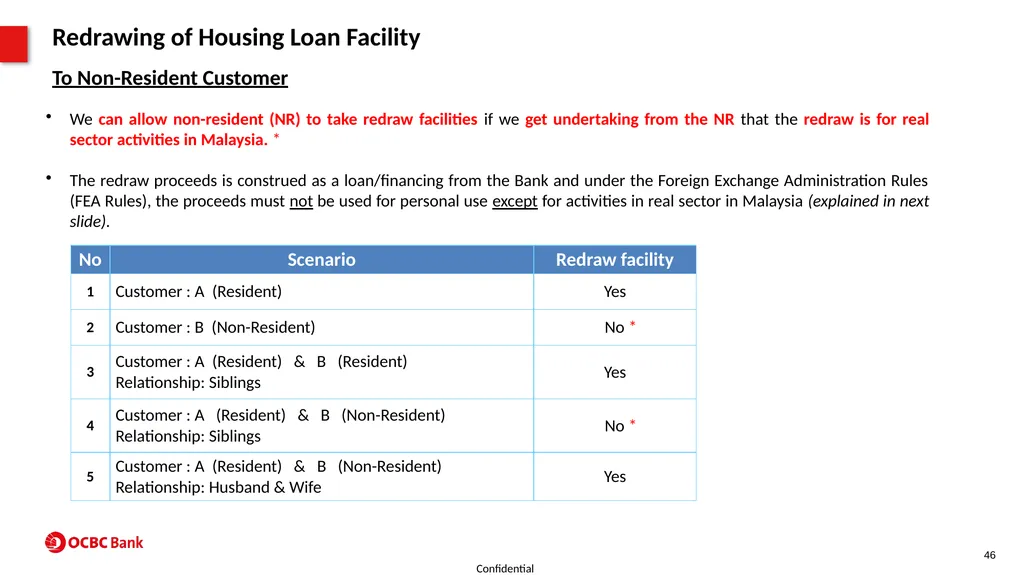
46 Redrawing of Housing Loan Facility
To Non-Resident Customer We can allow non-resident (NR) to take redraw facilities if we get undertaking from the NR that the redraw is for real sector activities in Malaysia. *
The redraw proceeds is construed as a loan/financing from the Bank and under the Foreign Exchange Administration Rules (FEA Rules), the proceeds must not be used for personal use except for activities in real sector in Malaysia (explained in next slide).<br>
The redraw proceeds is construed as a loan/financing from the Bank and under the Foreign Exchange Administration Rules (FEA Rules), the proceeds must not be used for personal use except for activities in real sector in Malaysia (explained in next slide).<br>
47
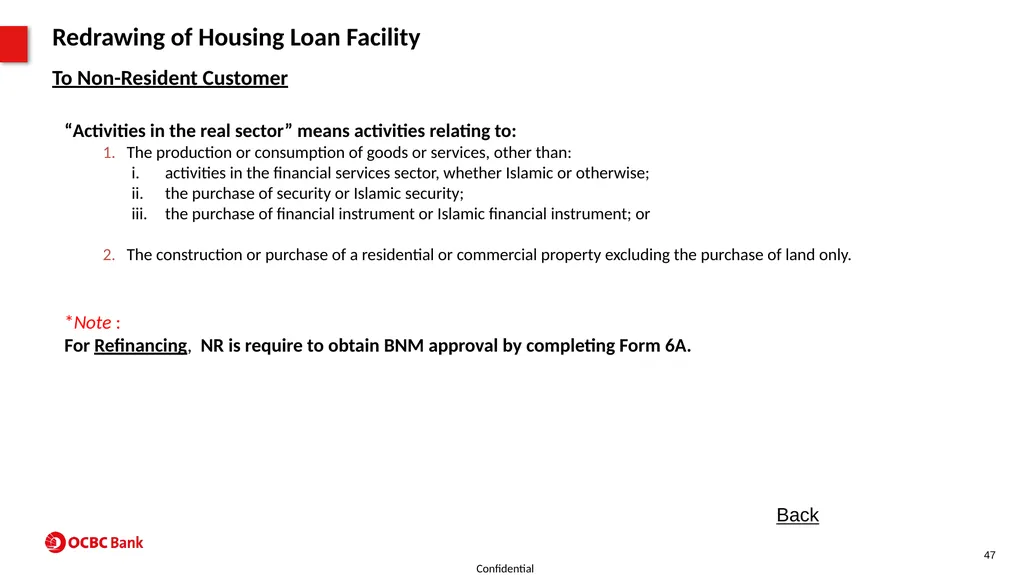
“Activities in the real sector” means activities relating to:
The production or consumption of goods or services, other than:
activities in the financial services sector, whether Islamic or otherwise;
the purchase of security or Islamic security;
the purchase of financial instrument or Islamic financial instrument; or
The construction or purchase of a residential or commercial property excluding the purchase of land only.
*Note :
For Refinancing, NR is require to obtain BNM approval by completing Form 6A. 47 Back Redrawing of Housing Loan Facility To Non-Resident Customer<br>
48
48 7. Financing Products & Others
Types of Secured Financing<br>
Types of Secured Financing<br>
49
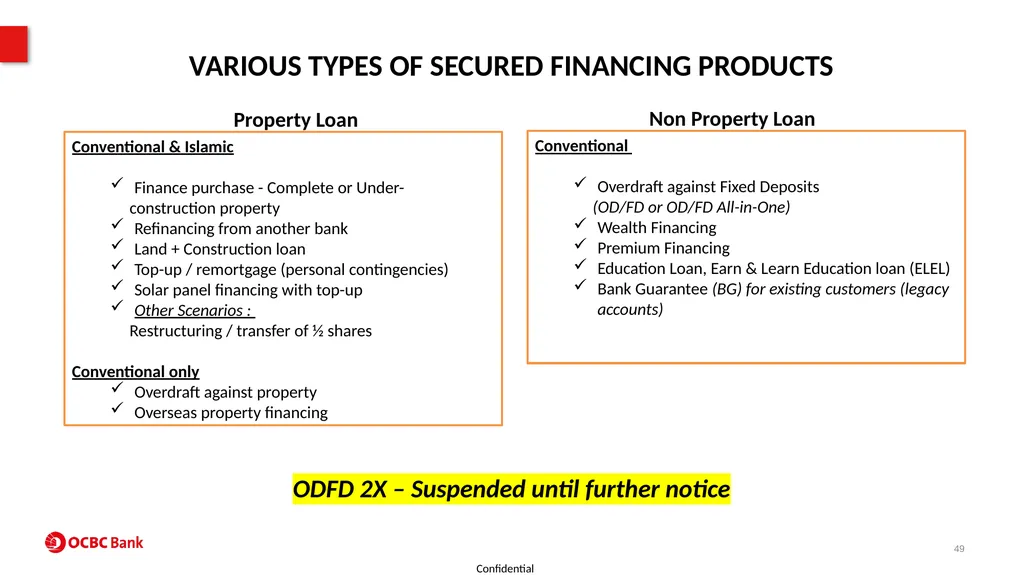
49 VARIOUS TYPES OF SECURED FINANCING PRODUCTS Property Loan Non Property Loan Conventional & Islamic
Finance purchase - Complete or Under-
construction property
Refinancing from another bank
Land + Construction loan
Top-up / remortgage (personal contingencies)
Solar panel financing with top-up
Other Scenarios :
Restructuring / transfer of ½ shares
Conventional only
Overdraft against property
Overseas property financing Conventional
Overdraft against Fixed Deposits
(OD/FD or OD/FD All-in-One)
Wealth Financing
Premium Financing
Education Loan, Earn & Learn Education loan (ELEL)
Bank Guarantee (BG) for existing customers (legacy accounts) ODFD 2X – Suspended until further notice<br>
50
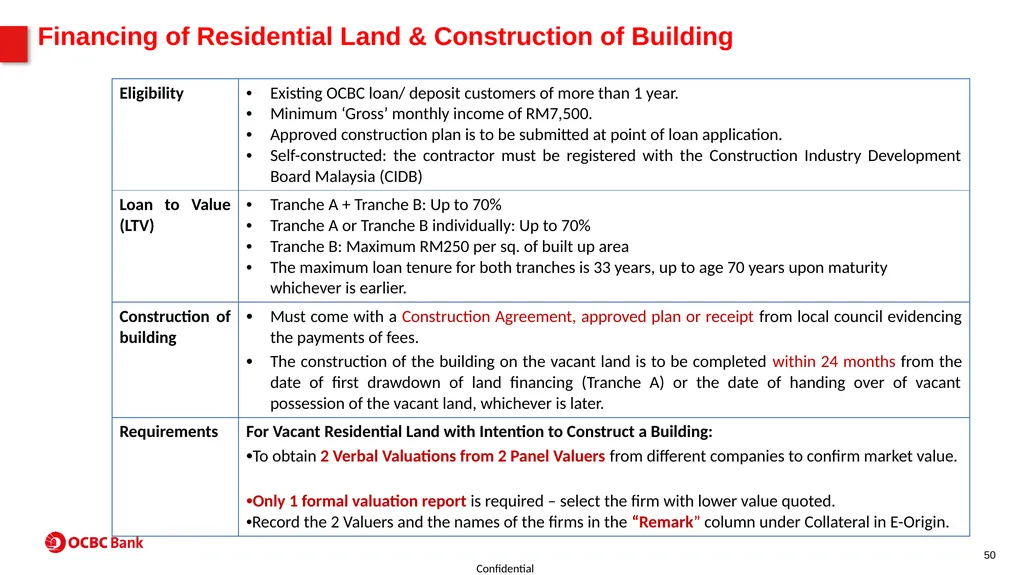
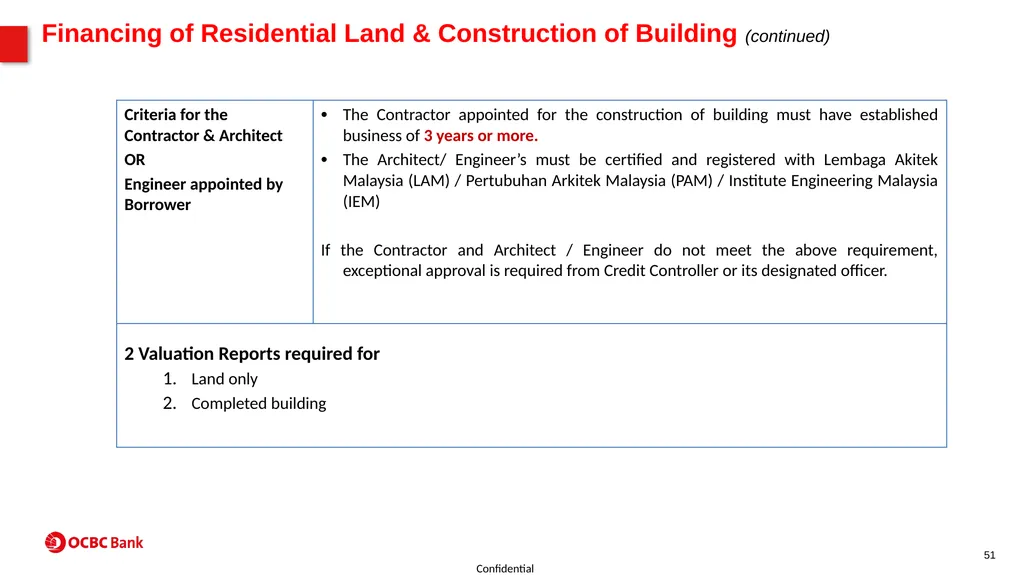
Financing of Residential Land & Construction of Building 50<br>
51
51 Financing of Residential Land & Construction of Building (continued)<br>
52
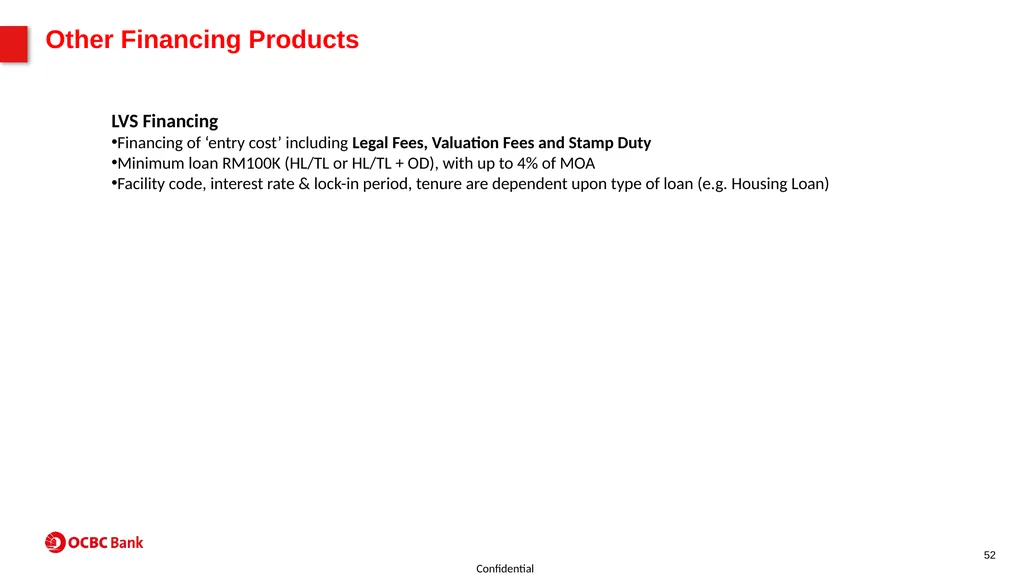
Other Financing Products LVS Financing
Financing of ‘entry cost’ including Legal Fees, Valuation Fees and Stamp Duty
Minimum loan RM100K (HL/TL or HL/TL + OD), with up to 4% of MOA
Facility code, interest rate & lock-in period, tenure are dependent upon type of loan (e.g. Housing Loan) 52<br>
Financing of ‘entry cost’ including Legal Fees, Valuation Fees and Stamp Duty
Minimum loan RM100K (HL/TL or HL/TL + OD), with up to 4% of MOA
Facility code, interest rate & lock-in period, tenure are dependent upon type of loan (e.g. Housing Loan) 52<br>
53
53 8. Appendix
Malay Reserve Land (MRL)<br>
Malay Reserve Land (MRL)<br>
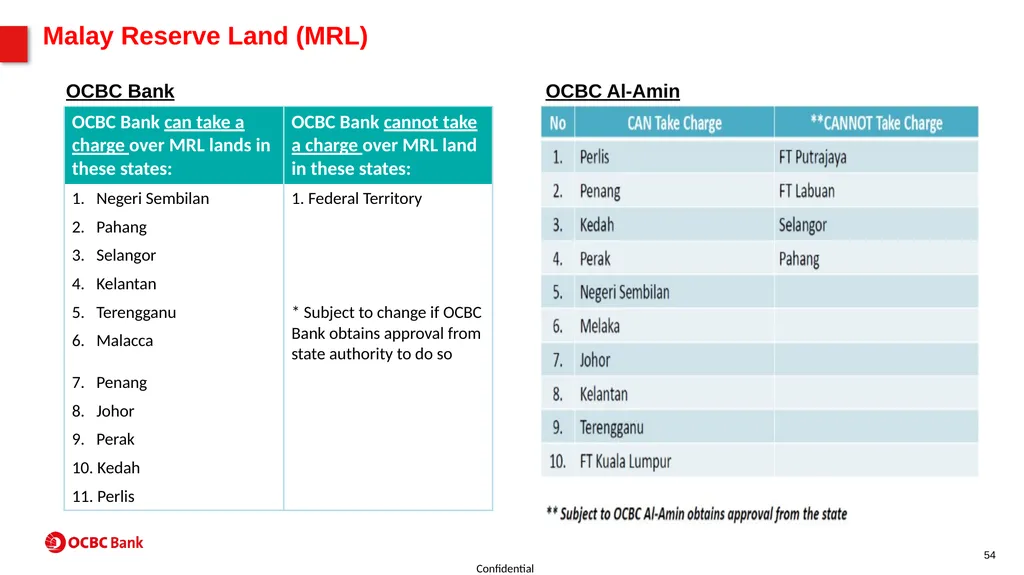
54
Malay Reserve Land (MRL) 54 OCBC Bank OCBC Al-Amin<br>
55
Do you have Home Loan? Do you have Home Loan? Do you have Home Loan? Do you have Home Loan? Do you have Home Loan? Do you have Home Loan? Do you have Home Loan? Do you have Home Loan? Do you have Home Loan? Do you have Home Loan?<br>
56
THANK YOU For Internal Use<br>