
Controversial issues under the Income Tax & Fake


















Description: Controversial issues under the Income Tax Fake Invoice National Conference Indore Branch of CIRC of ICAI 23rd December, 2023 Tushar P. Hemani Senior Advocate Tushar Hemani, Senior Advocate 1 Fake Invoice - IT Accommodation Billing Fake
Related Topics
Download Presentation
"Controversial issues under the Income Tax & Fake" is the property of its rightful owner. Permission is granted to download and print the materials on this website for personal, non-commercial use only, and to display it on your personal computer provided you do not modify the materials and that you retain all copyright notices contained in the materials. By downloading content from our website, you accept the terms of this agreement.
Presentation Transcript
slide1. Controversial issues under the Income Tax
&
Fake Invoice National Conference
Indore Branch of CIRC of ICAI
23rd December, 2023
Tushar P. Hemani
Senior Advocate Tushar Hemani, Senior Advocate 1<br>
slide2. Fake Invoice - IT Accommodation Billing
Fake Billing
Genuine transaction becomes billing transaction due to lack of proof or supplier related issues;
Supplier not traceable
Supplier never existed
Supplier is alleged to be bogus
Supplier is proved to be bogus
Supplier’s GST registration is cancelled prospectively or retrospectively Tushar Hemani, Advocate 2<br>
slide3. PO & Invoice [Invoice Reference Number (IRN)];
E-way bill;
Transport receipt, affidavit of driver;
Weight bridge slip;
Toll payment receipts;
RFID vehicle tracking details;
GSTR1 of Seller, GSTR2B of buyer, GSTR3B filed by both the parties;
Correspondence with supplier;
CCTV footage;
payment details and relevant bank statement;
Internal documents e.g. Inward register, quantity details etc. Tushar Hemani, Senior Advocate 3<br>
slide4. Quantify Details Even though the assessee was a scrap dealer, the addition u/s. 69C on account of bogus purchases was held not justified as assessee had maintained trading account with quantitative tally of purchases, opening stock, sales and closing stock and no discrepancy in such quantitative tally was found - Manoj Sharma v. ITO [2019] 103 taxmann.com 105 (Delhi - Trib.)
What if quantity details are not maintained; Tushar Hemani, Senior Advocate 4<br>
slide5. Burden of Proof Where assessee had submitted purchase bills, transportation bills, confirmed copy of account and VAT Registration of sellers as also their income-tax Return and payment was made through cheques, impugned purchases could not be disallowed - CIT v. Odeon Builders (P.) Ltd. 418 ITR 315 (SC).
Where assessee brought on record name and address of parties, their PAN, TDS deducted, date of bills, details of cheques issued, etc., to establish genuineness of purchase transactions, in such a case, he could not be held responsible for parties not appearing in person and, thus, addition so made under section 69C deserved to be deleted - Pr. CIT v. Chawla Interbild Construction Co. (P.) Ltd. 412 ITR 152 (Bom). Tushar Hemani, Senior Advocate 5<br>
slide6. Natural Justice Merely on suspicion bases on information received from sales Tax authority, assessing officer could not make addition on account of bogus purchases without carrying out independent enquiry and affording opportunity to Assessee to controvert statements made by seller - Pr. CIT v. Shapoorji Pallonji & Co. Ltd. [2022] 288 Taxman 661 (SC).
No addition can be made in respect of bogus purchases merely on the basis of material / information received from the Maharashtra Sales Tax Department without providing such material to the assessee or affording an opportunity to cross examine the concerned parties - Shailesh Keshavlal Shah vs. ITO – ITA 1877 to 1879/Ahd/2015. Tushar Hemani, Senior Advocate 6<br>
slide7. Sales – whether accepted? Bombay High Court in the case of Pr. CIT v. Nitin Ramdeoji Lohia [2022] 145 taxmann.com 546 held that Where AO made addition by disallowing expenses on purchases on ground that an information was received from sales tax department that assessee was beneficiary of accommodation entries on account of bogus purchases, in absence of AO not disputing corresponding sales transactions, purchases could not be treated as bogus and, thus, impugned addition made on account of bogus purchases to be deleted. Tushar Hemani, Senior Advocate 7<br>
slide8. Percentage disallowance CIT vs La Medica 250 ITR 575 (Del) – 100%
Sanjay Oil Cake Ind vs CIT 316 ITR 274 (Guj) – 25%
Pr. CIT v. Suraj Infrastructures (P.) Ltd [2023] 156 taxmann.com 192 (Bombay) – 12.5%
Pr. CIT v. Rakesh Kailashchand Jain [2023] 156 taxmann.com 82 (Gujarat) – 6%
CIT vs. Gujarat Ambuja Export Ltd. – [2014] 43 taxmann.com 244 (Gujarat) – 5% Tushar Hemani, Senior Advocate 8<br>
slide9. Other Approaches Dhondiram Naryan Limbhore vs Pr.CIT 153 taxmann.com 539 (Bom) addition was to be limited to extent of bringing GP rate on tainted purchases at same rate as applied in other genuine purchases.
Nehal Hsamukhari Gandhi vs. DCIT – ITA 2578/Ahd/2017 - NP Tushar Hemani, Senior Advocate 9<br>
slide10. Other Issues Distinction between a trader, manufacturer and/or consumer.
Rejection of books of accounts 145(3);
GP/NP comparison (history & Industry average);
Disallowance u/s 69C – justified? (expenditure incurred and Assessee offers no explanation)
Impact of S. 40A(3) [Hynoup - 290 ITR 702 (Guj)];
GP addition vs addition as percentage of bogus purchases Tushar Hemani, Senior Advocate 10<br>
slide11. Curious case of N K Ind Ltd [2016] 72 taxmann.com 289 (Gujarat) Whether 25% or 100% disallowance is confirmed by HC
Before Guj High Court, both Revenue and Assessee were in appeal.
Assessee was in appeal against confirmation of disallowance @ 25% out of purchases whereas Revenue was in appeal against deletion of 75% out of purchases by the ITAT.
Hon’ble High Court while dismissing both the appeals, gave the following finding: Tushar Hemani, Senior Advocate 11<br>
slide12. “6. The Tribunal in the case of Vijay Proteins Ltd. (supra) has observed that it would be just and proper to direct the Assessing Officer to restrict the addition in respect of the undisclosed income relating to the purchases to 25% of the total purchases. The said decision was confirmed by this Court as well. On consideration of the matter, we find that the facts of the present case are identical to those of M/s. Indian Woollen Carpet Factory (supra) or Vijay Proteins Ltd. (supra) In the present case the Tribunal has categorically observed that the assessee had shown bogus purchases amounting to Rs. 2,92,93,288/- and taxing only 25% of these bogus claim goes against the principles of Sections 68 and 69C of the Income Tax Act. The entire purchases shown on the basis of fictitious invoices have been debited in the trading account since the transaction has been found to be bogus. The Tribunal having once come to a categorical finding that the amount of Rs. 2,92,93,288/- represented alleged purchases from bogus suppliers it was not incumbent on it to restrict the disallowance to only Rs. 73,23,322/-.”
xxx…
9. In view of the above, the impugned judgment and order passed by the Tribunal is modified accordingly. Hence, the present Tax Appeals are dismissed.” Tushar Hemani, Senior Advocate 12<br>
slide13. Assessee preferred SLP against confirmation of 25% which got dismissed. [2017] 84 taxmann.com 195 (SC)
Subsequently, Gujarat High Court itself distinguished judgement in the case of N K Ind. Ltd. In the following cases:
[2019] 106 taxmann.com 316 (Gujarat) Pr. CIT v. Synbiotics Ltd.
[2023] 148 taxmann.com 154 (Gujarat) Pr. CIT v. Surya Impex Tushar Hemani, Senior Advocate 13<br>
slide14. Bogus Billing – GST Tushar Hemani, Senior Advocate 14<br>
slide15. Evidences to prove genuineness of the transaction State of Karnataka vs Ecom Gill Coffee Trading Pvt. Ltd. (2023) 4 Centax 223 (S.C.): “In view of the above and for the reasons stated above and in absence of any further cogent material like furnishing the name and address of the selling dealer, details of the vehicle which has delivered the goods, payment of freight charges, acknowledgement of taking delivery of goods, tax invoices and payment particulars etc. and the actual physical movement of the goods by producing the cogent materials”. Tushar Hemani, Senior Advocate 15<br>
slide16. Evidences GSTR1 of Seller, GSTR2B of buyer, GSTR3B filed by both the parties.
PO & Invoice [Invoice Reference Number (IRN)];
E-way bill;
Transport receipt, affidavit of driver, Weight bridge slip, Toll payment receipts;
RFID/GPS vehicle tracking details, CCTV footage;
payment details and relevant bank statement;
Internal documents e.g. Inward register, quantity details etc.
Correspondence with supplier; Tushar Hemani, Senior Advocate 16<br>
slide17. Scheme of the GST Act GST – tax on supplies of goods or services.
Tax only on value addition – to the extent goods or supplies suffered tax earlier, available in the form of ITC.
Identity of goods or supplies that has suffered tax.
S. 16 - Eligibility and condition for taking ITC - Registered person can claim ITC if he is in possession of tax invoice/debit note etc issued by supplier of goods or services. So ITC can only flow from supplier.
No claim of ITC allowed if tax not paid by supplier into Govt treasure – S. 16(2)(c)
S. 155 - Burden of proof for entitlement of ITC is on the claimant. Tushar Hemani, Senior Advocate 17<br>
slide18. Issues GST investigations reveal that
Supplier not traceable;
Supplier never existed at the billing address;
Supplier is alleged to be bogus as it has no place of business/godown or supplies or has not filied required returns;
Supplier is proved to be bogus as he has confessed during investigation to that effect by giving statement/affidavit.
Supplier’s GST registration is cancelled prospectively or retrospectively;
Supplier’s supplier has any of the above stated issues. Tushar Hemani, Senior Advocate 18<br>
slide19. Consequences Proceedings u/s 73;
Proceedings u/s 74;
Summons u/s 70;
Bank attachment u/s 83;
Arrest u/s 69 rw S. 132. Tushar Hemani, Senior Advocate 19<br>
slide20. S. 73 / S. 74 Insist for formal communication – Intimation (DRC-01A), SCN u/s 73-74 (DRC-01), so that appropriate reply can be filed and defenses can be raised.
No recovery is permissible w/o SCN and adjudication –(Gokak Patel Volkart Ltd. vs. Collector of Central Excise 1987 (28) ELT 53 (S.C.))
Payment under protest via letter is a valid mechanism when no mechanism is notified in the law - India Cements Ltd. vs CCE 1989 (41) E.L.T. 358 (S.C.) Tushar Hemani, Senior Advocate 20<br>
slide21. Scheme of availing the benefit of lower penalty u/s 74(5) of the CGST Act, 2017 is to be exercised at the complete discretion of the taxpayer as the same entails communication of the amounts paid as per the said scheme to the officer to seek conclusion of the proceedings. It cannot apply when the taxpayer intends to contest the matter [Shri Nandhi Dhall Mills India Pvt vs. Senior Senior Intelligence Officer W.P. No. 5192 of 2020) (Mad.)]
“27. Merely because an assesseehas, under the stress of investigation, signed a statement admitting tax liability and has also made a few payments as per the statement, cannot lead to self-assessment or self-ascertainment. The ascertainment contemplated under Section 74(5) is of the nature of self-assessment and amounts to a determination which is unconditional, and not one that is retracted as in the present case. Had such ascertainment/self-assessment had been made, there would be no further proceedings contemplated, as Section 74(6) states that with ascertainment of demand in Section 74(5), no proceedings for show cause under Section 74(1) shall be issued. In this case, enquiry and investigation are on-going, personal hearings have been afforded and both the parties are fully geared towards issuing/receiving a show cause notice and taking matters forward. Thus, the understanding and application of Section 74(5) in this case, is, in my view, wholly misconceived.” Tushar Hemani, Senior Advocate 21<br>
slide22. Only the first buyer needs to pay tax in a chain of transactions (Circular 171 dt. 06/07/2022).
Instruction No. 01/2022-23 dated 25.05.2022 – No collection or deposit of tax during the course of search, inspection or investigation. Unless deposited voluntarily. Tushar Hemani, Senior Advocate 22<br>
slide23. Summons, Bank Attachment & Arrest Summons - Instruction No. 03/2022-23 dated 17.08.2022 – Guidelines for issuance of summons – no summons for collecting statutory records, or to call MD, CFO unless necessary.
Bank attachment - Provisional attachment S. 83 –after initiation of proceedings under chapters XII, XIV, XV – Commissioner is of the opinion that in order to protect interest of the revenue – (Radha Krishan Industries v. State of Himachal Pradesh — 2021 (48) G.S.T.L. 113 (S.C.) Tushar Hemani, Senior Advocate 23<br>
slide24. Arrest and Bail - Instruction No. 02/2022-23 dated 17.08.2022 – Power to be exercised exceptionally. Arrest only when “the need to ensure proper investigation and prevent the possibility of tempering with evidence or intimidating or influencing witness exists.” No arrest in case of default of technical nature or when assessee co-operates. Tushar Hemani, Senior Advocate 24<br>
slide25. Technical Defenses Affidavit of the supplier – Examination in chief required by the Adjudicating Authority (G-Tech Industries Versus Union of India and Others 2016 (339) ELT 209 P&H) & Cross-examination to be demanded (Swadeshi Polytex Limited Versus Collector of Central Excise, Meerut 2000 (122) ELT 641 (SC))
ITC cannot be denied on account of misconduct at the end of the supplier’s supplier in the absence of any collusion (Balaji Exim vs. Commissioner, CGST [2023] 149 taxmann.com 44 (Delhi) Tushar Hemani, Senior Advocate 25<br>
slide26. Bogus Billing – GST vs IT During the course of an IT search, material is found indicating unaccounted turnover outside the books. IT department proposes to add the said turnover on the basis of the seized documents. Assessee wants to surrender only GP on this unaccounted turnover. However, Assessee is worried about GST consequences. Kindly advice. Tushar Hemani, Senior Advocate 26<br>
slide27. During the course of GST search, material is found indicating purchases from dealers whose registration were found to be cancelled ab-initio as they were found to be indulging into bogus billing without actual supply of material. Assessee is asked to reverse the ITC claimed from such supplier on the ground that the same is fake and fraudulent. Assessee wants to surrender such ITC and pay the necessary amount into the Govt. treasury. However, Assessee is worried about IT consequences. Kindly advice. Tushar Hemani, Senior Advocate 27<br>
slide28. In an income tax assessment, sales are treated as accommodation entries and addition to that effect is made u/s 68 of the IT Act. GST department on the strength of such AO, want to treat the said sales as billing transaction and deny ITC in the hands of the purchaser. Recovery notices for wrong claim of ITC is issued against the said purchaser. Kindly advice. (Circular No. 171/03/2022-GST dated 06/07/2022, Example 3) Tushar Hemani, Senior Advocate 28<br>
slide29. Interplay between
IBC & Income Tax Tushar Hemani, Senior Advocate 29<br>
slide30. Tata Steel Ltd. vs. DCIT W.P.(C) 13188/2018 Facts:
Assessment order for AY 2001-02 was passed on 28.02.2003. Addition was confirmed upto High Court. SLP has been accepted by Supreme Court & is pending for adjudication.
Assessment order vis-à-vis AY 2009-10, 2010-11 & 2013-14 was passed on 30.12.2016. CIT(A) dismissed the first appeal & also triggered penalty proceedings u/s. 271(1)(c). Second appeal with ITAT is pending.
Insolvency proceedings were triggered against the assessee. Petition was admitted by NCLT on 26.07.2017
Public announcement was published on 28.07.2017. Tushar Hemani, Senior Advocate 30<br>
slide31. Revenue lodged its claims to Interim Resolution Professional (IRP) on 28.09.2017, 24.10.2017 & 25.10.2017 for AY 2009-10, 2010-11 & 2013-14 but not for AY 2001-02.
Penalty order u/s. 271(1)(c) vis-à-vis AY 2009-10, 2010-11 & 2013-14 was passed on 23.04.2018.
Resolution Plan was admitted by NCLT on 15.05.2018.
Notice u/s. 221(1) was issued on 28.08.2018 requiring assessee to deposit tax for all 4 AYs & seeking response as to why penalty u/s. 221(1) shall not be levied.
Revenue lodged an updated claim with Resolution Professional (RP) on 20.09.2018 wherein the claim for the demand of tax for AY 2001-02 & penalties for all 4 assessment years were added. Tushar Hemani, Senior Advocate 31<br>
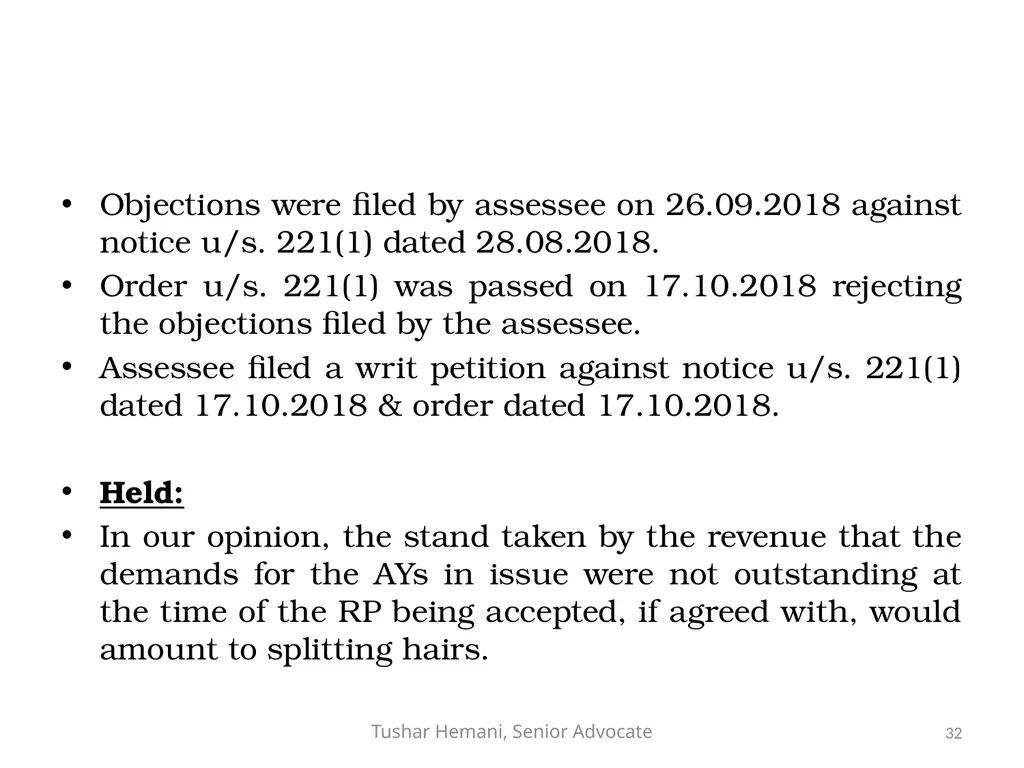
slide32. Objections were filed by assessee on 26.09.2018 against notice u/s. 221(1) dated 28.08.2018.
Order u/s. 221(1) was passed on 17.10.2018 rejecting the objections filed by the assessee.
Assessee filed a writ petition against notice u/s. 221(1) dated 17.10.2018 & order dated 17.10.2018.
Held:
In our opinion, the stand taken by the revenue that the demands for the AYs in issue were not outstanding at the time of the RP being accepted, if agreed with, would amount to splitting hairs. Tushar Hemani, Senior Advocate 32<br>
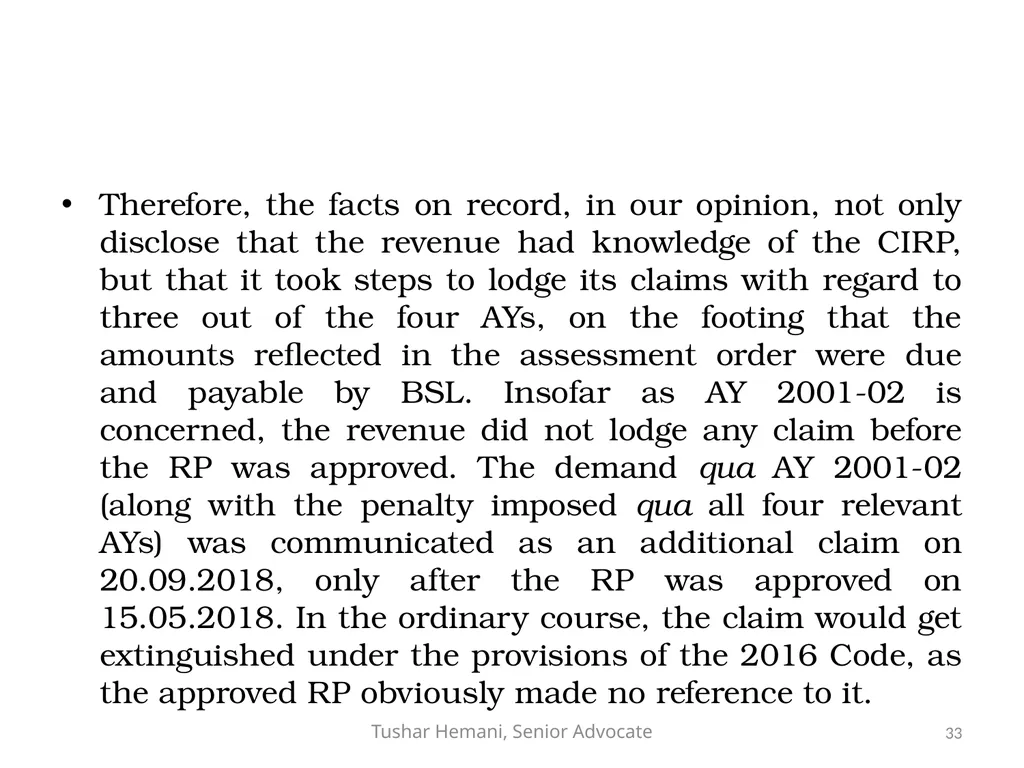
slide33. Therefore, the facts on record, in our opinion, not only disclose that the revenue had knowledge of the CIRP, but that it took steps to lodge its claims with regard to three out of the four AYs, on the footing that the amounts reflected in the assessment order were due and payable by BSL. Insofar as AY 2001-02 is concerned, the revenue did not lodge any claim before the RP was approved. The demand qua AY 2001-02 (along with the penalty imposed qua all four relevant AYs) was communicated as an additional claim on 20.09.2018, only after the RP was approved on 15.05.2018. In the ordinary course, the claim would get extinguished under the provisions of the 2016 Code, as the approved RP obviously made no reference to it. Tushar Hemani, Senior Advocate 33<br>
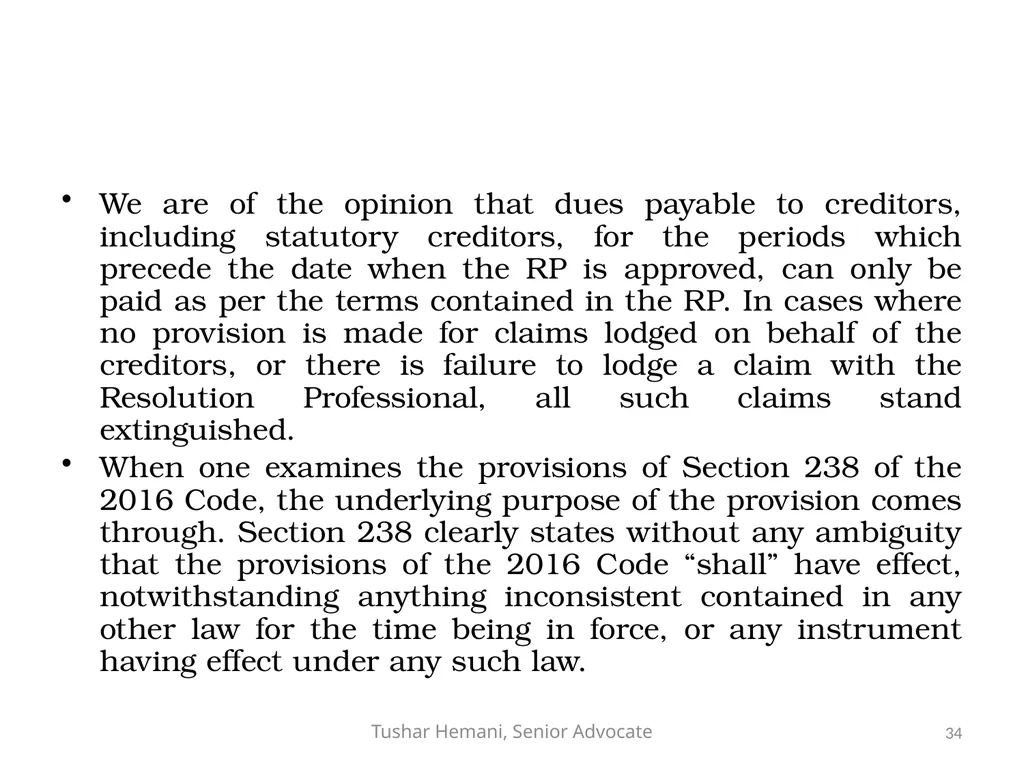
slide34. We are of the opinion that dues payable to creditors, including statutory creditors, for the periods which precede the date when the RP is approved, can only be paid as per the terms contained in the RP. In cases where no provision is made for claims lodged on behalf of the creditors, or there is failure to lodge a claim with the Resolution Professional, all such claims stand extinguished.
When one examines the provisions of Section 238 of the 2016 Code, the underlying purpose of the provision comes through. Section 238 clearly states without any ambiguity that the provisions of the 2016 Code “shall” have effect, notwithstanding anything inconsistent contained in any other law for the time being in force, or any instrument having effect under any such law. Tushar Hemani, Senior Advocate 34<br>
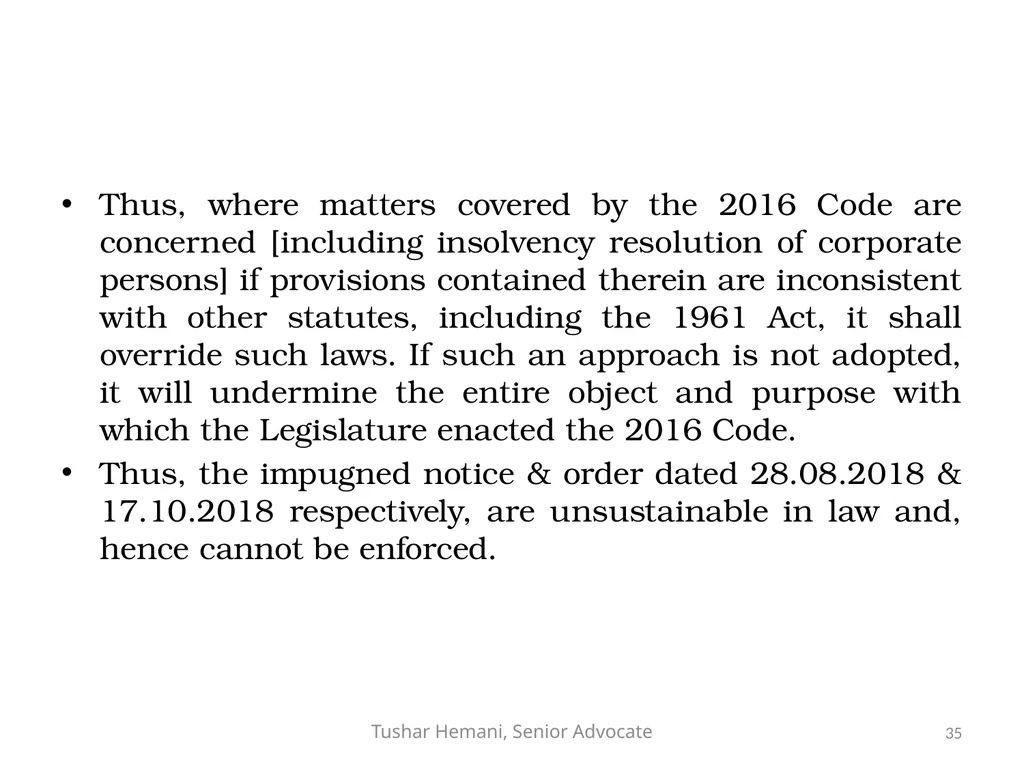
slide35. Thus, where matters covered by the 2016 Code are concerned [including insolvency resolution of corporate persons] if provisions contained therein are inconsistent with other statutes, including the 1961 Act, it shall override such laws. If such an approach is not adopted, it will undermine the entire object and purpose with which the Legislature enacted the 2016 Code.
Thus, the impugned notice & order dated 28.08.2018 & 17.10.2018 respectively, are unsustainable in law and, hence cannot be enforced. Tushar Hemani, Senior Advocate 35<br>
slide36. Rishi Ganga Power Corporation Ltd. vs. ACIT W.P.(C) 3167/2020 Facts:
Notices u/s. 143(2) were issued on 09.08.2018, 28.09.2018 & 30.09.2018 followed by a notices u/s. 142(1) dated 14.03.2019, 22.10.2019 & 04.11.2019.
None of the notices were complied, hence a penalty order u/s. 272A(1)(d) was passed on 21.11.2019.
Eventually an ex-parte assessment order u/s. 143(3) came to be passed on 06.12.2019.
Meanwhile a petition was filed under IBC against the assessee which was admitted by NCLT on 25.01.2018.
Consequent to insolvency proceedings, public announcement was made on 31.01.2018 which was published in various newspapers on 02.02.2018 & 03.02.2018. Tushar Hemani, Senior Advocate 36<br>
slide37. No claims were lodged by the Revenue being an operational creditor, with Resolution Professional (RP).
Resolution Plan was approved by NCLT on 13.11.2018.
On 11.02.2020, the new management who has taken over the affairs of the assessee, wrote to AO, explaining reasons for non-participation in assessment proceedings and requesting the AO for deletion of additions made thereunder.
Since there was no response from revenue, the assessee filed a writ petition in the High Court. Tushar Hemani, Senior Advocate 37<br>
slide38. Held:
Revenue argued that it has not lodged claims with the RP pursuant to public announcement on 31.01.2018 because claims had not fructified into demands on that date. The assessment order resulting in demand was passed on 06.12.2019.
IBBI (Insolvency Resolution Process for Corporate Persons) Regulations, 2016 require operational creditors to submit their claim with proof to the IRP, which are not necessarily claims that have been adjudicated. As per Regulation 7 of 2016 Regulations, operational creditors must file their claims with proof in the prescribed form i.e. Form B. Regulation 7, when read alongside particulars sought against Sr. No. 6 of Form B, would drive home the point that it can include claims that are disputed. Tushar Hemani, Senior Advocate 38<br>
slide39. Furthermore, the definition of claim u/s. 3(6)(a) of the 2016 Code puts these aspects beyond doubt:
“3. Definitions.- In this Code, unless the context otherwise requires,-
xxx xxxxxx
(6) “claim” means-
(a) a right to payment, whether or not such right is reduced to judgment, fixed, disputed, undisputed, legal, equitable, secured or unsecured;” Tushar Hemani, Senior Advocate 39<br>
slide40. Thus, having regard to the fact that the revenue had not lodged its claim, despite the publication of the public announcement by the Resolution Professional inviting claims from creditors, including statutory/operational creditors such as the revenue, no provision could be made [even if it may otherwise have been possible] in the approved RP. The terms contained in the approved RP are binding on all stakeholders, including those who could have filed claims but chose not to lodge them. The revenue, having failed to lodge its claim, cannot enforce the impugned orders and notices, given the binding nature of the approved RP. Tushar Hemani, Senior Advocate 40<br>
slide41. Section 31 of the 2016 Code, among other things, stipulates that once the RP is approved, it shall be binding on the corporate debtor and its employees, members, and creditors, which includes the Central Government, State Government, Local Authority to whom a debt in respect of payment of dues arising under any law for the time being in force and also on authorities to whom statutory dues are owed.
Accordingly, the assessment and penalty orders were quashed. Tushar Hemani, Senior Advocate 41<br>
slide42. Reopening Tushar Hemani, Senior Advocate 42<br>
slide43. Ganesh Dass Khanna vs ITO [WP(c) 11527/2022, dated 10/11/2023] Facts:
Notices u/s 148 of the unamended IT Act came to be issued for AY 2016-17 on 30.6.2021) & AY 2017-18 on 28.06.2021.
Pursuant to judgement of Supreme Court in case of Union of India v. Ashish Agarwal [2022] 444 ITR 1 (SC), revenue issued another notice under section 148A(b) dated 20-5-2022.
Assessee contended that reassessment proceedings triggered against it were time-barred as limitation period of three years qua relevant assessment years had expired and alleged escapement was below Rs.50 lacs. Tushar Hemani, Senior Advocate 43<br>
slide44. Issue:
After the coming into force of FA 2021, in cases where, for the relevant AY, the alleged escaped income was less than Rs.50 lakhs, notice under Section 148 could only be issued for commencement of reassessment proceedings within the limitation period provided in Clause (a) of Section 149(1) of the amended 1961 Act.
Consequently, for AYs 2016-17 & 2017-18, whether the order passed under Section 148A(d) and the consequent notice issued under Section 148 of the amended 1961 Act falls foul of the limitation prescribed in Clause (a) of Sub-Section (1) of Section 149?
Thus, in the ordinary course, the limitation for AY 2016-17 would expire on 31.03.2020; likewise, for AY 2017-18, the end date for the culmination of the limitation period would be 31.03.2021.
The revenue seeks to take recourse to the provisions of Section 3(1) of TOLA and the Notifications issued thereunder, from time to time, which, in effect, extended the end date for completion of proceedings and compliances up until 30.06.2021. Tushar Hemani, Senior Advocate 44<br>
slide45. Further following arguments were raised by the Revenue:
First, the observations made in the judgment of the Supreme Court in Ashish Agrawal‟s case.
Second, the observations made in paragraphs 98 and 99 by the coordinate bench in Mon Mohan Kohli‟s case.
Third, the extension of the time limit, as noticed hereinabove, granted via the subject Notifications by the Central Government in the exercise of powers under Section 3(1) of TOLA.
Fourth, the third and fourth provisos appended to Section 149 of the 1961 Act, which provide for the exclusion of periods referred to therein, which, if excised, would bring the impugned notices and orders within the limitation prescribed under Section 149(1)(a) of the amended 1961 Act.
Fifth, the issue raised before the Court is no longer res integra, given the judgments rendered by the coordinate bench in Touchstone and Salil Gulati. Tushar Hemani, Senior Advocate 45<br>
slide46. Held:
“Concededly, these notices were issued between 01.04.2021 and 30.06.2021, by which time limitation of three years under section 149(1)(a) had already expired and, thus, same were barred by limitation at the inception itself.”
Furthermore, the reference made in paragraphs 6.1 and 6.2(ii) of the Instruction dated 11.05.2022, to the extent it propounds the “travel back in time” theory, is declared bad in law. Tushar Hemani, Senior Advocate 46<br>
slide47. Kankanala Ravindra Reddy vs. ITO [2023] 156 taxmann.com 178 (Telangana) Facts:
For the AY 2016-17, the jurisdictional AO issued a notice to the assessee under section 148A and proceeded to reassess the income of the assessee and passed a further order under section 148A(d) and issued a reopening notice under section 148.
The assessee filed a writ petition contending that the reassessment has to be conducted in a faceless manner, rather than being assessed by the jurisdictional officer as was provided under section 144B and in accordance with the scheme enacted by the Central Government under section 151A. Tushar Hemani, Senior Advocate 47<br>
slide48. Held:
On preferring a writ before the Hon’ble High Court, it was observed that the Hon’ble Supreme Court in the case of Union of India vs. Ashish Agarwal – 444 ITR 1, ordered that notices issued under section 148 after enactment of Finance Act, 2021 shall be deemed to be notices issued under section 148A i.e. new provision inserted by Finance Act, 2021. However, the Hon’ble Supreme Court has only permitted the revenue to proceed further with reassessment proceedings under the amended provisions of law, more particularly, as amended by Finance Act, 2021. Tushar Hemani, Senior Advocate 48<br>
slide49. It was observed that certain provisions of the Income-tax Act which stood amended with effect from 1-4-2021 by virtue of the Finance Act, 2021. Section 144B inserted by virtue of the Finance Act, 2021, with effect from 1-4-2021 provides for faceless assessment and subsection (1) of the said newly inserted section 144B is an non obstante clause. Sub-section (1) of section 151A was inserted with effect from 1-11-2020 which refers to faceless assessment of income escaping assessment. Section 130 was amended so far as conferring jurisdiction of income tax authorities in light of faceless assessment procedure. Tushar Hemani, Senior Advocate 49<br>
slide50. In furtherance to the powers conferred under sub-sections (1) and (2) of section 130, CBDT framed a scheme called as the 'Faceless Jurisdiction of Income-tax Authorities Scheme, 2022.’ which defines automated allocation.
Further, CBDT again in exercise of its powers conferred under sub-sections (1) and (2) of section 151A framed another scheme called as the e-assessment of Income Escaping Assessment Scheme, 2022, which defines automated allocation and the scope of the scheme again has been envisaged in section 3 of the said scheme. Tushar Hemani, Senior Advocate 50<br>
slide51. After the introduction of the above two schemes, it becomes mandatory for the revenue to conduct/initiate proceedings pertaining to reassessment under sections147, 148 & 148A in a faceless manner. Proceedings under section 147 and section 148 would now have to be taken as per the procedure legislated by the Parliament in respect of reopening/reassessment i.e., proceedings under section 148A.
In the instant case, both the proceedings i.e., the impugned proceedings under section 148A, as well as the consequential notices under section 148 were issued by the local jurisdictional officer and not in the prescribed faceless manner. The order under section 148A(d) and the notices under section 148 are issued on 29-7-2022, i.e., after the 'Faceless Jurisdiction of the Income-tax Authorities Scheme, 2022’ and the 'e-Assessment of Income Escaping Assessment Scheme, 2022' were introduced. Tushar Hemani, Senior Advocate 51<br>
slide52. In the instant case, undisputedly the department has not proceeded against the petitioner under the substituted provisions of the Finance Act, 2021. Rather, it proceeded with the unamended provisions of law.
Hence, the impugned notice was set aside/quashed. Tushar Hemani, Senior Advocate 52<br>
slide53. 143(1) followed by 143(3) Tushar Hemani, Senior Advocate 53<br>
slide54. NSE Ltd. vs. DCIT ITA No. 732/Mum/2023 Facts:
Return of income was processed u/s. 143(1) disallowing an expenditure marked as capital expenditure in the tax audit report without considering the response of the assessee to proposed adjustments u/s. 143(1)(a)
Rectification u/s. 154 was filed, however no order was made by CPC, hence an appeal was filed before CIT(A).
Meanwhile, order u/s. 143(3) was passed on 28.09.2022 where no query was raised w.r.t. issue of allowability of such expenditure.
Thereafter CIT(A) passed his order on 12.01.2023 dismissing the assessee’s appeal against adjustment u/s. 143(1). Tushar Hemani, Senior Advocate 54<br>
slide55. Held:
The ITAT observed that neither assessee’s response to proposed adjustment was considered, nor application u/s. 154 was disposed of, amounting to violation of proviso 1 and 2 of the section 143(1) and making whole action null and void. Further, as the case of assessee was scrutinized u/s. 143(2) and assessment order u/s. 143(3) was passed, technically the doctrine of merger comes into picture, therefore the impugned adjustment by CPC gets merged into order passed u/s. 143(3) of the Act and order passed u/s. 143(3) only survives. Hence, the whole issue becomes academic including the order passed by CIT(A).
As far as reporting by Tax Auditor is concerned, maybe he has been appointed by the assessee, still his independence is always assumed and he is always free to give his own legal opinion, but the same is not binding on assessee or revenue. Tushar Hemani, Senior Advocate 55<br>
slide56. Controversies
u/s 197 of the Act Tushar Hemani, Senior Advocate 56<br>
slide57. ST Engineering Electronics Ltd. vs. ACIT ITA No. 755/Chny/2022 Facts:
Assessee has entered into fixed price sub-contract with the awardee of contract for undertaking signaling, platform screen doors & telecommunication work for Chennai Metro Rail Project. Assessee follows percentage of completion method (POCM) as per AS-7.
Assessee has obtained lower deduction certificate u/s. 197 by providing estimated costs & revenue details for FY 2012-13 till FY 2017-18 until which contract was expected to be completed.
Projected revenue under application u/s. 197 for FY 2017-18 was Rs. 2587.75 lakhs, however the revenue as per financial statements was Rs. 1146.03 lakhs along with a contract loss of Rs. 495.65 lakhs. Tushar Hemani, Senior Advocate 57<br>
slide58. Assessee submitted that the duration of project got extended to FY 2020-21. Revenue & costs were recorded as per POCM. Unrecognized portion of revenue was recorded & offered to tax in succeeding years.
Still, AO made an addition of shortfall in revenue in financial statements & application u/s. 197, after getting directions from DRP. Tushar Hemani, Senior Advocate 58<br>
slide59. Held:
The Hon’ble ITAT observed that in the application u/s. 197, the assessee has merely projected the contract revenue and these estimations could not be taken to be turnover disregarding revenue earned by assessee based on actual work certified by the contractor.
The deviation in estimation & actual revenue stood explained by the fact that duration of project got extended much beyond the original contract period.
Further, the aggregate contract revenue has been offered to tax over the life of the contract period starting from FY 2012-13 to FY 2022-23. Hence, taxing more amounts in this year would result into bringing to tax contract revenues much more than fixed price contract value to be received over life of the contract.
The appeal of the assessee stands allowed. Tushar Hemani, Senior Advocate 59<br>
slide60. Shreyansh Retail Pvt Ltd vs. DCIT W.P.(C) 11877/2023 Facts:
Assessee applied for Lower Deduction of tax certificate (LDC) seeking rate of TDS at 0.01% as against rate of 1% prescribed u/s 194O.
Assessee submitted various details called for by the DCIT along with calculation of projected tax refund of Rs. 45.05 crores under 0.5% TDS rate.
A non-speaking order was passed permitting deduction of TDS @ 0.5% as against 0.01% sought by the assessee. Tushar Hemani, Senior Advocate 60<br>
slide61. Held:
The Hon’ble Delhi High Court observed that the Impugned Order set forth no reasons for not accepting the rate of 0.01% as requested by the assessee.
At the request of the DR, an opportunity was granted to department to file a counter-affidavit furnishing reasons as regards conclusion arrived at in the Impugned Order.
However, the Court set aside the order by observing that the Impugned Order must stand on its own legs, & accordingly, reasons furnished by a counter-affidavit could not be supplanted in the Impugned Order.
Reliance was placed on the case of Mohinder Singh Gill v. Chief Election Comm., (1978) 1 SCC 405, wherein the Hon’ble Supreme Court held as under: Tushar Hemani, Senior Advocate 61<br>
slide62. “8. The second equally relevant matter is that when a statutory functionary makes an order based on certain grounds, its validity must be judged by the reasons so mentioned and cannot be supplemented by fresh reasons in the shape of affidavit or otherwise. Otherwise, an order bad in the beginning may, by the time it comes to court on account of a challenge, get validated by additional grounds later brought out. We may here draw attention to the observations of Bose, J. in Gordhandas Bhanji [Commr. of Police, Bombay v. Gordhandas Bhanji, 1951 SCC 1088 : AIR 1952 SC 16] : Tushar Hemani, Senior Advocate 62<br>
slide63. “Public orders, publicly made, in exercise of a statutory authority cannot be construed in the light of explanations subsequently given by the officer making the order of what he meant, or of what was in his mind, or what he intended to do. Public orders made by public authorities are meant to have public effect and are intended to affect the acting and conduct of those to whom they are addressed and must be construed objectively with reference to the language used in the order itself.”
Orders are not like old wine becoming better as they grow older.” Tushar Hemani, Senior Advocate 63<br>
slide64. Bitkuber Investments P. Ltd. & others vs. DCIT W.P. No. 11565 of 2023 Facts:
Assessee company got incorporated in March, 2021 and has started its operations in April, 2022.
Assessee is part of group entities including M/s. Bitcipher Labs LLP & Chain Laps Pte. Ltd. (Singapore) (“M/s. Bitcipher”).
Assessee applied for Non-deduction of TDS certificate u/s. 197 for FY 2023-24.
The application u/s. 197 got rejected majorly on following grounds:
Assessee cannot avail assistance of Rule 28AA
There is no precedential guidance for examining the basis of estimation Tushar Hemani, Senior Advocate 64<br>
slide65. iii. A survey u/s. 133A is conducted on M/s. Bitcipher’s premises resulting in initiation of proceedings u/s. 201.
iv. Ambiguity in transactions under different agreements between assessee and M/s. Bitcipher which are under common control of Chain Labs Pte. Ltd. like:
Agreements are executed after survey u/s. 133A
It is not clear whether any asset would remain with M/s. Bitcipher to discharge liability u/s. 201
Agreements do not have specific clauses on present & future liability of M/s. Bitcipher, there is no clarity on how the tax will be discharged. Tushar Hemani, Senior Advocate 65<br>
slide66. Held:
Section 197(2A) stipulates that CBDT may make Rules specifying cases & circumstances under which application can be made, conditions s.t. which certificate may be granted & matters connected therewith.
However, those conditions cannot impose a classification amongst the assessees to even file an application when provisions do not contemplate the same. Tushar Hemani, Senior Advocate 66<br>
slide67. Rule 28AA(2) requires the AO to determine existing & estimated liability after considering the following:
tax payable on estimated income of previous year (PY)
tax payable on assessed/returned/estimated income, as the case may be, for last 4 PYs.
Existing liability under Income Tax/Wealth Tax Act
Advance tax payment, TDS & TCS for the PY till the date of making of application.
However, the above details cannot be read to say that a Certificate will be issued only when returns for the 4 PYs are filed or tax must be paid for PY inasmuch as provisions of Rule 28AA(1) and 2(i) & 2(ii) contemplate estimated liability & estimated income. Tushar Hemani, Senior Advocate 67<br>
slide68. If the contention that only if returns are filed for 4 PYs, or the payment of tax, is accepted as a condition for entertaining an application u/s. 197(1), it would result into permitting classification & rendering redundant the concept of estimated liability & estimated income that are built into Rule 28AA.
Further, on an application u/s. 197(1), AO has to record his satisfaction only upon the examination of circumstances mentioned in Rule 28AA. The liability of another entity (here M/s. Bitcipher), even if it is the sister concern, would be extraneous.
The order was quashed and the matter was sent to AO for reconsideration. Tushar Hemani, Senior Advocate 68<br>
slide69. Settlement Commission
Few issues Tushar Hemani, Senior Advocate 69<br>
slide70. Kotak Mahindra Bank Ltd. v. CIT [2023] 458 ITR 113 (SC) Facts:
During assessment proceedings for assessment year 1997-98, the AO observed that the assessee was accounting for lease rentals by treating same as financial transaction and lease rental was bifurcated into capital repayment portion and interest component. Only interest was offered for tax. Accordingly, the AO opined that since assessee treated such leases as loans granted to the lessees to purchase the assets, the ownership of the assets was vested with the lessees. He, thus, issued reopening notice for AYs 1994-1995 to 1996-1997 on ground that assessee claimed depreciation on said assets even though it was not owner of the assets. AO also levied penalty u/s 271(1)(c).
The assessee approached Settlement Commission to settle its tax liabilities under section 245C. Tushar Hemani, Senior Advocate 70<br>
slide71. The revenue raised preliminary objection contending that assessee had not made a full and true disclosure of its income which had not been disclosed before the AO. Disallowance of depreciation was already discovered by the AO. There is no new or additional income being offered by the assessee.
The Settlement Commission found the application maintainable and passed order determining additional income and also annulled the penalty levied by the AO on ground that the non-disclosure of lease rentals was on account of RBI guideline and the assessee subsequently disclosed said rentals before Settlement Commission when the assessee realised the omission to disclose the same as per income-tax law.
Revenue challenged the order of Settlement Commission, wherein the Single Judge did not find the reasoning of the Settlement Commission convincing and held the Order granting immunity from penalty and prosecution to be an illegal order. Matter was remanded to Settlement Commission for the limited purpose of reconsidering the question of immunity from levy of penalty and prosecution.
DB confirmed the order of Single Judge. Tushar Hemani, Senior Advocate 71<br>
slide72. Held:
Settlement Commission was right in granting immunity. The necessary ingredients for granting immunity from prosecution would be: (a) the assessee should have co-operated with the Settlement Commission in the proceedings before it; and (b) the assessee should have made a full and true disclosure of its income and the manner in which such income has been derived, to the satisfaction of the Commission.
According to the revenue, in the present case, what had been "disclosed" in the application was the same as what was "discovered" by the Assessing Officer and therefore, the application of the assessee ought not to have been entertained by the Commission, and further, immunity under section 245H ought not to have been granted.
Even if the pre-conditions prescribed under section 245C are to be read into section 245H, it cannot be said that in every case, the material "disclosed" by the assessee before the Commission must be something apart from what was discovered by the Assessing Officer. What is of relevance is that the assessee offered to tax, income, in addition to the income recorded in the return of income. Tushar Hemani, Senior Advocate 72<br>
slide73. Section 245C read with section 245H only contemplates full and true disclosure of income to be made before the Settlement Commission, regardless of the disclosures or discoveries made before/by the Assessing Officer. Disclosure may also include the income discovered by the Assessing Officer.
Powers vested with the Settlement Commission u/s 245H is a discretionary power to be exercised if the Settlement Commission is satisfied that an assessee has complied with the preconditions specified therein. It is trite that any judicial, quasi-judicial or administrative authority must while exercising discretion, direct itself properly in law and consider all the facts and material that it is bound to consider while excluding from consideration irrelevant aspects of the matter. Tushar Hemani, Senior Advocate 73<br>
slide74. Jain Metal Rolling Mills & others vs. UOI & others W.P. No. 13455 of 2021 Facts:
Finance Act, 2021 has abolished the Income Tax Settlement Commission (ITSC) by making certain amendments in Section 245-A. However, such abolition was made w.e.f. 01.02.2021 i.e. the date on which Finance Bill, 2021 was introduced in the Parliament instead of 01.04.2021 when the Finance Act, 2021 came into force.
An Interim Board was constituted for disposal of pending applications with ITSC, however only the applications pending on 01.02.2021 were considered and the applications to ITSC during 01.02.2021 to 31.03.2021 were rejected on account of abolition of ITSC w.e.f. 01.02.2021.
Hence, writ petitions were filed challenging the constitutional validity of this retrospective amendment. Tushar Hemani, Senior Advocate 74<br>
slide75. Held:
The basic ground of attack on the constitutionality of the impugned enactment is that it is retrospective in nature and that it takes away the vested rights of the petitioners. In this regard, the contention on behalf of the State is that the settlement itself is concession and therefore, the writ petitioners cannot claim any vested right. We are unable to countenance the said argument on behalf of the State. It may be true that the orders passed by ITSC containing terms of settlement has the trappings of concession and benevolence showered by the State to a particular assessee. But, such benevolence, concession etc., are exercised by the State through a statutory regime. Tushar Hemani, Senior Advocate 75<br>
slide76. The State had every right to abolish the ITSC. While being so, in appropriate cases, the right to enact a law with retrospective operation is also well recognized. In the instant case, on a perusal of the impugned legislation, it was given retrospective effect with effect from 01.02.2021 on the premise that it is on the said date, that the Bill was introduced by the Parliament, by which, all the assessees and the general public concerned are made to know about the policy decision in the making by which the State proposed to make the ITSC inoperative. The act of the State in abolishing the ITSC with effect from a cut-off date per se cannot be illegal or ultra vires the Constitution. Tushar Hemani, Senior Advocate 76<br>
slide77. But, at the same time, the ITSC did exist legally and factually until 31.03.2021. Every eligible assessee had a right to approach the ITSC, if they had a ‘case’ pending against them. The definition of 'case' as per Section 245-A(eb) is also extracted above. Therefore, even if any proceeding for assessments/reopening is issued after 01.02.2021 upto 31.03.2021, the assessee had a ‘case’ to approach the Commission and if they had submitted an application and if no final order has been passed under Sub-Section 4 of 245(D) on or before 31.01.2021, then the said application is treated as a ‘pending application’. It can be seen that in respect of the case of the petitioners whose matters had arisen before the notification of the Act on 01.04.2021, but, after the cut-off date of 01.02.2021, were also very much eligible to approach the ITSC. Tushar Hemani, Senior Advocate 77<br>
slide78. Without amending the definition of case pending applications etc., Section 245C(5) simply provides that no application shall be made under the Section on or after the first day of February, 2021. The right to file application before ITSC is very much existent and has been exercised till 31.03.2021. The retrospective legislation by way of legal fiction attempts to make it as if it is unavailable.
As a matter of fact, the applications are either made by the petitioners or on direction by the orders of the Court as the ITSC was in the statute book in the interregnum period before the retrospective legislation came into force. Therefore, the retrospectivity also makes these directions of Court and the consequential applications being filed before the ITSC nugatory. Tushar Hemani, Senior Advocate 78<br>
slide79. Therefore, when we consider the instant case, the purpose of the retrospective legislation is to make the ITSC inoperative right from the date of the introduction of the Bill and to send all the pending applications to the Interim Board. Therefore, fixing the last date for filing the applications alone travels beyond the purpose and results in more retrospectivity than which is needed and thus, runs counter to the other parts of the Act. As a matter of fact, as per the principle of lex prospicit non respicit (law looks forward not back) it can be seen that the purport of the legislation is only to do away with the policy of resolution through ITSC. Tushar Hemani, Senior Advocate 79<br>
slide80. As a matter of fact, the Central Government has to make a Scheme for the purposes of Settlement in respect of pending applications by the Interim Board as per Section 245D(11) and such scheme had to be placed before the Parliament. Thus, neither there is any intent nor it is within the purpose to do away with the ‘pending applications’ in respect of matters in which the ‘cases’ arose from 01.02.2021 to 31.03.2021. Thus, we find that it is just and necessary to read down the last date mentioned for filing applications in Section 245C(5) as 31.03.2021 and consequently the last date mentioned in paragraph No.4(i) of the Circular should also read as 31.03.2021.
The decision was rendered in favour of assessee and accordingly, the writ petitions were partly allowed. Tushar Hemani, Senior Advocate 80<br>
slide81. Document
Identification
Number Tushar Hemani, Senior Advocate 81<br>
slide82. Sharda Devi Bajaj & Others vs. DCIT ITA No. 3006, 3008, 3009/Del/2022 Facts:
Assessment order was passed in the case of assessee which was also confirmed by CIT(A).
Assessee filed an appeal before ITAT where in addition to challenging on merits, assessee raised an additional ground stating that assessment order does not contain DIN (Document Identification Number).
Held:
Hon’ble ITAT held that the additional ground pertains to a question of law which is based on material already on record and hence, it deserves to be admitted. Tushar Hemani, Senior Advocate 82<br>
slide83. Reliance was made to decision of Hon’ble Supreme Court in NTPC vs. CIT (1998) 229 ITR 383 (SC) wherein it was held that the view that the Tribunal is confined only to issues arising out of the appeal before the CIT(A) is too narrow a view of the powers of the Appellate Tribunal. It has been held that Tribunal will have a discretion to allow or not to allow new ground to be raised. However, where the Tribunal is only required to consider a question of law arising from the facts which are on record, in the assessment proceedings, there is no reason, why such a question should not be allowed to be raised. Tushar Hemani, Senior Advocate 83<br>
slide84. On merits, it was held that the CBDT Circular No. 19/2019 dated 14.8.2019 has mandated, Generation/ Allotment/ Quoting of computer generated Document Identification Number (DIN) in the body of all communications, in the nature of notices/summons/ letters/ correspondences as well as the orders passed.
Para 3 of the Circular sets out, exceptional circumstances, in which such communications may be issued manually, with the rider that this shall be done only after recording reasons in writing in the file and with the prior written approval of the Chief Commissioner/Director of Income Tax. Tushar Hemani, Senior Advocate 84<br>
slide85. Para 4 of the Circular provides that any communication which is not in conformity with the requirement of Para 2 and Para 3 shall be treated as invalid and shall be deemed to have never been issued.
In the present case, it is not in dispute and otherwise, it is a matter of record that the order of the Assessing Officer does not bear any DIN.
On behalf of the Revenue reliance is placed on the communication dated 17.9.2019 which pertains to the roll out of facility for System generated Document (i.e. Intimation Letter) containing Document Identification number (DIN) for documents issued outside the system but uploaded manually in Income Tax Business Application (ITBA). Tushar Hemani, Senior Advocate 85<br>
slide86. From para 4 of the communication dated 17.09.2019, it is clear that it pertains to the functionality to capture and uphold the letters, notices and orders issued manually and served on taxpayers by users due to any exceptional circumstances under Para 3 (i), (ii) and (iii) of the aforesaid Circular dated 14.8.2019. It is not the case made out that there are any exceptional reasons recorded in these appeals as required by the Circular dated 14.8.2019. Thus, in our opinion, the said communication cannot come to the aid of the Revenue in the present Appeals.
Hence, the additional ground as raised has to succeed. Tushar Hemani, Senior Advocate 86<br>
slide87. Gupta Domestic Fuels (Nagpur) Ltd.& Others vs. ACIT ITA No. 61/NAG/2022 & others Facts:
Assessment orders and appellate orders were issued without quoting computer-generated DIN (Document Identification Number) in the body of the orders.
DIN were intimated to assessees by separate letters.
Held:
On appeal to ITAT, it was held that circular No. 19/2019 dt. 14/08/2019 mandated the income tax authorities w.e.f. 01/10/2019 for generation, allotment and communication of computer generated DIN in relation to any assessment, appeals, orders, statutory or otherwise, exemptions, enquiry, investigation, verification of information, penalty, prosecution, rectification, approval etc. Tushar Hemani, Senior Advocate 87<br>
slide88. Intimation of DIN by separate letters communicated within 15 days of issuance of former DIN less communication would be valid only if, former DIN less communication is issued incorporating therein the reason for issue of such DIN less communication in terms of para 3(i) to 3(v) [as applicable] along with the Number & date of obtaining written approval of the Chief Commissioner / Director General of Income-Tax in a specified format, and not otherwise.
The decision was held in favour of assessees rendering the impugned orders invalid as if they have never been issued. Tushar Hemani, Senior Advocate 88<br>
slide89. 153A & 153C Tushar Hemani, Senior Advocate 89<br>
slide90. PCIT vs. Abhisar Buildwell Pvt. Ltd. [2023] 454 ITR 212 (SC) Facts:
The core issue involved in the instant appeal filed by revenue was the scope of assessment under section 153A. According to the revenue, the Assessing Officer was competent to consider all the material that was available on record including that found during the search, and make an assessment of 'total income'.
However, according to the assessee if no assessment proceeding was pending on the date of initiation of the search, the Assessing Officer might consider only the incriminating material found during the search and was precluded from considering any other material derived from any other source. Tushar Hemani, Senior Advocate 90<br>
slide91. Held:
The observations of Hon’ble Supreme Court are as under:
That in case of search under section 132 or requisition under section 132A, the AO assumes the jurisdiction for block assessment under section 153A;
All pending assessments/reassessments shall stand abated;
In case any incriminating material is found/unearthed, even, in case of unabated/completed assessments, the AO would assume the jurisdiction to assess or reassess the 'total income' taking into consideration the incriminating material unearthed during the search and the other material available with the AO including the income declared in the returns; and Tushar Hemani, Senior Advocate 91<br>
slide92. In case no incriminating material is unearthed during the search, the AO cannot assess or reassess taking into consideration the other material in respect of completed assessments/unabated assessments. Meaning thereby, in respect of completed/unabated assessments, no addition can be made by the AO in absence of any incriminating material found during the course of search under section 132 or requisition under section 132A of the Act, 1961. However, the completed/unabated assessments can be re-opened by the AO in exercise of powers under sections 147/148 of the Act, subject to fulfilment of the conditions as envisaged/mentioned under sections 147/148 of the Act and those powers are saved. Tushar Hemani, Senior Advocate 92<br>
slide93. CIT vs. Jasjit Singh [2023] 458 ITR 437 (SC) Facts:
Search was conducted on a third party on 19.02.2009 where documents belonging to assessee were found.
The assessment of assessee was centralized on 16.06.2009. Assessment of AY 2009-10 was completed u/s. 143(3) treating the AY 2009-10 as year of search & assessments of AY 2003-04 to 2008-09 were reopened u/s. 153C.
Assessee contended that as per first proviso to Section 153C, the year in which documents belonging to him were transferred to his jurisdictional AO shall be considered as year of search i.e. AY 2010-11 when his case was centralized on 16.06.2009 & not AY 2009-10. Tushar Hemani, Senior Advocate 93<br>
slide94. Assessee submitted that the assessment of AY 2009-10 framed u/s. 143(3) without issuing notice u/s. 153C and recording satisfaction is null and void.
CIT(A) has confirmed the validity of assessment order u/s. 143(3) for AY 2009-10.
On appeal, ITAT held in favour of assessee.
On further appeal, the High Court upheld the order of ITAT.
Held:
On appeal, the Hon’ble Supreme Court dismissed the appeal and held that the submission of revenue that the first proviso to Section 153C is confined only to question of abatement is unsubstantial and without merit. Tushar Hemani, Senior Advocate 94<br>
slide95. It is evident on a plain interpretation of section 153C(1) that the Parliamentary intent to enact the proviso was to cater not merely to the question of abatement but also with regard to the date from which the six year period was to be reckoned, in respect of which the returns were to be filed by the third party, whose premises are not searched and in respect of whom the specific provision u/s. 153-C was enacted.
If the date would virtually relate back to the date of seizure as contended by revenue, it would cause prejudice to third party who is not searched. For instance, if the papers are assigned u/s. 153C after 4 years, the third party assessee has to preserve records for at least 10 years which is not the requirement in law. Accordingly, the revenue’s appeals were dismissed. Tushar Hemani, Senior Advocate 95<br>
slide96. Tax Appeals Tushar Hemani, Senior Advocate 96<br>
slide97. Bikram Singh vs. PCIT [2023] 154 taxmann.com 80 (SC) Facts:
During assessment proceedings, AO made addition under section 68 in respect of loans/advances received from eight persons, on ground that assessee was unable to establish identity, creditworthiness and genuineness of said persons and transactions.
Tribunal set aside additions in respect of four creditors.
High Court restored the matter to AO holding that mere establishing of their identity and fact that amounts had been transferred through cheque payments, did not by itself mean that transactions were genuine. Tushar Hemani, Senior Advocate 97<br>
slide98. Held:
On appeal to Hon’ble Supreme Court, it was observed that the High Court has not followed procedure under section 260A.
On a reading of the provision of section 260A, it is noted that an appeal before the High Court is maintainable only on a substantial question of law (not a question of fact or only a question of law). The High Court when entertaining such an appeal must formulate that question and admit the appeal, thereafter, on the question so formulated the respondent must also be heard and consequently the matter must be disposed of depending on whether the substantial question of law requires to be answered for Tushar Hemani, Senior Advocate 98<br>
slide99. or against either of the parties or no such question of law would arise. The High Court has also the power to formulate a fresh question of law if it so arises on hearing the respective parties in the event, such a substantial question of law would arise and if the High Court is satisfied the said case involves such a question.
Further, sub-section (7) of section 260A states that 'save as otherwise provided in this Act, the provisions of the Code of Civil Procedure, 1908 (5 of 1908), relating to appeals to the High Court shall, as far as may be, apply in the case of appeals under this section’. Since the appeal filed under section 260A is akin to a Second Appeal, section 100 read with Order XLII rule 1 of Code Tushar Hemani, Senior Advocate 99<br>
slide100. of Civil Procedure would apply, wherein, in a Regular Second Appeal under the said provision read with section 100 of the said Code, the formulation of a substantial question of law when the matter is entertained and admitted would be required, otherwise the High Court has the power to dismiss such a Second Appeal on the ground that no such substantial question of law arises in the appeal.
In the present case, it is found that the High Court did not formulate any substantial question of law at the time of admitting the appeal, rather the appeal was heard on merits and in the absence of formulating the substantial question of law the appeal was reserved for judgment. Tushar Hemani, Senior Advocate 100<br>
slide101. During the course of preparation of the judgment, the question of law was framed stated to be a 'question of law' and the matter was then admitted and at the same time considered on merits. Issuance of notice prior to admission without framing any substantial question(s) of law is not contemplated under section 260A. The High Court has either to admit or not admit the appeal. If the High Court admits the appeal then substantial question(s) of law has to be framed and the respondent put on notice on such substantial question(s) of law. On the contrary, if the High Court is of the view that no substantial question of law arises, then the appeal has to be dismissed. Tushar Hemani, Senior Advocate 101<br>
slide102. It is found that the procedure adopted by the High Court in the instant case is not in consonance with what is contemplated under section 260A and hence, on that short ground alone the impugned judgment is set aside. The matter is remanded to the High Court for re consideration of the appeal filed by the respondent-revenue having regard to the essentials of section 260A and in accordance with law. Tushar Hemani, Senior Advocate 102<br>
slide103. PCIT vs. KGY Glass Industries P. Ltd. R/Tax Appeal No. 722 of 2023 Facts:
Assessee company opted to be taxed as per provisions of Section 115BAA while filing return of income.
Return was processed by CPC u/s 143(1) on 20/12/2021 and income was taxed as per Section 115JB & not as per concessional rate u/s. 115BAA because assessee has not filed Form 10-IC on or before due date of filing return of income.
Form 10-IC could not be uploaded by the assessee before due dated of return of income due to some technical error. The time limit for filing Form 10-IC was extended to 30.06.2022 and assessee physically filed such form before AO on 29.06.2022.
Appeal was filed before CIT(A) which came to be dismissed holding that filing of Form 10-IC before due date of return of income is a mandatory requirement as per Section 115BAA(5) r.w. Rule 21AE. Tushar Hemani, Senior Advocate 103<br>
slide104. Further appeal was filed before Hon’ble ITAT which was allowed in favour of assessee.
Held:
On Revenue’s appeal, the Hon’ble High Court observed that during the relevant period, due date of filing Form 10-IC was extended to 30.06.2022. The assessee physically filed such Form before AO on 29.06.2022. Copy of such form was also placed before ITAT.
Since assessee could not upload Form 10-IC on account of technical error, there being no fault of assessee, it could not be deprived of benefit particularly when this being first year for availing such benefits.
Accordingly issue was decided in favour of assessee and revenue’s appeal was dismissed. Tushar Hemani, Senior Advocate 104<br>
slide105. PCIT vs. Jigar Jashwantlal Shah R/Tax Appeal No. 80 & 96 of 2023 Facts:
Assessee is a director in a company. Such company issued right shares at Rs. 10 per share.
Assessee was allotted 1,03,000 right shares of such company in proportion to his existing shareholding.
Assessee was allotted additional 82,200 right shares due to renunciation of rights by his wife & father.
Assessee was allotted additional 14,800 right shares due to renunciation of rights by a third party.
AO invoked Section 56(2)(vii)(c), computed FMV of right shares at Rs. 255 per share & made the addition of the differential amount. Tushar Hemani, Senior Advocate 105<br>
slide106. CIT(A) partly allowed the appeal to the extent of 1,03,000 right shares allotted proportionate to existing shareholding of the assessee.
ITAT allowed the appeal to the extent of 1,85,200 right shares [1,03,000 as allowed by CIT(A) + 82,200 being right shares allotted pursuant to renunciation of rights by the assessee’s wife and father in addition to what has been allowed by CIT(A)].
Revenue filed an appeal before the Hon’ble Gujarat High Court against the order of ITAT. Tushar Hemani, Senior Advocate 106<br>
slide107. Held:
On appeal, Gujarat High Court observed that on conjoint reading of provision as well as explanatory note of the said provision, it is clear that only when an individual or a HUF receives any property for consideration which is less than the FMV, the provisions of Sec.56(2)(vii)(c) would be attracted.
In the facts of the case, the shares had come into existence only when the allotment is made by the company as right shares cannot be said to be “received from any person”. In other words, the property must pre-exist for application of Sec.56(2)(vii)(c), which is clear from the intention of the legislature. Tushar Hemani, Senior Advocate 107<br>
slide108. If the shares are allotted strictly on proportionate basis based on existing shareholding, then though the provisions per se are applicable, but will not operate adversely because the gain accruing on allotment of fresh shares will be offset by the loss in value of existing shares.
The Tribunal, therefore held that the provisions of sec.56(2)(vii)(c) would not apply in respect of allocation of 1,03,000 right shares allotted to the assessee proportionate to its share holding in the company. Tushar Hemani, Senior Advocate 108<br>
slide109. Further, it is a settled principle of law that what cannot be done directly cannot be done indirectly as well. The Tribunal, therefore, held that had the wife and father of the assessee directly transferred their shares in favour of the assessee, provisions of Sec.56(2)(vii)(c) of the Act could not have been invoked since both of them are falling in the definition of “relatives” which are excluded from within the purview of operation of Sec.56(2)(vii)(c) of the Act. As a consequence it was held that the renunciation of right shares by wife and father of the assessee by not exercising the right to subscribe would not attract the provisions of Sec.56(2)(vii)(c) of the Act. Tushar Hemani, Senior Advocate 109<br>
slide110. With regard to the application of Sec.56(2)(vii)(c) of the Act for the balance 14,800 shares allotted to the assessee as a result of third pary share-holder declining to apply for right shares in favour of the assessee, the Tribunal held against the assessee because renunciation of rights in favour of the assessee by third party who are not related does lead to disproportionate allocation of shares in favour of the assessee.
Hence, the appeals of the Revenue were dismissed. Tushar Hemani, Senior Advocate 110<br>
slide111. PCIT vs. Weilburger Coatings (India) Pvt. Ltd. IA NO: GA/1/2023, GA/2/2023 – Calcutta HC Facts:
Assessee’s case was selected for limited scrutiny & certain additions were made by AO which were confirmed by CIT(A).
Assessee raised an additional ground before ITAT contending that AO has no jurisdiction to make additions on the issues beyond limited scrutiny.
ITAT agreed to the contention of the assessee and allowed the assessee’s appeal holding that AO has exceeded his jurisdiction. Tushar Hemani, Senior Advocate 111<br>
slide112. Held:
On further appeal, Hon’ble Calcutta High Court held that ITAT has rightly allowed the appeal of the assessee.
Reliance was placed on the decision of PCIT vs. Sukhdham Infrastructures LLP – ITAT No. 164 of 2023 dated 14.08.2023, where an identical contention was raised stating that at best the action of AO could be construed as an irregularity. Such contention was rejected by the Court with the following observations:
“While considering the said issue, the Hon’ble Supreme Court noted the distinction between the statutes affecting rights and those affecting mere procedure. The revenue Tushar Hemani, Senior Advocate 112<br>
slide113. cannot rely upon the said decision as the scheme of assessment as provided under Section 143 of the Act is a complete code by itself and the circumstances under which the power under sub-section (2) of Section 143 could be invoked has been clearly spelt out and on a reading of sub-section (3) of Section 143, it s evidently clear that on the day specified in the notice issued under sub-section (2), or as soon afterwards as may be, after hearing such evidence as the assessee may produce and such other evidence as the Assessing Officer may require on specified points, and after taking into account all relevant material which he has gathered, the Assessing Officer shall, by an order in writing, make an assessment of the total income or loss of the assessee, and determine the sum payable by him or refund of any amount due to him on the basis of such assessment. Tushar Hemani, Senior Advocate 113<br>
slide114. Therefore, the question of part of the provision being procedural is an incorrect interpretation of the scheme provided under Section 143 of the Act. Further, as noted above, the CIT(A) has examined the merits of the matter and after taking note of the facts granted relief to the assessee to the extent indicated therein. Thus, for the above reasons, we find that the revenue has not made out any case for interference of the order passed by the Tribunal. Accordingly, the appeal fails and is dismissed.
The substantial questions of law are answered against the revenue.
The application for stay being GA 1 of 2023 is also dismissed.” Tushar Hemani, Senior Advocate 114<br>
slide115. Mutuality Tushar Hemani, Senior Advocate 115<br>
slide116. Secundrabad Club etc. vs. CIT [2023] 457 ITR 263 (SC) Facts:
The assessee-clubs deposited surplus funds by way of bank deposits in various bank and claimed interest earned on said deposits was exempt on the principle of mutuality.
On appeal, the various High Courts held that the interest earned on the bank deposits made by the assessee-clubs was liable to be taxed in the hands of the clubs and the principle of mutuality would not apply. Tushar Hemani, Senior Advocate 116<br>
slide117. Held:
On further appeal, the Hon’ble Supreme Court held that the triple test for applying principle of mutuality was discussed in the case of Bangalore Club vs. CIT [350 ITR 509 (SC)]. The triple test is as under:
Complete identity between contributors & participators
Action of participators & contributors must be in furtherance of the mandate of associations or Clubs.
There must be no scope for profiteering by the contributors from a fund made by them which could only be expended or returned to themselves. Tushar Hemani, Senior Advocate 117<br>
slide118. That, it is not a normal activity of the assessee clubs to deposit funds in a bank. It is only when a surplus is generated. In the absence of the said fixed deposits being utilized by the banks for their transactions with their customers, no interest can be payable on the fixed deposits. This is so in respect of any customer of a bank who would deposit surplus funds in a bank. It may be that the interest income would be ultimately used for the benefit of the members of the clubs but that is not a consideration which would have an impact on satisfying the triple test of mutuality. Tushar Hemani, Senior Advocate 118<br>
slide119. It was observed in Bangalore Club (supra) that even if ultimately the interest income and surplus funds in the
fixed deposit are utilized for the benefit of the members of the clubs, the fact remains that when the fixed deposits were made by the clubs in the banks, they were exposed to transactions with third parties, i.e., between the banks and its customers and this would snap the principle of mutuality breaching the triple test.
The question asked therefore is - at what point does the relationship of mutuality end and that of trading begin. If there is an entry of a third party or non-member to deal with the contributions of or funds of the club or to Tushar Hemani, Senior Advocate 119<br>
slide120. utilize the funds of the club and return the same with interest, then, the relationship of the parties is not on the basis of a privity of mutuality. The essential condition of mutuality, i.e., identity between the contributors and participators would end. The relationship would then be like any other commercial relationship such as that between a customer and a bank where the fixed deposit is made by the customer for the purpose of earning an interest income.
Thus, the interest income earned on fixed deposits made in the banks by the appellant Clubs has to be treated like any other income from other sources within the meaning of section 2(24).
Consequently, the appeals were dismissed. Tushar Hemani, Senior Advocate 120<br>
slide121. Prosecution Tushar Hemani, Senior Advocate 121<br>
slide122. Tirumala Tirupati Constructions P. Ltd. vs. ADIT Criminal Petition No. 2684 of 2022 Facts:
Assessee has sold land in AY 2015-16 & 2016-17 at the rates below Sub-Registrar office. Assessee has not filed returns of income for such AYs & not paid any tax.
Sanction u/s. 279(1) was issued by PDIT(Inv.), Hyderabad to DDIT(Inv.) for prosecuting the assessee for offences punishable u/s. 276(1) & 278B.
Pursuant to such sanction, ADIT(Inv.) filed a criminal complaint to Special Court of Economic Offences, Hyderabad.
Assessee has challenged the said criminal complaint contending that initiation of prosecution is illegal & void-ab-initio. Tushar Hemani, Senior Advocate 122<br>
slide123. Held:
As per Section 279(1), sanction has to be accorded by an officer at the level of CCIT/DGIT. However, in the present case, sanction has been accorded by PDIT, who is lower in rank than CCIT.
Further, sanction was accorded to DDIT but complaint was filed by ADIT, who is lower in rank than DDIT.
It is evident that if a statutory authority has been vested with jurisdiction, he has to exercise it accordingly and if discretion is exercised under the directions or in compliance of some higher authority’s instruction, then it would be a case of failure to exercise discretion altogether. Tushar Hemani, Senior Advocate 123<br>
slide124. The authority which has initiated the prosecution must have sanction of law. Otherwise, it amounts to illegal action.
If a statute has conferred a power to act and has laid down the method, any power must be exercised discreetly, which prohibits doing of act in any another manner. Which means, if a sanction has been granted to the Deputy director to launch prosecution against the petitioner company, it is for the Deputy Director alone to launch the prosecution but not the Assistant Director.
Even though DDIT is a senior officer & ADIT is a junior officer and both were doing the same duties, the said contention cannot be taken into consideration as in the present case, the sanction is accorded to the DDIT for initiating prosecution and not to ADIT. Hence, the proceedings were quashed. Tushar Hemani, Senior Advocate 124<br>
slide125. Scope of S. 254(2) Tushar Hemani, Senior Advocate 125<br>
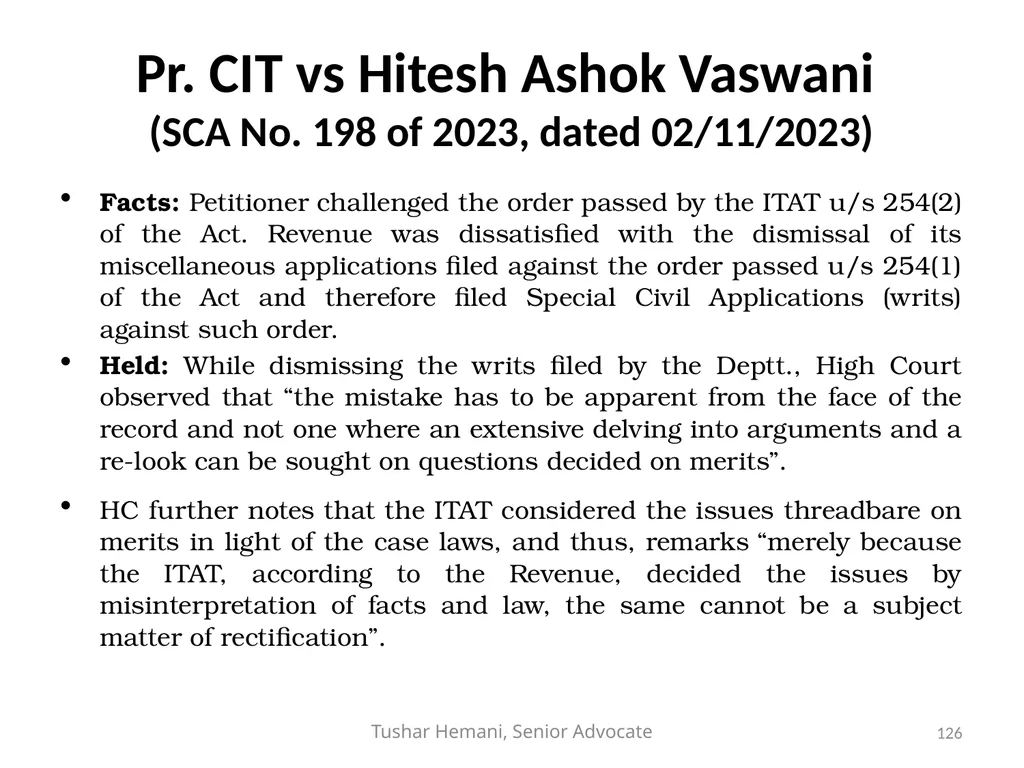
slide126. Pr. CIT vs Hitesh Ashok Vaswani (SCA No. 198 of 2023, dated 02/11/2023) Facts: Petitioner challenged the order passed by the ITAT u/s 254(2) of the Act. Revenue was dissatisfied with the dismissal of its miscellaneous applications filed against the order passed u/s 254(1) of the Act and therefore filed Special Civil Applications (writs) against such order.
Held: While dismissing the writs filed by the Deptt., High Court observed that “the mistake has to be apparent from the face of the record and not one where an extensive delving into arguments and a re-look can be sought on questions decided on merits”.
HC further notes that the ITAT considered the issues threadbare on merits in light of the case laws, and thus, remarks “merely because the ITAT, according to the Revenue, decided the issues by misinterpretation of facts and law, the same cannot be a subject matter of rectification”. Tushar Hemani, Senior Advocate 126<br>
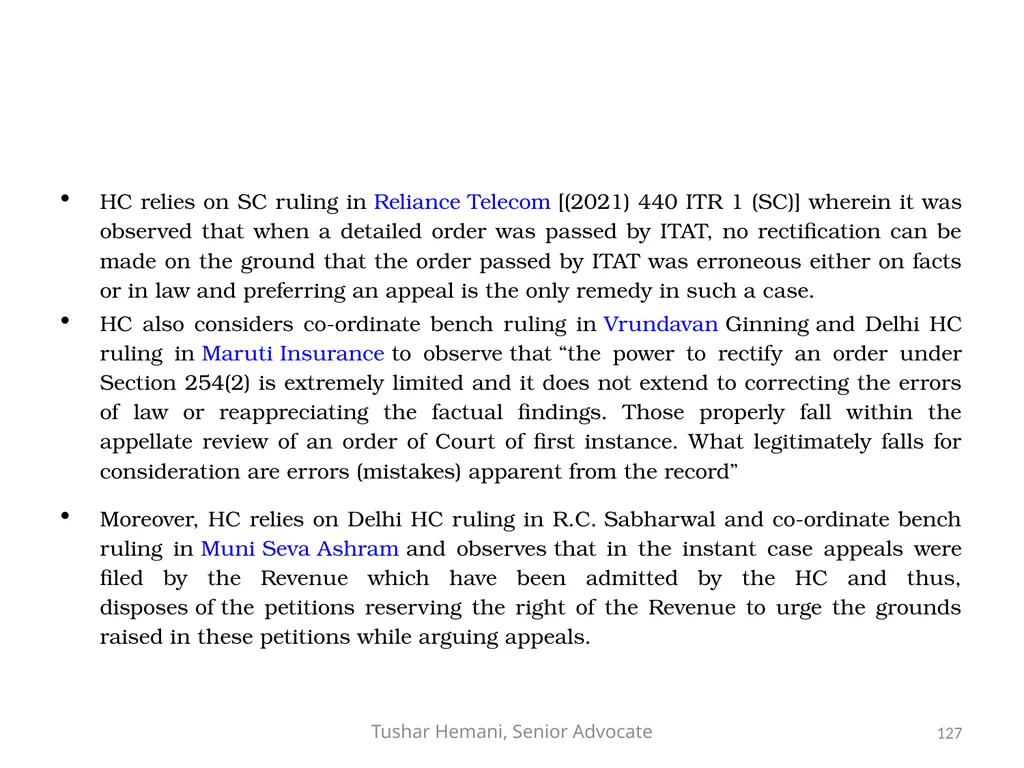
slide127. HC relies on SC ruling in Reliance Telecom [(2021) 440 ITR 1 (SC)] wherein it was observed that when a detailed order was passed by ITAT, no rectification can be made on the ground that the order passed by ITAT was erroneous either on facts or in law and preferring an appeal is the only remedy in such a case.
HC also considers co-ordinate bench ruling in Vrundavan Ginning and Delhi HC ruling in Maruti Insurance to observe that “the power to rectify an order under Section 254(2) is extremely limited and it does not extend to correcting the errors of law or reappreciating the factual findings. Those properly fall within the appellate review of an order of Court of first instance. What legitimately falls for consideration are errors (mistakes) apparent from the record”
Moreover, HC relies on Delhi HC ruling in R.C. Sabharwal and co-ordinate bench ruling in Muni Seva Ashram and observes that in the instant case appeals were filed by the Revenue which have been admitted by the HC and thus, disposes of the petitions reserving the right of the Revenue to urge the grounds raised in these petitions while arguing appeals. Tushar Hemani, Senior Advocate 127<br>
slide128. Regarding the petitions where Revenue has not filed appeals, HC holds that once the ITAT had considered the issues on merits and undertaken a detailed discussion, no rectification could be made on the grounds stated in the MAs; HC anlayses the batch of petitions in under four categories including a category of cases covered by SC ruling in Vikram Bhatia which was delivered after the MA was dismissed by ITAT; Across the categories, HC observes that issue raised by Revenue in MAs requires long drawn argument which is not allowed under Section 254(2) and if the Revenue feels the order passed by the ITAT is erroneous on account of law or on fact, then the only remedy available is to challenge the order at higher forum.
While dismissing the writs, high court also observed that when ITAT dismissed the 254(2) applications, judgment in the case of ITO vs. Vikram Bhatia – (2023) 453 ITR 417 (SC) was not even delivered and therefore, the same cannot be pressed into service. Tushar Hemani, Senior Advocate 128<br>
slide129. Thank You Tushar Hemani, Senior Advocate 129<br>
Indore Branch of CIRC of ICAI
23rd December, 2023
Tushar P. Hemani
Senior Advocate Tushar Hemani, Senior Advocate 1<br>
slide2. Fake Invoice - IT Accommodation Billing
Fake Billing
Genuine transaction becomes billing transaction due to lack of proof or supplier related issues;
Supplier not traceable
Supplier never existed
Supplier is alleged to be bogus
Supplier is proved to be bogus
Supplier’s GST registration is cancelled prospectively or retrospectively Tushar Hemani, Advocate 2<br>
slide3. PO & Invoice [Invoice Reference Number (IRN)];
E-way bill;
Transport receipt, affidavit of driver;
Weight bridge slip;
Toll payment receipts;
RFID vehicle tracking details;
GSTR1 of Seller, GSTR2B of buyer, GSTR3B filed by both the parties;
Correspondence with supplier;
CCTV footage;
payment details and relevant bank statement;
Internal documents e.g. Inward register, quantity details etc. Tushar Hemani, Senior Advocate 3<br>
slide4. Quantify Details Even though the assessee was a scrap dealer, the addition u/s. 69C on account of bogus purchases was held not justified as assessee had maintained trading account with quantitative tally of purchases, opening stock, sales and closing stock and no discrepancy in such quantitative tally was found - Manoj Sharma v. ITO [2019] 103 taxmann.com 105 (Delhi - Trib.)
What if quantity details are not maintained; Tushar Hemani, Senior Advocate 4<br>
slide5. Burden of Proof Where assessee had submitted purchase bills, transportation bills, confirmed copy of account and VAT Registration of sellers as also their income-tax Return and payment was made through cheques, impugned purchases could not be disallowed - CIT v. Odeon Builders (P.) Ltd. 418 ITR 315 (SC).
Where assessee brought on record name and address of parties, their PAN, TDS deducted, date of bills, details of cheques issued, etc., to establish genuineness of purchase transactions, in such a case, he could not be held responsible for parties not appearing in person and, thus, addition so made under section 69C deserved to be deleted - Pr. CIT v. Chawla Interbild Construction Co. (P.) Ltd. 412 ITR 152 (Bom). Tushar Hemani, Senior Advocate 5<br>
slide6. Natural Justice Merely on suspicion bases on information received from sales Tax authority, assessing officer could not make addition on account of bogus purchases without carrying out independent enquiry and affording opportunity to Assessee to controvert statements made by seller - Pr. CIT v. Shapoorji Pallonji & Co. Ltd. [2022] 288 Taxman 661 (SC).
No addition can be made in respect of bogus purchases merely on the basis of material / information received from the Maharashtra Sales Tax Department without providing such material to the assessee or affording an opportunity to cross examine the concerned parties - Shailesh Keshavlal Shah vs. ITO – ITA 1877 to 1879/Ahd/2015. Tushar Hemani, Senior Advocate 6<br>
slide7. Sales – whether accepted? Bombay High Court in the case of Pr. CIT v. Nitin Ramdeoji Lohia [2022] 145 taxmann.com 546 held that Where AO made addition by disallowing expenses on purchases on ground that an information was received from sales tax department that assessee was beneficiary of accommodation entries on account of bogus purchases, in absence of AO not disputing corresponding sales transactions, purchases could not be treated as bogus and, thus, impugned addition made on account of bogus purchases to be deleted. Tushar Hemani, Senior Advocate 7<br>
slide8. Percentage disallowance CIT vs La Medica 250 ITR 575 (Del) – 100%
Sanjay Oil Cake Ind vs CIT 316 ITR 274 (Guj) – 25%
Pr. CIT v. Suraj Infrastructures (P.) Ltd [2023] 156 taxmann.com 192 (Bombay) – 12.5%
Pr. CIT v. Rakesh Kailashchand Jain [2023] 156 taxmann.com 82 (Gujarat) – 6%
CIT vs. Gujarat Ambuja Export Ltd. – [2014] 43 taxmann.com 244 (Gujarat) – 5% Tushar Hemani, Senior Advocate 8<br>
slide9. Other Approaches Dhondiram Naryan Limbhore vs Pr.CIT 153 taxmann.com 539 (Bom) addition was to be limited to extent of bringing GP rate on tainted purchases at same rate as applied in other genuine purchases.
Nehal Hsamukhari Gandhi vs. DCIT – ITA 2578/Ahd/2017 - NP Tushar Hemani, Senior Advocate 9<br>
slide10. Other Issues Distinction between a trader, manufacturer and/or consumer.
Rejection of books of accounts 145(3);
GP/NP comparison (history & Industry average);
Disallowance u/s 69C – justified? (expenditure incurred and Assessee offers no explanation)
Impact of S. 40A(3) [Hynoup - 290 ITR 702 (Guj)];
GP addition vs addition as percentage of bogus purchases Tushar Hemani, Senior Advocate 10<br>
slide11. Curious case of N K Ind Ltd [2016] 72 taxmann.com 289 (Gujarat) Whether 25% or 100% disallowance is confirmed by HC
Before Guj High Court, both Revenue and Assessee were in appeal.
Assessee was in appeal against confirmation of disallowance @ 25% out of purchases whereas Revenue was in appeal against deletion of 75% out of purchases by the ITAT.
Hon’ble High Court while dismissing both the appeals, gave the following finding: Tushar Hemani, Senior Advocate 11<br>
slide12. “6. The Tribunal in the case of Vijay Proteins Ltd. (supra) has observed that it would be just and proper to direct the Assessing Officer to restrict the addition in respect of the undisclosed income relating to the purchases to 25% of the total purchases. The said decision was confirmed by this Court as well. On consideration of the matter, we find that the facts of the present case are identical to those of M/s. Indian Woollen Carpet Factory (supra) or Vijay Proteins Ltd. (supra) In the present case the Tribunal has categorically observed that the assessee had shown bogus purchases amounting to Rs. 2,92,93,288/- and taxing only 25% of these bogus claim goes against the principles of Sections 68 and 69C of the Income Tax Act. The entire purchases shown on the basis of fictitious invoices have been debited in the trading account since the transaction has been found to be bogus. The Tribunal having once come to a categorical finding that the amount of Rs. 2,92,93,288/- represented alleged purchases from bogus suppliers it was not incumbent on it to restrict the disallowance to only Rs. 73,23,322/-.”
xxx…
9. In view of the above, the impugned judgment and order passed by the Tribunal is modified accordingly. Hence, the present Tax Appeals are dismissed.” Tushar Hemani, Senior Advocate 12<br>
slide13. Assessee preferred SLP against confirmation of 25% which got dismissed. [2017] 84 taxmann.com 195 (SC)
Subsequently, Gujarat High Court itself distinguished judgement in the case of N K Ind. Ltd. In the following cases:
[2019] 106 taxmann.com 316 (Gujarat) Pr. CIT v. Synbiotics Ltd.
[2023] 148 taxmann.com 154 (Gujarat) Pr. CIT v. Surya Impex Tushar Hemani, Senior Advocate 13<br>
slide14. Bogus Billing – GST Tushar Hemani, Senior Advocate 14<br>
slide15. Evidences to prove genuineness of the transaction State of Karnataka vs Ecom Gill Coffee Trading Pvt. Ltd. (2023) 4 Centax 223 (S.C.): “In view of the above and for the reasons stated above and in absence of any further cogent material like furnishing the name and address of the selling dealer, details of the vehicle which has delivered the goods, payment of freight charges, acknowledgement of taking delivery of goods, tax invoices and payment particulars etc. and the actual physical movement of the goods by producing the cogent materials”. Tushar Hemani, Senior Advocate 15<br>
slide16. Evidences GSTR1 of Seller, GSTR2B of buyer, GSTR3B filed by both the parties.
PO & Invoice [Invoice Reference Number (IRN)];
E-way bill;
Transport receipt, affidavit of driver, Weight bridge slip, Toll payment receipts;
RFID/GPS vehicle tracking details, CCTV footage;
payment details and relevant bank statement;
Internal documents e.g. Inward register, quantity details etc.
Correspondence with supplier; Tushar Hemani, Senior Advocate 16<br>
slide17. Scheme of the GST Act GST – tax on supplies of goods or services.
Tax only on value addition – to the extent goods or supplies suffered tax earlier, available in the form of ITC.
Identity of goods or supplies that has suffered tax.
S. 16 - Eligibility and condition for taking ITC - Registered person can claim ITC if he is in possession of tax invoice/debit note etc issued by supplier of goods or services. So ITC can only flow from supplier.
No claim of ITC allowed if tax not paid by supplier into Govt treasure – S. 16(2)(c)
S. 155 - Burden of proof for entitlement of ITC is on the claimant. Tushar Hemani, Senior Advocate 17<br>
slide18. Issues GST investigations reveal that
Supplier not traceable;
Supplier never existed at the billing address;
Supplier is alleged to be bogus as it has no place of business/godown or supplies or has not filied required returns;
Supplier is proved to be bogus as he has confessed during investigation to that effect by giving statement/affidavit.
Supplier’s GST registration is cancelled prospectively or retrospectively;
Supplier’s supplier has any of the above stated issues. Tushar Hemani, Senior Advocate 18<br>
slide19. Consequences Proceedings u/s 73;
Proceedings u/s 74;
Summons u/s 70;
Bank attachment u/s 83;
Arrest u/s 69 rw S. 132. Tushar Hemani, Senior Advocate 19<br>
slide20. S. 73 / S. 74 Insist for formal communication – Intimation (DRC-01A), SCN u/s 73-74 (DRC-01), so that appropriate reply can be filed and defenses can be raised.
No recovery is permissible w/o SCN and adjudication –(Gokak Patel Volkart Ltd. vs. Collector of Central Excise 1987 (28) ELT 53 (S.C.))
Payment under protest via letter is a valid mechanism when no mechanism is notified in the law - India Cements Ltd. vs CCE 1989 (41) E.L.T. 358 (S.C.) Tushar Hemani, Senior Advocate 20<br>
slide21. Scheme of availing the benefit of lower penalty u/s 74(5) of the CGST Act, 2017 is to be exercised at the complete discretion of the taxpayer as the same entails communication of the amounts paid as per the said scheme to the officer to seek conclusion of the proceedings. It cannot apply when the taxpayer intends to contest the matter [Shri Nandhi Dhall Mills India Pvt vs. Senior Senior Intelligence Officer W.P. No. 5192 of 2020) (Mad.)]
“27. Merely because an assesseehas, under the stress of investigation, signed a statement admitting tax liability and has also made a few payments as per the statement, cannot lead to self-assessment or self-ascertainment. The ascertainment contemplated under Section 74(5) is of the nature of self-assessment and amounts to a determination which is unconditional, and not one that is retracted as in the present case. Had such ascertainment/self-assessment had been made, there would be no further proceedings contemplated, as Section 74(6) states that with ascertainment of demand in Section 74(5), no proceedings for show cause under Section 74(1) shall be issued. In this case, enquiry and investigation are on-going, personal hearings have been afforded and both the parties are fully geared towards issuing/receiving a show cause notice and taking matters forward. Thus, the understanding and application of Section 74(5) in this case, is, in my view, wholly misconceived.” Tushar Hemani, Senior Advocate 21<br>
slide22. Only the first buyer needs to pay tax in a chain of transactions (Circular 171 dt. 06/07/2022).
Instruction No. 01/2022-23 dated 25.05.2022 – No collection or deposit of tax during the course of search, inspection or investigation. Unless deposited voluntarily. Tushar Hemani, Senior Advocate 22<br>
slide23. Summons, Bank Attachment & Arrest Summons - Instruction No. 03/2022-23 dated 17.08.2022 – Guidelines for issuance of summons – no summons for collecting statutory records, or to call MD, CFO unless necessary.
Bank attachment - Provisional attachment S. 83 –after initiation of proceedings under chapters XII, XIV, XV – Commissioner is of the opinion that in order to protect interest of the revenue – (Radha Krishan Industries v. State of Himachal Pradesh — 2021 (48) G.S.T.L. 113 (S.C.) Tushar Hemani, Senior Advocate 23<br>
slide24. Arrest and Bail - Instruction No. 02/2022-23 dated 17.08.2022 – Power to be exercised exceptionally. Arrest only when “the need to ensure proper investigation and prevent the possibility of tempering with evidence or intimidating or influencing witness exists.” No arrest in case of default of technical nature or when assessee co-operates. Tushar Hemani, Senior Advocate 24<br>
slide25. Technical Defenses Affidavit of the supplier – Examination in chief required by the Adjudicating Authority (G-Tech Industries Versus Union of India and Others 2016 (339) ELT 209 P&H) & Cross-examination to be demanded (Swadeshi Polytex Limited Versus Collector of Central Excise, Meerut 2000 (122) ELT 641 (SC))
ITC cannot be denied on account of misconduct at the end of the supplier’s supplier in the absence of any collusion (Balaji Exim vs. Commissioner, CGST [2023] 149 taxmann.com 44 (Delhi) Tushar Hemani, Senior Advocate 25<br>
slide26. Bogus Billing – GST vs IT During the course of an IT search, material is found indicating unaccounted turnover outside the books. IT department proposes to add the said turnover on the basis of the seized documents. Assessee wants to surrender only GP on this unaccounted turnover. However, Assessee is worried about GST consequences. Kindly advice. Tushar Hemani, Senior Advocate 26<br>
slide27. During the course of GST search, material is found indicating purchases from dealers whose registration were found to be cancelled ab-initio as they were found to be indulging into bogus billing without actual supply of material. Assessee is asked to reverse the ITC claimed from such supplier on the ground that the same is fake and fraudulent. Assessee wants to surrender such ITC and pay the necessary amount into the Govt. treasury. However, Assessee is worried about IT consequences. Kindly advice. Tushar Hemani, Senior Advocate 27<br>
slide28. In an income tax assessment, sales are treated as accommodation entries and addition to that effect is made u/s 68 of the IT Act. GST department on the strength of such AO, want to treat the said sales as billing transaction and deny ITC in the hands of the purchaser. Recovery notices for wrong claim of ITC is issued against the said purchaser. Kindly advice. (Circular No. 171/03/2022-GST dated 06/07/2022, Example 3) Tushar Hemani, Senior Advocate 28<br>
slide29. Interplay between
IBC & Income Tax Tushar Hemani, Senior Advocate 29<br>
slide30. Tata Steel Ltd. vs. DCIT W.P.(C) 13188/2018 Facts:
Assessment order for AY 2001-02 was passed on 28.02.2003. Addition was confirmed upto High Court. SLP has been accepted by Supreme Court & is pending for adjudication.
Assessment order vis-à-vis AY 2009-10, 2010-11 & 2013-14 was passed on 30.12.2016. CIT(A) dismissed the first appeal & also triggered penalty proceedings u/s. 271(1)(c). Second appeal with ITAT is pending.
Insolvency proceedings were triggered against the assessee. Petition was admitted by NCLT on 26.07.2017
Public announcement was published on 28.07.2017. Tushar Hemani, Senior Advocate 30<br>
slide31. Revenue lodged its claims to Interim Resolution Professional (IRP) on 28.09.2017, 24.10.2017 & 25.10.2017 for AY 2009-10, 2010-11 & 2013-14 but not for AY 2001-02.
Penalty order u/s. 271(1)(c) vis-à-vis AY 2009-10, 2010-11 & 2013-14 was passed on 23.04.2018.
Resolution Plan was admitted by NCLT on 15.05.2018.
Notice u/s. 221(1) was issued on 28.08.2018 requiring assessee to deposit tax for all 4 AYs & seeking response as to why penalty u/s. 221(1) shall not be levied.
Revenue lodged an updated claim with Resolution Professional (RP) on 20.09.2018 wherein the claim for the demand of tax for AY 2001-02 & penalties for all 4 assessment years were added. Tushar Hemani, Senior Advocate 31<br>
slide32. Objections were filed by assessee on 26.09.2018 against notice u/s. 221(1) dated 28.08.2018.
Order u/s. 221(1) was passed on 17.10.2018 rejecting the objections filed by the assessee.
Assessee filed a writ petition against notice u/s. 221(1) dated 17.10.2018 & order dated 17.10.2018.
Held:
In our opinion, the stand taken by the revenue that the demands for the AYs in issue were not outstanding at the time of the RP being accepted, if agreed with, would amount to splitting hairs. Tushar Hemani, Senior Advocate 32<br>
slide33. Therefore, the facts on record, in our opinion, not only disclose that the revenue had knowledge of the CIRP, but that it took steps to lodge its claims with regard to three out of the four AYs, on the footing that the amounts reflected in the assessment order were due and payable by BSL. Insofar as AY 2001-02 is concerned, the revenue did not lodge any claim before the RP was approved. The demand qua AY 2001-02 (along with the penalty imposed qua all four relevant AYs) was communicated as an additional claim on 20.09.2018, only after the RP was approved on 15.05.2018. In the ordinary course, the claim would get extinguished under the provisions of the 2016 Code, as the approved RP obviously made no reference to it. Tushar Hemani, Senior Advocate 33<br>
slide34. We are of the opinion that dues payable to creditors, including statutory creditors, for the periods which precede the date when the RP is approved, can only be paid as per the terms contained in the RP. In cases where no provision is made for claims lodged on behalf of the creditors, or there is failure to lodge a claim with the Resolution Professional, all such claims stand extinguished.
When one examines the provisions of Section 238 of the 2016 Code, the underlying purpose of the provision comes through. Section 238 clearly states without any ambiguity that the provisions of the 2016 Code “shall” have effect, notwithstanding anything inconsistent contained in any other law for the time being in force, or any instrument having effect under any such law. Tushar Hemani, Senior Advocate 34<br>
slide35. Thus, where matters covered by the 2016 Code are concerned [including insolvency resolution of corporate persons] if provisions contained therein are inconsistent with other statutes, including the 1961 Act, it shall override such laws. If such an approach is not adopted, it will undermine the entire object and purpose with which the Legislature enacted the 2016 Code.
Thus, the impugned notice & order dated 28.08.2018 & 17.10.2018 respectively, are unsustainable in law and, hence cannot be enforced. Tushar Hemani, Senior Advocate 35<br>
slide36. Rishi Ganga Power Corporation Ltd. vs. ACIT W.P.(C) 3167/2020 Facts:
Notices u/s. 143(2) were issued on 09.08.2018, 28.09.2018 & 30.09.2018 followed by a notices u/s. 142(1) dated 14.03.2019, 22.10.2019 & 04.11.2019.
None of the notices were complied, hence a penalty order u/s. 272A(1)(d) was passed on 21.11.2019.
Eventually an ex-parte assessment order u/s. 143(3) came to be passed on 06.12.2019.
Meanwhile a petition was filed under IBC against the assessee which was admitted by NCLT on 25.01.2018.
Consequent to insolvency proceedings, public announcement was made on 31.01.2018 which was published in various newspapers on 02.02.2018 & 03.02.2018. Tushar Hemani, Senior Advocate 36<br>
slide37. No claims were lodged by the Revenue being an operational creditor, with Resolution Professional (RP).
Resolution Plan was approved by NCLT on 13.11.2018.
On 11.02.2020, the new management who has taken over the affairs of the assessee, wrote to AO, explaining reasons for non-participation in assessment proceedings and requesting the AO for deletion of additions made thereunder.
Since there was no response from revenue, the assessee filed a writ petition in the High Court. Tushar Hemani, Senior Advocate 37<br>
slide38. Held:
Revenue argued that it has not lodged claims with the RP pursuant to public announcement on 31.01.2018 because claims had not fructified into demands on that date. The assessment order resulting in demand was passed on 06.12.2019.
IBBI (Insolvency Resolution Process for Corporate Persons) Regulations, 2016 require operational creditors to submit their claim with proof to the IRP, which are not necessarily claims that have been adjudicated. As per Regulation 7 of 2016 Regulations, operational creditors must file their claims with proof in the prescribed form i.e. Form B. Regulation 7, when read alongside particulars sought against Sr. No. 6 of Form B, would drive home the point that it can include claims that are disputed. Tushar Hemani, Senior Advocate 38<br>
slide39. Furthermore, the definition of claim u/s. 3(6)(a) of the 2016 Code puts these aspects beyond doubt:
“3. Definitions.- In this Code, unless the context otherwise requires,-
xxx xxxxxx
(6) “claim” means-
(a) a right to payment, whether or not such right is reduced to judgment, fixed, disputed, undisputed, legal, equitable, secured or unsecured;” Tushar Hemani, Senior Advocate 39<br>
slide40. Thus, having regard to the fact that the revenue had not lodged its claim, despite the publication of the public announcement by the Resolution Professional inviting claims from creditors, including statutory/operational creditors such as the revenue, no provision could be made [even if it may otherwise have been possible] in the approved RP. The terms contained in the approved RP are binding on all stakeholders, including those who could have filed claims but chose not to lodge them. The revenue, having failed to lodge its claim, cannot enforce the impugned orders and notices, given the binding nature of the approved RP. Tushar Hemani, Senior Advocate 40<br>
slide41. Section 31 of the 2016 Code, among other things, stipulates that once the RP is approved, it shall be binding on the corporate debtor and its employees, members, and creditors, which includes the Central Government, State Government, Local Authority to whom a debt in respect of payment of dues arising under any law for the time being in force and also on authorities to whom statutory dues are owed.
Accordingly, the assessment and penalty orders were quashed. Tushar Hemani, Senior Advocate 41<br>
slide42. Reopening Tushar Hemani, Senior Advocate 42<br>
slide43. Ganesh Dass Khanna vs ITO [WP(c) 11527/2022, dated 10/11/2023] Facts:
Notices u/s 148 of the unamended IT Act came to be issued for AY 2016-17 on 30.6.2021) & AY 2017-18 on 28.06.2021.
Pursuant to judgement of Supreme Court in case of Union of India v. Ashish Agarwal [2022] 444 ITR 1 (SC), revenue issued another notice under section 148A(b) dated 20-5-2022.
Assessee contended that reassessment proceedings triggered against it were time-barred as limitation period of three years qua relevant assessment years had expired and alleged escapement was below Rs.50 lacs. Tushar Hemani, Senior Advocate 43<br>
slide44. Issue:
After the coming into force of FA 2021, in cases where, for the relevant AY, the alleged escaped income was less than Rs.50 lakhs, notice under Section 148 could only be issued for commencement of reassessment proceedings within the limitation period provided in Clause (a) of Section 149(1) of the amended 1961 Act.
Consequently, for AYs 2016-17 & 2017-18, whether the order passed under Section 148A(d) and the consequent notice issued under Section 148 of the amended 1961 Act falls foul of the limitation prescribed in Clause (a) of Sub-Section (1) of Section 149?
Thus, in the ordinary course, the limitation for AY 2016-17 would expire on 31.03.2020; likewise, for AY 2017-18, the end date for the culmination of the limitation period would be 31.03.2021.
The revenue seeks to take recourse to the provisions of Section 3(1) of TOLA and the Notifications issued thereunder, from time to time, which, in effect, extended the end date for completion of proceedings and compliances up until 30.06.2021. Tushar Hemani, Senior Advocate 44<br>
slide45. Further following arguments were raised by the Revenue:
First, the observations made in the judgment of the Supreme Court in Ashish Agrawal‟s case.
Second, the observations made in paragraphs 98 and 99 by the coordinate bench in Mon Mohan Kohli‟s case.
Third, the extension of the time limit, as noticed hereinabove, granted via the subject Notifications by the Central Government in the exercise of powers under Section 3(1) of TOLA.
Fourth, the third and fourth provisos appended to Section 149 of the 1961 Act, which provide for the exclusion of periods referred to therein, which, if excised, would bring the impugned notices and orders within the limitation prescribed under Section 149(1)(a) of the amended 1961 Act.
Fifth, the issue raised before the Court is no longer res integra, given the judgments rendered by the coordinate bench in Touchstone and Salil Gulati. Tushar Hemani, Senior Advocate 45<br>
slide46. Held:
“Concededly, these notices were issued between 01.04.2021 and 30.06.2021, by which time limitation of three years under section 149(1)(a) had already expired and, thus, same were barred by limitation at the inception itself.”
Furthermore, the reference made in paragraphs 6.1 and 6.2(ii) of the Instruction dated 11.05.2022, to the extent it propounds the “travel back in time” theory, is declared bad in law. Tushar Hemani, Senior Advocate 46<br>
slide47. Kankanala Ravindra Reddy vs. ITO [2023] 156 taxmann.com 178 (Telangana) Facts:
For the AY 2016-17, the jurisdictional AO issued a notice to the assessee under section 148A and proceeded to reassess the income of the assessee and passed a further order under section 148A(d) and issued a reopening notice under section 148.
The assessee filed a writ petition contending that the reassessment has to be conducted in a faceless manner, rather than being assessed by the jurisdictional officer as was provided under section 144B and in accordance with the scheme enacted by the Central Government under section 151A. Tushar Hemani, Senior Advocate 47<br>
slide48. Held:
On preferring a writ before the Hon’ble High Court, it was observed that the Hon’ble Supreme Court in the case of Union of India vs. Ashish Agarwal – 444 ITR 1, ordered that notices issued under section 148 after enactment of Finance Act, 2021 shall be deemed to be notices issued under section 148A i.e. new provision inserted by Finance Act, 2021. However, the Hon’ble Supreme Court has only permitted the revenue to proceed further with reassessment proceedings under the amended provisions of law, more particularly, as amended by Finance Act, 2021. Tushar Hemani, Senior Advocate 48<br>
slide49. It was observed that certain provisions of the Income-tax Act which stood amended with effect from 1-4-2021 by virtue of the Finance Act, 2021. Section 144B inserted by virtue of the Finance Act, 2021, with effect from 1-4-2021 provides for faceless assessment and subsection (1) of the said newly inserted section 144B is an non obstante clause. Sub-section (1) of section 151A was inserted with effect from 1-11-2020 which refers to faceless assessment of income escaping assessment. Section 130 was amended so far as conferring jurisdiction of income tax authorities in light of faceless assessment procedure. Tushar Hemani, Senior Advocate 49<br>
slide50. In furtherance to the powers conferred under sub-sections (1) and (2) of section 130, CBDT framed a scheme called as the 'Faceless Jurisdiction of Income-tax Authorities Scheme, 2022.’ which defines automated allocation.
Further, CBDT again in exercise of its powers conferred under sub-sections (1) and (2) of section 151A framed another scheme called as the e-assessment of Income Escaping Assessment Scheme, 2022, which defines automated allocation and the scope of the scheme again has been envisaged in section 3 of the said scheme. Tushar Hemani, Senior Advocate 50<br>
slide51. After the introduction of the above two schemes, it becomes mandatory for the revenue to conduct/initiate proceedings pertaining to reassessment under sections147, 148 & 148A in a faceless manner. Proceedings under section 147 and section 148 would now have to be taken as per the procedure legislated by the Parliament in respect of reopening/reassessment i.e., proceedings under section 148A.
In the instant case, both the proceedings i.e., the impugned proceedings under section 148A, as well as the consequential notices under section 148 were issued by the local jurisdictional officer and not in the prescribed faceless manner. The order under section 148A(d) and the notices under section 148 are issued on 29-7-2022, i.e., after the 'Faceless Jurisdiction of the Income-tax Authorities Scheme, 2022’ and the 'e-Assessment of Income Escaping Assessment Scheme, 2022' were introduced. Tushar Hemani, Senior Advocate 51<br>
slide52. In the instant case, undisputedly the department has not proceeded against the petitioner under the substituted provisions of the Finance Act, 2021. Rather, it proceeded with the unamended provisions of law.
Hence, the impugned notice was set aside/quashed. Tushar Hemani, Senior Advocate 52<br>
slide53. 143(1) followed by 143(3) Tushar Hemani, Senior Advocate 53<br>
slide54. NSE Ltd. vs. DCIT ITA No. 732/Mum/2023 Facts:
Return of income was processed u/s. 143(1) disallowing an expenditure marked as capital expenditure in the tax audit report without considering the response of the assessee to proposed adjustments u/s. 143(1)(a)
Rectification u/s. 154 was filed, however no order was made by CPC, hence an appeal was filed before CIT(A).
Meanwhile, order u/s. 143(3) was passed on 28.09.2022 where no query was raised w.r.t. issue of allowability of such expenditure.
Thereafter CIT(A) passed his order on 12.01.2023 dismissing the assessee’s appeal against adjustment u/s. 143(1). Tushar Hemani, Senior Advocate 54<br>
slide55. Held:
The ITAT observed that neither assessee’s response to proposed adjustment was considered, nor application u/s. 154 was disposed of, amounting to violation of proviso 1 and 2 of the section 143(1) and making whole action null and void. Further, as the case of assessee was scrutinized u/s. 143(2) and assessment order u/s. 143(3) was passed, technically the doctrine of merger comes into picture, therefore the impugned adjustment by CPC gets merged into order passed u/s. 143(3) of the Act and order passed u/s. 143(3) only survives. Hence, the whole issue becomes academic including the order passed by CIT(A).
As far as reporting by Tax Auditor is concerned, maybe he has been appointed by the assessee, still his independence is always assumed and he is always free to give his own legal opinion, but the same is not binding on assessee or revenue. Tushar Hemani, Senior Advocate 55<br>
slide56. Controversies
u/s 197 of the Act Tushar Hemani, Senior Advocate 56<br>
slide57. ST Engineering Electronics Ltd. vs. ACIT ITA No. 755/Chny/2022 Facts:
Assessee has entered into fixed price sub-contract with the awardee of contract for undertaking signaling, platform screen doors & telecommunication work for Chennai Metro Rail Project. Assessee follows percentage of completion method (POCM) as per AS-7.
Assessee has obtained lower deduction certificate u/s. 197 by providing estimated costs & revenue details for FY 2012-13 till FY 2017-18 until which contract was expected to be completed.
Projected revenue under application u/s. 197 for FY 2017-18 was Rs. 2587.75 lakhs, however the revenue as per financial statements was Rs. 1146.03 lakhs along with a contract loss of Rs. 495.65 lakhs. Tushar Hemani, Senior Advocate 57<br>
slide58. Assessee submitted that the duration of project got extended to FY 2020-21. Revenue & costs were recorded as per POCM. Unrecognized portion of revenue was recorded & offered to tax in succeeding years.
Still, AO made an addition of shortfall in revenue in financial statements & application u/s. 197, after getting directions from DRP. Tushar Hemani, Senior Advocate 58<br>
slide59. Held:
The Hon’ble ITAT observed that in the application u/s. 197, the assessee has merely projected the contract revenue and these estimations could not be taken to be turnover disregarding revenue earned by assessee based on actual work certified by the contractor.
The deviation in estimation & actual revenue stood explained by the fact that duration of project got extended much beyond the original contract period.
Further, the aggregate contract revenue has been offered to tax over the life of the contract period starting from FY 2012-13 to FY 2022-23. Hence, taxing more amounts in this year would result into bringing to tax contract revenues much more than fixed price contract value to be received over life of the contract.
The appeal of the assessee stands allowed. Tushar Hemani, Senior Advocate 59<br>
slide60. Shreyansh Retail Pvt Ltd vs. DCIT W.P.(C) 11877/2023 Facts:
Assessee applied for Lower Deduction of tax certificate (LDC) seeking rate of TDS at 0.01% as against rate of 1% prescribed u/s 194O.
Assessee submitted various details called for by the DCIT along with calculation of projected tax refund of Rs. 45.05 crores under 0.5% TDS rate.
A non-speaking order was passed permitting deduction of TDS @ 0.5% as against 0.01% sought by the assessee. Tushar Hemani, Senior Advocate 60<br>
slide61. Held:
The Hon’ble Delhi High Court observed that the Impugned Order set forth no reasons for not accepting the rate of 0.01% as requested by the assessee.
At the request of the DR, an opportunity was granted to department to file a counter-affidavit furnishing reasons as regards conclusion arrived at in the Impugned Order.
However, the Court set aside the order by observing that the Impugned Order must stand on its own legs, & accordingly, reasons furnished by a counter-affidavit could not be supplanted in the Impugned Order.
Reliance was placed on the case of Mohinder Singh Gill v. Chief Election Comm., (1978) 1 SCC 405, wherein the Hon’ble Supreme Court held as under: Tushar Hemani, Senior Advocate 61<br>
slide62. “8. The second equally relevant matter is that when a statutory functionary makes an order based on certain grounds, its validity must be judged by the reasons so mentioned and cannot be supplemented by fresh reasons in the shape of affidavit or otherwise. Otherwise, an order bad in the beginning may, by the time it comes to court on account of a challenge, get validated by additional grounds later brought out. We may here draw attention to the observations of Bose, J. in Gordhandas Bhanji [Commr. of Police, Bombay v. Gordhandas Bhanji, 1951 SCC 1088 : AIR 1952 SC 16] : Tushar Hemani, Senior Advocate 62<br>
slide63. “Public orders, publicly made, in exercise of a statutory authority cannot be construed in the light of explanations subsequently given by the officer making the order of what he meant, or of what was in his mind, or what he intended to do. Public orders made by public authorities are meant to have public effect and are intended to affect the acting and conduct of those to whom they are addressed and must be construed objectively with reference to the language used in the order itself.”
Orders are not like old wine becoming better as they grow older.” Tushar Hemani, Senior Advocate 63<br>
slide64. Bitkuber Investments P. Ltd. & others vs. DCIT W.P. No. 11565 of 2023 Facts:
Assessee company got incorporated in March, 2021 and has started its operations in April, 2022.
Assessee is part of group entities including M/s. Bitcipher Labs LLP & Chain Laps Pte. Ltd. (Singapore) (“M/s. Bitcipher”).
Assessee applied for Non-deduction of TDS certificate u/s. 197 for FY 2023-24.
The application u/s. 197 got rejected majorly on following grounds:
Assessee cannot avail assistance of Rule 28AA
There is no precedential guidance for examining the basis of estimation Tushar Hemani, Senior Advocate 64<br>
slide65. iii. A survey u/s. 133A is conducted on M/s. Bitcipher’s premises resulting in initiation of proceedings u/s. 201.
iv. Ambiguity in transactions under different agreements between assessee and M/s. Bitcipher which are under common control of Chain Labs Pte. Ltd. like:
Agreements are executed after survey u/s. 133A
It is not clear whether any asset would remain with M/s. Bitcipher to discharge liability u/s. 201
Agreements do not have specific clauses on present & future liability of M/s. Bitcipher, there is no clarity on how the tax will be discharged. Tushar Hemani, Senior Advocate 65<br>
slide66. Held:
Section 197(2A) stipulates that CBDT may make Rules specifying cases & circumstances under which application can be made, conditions s.t. which certificate may be granted & matters connected therewith.
However, those conditions cannot impose a classification amongst the assessees to even file an application when provisions do not contemplate the same. Tushar Hemani, Senior Advocate 66<br>
slide67. Rule 28AA(2) requires the AO to determine existing & estimated liability after considering the following:
tax payable on estimated income of previous year (PY)
tax payable on assessed/returned/estimated income, as the case may be, for last 4 PYs.
Existing liability under Income Tax/Wealth Tax Act
Advance tax payment, TDS & TCS for the PY till the date of making of application.
However, the above details cannot be read to say that a Certificate will be issued only when returns for the 4 PYs are filed or tax must be paid for PY inasmuch as provisions of Rule 28AA(1) and 2(i) & 2(ii) contemplate estimated liability & estimated income. Tushar Hemani, Senior Advocate 67<br>
slide68. If the contention that only if returns are filed for 4 PYs, or the payment of tax, is accepted as a condition for entertaining an application u/s. 197(1), it would result into permitting classification & rendering redundant the concept of estimated liability & estimated income that are built into Rule 28AA.
Further, on an application u/s. 197(1), AO has to record his satisfaction only upon the examination of circumstances mentioned in Rule 28AA. The liability of another entity (here M/s. Bitcipher), even if it is the sister concern, would be extraneous.
The order was quashed and the matter was sent to AO for reconsideration. Tushar Hemani, Senior Advocate 68<br>
slide69. Settlement Commission
Few issues Tushar Hemani, Senior Advocate 69<br>
slide70. Kotak Mahindra Bank Ltd. v. CIT [2023] 458 ITR 113 (SC) Facts:
During assessment proceedings for assessment year 1997-98, the AO observed that the assessee was accounting for lease rentals by treating same as financial transaction and lease rental was bifurcated into capital repayment portion and interest component. Only interest was offered for tax. Accordingly, the AO opined that since assessee treated such leases as loans granted to the lessees to purchase the assets, the ownership of the assets was vested with the lessees. He, thus, issued reopening notice for AYs 1994-1995 to 1996-1997 on ground that assessee claimed depreciation on said assets even though it was not owner of the assets. AO also levied penalty u/s 271(1)(c).
The assessee approached Settlement Commission to settle its tax liabilities under section 245C. Tushar Hemani, Senior Advocate 70<br>
slide71. The revenue raised preliminary objection contending that assessee had not made a full and true disclosure of its income which had not been disclosed before the AO. Disallowance of depreciation was already discovered by the AO. There is no new or additional income being offered by the assessee.
The Settlement Commission found the application maintainable and passed order determining additional income and also annulled the penalty levied by the AO on ground that the non-disclosure of lease rentals was on account of RBI guideline and the assessee subsequently disclosed said rentals before Settlement Commission when the assessee realised the omission to disclose the same as per income-tax law.
Revenue challenged the order of Settlement Commission, wherein the Single Judge did not find the reasoning of the Settlement Commission convincing and held the Order granting immunity from penalty and prosecution to be an illegal order. Matter was remanded to Settlement Commission for the limited purpose of reconsidering the question of immunity from levy of penalty and prosecution.
DB confirmed the order of Single Judge. Tushar Hemani, Senior Advocate 71<br>
slide72. Held:
Settlement Commission was right in granting immunity. The necessary ingredients for granting immunity from prosecution would be: (a) the assessee should have co-operated with the Settlement Commission in the proceedings before it; and (b) the assessee should have made a full and true disclosure of its income and the manner in which such income has been derived, to the satisfaction of the Commission.
According to the revenue, in the present case, what had been "disclosed" in the application was the same as what was "discovered" by the Assessing Officer and therefore, the application of the assessee ought not to have been entertained by the Commission, and further, immunity under section 245H ought not to have been granted.
Even if the pre-conditions prescribed under section 245C are to be read into section 245H, it cannot be said that in every case, the material "disclosed" by the assessee before the Commission must be something apart from what was discovered by the Assessing Officer. What is of relevance is that the assessee offered to tax, income, in addition to the income recorded in the return of income. Tushar Hemani, Senior Advocate 72<br>
slide73. Section 245C read with section 245H only contemplates full and true disclosure of income to be made before the Settlement Commission, regardless of the disclosures or discoveries made before/by the Assessing Officer. Disclosure may also include the income discovered by the Assessing Officer.
Powers vested with the Settlement Commission u/s 245H is a discretionary power to be exercised if the Settlement Commission is satisfied that an assessee has complied with the preconditions specified therein. It is trite that any judicial, quasi-judicial or administrative authority must while exercising discretion, direct itself properly in law and consider all the facts and material that it is bound to consider while excluding from consideration irrelevant aspects of the matter. Tushar Hemani, Senior Advocate 73<br>
slide74. Jain Metal Rolling Mills & others vs. UOI & others W.P. No. 13455 of 2021 Facts:
Finance Act, 2021 has abolished the Income Tax Settlement Commission (ITSC) by making certain amendments in Section 245-A. However, such abolition was made w.e.f. 01.02.2021 i.e. the date on which Finance Bill, 2021 was introduced in the Parliament instead of 01.04.2021 when the Finance Act, 2021 came into force.
An Interim Board was constituted for disposal of pending applications with ITSC, however only the applications pending on 01.02.2021 were considered and the applications to ITSC during 01.02.2021 to 31.03.2021 were rejected on account of abolition of ITSC w.e.f. 01.02.2021.
Hence, writ petitions were filed challenging the constitutional validity of this retrospective amendment. Tushar Hemani, Senior Advocate 74<br>
slide75. Held:
The basic ground of attack on the constitutionality of the impugned enactment is that it is retrospective in nature and that it takes away the vested rights of the petitioners. In this regard, the contention on behalf of the State is that the settlement itself is concession and therefore, the writ petitioners cannot claim any vested right. We are unable to countenance the said argument on behalf of the State. It may be true that the orders passed by ITSC containing terms of settlement has the trappings of concession and benevolence showered by the State to a particular assessee. But, such benevolence, concession etc., are exercised by the State through a statutory regime. Tushar Hemani, Senior Advocate 75<br>
slide76. The State had every right to abolish the ITSC. While being so, in appropriate cases, the right to enact a law with retrospective operation is also well recognized. In the instant case, on a perusal of the impugned legislation, it was given retrospective effect with effect from 01.02.2021 on the premise that it is on the said date, that the Bill was introduced by the Parliament, by which, all the assessees and the general public concerned are made to know about the policy decision in the making by which the State proposed to make the ITSC inoperative. The act of the State in abolishing the ITSC with effect from a cut-off date per se cannot be illegal or ultra vires the Constitution. Tushar Hemani, Senior Advocate 76<br>
slide77. But, at the same time, the ITSC did exist legally and factually until 31.03.2021. Every eligible assessee had a right to approach the ITSC, if they had a ‘case’ pending against them. The definition of 'case' as per Section 245-A(eb) is also extracted above. Therefore, even if any proceeding for assessments/reopening is issued after 01.02.2021 upto 31.03.2021, the assessee had a ‘case’ to approach the Commission and if they had submitted an application and if no final order has been passed under Sub-Section 4 of 245(D) on or before 31.01.2021, then the said application is treated as a ‘pending application’. It can be seen that in respect of the case of the petitioners whose matters had arisen before the notification of the Act on 01.04.2021, but, after the cut-off date of 01.02.2021, were also very much eligible to approach the ITSC. Tushar Hemani, Senior Advocate 77<br>
slide78. Without amending the definition of case pending applications etc., Section 245C(5) simply provides that no application shall be made under the Section on or after the first day of February, 2021. The right to file application before ITSC is very much existent and has been exercised till 31.03.2021. The retrospective legislation by way of legal fiction attempts to make it as if it is unavailable.
As a matter of fact, the applications are either made by the petitioners or on direction by the orders of the Court as the ITSC was in the statute book in the interregnum period before the retrospective legislation came into force. Therefore, the retrospectivity also makes these directions of Court and the consequential applications being filed before the ITSC nugatory. Tushar Hemani, Senior Advocate 78<br>
slide79. Therefore, when we consider the instant case, the purpose of the retrospective legislation is to make the ITSC inoperative right from the date of the introduction of the Bill and to send all the pending applications to the Interim Board. Therefore, fixing the last date for filing the applications alone travels beyond the purpose and results in more retrospectivity than which is needed and thus, runs counter to the other parts of the Act. As a matter of fact, as per the principle of lex prospicit non respicit (law looks forward not back) it can be seen that the purport of the legislation is only to do away with the policy of resolution through ITSC. Tushar Hemani, Senior Advocate 79<br>
slide80. As a matter of fact, the Central Government has to make a Scheme for the purposes of Settlement in respect of pending applications by the Interim Board as per Section 245D(11) and such scheme had to be placed before the Parliament. Thus, neither there is any intent nor it is within the purpose to do away with the ‘pending applications’ in respect of matters in which the ‘cases’ arose from 01.02.2021 to 31.03.2021. Thus, we find that it is just and necessary to read down the last date mentioned for filing applications in Section 245C(5) as 31.03.2021 and consequently the last date mentioned in paragraph No.4(i) of the Circular should also read as 31.03.2021.
The decision was rendered in favour of assessee and accordingly, the writ petitions were partly allowed. Tushar Hemani, Senior Advocate 80<br>
slide81. Document
Identification
Number Tushar Hemani, Senior Advocate 81<br>
slide82. Sharda Devi Bajaj & Others vs. DCIT ITA No. 3006, 3008, 3009/Del/2022 Facts:
Assessment order was passed in the case of assessee which was also confirmed by CIT(A).
Assessee filed an appeal before ITAT where in addition to challenging on merits, assessee raised an additional ground stating that assessment order does not contain DIN (Document Identification Number).
Held:
Hon’ble ITAT held that the additional ground pertains to a question of law which is based on material already on record and hence, it deserves to be admitted. Tushar Hemani, Senior Advocate 82<br>
slide83. Reliance was made to decision of Hon’ble Supreme Court in NTPC vs. CIT (1998) 229 ITR 383 (SC) wherein it was held that the view that the Tribunal is confined only to issues arising out of the appeal before the CIT(A) is too narrow a view of the powers of the Appellate Tribunal. It has been held that Tribunal will have a discretion to allow or not to allow new ground to be raised. However, where the Tribunal is only required to consider a question of law arising from the facts which are on record, in the assessment proceedings, there is no reason, why such a question should not be allowed to be raised. Tushar Hemani, Senior Advocate 83<br>
slide84. On merits, it was held that the CBDT Circular No. 19/2019 dated 14.8.2019 has mandated, Generation/ Allotment/ Quoting of computer generated Document Identification Number (DIN) in the body of all communications, in the nature of notices/summons/ letters/ correspondences as well as the orders passed.
Para 3 of the Circular sets out, exceptional circumstances, in which such communications may be issued manually, with the rider that this shall be done only after recording reasons in writing in the file and with the prior written approval of the Chief Commissioner/Director of Income Tax. Tushar Hemani, Senior Advocate 84<br>
slide85. Para 4 of the Circular provides that any communication which is not in conformity with the requirement of Para 2 and Para 3 shall be treated as invalid and shall be deemed to have never been issued.
In the present case, it is not in dispute and otherwise, it is a matter of record that the order of the Assessing Officer does not bear any DIN.
On behalf of the Revenue reliance is placed on the communication dated 17.9.2019 which pertains to the roll out of facility for System generated Document (i.e. Intimation Letter) containing Document Identification number (DIN) for documents issued outside the system but uploaded manually in Income Tax Business Application (ITBA). Tushar Hemani, Senior Advocate 85<br>
slide86. From para 4 of the communication dated 17.09.2019, it is clear that it pertains to the functionality to capture and uphold the letters, notices and orders issued manually and served on taxpayers by users due to any exceptional circumstances under Para 3 (i), (ii) and (iii) of the aforesaid Circular dated 14.8.2019. It is not the case made out that there are any exceptional reasons recorded in these appeals as required by the Circular dated 14.8.2019. Thus, in our opinion, the said communication cannot come to the aid of the Revenue in the present Appeals.
Hence, the additional ground as raised has to succeed. Tushar Hemani, Senior Advocate 86<br>
slide87. Gupta Domestic Fuels (Nagpur) Ltd.& Others vs. ACIT ITA No. 61/NAG/2022 & others Facts:
Assessment orders and appellate orders were issued without quoting computer-generated DIN (Document Identification Number) in the body of the orders.
DIN were intimated to assessees by separate letters.
Held:
On appeal to ITAT, it was held that circular No. 19/2019 dt. 14/08/2019 mandated the income tax authorities w.e.f. 01/10/2019 for generation, allotment and communication of computer generated DIN in relation to any assessment, appeals, orders, statutory or otherwise, exemptions, enquiry, investigation, verification of information, penalty, prosecution, rectification, approval etc. Tushar Hemani, Senior Advocate 87<br>
slide88. Intimation of DIN by separate letters communicated within 15 days of issuance of former DIN less communication would be valid only if, former DIN less communication is issued incorporating therein the reason for issue of such DIN less communication in terms of para 3(i) to 3(v) [as applicable] along with the Number & date of obtaining written approval of the Chief Commissioner / Director General of Income-Tax in a specified format, and not otherwise.
The decision was held in favour of assessees rendering the impugned orders invalid as if they have never been issued. Tushar Hemani, Senior Advocate 88<br>
slide89. 153A & 153C Tushar Hemani, Senior Advocate 89<br>
slide90. PCIT vs. Abhisar Buildwell Pvt. Ltd. [2023] 454 ITR 212 (SC) Facts:
The core issue involved in the instant appeal filed by revenue was the scope of assessment under section 153A. According to the revenue, the Assessing Officer was competent to consider all the material that was available on record including that found during the search, and make an assessment of 'total income'.
However, according to the assessee if no assessment proceeding was pending on the date of initiation of the search, the Assessing Officer might consider only the incriminating material found during the search and was precluded from considering any other material derived from any other source. Tushar Hemani, Senior Advocate 90<br>
slide91. Held:
The observations of Hon’ble Supreme Court are as under:
That in case of search under section 132 or requisition under section 132A, the AO assumes the jurisdiction for block assessment under section 153A;
All pending assessments/reassessments shall stand abated;
In case any incriminating material is found/unearthed, even, in case of unabated/completed assessments, the AO would assume the jurisdiction to assess or reassess the 'total income' taking into consideration the incriminating material unearthed during the search and the other material available with the AO including the income declared in the returns; and Tushar Hemani, Senior Advocate 91<br>
slide92. In case no incriminating material is unearthed during the search, the AO cannot assess or reassess taking into consideration the other material in respect of completed assessments/unabated assessments. Meaning thereby, in respect of completed/unabated assessments, no addition can be made by the AO in absence of any incriminating material found during the course of search under section 132 or requisition under section 132A of the Act, 1961. However, the completed/unabated assessments can be re-opened by the AO in exercise of powers under sections 147/148 of the Act, subject to fulfilment of the conditions as envisaged/mentioned under sections 147/148 of the Act and those powers are saved. Tushar Hemani, Senior Advocate 92<br>
slide93. CIT vs. Jasjit Singh [2023] 458 ITR 437 (SC) Facts:
Search was conducted on a third party on 19.02.2009 where documents belonging to assessee were found.
The assessment of assessee was centralized on 16.06.2009. Assessment of AY 2009-10 was completed u/s. 143(3) treating the AY 2009-10 as year of search & assessments of AY 2003-04 to 2008-09 were reopened u/s. 153C.
Assessee contended that as per first proviso to Section 153C, the year in which documents belonging to him were transferred to his jurisdictional AO shall be considered as year of search i.e. AY 2010-11 when his case was centralized on 16.06.2009 & not AY 2009-10. Tushar Hemani, Senior Advocate 93<br>
slide94. Assessee submitted that the assessment of AY 2009-10 framed u/s. 143(3) without issuing notice u/s. 153C and recording satisfaction is null and void.
CIT(A) has confirmed the validity of assessment order u/s. 143(3) for AY 2009-10.
On appeal, ITAT held in favour of assessee.
On further appeal, the High Court upheld the order of ITAT.
Held:
On appeal, the Hon’ble Supreme Court dismissed the appeal and held that the submission of revenue that the first proviso to Section 153C is confined only to question of abatement is unsubstantial and without merit. Tushar Hemani, Senior Advocate 94<br>
slide95. It is evident on a plain interpretation of section 153C(1) that the Parliamentary intent to enact the proviso was to cater not merely to the question of abatement but also with regard to the date from which the six year period was to be reckoned, in respect of which the returns were to be filed by the third party, whose premises are not searched and in respect of whom the specific provision u/s. 153-C was enacted.
If the date would virtually relate back to the date of seizure as contended by revenue, it would cause prejudice to third party who is not searched. For instance, if the papers are assigned u/s. 153C after 4 years, the third party assessee has to preserve records for at least 10 years which is not the requirement in law. Accordingly, the revenue’s appeals were dismissed. Tushar Hemani, Senior Advocate 95<br>
slide96. Tax Appeals Tushar Hemani, Senior Advocate 96<br>
slide97. Bikram Singh vs. PCIT [2023] 154 taxmann.com 80 (SC) Facts:
During assessment proceedings, AO made addition under section 68 in respect of loans/advances received from eight persons, on ground that assessee was unable to establish identity, creditworthiness and genuineness of said persons and transactions.
Tribunal set aside additions in respect of four creditors.
High Court restored the matter to AO holding that mere establishing of their identity and fact that amounts had been transferred through cheque payments, did not by itself mean that transactions were genuine. Tushar Hemani, Senior Advocate 97<br>
slide98. Held:
On appeal to Hon’ble Supreme Court, it was observed that the High Court has not followed procedure under section 260A.
On a reading of the provision of section 260A, it is noted that an appeal before the High Court is maintainable only on a substantial question of law (not a question of fact or only a question of law). The High Court when entertaining such an appeal must formulate that question and admit the appeal, thereafter, on the question so formulated the respondent must also be heard and consequently the matter must be disposed of depending on whether the substantial question of law requires to be answered for Tushar Hemani, Senior Advocate 98<br>
slide99. or against either of the parties or no such question of law would arise. The High Court has also the power to formulate a fresh question of law if it so arises on hearing the respective parties in the event, such a substantial question of law would arise and if the High Court is satisfied the said case involves such a question.
Further, sub-section (7) of section 260A states that 'save as otherwise provided in this Act, the provisions of the Code of Civil Procedure, 1908 (5 of 1908), relating to appeals to the High Court shall, as far as may be, apply in the case of appeals under this section’. Since the appeal filed under section 260A is akin to a Second Appeal, section 100 read with Order XLII rule 1 of Code Tushar Hemani, Senior Advocate 99<br>
slide100. of Civil Procedure would apply, wherein, in a Regular Second Appeal under the said provision read with section 100 of the said Code, the formulation of a substantial question of law when the matter is entertained and admitted would be required, otherwise the High Court has the power to dismiss such a Second Appeal on the ground that no such substantial question of law arises in the appeal.
In the present case, it is found that the High Court did not formulate any substantial question of law at the time of admitting the appeal, rather the appeal was heard on merits and in the absence of formulating the substantial question of law the appeal was reserved for judgment. Tushar Hemani, Senior Advocate 100<br>
slide101. During the course of preparation of the judgment, the question of law was framed stated to be a 'question of law' and the matter was then admitted and at the same time considered on merits. Issuance of notice prior to admission without framing any substantial question(s) of law is not contemplated under section 260A. The High Court has either to admit or not admit the appeal. If the High Court admits the appeal then substantial question(s) of law has to be framed and the respondent put on notice on such substantial question(s) of law. On the contrary, if the High Court is of the view that no substantial question of law arises, then the appeal has to be dismissed. Tushar Hemani, Senior Advocate 101<br>
slide102. It is found that the procedure adopted by the High Court in the instant case is not in consonance with what is contemplated under section 260A and hence, on that short ground alone the impugned judgment is set aside. The matter is remanded to the High Court for re consideration of the appeal filed by the respondent-revenue having regard to the essentials of section 260A and in accordance with law. Tushar Hemani, Senior Advocate 102<br>
slide103. PCIT vs. KGY Glass Industries P. Ltd. R/Tax Appeal No. 722 of 2023 Facts:
Assessee company opted to be taxed as per provisions of Section 115BAA while filing return of income.
Return was processed by CPC u/s 143(1) on 20/12/2021 and income was taxed as per Section 115JB & not as per concessional rate u/s. 115BAA because assessee has not filed Form 10-IC on or before due date of filing return of income.
Form 10-IC could not be uploaded by the assessee before due dated of return of income due to some technical error. The time limit for filing Form 10-IC was extended to 30.06.2022 and assessee physically filed such form before AO on 29.06.2022.
Appeal was filed before CIT(A) which came to be dismissed holding that filing of Form 10-IC before due date of return of income is a mandatory requirement as per Section 115BAA(5) r.w. Rule 21AE. Tushar Hemani, Senior Advocate 103<br>
slide104. Further appeal was filed before Hon’ble ITAT which was allowed in favour of assessee.
Held:
On Revenue’s appeal, the Hon’ble High Court observed that during the relevant period, due date of filing Form 10-IC was extended to 30.06.2022. The assessee physically filed such Form before AO on 29.06.2022. Copy of such form was also placed before ITAT.
Since assessee could not upload Form 10-IC on account of technical error, there being no fault of assessee, it could not be deprived of benefit particularly when this being first year for availing such benefits.
Accordingly issue was decided in favour of assessee and revenue’s appeal was dismissed. Tushar Hemani, Senior Advocate 104<br>
slide105. PCIT vs. Jigar Jashwantlal Shah R/Tax Appeal No. 80 & 96 of 2023 Facts:
Assessee is a director in a company. Such company issued right shares at Rs. 10 per share.
Assessee was allotted 1,03,000 right shares of such company in proportion to his existing shareholding.
Assessee was allotted additional 82,200 right shares due to renunciation of rights by his wife & father.
Assessee was allotted additional 14,800 right shares due to renunciation of rights by a third party.
AO invoked Section 56(2)(vii)(c), computed FMV of right shares at Rs. 255 per share & made the addition of the differential amount. Tushar Hemani, Senior Advocate 105<br>
slide106. CIT(A) partly allowed the appeal to the extent of 1,03,000 right shares allotted proportionate to existing shareholding of the assessee.
ITAT allowed the appeal to the extent of 1,85,200 right shares [1,03,000 as allowed by CIT(A) + 82,200 being right shares allotted pursuant to renunciation of rights by the assessee’s wife and father in addition to what has been allowed by CIT(A)].
Revenue filed an appeal before the Hon’ble Gujarat High Court against the order of ITAT. Tushar Hemani, Senior Advocate 106<br>
slide107. Held:
On appeal, Gujarat High Court observed that on conjoint reading of provision as well as explanatory note of the said provision, it is clear that only when an individual or a HUF receives any property for consideration which is less than the FMV, the provisions of Sec.56(2)(vii)(c) would be attracted.
In the facts of the case, the shares had come into existence only when the allotment is made by the company as right shares cannot be said to be “received from any person”. In other words, the property must pre-exist for application of Sec.56(2)(vii)(c), which is clear from the intention of the legislature. Tushar Hemani, Senior Advocate 107<br>
slide108. If the shares are allotted strictly on proportionate basis based on existing shareholding, then though the provisions per se are applicable, but will not operate adversely because the gain accruing on allotment of fresh shares will be offset by the loss in value of existing shares.
The Tribunal, therefore held that the provisions of sec.56(2)(vii)(c) would not apply in respect of allocation of 1,03,000 right shares allotted to the assessee proportionate to its share holding in the company. Tushar Hemani, Senior Advocate 108<br>
slide109. Further, it is a settled principle of law that what cannot be done directly cannot be done indirectly as well. The Tribunal, therefore, held that had the wife and father of the assessee directly transferred their shares in favour of the assessee, provisions of Sec.56(2)(vii)(c) of the Act could not have been invoked since both of them are falling in the definition of “relatives” which are excluded from within the purview of operation of Sec.56(2)(vii)(c) of the Act. As a consequence it was held that the renunciation of right shares by wife and father of the assessee by not exercising the right to subscribe would not attract the provisions of Sec.56(2)(vii)(c) of the Act. Tushar Hemani, Senior Advocate 109<br>
slide110. With regard to the application of Sec.56(2)(vii)(c) of the Act for the balance 14,800 shares allotted to the assessee as a result of third pary share-holder declining to apply for right shares in favour of the assessee, the Tribunal held against the assessee because renunciation of rights in favour of the assessee by third party who are not related does lead to disproportionate allocation of shares in favour of the assessee.
Hence, the appeals of the Revenue were dismissed. Tushar Hemani, Senior Advocate 110<br>
slide111. PCIT vs. Weilburger Coatings (India) Pvt. Ltd. IA NO: GA/1/2023, GA/2/2023 – Calcutta HC Facts:
Assessee’s case was selected for limited scrutiny & certain additions were made by AO which were confirmed by CIT(A).
Assessee raised an additional ground before ITAT contending that AO has no jurisdiction to make additions on the issues beyond limited scrutiny.
ITAT agreed to the contention of the assessee and allowed the assessee’s appeal holding that AO has exceeded his jurisdiction. Tushar Hemani, Senior Advocate 111<br>
slide112. Held:
On further appeal, Hon’ble Calcutta High Court held that ITAT has rightly allowed the appeal of the assessee.
Reliance was placed on the decision of PCIT vs. Sukhdham Infrastructures LLP – ITAT No. 164 of 2023 dated 14.08.2023, where an identical contention was raised stating that at best the action of AO could be construed as an irregularity. Such contention was rejected by the Court with the following observations:
“While considering the said issue, the Hon’ble Supreme Court noted the distinction between the statutes affecting rights and those affecting mere procedure. The revenue Tushar Hemani, Senior Advocate 112<br>
slide113. cannot rely upon the said decision as the scheme of assessment as provided under Section 143 of the Act is a complete code by itself and the circumstances under which the power under sub-section (2) of Section 143 could be invoked has been clearly spelt out and on a reading of sub-section (3) of Section 143, it s evidently clear that on the day specified in the notice issued under sub-section (2), or as soon afterwards as may be, after hearing such evidence as the assessee may produce and such other evidence as the Assessing Officer may require on specified points, and after taking into account all relevant material which he has gathered, the Assessing Officer shall, by an order in writing, make an assessment of the total income or loss of the assessee, and determine the sum payable by him or refund of any amount due to him on the basis of such assessment. Tushar Hemani, Senior Advocate 113<br>
slide114. Therefore, the question of part of the provision being procedural is an incorrect interpretation of the scheme provided under Section 143 of the Act. Further, as noted above, the CIT(A) has examined the merits of the matter and after taking note of the facts granted relief to the assessee to the extent indicated therein. Thus, for the above reasons, we find that the revenue has not made out any case for interference of the order passed by the Tribunal. Accordingly, the appeal fails and is dismissed.
The substantial questions of law are answered against the revenue.
The application for stay being GA 1 of 2023 is also dismissed.” Tushar Hemani, Senior Advocate 114<br>
slide115. Mutuality Tushar Hemani, Senior Advocate 115<br>
slide116. Secundrabad Club etc. vs. CIT [2023] 457 ITR 263 (SC) Facts:
The assessee-clubs deposited surplus funds by way of bank deposits in various bank and claimed interest earned on said deposits was exempt on the principle of mutuality.
On appeal, the various High Courts held that the interest earned on the bank deposits made by the assessee-clubs was liable to be taxed in the hands of the clubs and the principle of mutuality would not apply. Tushar Hemani, Senior Advocate 116<br>
slide117. Held:
On further appeal, the Hon’ble Supreme Court held that the triple test for applying principle of mutuality was discussed in the case of Bangalore Club vs. CIT [350 ITR 509 (SC)]. The triple test is as under:
Complete identity between contributors & participators
Action of participators & contributors must be in furtherance of the mandate of associations or Clubs.
There must be no scope for profiteering by the contributors from a fund made by them which could only be expended or returned to themselves. Tushar Hemani, Senior Advocate 117<br>
slide118. That, it is not a normal activity of the assessee clubs to deposit funds in a bank. It is only when a surplus is generated. In the absence of the said fixed deposits being utilized by the banks for their transactions with their customers, no interest can be payable on the fixed deposits. This is so in respect of any customer of a bank who would deposit surplus funds in a bank. It may be that the interest income would be ultimately used for the benefit of the members of the clubs but that is not a consideration which would have an impact on satisfying the triple test of mutuality. Tushar Hemani, Senior Advocate 118<br>
slide119. It was observed in Bangalore Club (supra) that even if ultimately the interest income and surplus funds in the
fixed deposit are utilized for the benefit of the members of the clubs, the fact remains that when the fixed deposits were made by the clubs in the banks, they were exposed to transactions with third parties, i.e., between the banks and its customers and this would snap the principle of mutuality breaching the triple test.
The question asked therefore is - at what point does the relationship of mutuality end and that of trading begin. If there is an entry of a third party or non-member to deal with the contributions of or funds of the club or to Tushar Hemani, Senior Advocate 119<br>
slide120. utilize the funds of the club and return the same with interest, then, the relationship of the parties is not on the basis of a privity of mutuality. The essential condition of mutuality, i.e., identity between the contributors and participators would end. The relationship would then be like any other commercial relationship such as that between a customer and a bank where the fixed deposit is made by the customer for the purpose of earning an interest income.
Thus, the interest income earned on fixed deposits made in the banks by the appellant Clubs has to be treated like any other income from other sources within the meaning of section 2(24).
Consequently, the appeals were dismissed. Tushar Hemani, Senior Advocate 120<br>
slide121. Prosecution Tushar Hemani, Senior Advocate 121<br>
slide122. Tirumala Tirupati Constructions P. Ltd. vs. ADIT Criminal Petition No. 2684 of 2022 Facts:
Assessee has sold land in AY 2015-16 & 2016-17 at the rates below Sub-Registrar office. Assessee has not filed returns of income for such AYs & not paid any tax.
Sanction u/s. 279(1) was issued by PDIT(Inv.), Hyderabad to DDIT(Inv.) for prosecuting the assessee for offences punishable u/s. 276(1) & 278B.
Pursuant to such sanction, ADIT(Inv.) filed a criminal complaint to Special Court of Economic Offences, Hyderabad.
Assessee has challenged the said criminal complaint contending that initiation of prosecution is illegal & void-ab-initio. Tushar Hemani, Senior Advocate 122<br>
slide123. Held:
As per Section 279(1), sanction has to be accorded by an officer at the level of CCIT/DGIT. However, in the present case, sanction has been accorded by PDIT, who is lower in rank than CCIT.
Further, sanction was accorded to DDIT but complaint was filed by ADIT, who is lower in rank than DDIT.
It is evident that if a statutory authority has been vested with jurisdiction, he has to exercise it accordingly and if discretion is exercised under the directions or in compliance of some higher authority’s instruction, then it would be a case of failure to exercise discretion altogether. Tushar Hemani, Senior Advocate 123<br>
slide124. The authority which has initiated the prosecution must have sanction of law. Otherwise, it amounts to illegal action.
If a statute has conferred a power to act and has laid down the method, any power must be exercised discreetly, which prohibits doing of act in any another manner. Which means, if a sanction has been granted to the Deputy director to launch prosecution against the petitioner company, it is for the Deputy Director alone to launch the prosecution but not the Assistant Director.
Even though DDIT is a senior officer & ADIT is a junior officer and both were doing the same duties, the said contention cannot be taken into consideration as in the present case, the sanction is accorded to the DDIT for initiating prosecution and not to ADIT. Hence, the proceedings were quashed. Tushar Hemani, Senior Advocate 124<br>
slide125. Scope of S. 254(2) Tushar Hemani, Senior Advocate 125<br>
slide126. Pr. CIT vs Hitesh Ashok Vaswani (SCA No. 198 of 2023, dated 02/11/2023) Facts: Petitioner challenged the order passed by the ITAT u/s 254(2) of the Act. Revenue was dissatisfied with the dismissal of its miscellaneous applications filed against the order passed u/s 254(1) of the Act and therefore filed Special Civil Applications (writs) against such order.
Held: While dismissing the writs filed by the Deptt., High Court observed that “the mistake has to be apparent from the face of the record and not one where an extensive delving into arguments and a re-look can be sought on questions decided on merits”.
HC further notes that the ITAT considered the issues threadbare on merits in light of the case laws, and thus, remarks “merely because the ITAT, according to the Revenue, decided the issues by misinterpretation of facts and law, the same cannot be a subject matter of rectification”. Tushar Hemani, Senior Advocate 126<br>
slide127. HC relies on SC ruling in Reliance Telecom [(2021) 440 ITR 1 (SC)] wherein it was observed that when a detailed order was passed by ITAT, no rectification can be made on the ground that the order passed by ITAT was erroneous either on facts or in law and preferring an appeal is the only remedy in such a case.
HC also considers co-ordinate bench ruling in Vrundavan Ginning and Delhi HC ruling in Maruti Insurance to observe that “the power to rectify an order under Section 254(2) is extremely limited and it does not extend to correcting the errors of law or reappreciating the factual findings. Those properly fall within the appellate review of an order of Court of first instance. What legitimately falls for consideration are errors (mistakes) apparent from the record”
Moreover, HC relies on Delhi HC ruling in R.C. Sabharwal and co-ordinate bench ruling in Muni Seva Ashram and observes that in the instant case appeals were filed by the Revenue which have been admitted by the HC and thus, disposes of the petitions reserving the right of the Revenue to urge the grounds raised in these petitions while arguing appeals. Tushar Hemani, Senior Advocate 127<br>
slide128. Regarding the petitions where Revenue has not filed appeals, HC holds that once the ITAT had considered the issues on merits and undertaken a detailed discussion, no rectification could be made on the grounds stated in the MAs; HC anlayses the batch of petitions in under four categories including a category of cases covered by SC ruling in Vikram Bhatia which was delivered after the MA was dismissed by ITAT; Across the categories, HC observes that issue raised by Revenue in MAs requires long drawn argument which is not allowed under Section 254(2) and if the Revenue feels the order passed by the ITAT is erroneous on account of law or on fact, then the only remedy available is to challenge the order at higher forum.
While dismissing the writs, high court also observed that when ITAT dismissed the 254(2) applications, judgment in the case of ITO vs. Vikram Bhatia – (2023) 453 ITR 417 (SC) was not even delivered and therefore, the same cannot be pressed into service. Tushar Hemani, Senior Advocate 128<br>
slide129. Thank You Tushar Hemani, Senior Advocate 129<br>